
 Hazardous Lighting Market | 2026-2036
Hazardous Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Hazardous Lighting Market Foresight
Project finance structures for energy infrastructure retrofits is tilting procurement power toward engineering firms that bundle lighting with full electrical overhauls. Dialight PLC leverages its LED specialization to anchor long-term service contracts with offshore operators. Hubbell Inc. competes through vertical integration into explosion-proof enclosures, while R. STAHL sustains its position via German-engineered certification depth across ATEX and IECEx schemes.
Hazardous lighting denotes luminaires engineered to operate in environments where flammable gases, vapors, dust, or fibers create ignition risks, typically constructed with sealed housings rated for temperature classes T1 through T6 and impact-resistant lens materials. These fixtures serve the primary purpose of maintaining safe illumination without triggering combustion in classified zones across petrochemical, mining, and processing facilities. LED product types now dominate value capture due to extended operational life and reduced heat signatures, while explosion-proof technology commands premium positioning through mandatory third-party certification. Wireless control segments are gaining traction as facilities integrate lighting into broader industrial IoT monitoring architectures.
ATEX directives from European regulators, IECEx standards administered through the IEC, and OSHA's National Electric Code Article 500 classifications collectively shape product design thresholds and market access conditions for hazardous lighting manufacturers. The EU's F-Gas Regulation further constrains legacy fluorescent and HID options by limiting mercury-containing lamp imports. Stakeholders must monitor how evolving battery-backup mandates for emergency egress lighting in classified environments reshape fixture specification requirements.
Market Dynamics
LED retrofit cycles on offshore oil platforms are compressing replacement timelines as operators prioritize maintenance reduction over capital preservation, fundamentally reordering supplier relationships toward service-anchored contracts.
Growth Catalysts
- ATEX Directive tightening:European regulators are mandating stricter explosion-proof enclosure standards, forcing facility upgrades across petrochemical corridors and accelerating fixture replacement demand.
- Offshore platform electrification:North Sea and Gulf of Mexico operators are replacing legacy HID systems with LED arrays to eliminate helicopter-dependent maintenance cycles.
- F-Gas Regulation phaseout:The EU's mercury-containing lamp import restrictions are removing fluorescent alternatives from specification lists, channeling demand toward solid-state lighting.
Market Restraints
- Aluminum enclosure cost volatility:Die-cast housing materials face input price swings that compress margin predictability for explosion-proof fixture manufacturers.
- Certification body concentration:Third-party ATEX and IECEx testing capacity concentrates in German and UK laboratories, creating approval bottlenecks for new market entrants.
- Legacy infrastructure lock-in:Refinery electrical systems built for magnetic ballast loads require rewiring investment that delays LED conversion economics.
Strategic Opportunities
- Industrial IoT convergence:Wireless-enabled luminaires integrating with plant monitoring architectures open recurring software revenue streams beyond hardware sales.
- Battery-backup mandate expansion:Emergency egress lighting requirements in classified environments are extending to Zone 2 areas, broadening addressable fixture specifications.
- Engineering-procurement bundling:Full electrical overhaul contracts let lighting suppliers anchor multi-year service agreements with offshore operators.
Industry Challenges
- IECEx certification timeline compression:Extended third-party testing queues delay product launches and strain working capital for mid-tier manufacturers.
- Explosion-proof engineering talent scarcity:Specialized enclosure design expertise concentrates among aging technical workforces in Germany and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hazardous Lighting Market |
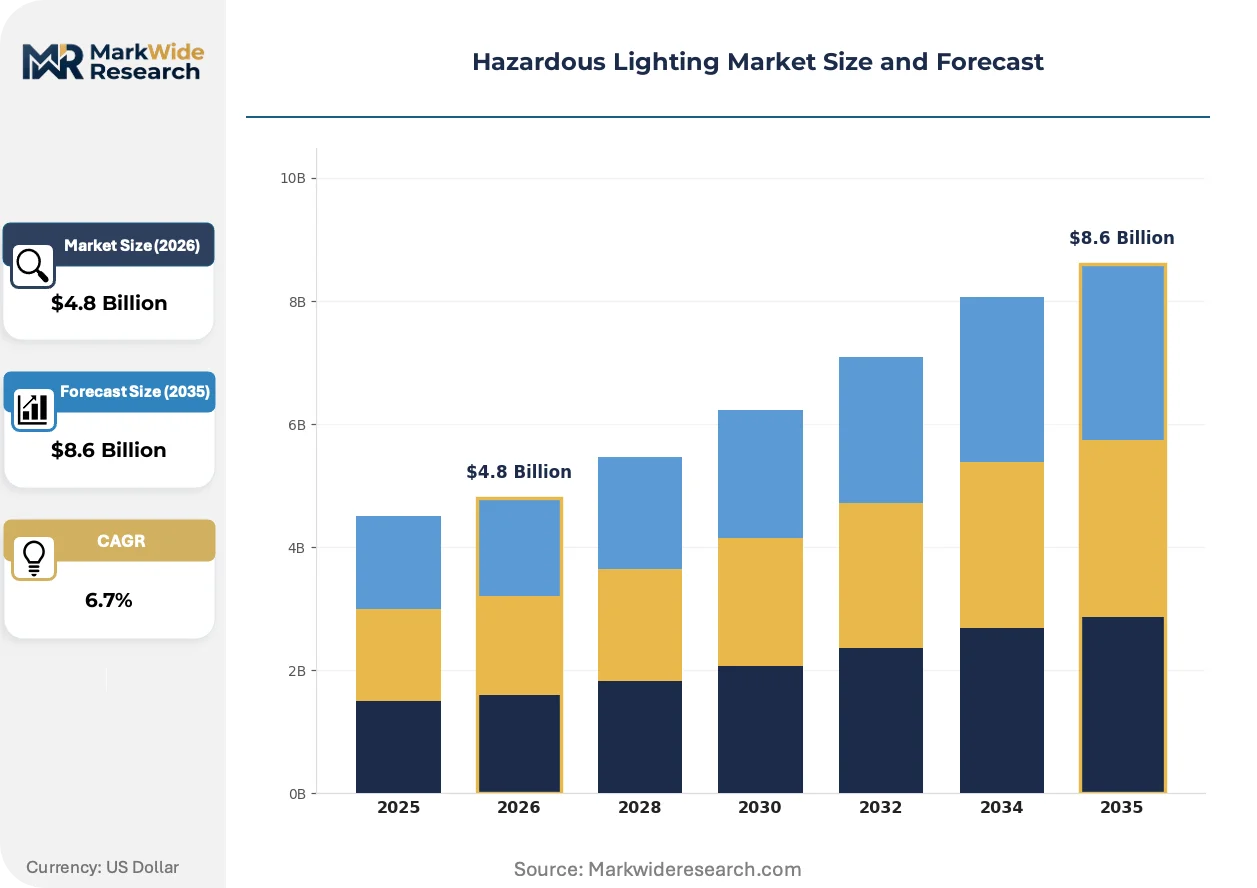
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, High-Intensity Discharge, Incandescent Application: Oil & Gas, Chemicals, Mining, Manufacturing End User: Industrial Facilities, Commercial Spaces, Marine Vessels, Refineries Technology: Smart Lighting, Wireless Control, Explosion-Proof, Bioluminescent |
| Companies Covered | Philips Lighting, Dialight PLC, Thomas & Betts Corporation (ABB Ltd), Hubbell Inc., Larson Electronics, Emerson Industrial Automation, R. STAHL, Lampsuite, Cooper Crouse-Hinds (Eaton), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hazardous Lighting Market Shifts & Advancements
Digital control architectures are penetrating hazardous environments previously dominated by hardwired switching, enabling predictive maintenance models that alter how operators value lighting assets over their operational life.
Wireless mesh networking is virtualizing fixture management across Zone 1 and Zone 2 environments. Offshore platform operators in the North Sea are deploying battery-backed nodes that eliminate conduit runs through explosive atmospheres. This topology is virtualizing the traditional division between lighting control and process safety systems.
OSHA's National Electric Code Article 500 revisions are reclassifying gas group boundaries in petrochemical facilities. The updated boundary definitions are triggering wholesale fixture re-specification in Texas and Louisiana refineries. IECEx-certified suppliers with pre-tested product families are capturing specification momentum.
Facility engineering departments are unbundling lighting procurement from general electrical contracting. Major Gulf Coast petrochemical operators now issue separate RFPs for hazardous-rated luminaires, bypassing traditional distributor channels. Direct manufacturer engagement is most pronounced among operators with centralized engineering functions in Houston.
Hazardous Lighting Market Segmentation
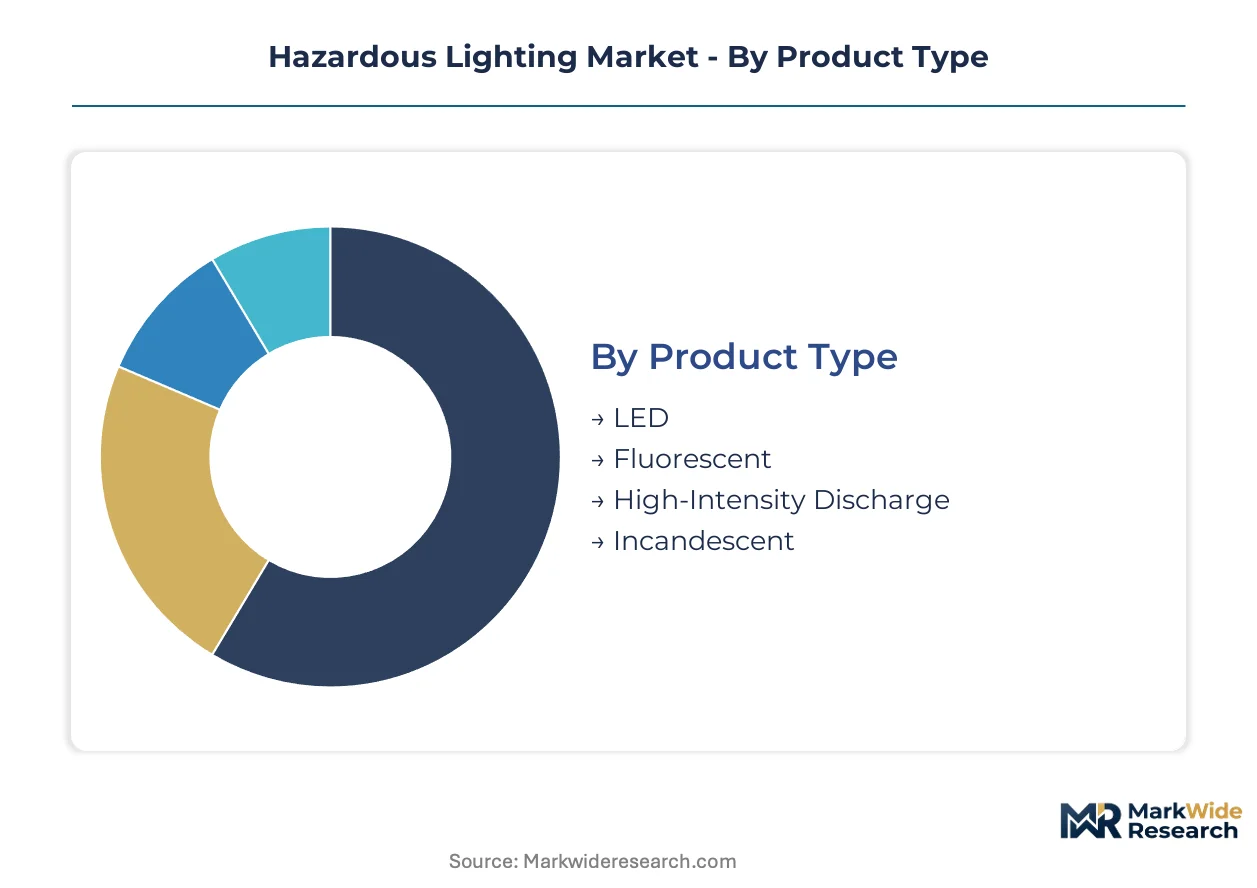
Hazardous lighting segmentation reveals how certification requirements, operational environments, and maintenance economics reshape procurement priorities across industrial verticals. Product type and technology dimensions now dominate specification decisions as facility operators weigh lifecycle costs against upfront capital outlays.
Product Type:
Cost tier differentiation separates segments by operational lifespan, energy consumption, and regulatory compliance trajectory in classified environments.
- LED:Solid-state semiconductor arrays deliver T6 temperature ratings with minimal heat signatures, eliminating ignition risks in Zone 0 environments. Offshore platforms in the Gulf of Mexico specify LED arrays to slash helicopter-dependent maintenance cycles. LED holds installed capacity. Fluorescent is rotating up the share rankings.
- Fluorescent:Mercury-vapor discharge tubes enclosed in sealed housings historically served T5-rated applications with lower capital thresholds. The EU's F-Gas Regulation constrains import volumes, channeling replacement demand toward solid-state alternatives as mercury-containing lamp stocks deplete.
- High-Intensity Discharge:Metal halide and sodium vapor systems retain niche positioning in high-lumen outdoor applications where instant restrike capability matters less than raw output.
- Incandescent:Tungsten filament construction persists only in legacy marine installations and specialized low-voltage applications where electromagnetic compatibility overrides efficiency concerns.
LED commands specification momentum. Fluorescent faces regulatory phaseout pressure.
Application:
Operational environment severity dictates enclosure engineering requirements, with gas group classifications and dust ignition sensitivity driving product selection.
- Oil & Gas:Drilling platforms, refineries, and pipeline terminals require ATEX Zone 1 and IECEx Ex d rated fixtures for hydrogen sulfide and methane atmospheres. North Sea operators prioritize LED retrofits to eliminate personnel exposure during maintenance windows in explosive atmospheres.
- Chemicals:Petrochemical corridors along the US Gulf Coast specify corrosion-resistant housings for chlorine and solvent vapor environments, with OSHA Article 500 classifications triggering wholesale fixture replacements.
- Mining:Underground coal operations demand IP6X dust-tight enclosures with methane ingress protection, where battery-backed emergency systems face extended regulatory scrutiny.
- Manufacturing:Paint booths, solvent storage, and fiber processing plants balance explosion-proof requirements against continuous production uptime needs.
Oil & Gas anchors procurement volume. Chemicals is climbing the fastest.
End User:
Customer type concentration determines whether procurement flows through engineering-procurement contractors or direct manufacturer engagement.
- Industrial Facilities:Integrated petrochemical complexes and bulk processing plants issue consolidated lighting specifications across multiple hazardous zones. Major Gulf Coast operators with centralized Houston engineering functions now unbundle luminaire procurement from general electrical contracting.
- Commercial Spaces:Fueling stations, paint retailers, and dry cleaning operations occupy smaller footprints with simpler Zone 2 classifications.
- Marine Vessels:Tankers, offshore supply boats, and LNG carriers face dual certification demands from flag state maritime authorities and classification societies.
- Refineries:Catalytic crackers, alkylation units, and sulfur recovery plants constitute the most specification-intensive segment with combined gas group and temperature class complexity.
Industrial Facilities dominate contract value. Refineries is gaining specification priority.
Technology:
Maturity stage stratifies segments between proven explosion-proof engineering and emerging digital control architectures.
- Explosion-Proof:Flamepath enclosures and pressurized housings certified to ATEX and IECEx standards constitute the mandatory baseline for Zone 1 deployment. German testing laboratories concentrate approval capacity, creating bottlenecks for new market entrants.
- Smart Lighting:Sensor-integrated fixtures enable occupancy-based dimming and daylight harvesting in non-continuous process areas.
- Wireless Control:Mesh networked nodes eliminate conduit runs through explosive atmospheres, virtualizing fixture management across Zone 1 and Zone 2 boundaries in North Sea platforms.
- Bioluminescent:Experimental bacterial luminescence systems remain laboratory-stage with no commercial hazardous environment deployment.
Explosion-Proof represents entrenched incumbent share. Wireless Control is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering corridors where IECEx certification bottlenecks create supply scarcity, while Gulf Coast procurement volumes in the United States leverage scale economics to compress supplier margins. Facility operators in Rotterdam and Houston unbundle luminaire specifications from electrical contracting, shifting negotiation leverage toward direct manufacturer engagement.
United States
Refinery modernization along the Texas and Louisiana petrochemical corridor accelerates fixture replacement schedules as OSHA Article 500 revisions trigger wholesale re-specification. The EPA coordinates with state regulators on emissions-related facility upgrades that incorporate lighting retrofits. Houston-based engineering departments at major integrated operators now issue separate RFPs for hazardous-rated luminaires, bypassing traditional distributor channels.
Germany
ATEX directive tightening forces facility upgrades across the Rhine-Ruhr chemical cluster and Bavarian industrial zones. ECHA enforcement of explosion-proof enclosure standards concentrates testing capacity in German and UK laboratories, creating approval bottlenecks. Stuttgart and Munich anchor specialized engineering talent pools for flamepath enclosure design, with aging technical workforces constraining new market entry.
United Kingdom
North Sea offshore platform electrification prioritizes LED retrofits to eliminate helicopter-dependent maintenance cycles in methane-rich atmospheres. The Health and Safety Executive enforces updated gas group classifications that align with IECEx standards. Aberdeen engineering clusters coordinate specification standards with Norwegian operators across the North Sea basin.
China
State-owned refinery expansions in the Yangtze River Delta and Pearl River Delta incorporate hazardous lighting into greenfield construction specifications. MIIT standards for industrial electrical equipment converge with international explosion-proof certification requirements. Shanghai and Ningbo manufacturing clusters supply die-cast aluminum enclosures to global fixture assemblers facing input cost volatility.
United Arab Emirates
ADNOC offshore platform upgrades and downstream refinery expansions in Abu Dhabi and Dubai drive specification demand for Zone 1 rated fixtures. MOHAP coordinates with international classification societies on dual certification requirements for marine and hazardous environment deployment. Jebel Ali industrial zones concentrate engineering-procurement contractors bundling lighting with full electrical overhauls.
Hazardous Lighting Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream of certification bottlenecks. The vendor base organizes around three archetypes: diversified electrical conglomerates with captive hazardous divisions, pure-play LED specialists anchoring long-term service contracts, and German-engineered certification depth players. Consolidation pressure concentrates among mid-tier manufacturers facing IECEx testing queue delays. Competitive moves center on backward integration into explosion-proof enclosure production and geographic expansion through engineering-procurement bundling partnerships.
Within the diversified electrical tier, Hubbell Inc. and Cooper Crouse-Hinds occupy positions spanning vertical integration into enclosure manufacturing. Among European certification-depth specialists, R. STAHL exemplifies German-engineered ATEX and IECEx scheme penetration. Dialight PLC anchors the LED specialization vector through service-anchored contract structures with offshore operators.
| Leading Market Players |
|---|
| Philips Lighting |
| Dialight PLC |
| Thomas & Betts Corporation (ABB Ltd) |
| Hubbell Inc. |
| Larson Electronics |
| Emerson Industrial Automation |
| R. STAHL |
| Lampsuite |
| Cooper Crouse-Hinds (Eaton) |
| Others |
Supply & Pricing Matrix
Regulatory chokepoint concentration in German and UK certification laboratories determines both three-tier pricing spreads across ATEX and IECEx tiers and supply chain geography favoring European engineering corridors. Aluminum die-cast enclosure volatility feeds directly into margin compression at the standard tier while premium fixtures absorb input swings through captive enclosure production.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle fixture supply with multi-year service agreements. Pricing stratifies across ATEX-certified premium, IECEx-standard, and economy tiers differentiated by certification depth and after-sales bundling intensity. Cost compression in the economy tier is intensifying because Chinese enclosure assemblers are bypassing German testing queues with MIIT-convergent products. Refinery procurement teams in Houston demonstrate highest price sensitivity, while North Sea offshore operators prioritize maintenance reduction over unit cost.
Supply Chain Analysis
Die-cast aluminum feedstock draws from Shanghai and Ningbo manufacturing clusters, with flamepath engineering expertise anchored in Stuttgart and Munich. German testing laboratories concentrate ATEX and IECEx approval capacity, creating single-source vulnerability for new market entrants seeking certification. Distribution runs through engineering-procurement contractors bundling lighting with full electrical overhauls, particularly in Jebel Ali and Gulf Coast petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless-enabled service contracts are expanding faster than hardware shipments as offshore operators integrate lighting into industrial IoT monitoring architectures. This service-attach layer reshapes vendor economics toward recurring revenue streams.
For Market Incumbents: Pre-empt mid-tier disintermediation by captive enclosure production in Ningbo or backward integration into flamepath engineering talent pools in Germany. Certification body concentration in UK and German laboratories represents a defendable moat if incumbents lock testing queue priority through volume commitments. For New Entrants and Emerging Players: Establish a beachhead in Zone 2 wireless control segments where IECEx testing requirements are less stringent than Zone 1 flamepath certifications. Battery-backed emergency egress fixtures for mining operations offer penetrable white space given extended regulatory scrutiny slowing incumbent product cycles. Target direct engagement with Houston-based engineering departments that have unbundled luminaire procurement from general electrical contracting. For Investors and Strategic Acquirers: The market sits at a retrofit acceleration phase that favors LED specialists with anchored service contracts over diversified electrical conglomerates. Long-term viability hinges on wireless control software recurring revenue attachment rates. Monitor IECEx testing queue duration as the inflection indicator—compression signals margin pressure for mid-tier manufacturers, extension signals pricing power for certification-depth players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enclosure Manufacturing | Captive die-cast aluminum supply insulates margin from Shanghai input volatility. |
| Long-term Service Contract Anchoring | Multi-year agreements with North Sea operators convert hardware sales into recurring revenue. |
| IECEx Certification Pre-testing Investment | Pre-tested product families capture specification momentum from OSHA Article 500 revisions. |
| Wireless Mesh Platform Integration | Sensor-enabled fixtures penetrate Zone 1 environments previously dominated by hardwired switching. |
| Geographic Expansion through EPC Bundling | Partnerships with Jebel Ali contractors open ADNOC offshore platform upgrade specifications. |
Research Methodology
Initial hypotheses were tested against primary input from offshore platform maintenance directors, refinery electrical engineers, EPC procurement leads, and hazardous lighting specification consultants and refined through secondary validation against SEC 10-K filings, IECEx certification registries, customs trade data, and OSHA regulatory dockets. Bottom-up fixture shipment estimates triangulated against top-down petrochemical capital expenditure tracking.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by LED, fluorescent, and HID technologies; application segmentation across oil and gas, chemicals, and mining; and technology segmentation distinguishing explosion-proof, smart lighting, and wireless control architectures. CAGRs derived from facility retrofit cycle analysis and regulatory mandate timing without year-specific anchoring. Forecast inputs included aluminum price trajectory assumptions and certification queue duration estimates.
Sensitivities concentrate around IECEx testing capacity expansion, F-Gas Regulation enforcement intensity, and offshore platform electrification commitment levels. Cross-checking against EIA petrochemical capacity addition data and ADNOC capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
North America Smart Lighting Market
Lighting
Recessed Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Connected Lighting Platform Market
Lighting
Global Lamps Market
Lighting
Lighting Product Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
Graphene Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Vintage Bulb Market
Lighting
Global Headlight Control Module Market
Lighting
Digital Light Processing Technology Market
Lighting
Ultraviolet Lamps Market
Lighting
Circadian Lighting Market
Lighting
Tritium Light Source Market
Lighting
LED Eye Protection Lamp Market