
 Loose-Fill Peanuts Market | 2026-2036
Loose-Fill Peanuts Market Size, Share, and Industry Trends Forecast 2026-2036
Loose-Fill Peanuts Market Foresight
The EU Packaging and Packaging Waste Regulation is expanding compliance obligations for protective packaging across member states. Sealed Air Corporation leverages its global manufacturing footprint to serve multinational e-commerce platforms with certified recyclable loose-fill solutions. Storopack Hans Reichenecker GmbH anchors its position through deep specialization in bio-based starch formulations. Smurfit Kappa Group competes by integrating loose-fill production with its corrugated packaging network across European distribution hubs.
Loose-fill peanuts are lightweight, interlocking cushioning particles engineered from expanded polystyrene, starch-based biopolymers, or polypropylene, typically measuring 10–40 mm in length with a bulk density below 10 kg/m³ for optimal void-fill efficiency. Their primary commercial purpose is to immobilize products within shipping containers, absorbing impact energy during distribution handling. Bio-based loose-fill now leads product type momentum as food-grade starch formulations achieve performance parity with polystyrene at comparable unit economics. E-commerce end users command the fastest-growing demand segment, driven by per-unit shipping volume expansion and unboxing experience requirements. Offline distribution channels still dominate bulk procurement for manufacturers and wholesalers, though direct sales relationships are capturing higher-margin custom formulation contracts.
REACH compliance governs chemical constituents in European loose-fill manufacturing, while the EU Green Deal's packaging reduction targets are forcing material substitution timelines. EPA regulations under the Toxic Substances Control Act influence polystyrene feedstock availability in the United States, shaping cross-border supply planning. Stakeholders must monitor how extended producer responsibility schemes in France and Germany redefine cost allocation between packaging producers and e-commerce platforms.
Market Dynamics
Material substitution timelines under the EU Green Deal are compressing polystyrene production windows while e-commerce fulfillment centers accelerate bio-based starch formulation adoption to meet retailer packaging mandates.
Growth Catalysts
- Amazon Frustration-Free Packaging:The program mandates reduced packaging waste and recyclable materials, forcing third-party sellers to switch from expanded polystyrene to certified bio-based loose-fill alternatives for Prime eligibility.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility schemes now assign full end-of-life costs to packaging producers, making starch-based peanuts economically competitive against petroleum-derived options.
- Precision electronics exporters:German automotive parts distributors demand high-performance protective packaging with electrostatic discharge protection, creating premium demand for modified starch formulations.
Market Restraints
- Feedstock volatility:Corn and potato starch prices fluctuate with agricultural commodity cycles, squeezing unit margins for bio-based manufacturers during drought periods in major growing regions.
- Polystyrene supply concentration:Expanded polystyrene resin production clusters in the US Gulf Coast and Northeast Asia, exposing European converters to transatlantic shipping cost swings and import dependency.
- Performance limitations in humidity:Unmodified starch peanuts lose structural integrity above 75% relative humidity, restricting their deployment for ocean freight lanes through tropical zones.
Strategic Opportunities
- France's extended producer responsibility expansion:The 2024 packaging fee restructuring penalizes non-recyclable materials at 4x the rate of certified circular alternatives, creating immediate switching incentives for cross-border e-commerce platforms.
- Closed-loop return systems:Bulk reverse logistics networks allow fulfillment centers to collect, clean, and reuse starch peanuts 8-12 times before material degradation, slashing per-shipment packaging costs.
- Pharmaceutical cold chain:Insulated shipper integration with bio-based void fill addresses temperature-sensitive biologics distribution, an application with stringent FDA validation requirements and limited incumbent suppliers.
Industry Challenges
- Composting infrastructure gaps:Industrial composting facilities required for starch peanut decomposition remain concentrated in Northern Europe, leaving Southern and Eastern European e-commerce customers without compliant disposal pathways.
- REACH registration timelines:Novel biopolymer additives require 18-24 month ECHA dossier preparation periods, delaying product launches for reformulated anti-static or water-resistant grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loose-Fill Peanuts Market |
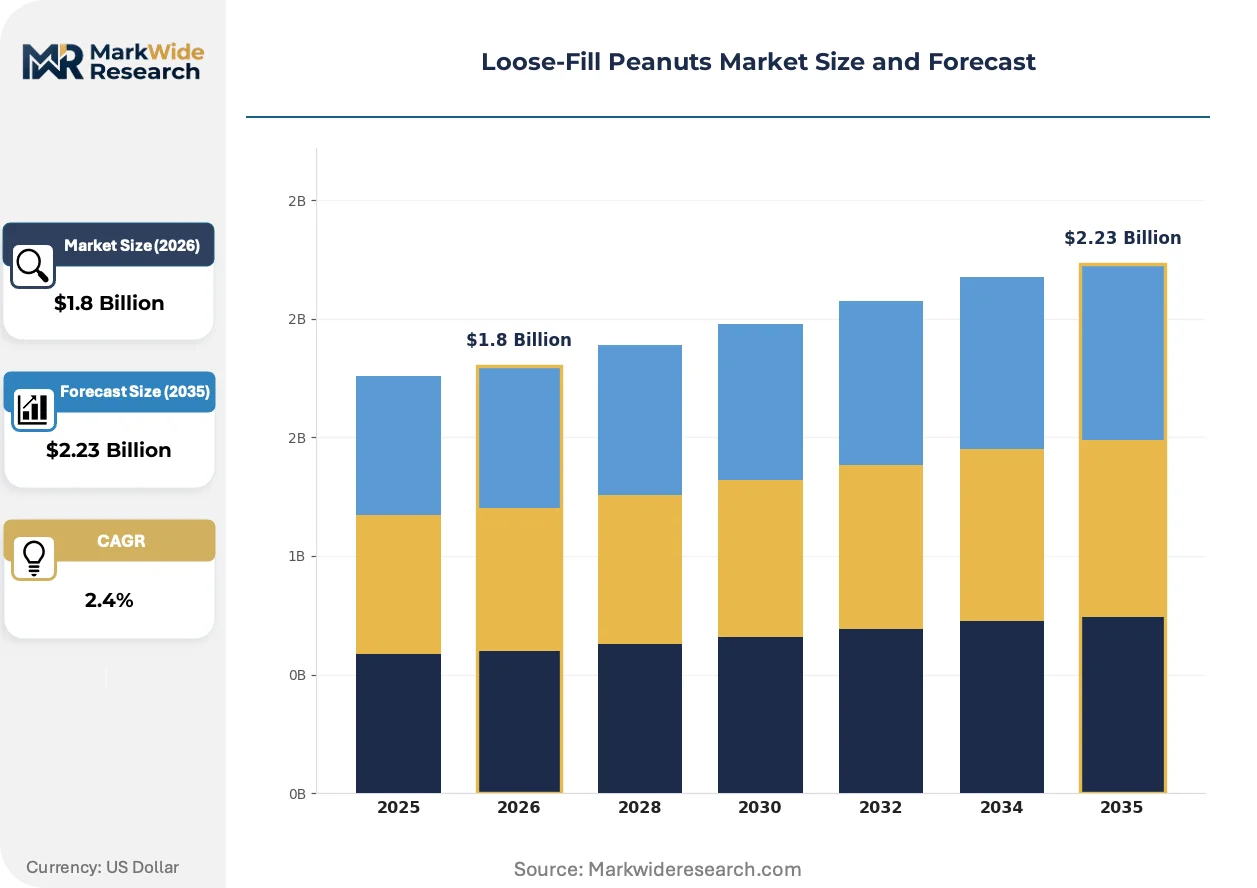
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Based, Polystyrene, Polypropylene, Other Packaging Type: Bags, Bulk Containers, Boxes, Pallets End User: Retailers, E-Commerce, Wholesalers, Manufacturers Distribution Channel: Online, Offline, Direct Sales, Third-Party Distributors |
| Companies Covered | Sealed Air Corporation, Storopack Hans Reichenecker GmbH, Smurfit Kappa Group, ACH Foam Technologies, FP International, Nefab Group, Free-Flow Packaging, Pregis LLC, Veritiv Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loose-Fill Peanuts Market Shifts & Advancements
Decentralized manufacturing footprints and on-site production systems are collapsing traditional supply chain geometries, while regulatory compliance automation and buyer sustainability scorecards rewrite procurement criteria across protective packaging categories.
On-site starch extrusion systems are decentralizing loose-fill production by enabling fulfillment centers to manufacture peanuts directly from raw starch pellets, eliminating inbound freight costs for bulky void-fill materials. Amazon and major third-party logistics providers in Germany and the Netherlands have piloted these systems since 2022. This shift compresses the addressable market for centralized polystyrene molders while creating captive demand for food-grade starch supply contracts.
REACH chemical safety dossier automation is accelerating material approval cycles for novel biopolymer additives, compressing the gap between laboratory formulation and commercial scale-up. ECHA's IUCLID software integration allows simultaneous multi-member state notification, reducing regulatory lag. Bio-based peanut producers in Belgium and Denmark leverage this to outpace US competitors still navigating EPA Toxic Substances Control Act state-by-state premanufacture notification requirements.
Buyer sustainability scorecards now weight packaging circularity at 15-25% of total supplier evaluation metrics, displacing pure unit-cost procurement for enterprise e-commerce accounts. Unboxing experience requirements from direct-to-consumer brands prioritize dissolvable starch peanuts over static-dissipative polystyrene. This preference shift concentrates fastest in German and French premium cosmetics and electronics verticals where brand positioning depends on visible environmental credentials.
Loose-Fill Peanuts Market Segmentation
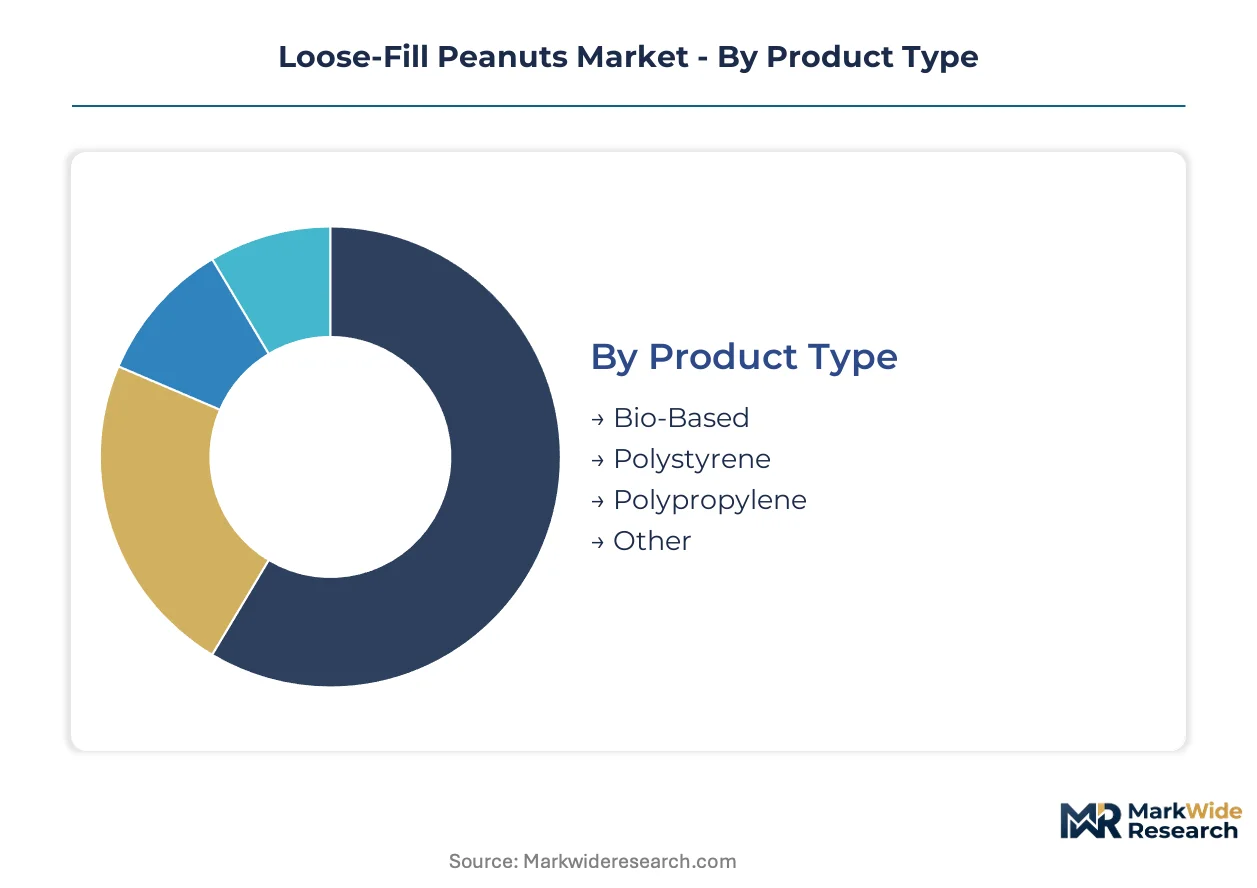
Segmentation in loose-fill peanuts reveals how material chemistry, packaging format, and channel economics fragment procurement decisions across protective packaging buyers. E-commerce fulfillment centers weigh compostability against unit cost, while automotive parts distributors prioritize electrostatic performance over disposability.
Product Type:
Material selection hinges on regulatory compliance timelines and end-of-life cost allocation under extended producer responsibility schemes.
- Bio-Based:Food-grade starch formulations achieve performance parity with petroleum-derived alternatives at comparable unit economics. German automotive parts distributors and precision electronics exporters in Bavaria drive premium demand for modified grades with electrostatic discharge protection.
- Polystyrene:Expanded polystyrene retains cost advantage in bulk void-fill applications where humidity exposure is minimal. Production concentration along the US Gulf Coast exposes European converters to transatlantic freight volatility and import dependency risks.
- Polypropylene:Recyclable thermoplastic variants serve closed-loop return systems in Netherlands-based fulfillment networks.
- Other:Experimental mycelium and seaweed-derived fillers target luxury cosmetics unboxing experiences in French premium verticals.
Bio-based leads on scale; other materials lead on momentum.
Packaging Type:
Volume economics and handling automation requirements dictate format selection across distribution node types.
- Bulk Containers:Tote-based delivery systems dominate manufacturer and wholesaler procurement, enabling gravity-fed dispensing into packing stations. Offline distribution channels in Germany capture highest-margin contracts through multi-year supply agreements.
- Bags:Pre-portioned polyethylene sacks serve small and mid-sized e-commerce operations lacking on-site extrusion capability. Amazon Frustration-Free Packaging compliance pressures third-party sellers toward certified recyclable bag formats.
- Boxes:Corrugated-integrated solutions from Smurfit Kappa's European hub network reduce inbound freight cube.
- Pallets:Unitized loads for high-volume automotive parts distributors in Stuttgart and Wolfsburg clusters.
Bulk containers lead on scale; bags lead on momentum.
End User:
Supply chain position determines performance specifications and sustainability verification requirements.
- E-Commerce:Direct-to-consumer brands prioritize dissolvable starch peanuts for unboxing experience differentiation. REACH-registered formulations from Belgian producers outpace US competitors in EU procurement scorecards.
- Retailers:Omnichannel fulfillment networks balance compostability claims with returns processing efficiency. France's packaging fee restructuring penalizes non-recyclable materials at quadruple rates.
- Wholesalers:Price-sensitive bulk procurement favors polystyrene where regulatory windows permit.
- Manufacturers:Captive packaging operations in automotive and electronics verticals specify anti-static grades.
Retailers lead on scale; e-commerce leads on momentum.
Distribution Channel:
Margin capture and technical service intensity separate channel strategies for bio-based versus conventional materials.
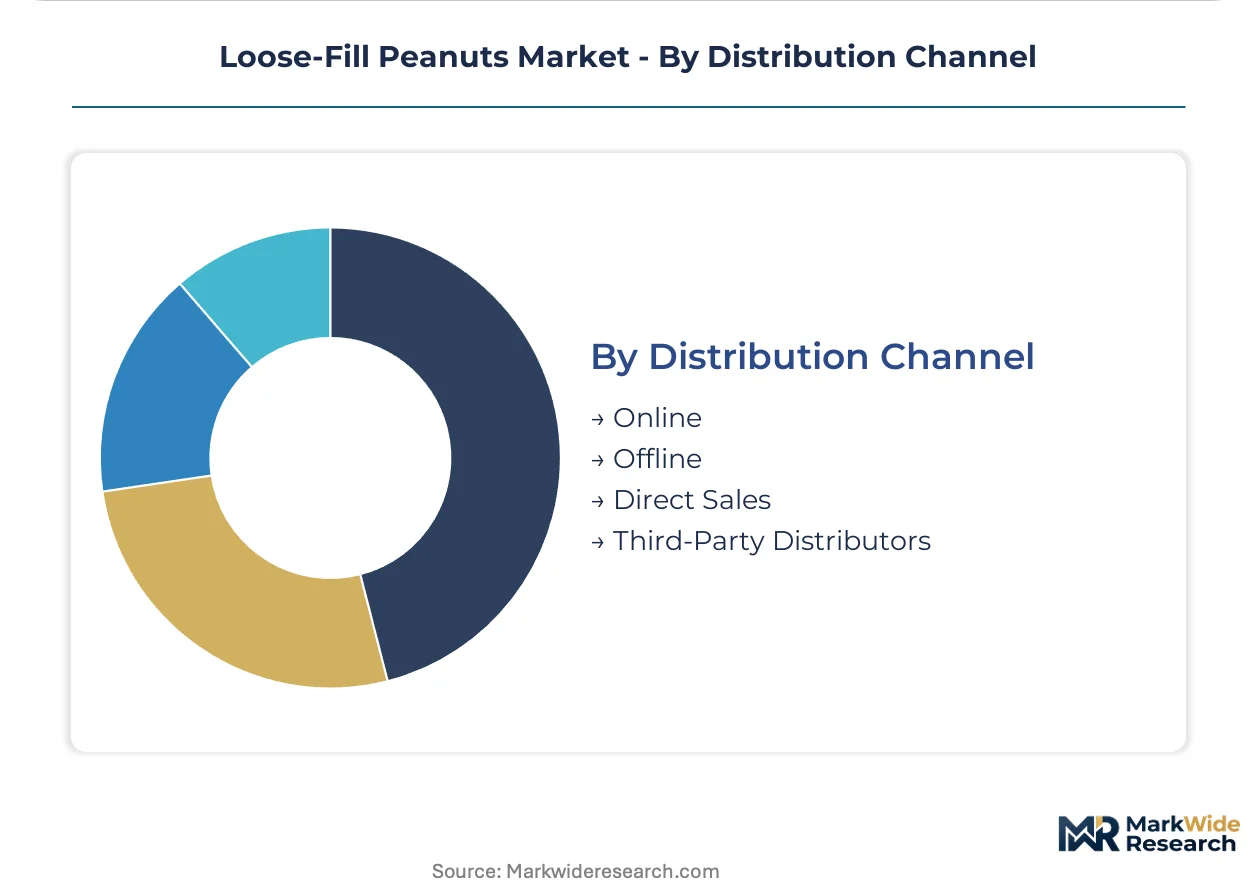
- Offline:Traditional distributor networks dominate bulk procurement for manufacturers and wholesalers, leveraging regional warehousing for just-in-time delivery to German automotive clusters.
- Direct Sales:Custom formulation contracts for enterprise e-commerce accounts bypass distributor markups. Sealed Air Corporation leverages direct relationships with multinational platforms.
- Online:Digital procurement portals capture small and mid-sized fulfillment center demand with standardized SKUs.
- Third-Party Distributors:Specialized protective packaging distributors offer technical consultation on REACH compliance and composting infrastructure access.
Offline leads on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Loose-fill peanuts originated as expanded polystyrene void-fill solutions in mid-20th century American manufacturing, with bio-based starch alternatives later commercialized through European chemical innovation. Geographic demand patterns now track regulatory pressure corridors and e-commerce fulfillment density.
Germany
Automotive parts distributors in Stuttgart and Wolfsburg clusters drive premium demand for anti-static starch formulations. REACH compliance timelines accelerate material substitution away from petroleum-derived alternatives. Bavarian precision electronics exporters specify modified biopolymer grades for electrostatic discharge protection in cross-border shipments.
United States
EPA regulations under the Toxic Substances Control Act constrain polystyrene feedstock availability, reshaping supply planning for Gulf Coast resin converters. Amazon Frustration-Free Packaging mandates force third-party sellers toward certified recyclable formats for Prime eligibility. Fulfillment centers in Texas and California pilot on-site starch extrusion systems to eliminate inbound freight costs.
France
Extended producer responsibility fee restructuring penalizes non-recyclable materials at quadruple rates versus certified circular alternatives. ANSM packaging guidelines influence pharmaceutical cold chain specifications for temperature-sensitive biologics. Île-de-France premium cosmetics brands prioritize dissolvable starch peanuts for unboxing experience differentiation.
Netherlands
Closed-loop return systems in Rotterdam and Amsterdam fulfillment networks enable 8-12 reuse cycles for starch peanuts before material degradation. ECHA dossier automation accelerates novel biopolymer additive approvals versus US state-by-state notification requirements. Randstad logistics hubs integrate bio-based void-fill with corrugated packaging networks for omnichannel retailers.
China
Dual carbon goals under national climate commitments compress timelines for petroleum-based packaging phase-out. NMPA pharmaceutical distribution standards create compliance barriers for imported protective packaging materials. Yangtze River Delta e-commerce platforms experiment with mycelium-derived fillers for luxury unboxing experiences.
Loose-Fill Peanuts Market Competitive Landscape
Capital-heavy resin producers compete with asset-light formulation specialists across divergent technology trajectories. The vendor base consolidates around three strategic tiers: multinational material science conglomerates with integrated polymer supply chains, regional biopolymer specialists with captive starch processing capabilities, and corrugated packaging networks extending into void-fill adjacencies. Dominant competitive moves include backward integration into agricultural feedstock sourcing and geographic expansion through distributor acquisition in high-regulation markets.
Among multinational protective packaging suppliers, Sealed Air Corporation occupies a position representing the integrated conglomerate archetype with global manufacturing footprints. Storopack Hans Reichenecker GmbH exemplifies the regional specialist model through deep concentration in bio-based starch formulations. Smurfit Kappa Group sits within the packaging network extension tier, leveraging corrugated production integration across European distribution hubs.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Storopack Hans Reichenecker GmbH |
| Smurfit Kappa Group |
| ACH Foam Technologies |
| FP International |
| Nefab Group |
| Free-Flow Packaging |
| Pregis LLC |
| Veritiv Corporation |
| Others |
Supply & Pricing Matrix
Amazon Frustration-Free Packaging mandates and EU extended producer responsibility schemes force third-party sellers and fulfillment centers toward certified bio-based formulations, compelling suppliers to reconfigure starch pellet sourcing networks and absorb agricultural commodity volatility into contract structures.
Pricing Analysis
Three-tier pricing structure across premium anti-static grades, standard compostable formulations, and economy polystyrene alternatives governs procurement negotiations. REACH-registered biopolymer additives command 15-25% premiums over unmodified starch, while volume scale and closed-loop return arrangements compress unit costs for enterprise e-commerce accounts. Price differentiation hinges on certification grade and electrostatic discharge performance. Pricing pressure stems from corn and potato starch feedstock volatility during drought cycles in major growing regions. Small and mid-sized fulfillment centers exhibit highest price sensitivity, whereas German automotive parts distributors prioritize performance specifications over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and Belgium anchor European bio-based loose-fill procurement, with hub-and-spoke patterns radiating toward fulfillment clusters in Stuttgart, Rotterdam, and Antwerp. Raw material supply draws from corn and potato starch processors in France, Germany, and Poland, plus expanded polystyrene resin converters along the US Gulf Coast. Single-source vulnerability concentrates in agricultural feedstock regions exposed to climate-induced harvest variability. Distribution runs through corrugated packaging networks for integrated void-fill solutions and direct bulk container delivery for high-volume automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation functions as a regulatory compounder, with France's 2024 packaging fee restructuring accelerating material substitution timelines and reshaping competitive economics across protective packaging procurement.
For Market Incumbents: Anticipate margin compression from on-site starch extrusion adoption at major fulfillment centers by securing captive food-grade starch supply contracts and investing in REACH-registered anti-static formulation R&D. Defensive positioning requires backward integration into agricultural feedstock sourcing and distributor acquisition in high-regulation markets to maintain channel control against asset-light biopolymer specialists. For New Entrants and Emerging Players: The price-point gap between premium electrostatic-protected grades and economy unmodified starch creates white-space opportunity in mid-tier modified formulations for mid-sized e-commerce accounts lacking Prime-scale volume. Target Netherlands-based closed-loop return networks and French premium cosmetics verticals where sustainability scorecard weighting exceeds pure unit-cost procurement. A technical consultation go-to-market angle on REACH compliance and composting infrastructure access differentiates against commodity suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional biopolymer specialists possessing captive starch processing capabilities and established ECHA dossier automation workflows. Long-term viability over a 5-10 year window favors acquisition targets with proven pharmaceutical cold chain validation and insulated shipper integration capabilities. Watch for inflection when industrial composting facility coverage expands into Southern and Eastern European markets currently lacking compliant disposal pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Sourcing | Corn and potato starch supply contracts from French and German agricultural processors secure margin against commodity volatility. |
| REACH-Registered Anti-Static Formulation Development | ECHA dossier automation accelerates approval cycles for modified biopolymer grades targeting Bavarian precision electronics exporters. |
| Closed-Loop Return System Partnerships | Rotterdam and Amsterdam fulfillment networks enable 8-12 reuse cycles, slashing per-shipment packaging costs for omnichannel retailers. |
| On-Site Extrusion Capability Deployment | German and Dutch fulfillment centers eliminate inbound freight costs while creating captive demand for food-grade starch pellets. |
| Pharmaceutical Cold Chain Validation | FDA and ANSM packaging guidelines for temperature-sensitive biologics create compliance barriers limiting incumbent supplier competition. |
Research Methodology
Multiple input streams — primary interviews with protective packaging procurement managers, plant engineers at starch extrusion facilities, and regulatory affairs specialists; secondary validation through ECHA REACH registrations, EU Packaging and Packaging Waste Regulation filings, and SEC disclosures from listed material science conglomerates; plus customs and trade data on expanded polystyrene resin flows — were reconciled through bottom-up and top-down triangulation.
Historical shipment volumes were cross-referenced against panel input from e-commerce fulfillment operators and automotive parts distributors to build the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, packaging format, end-use vertical, and regional regulatory cluster. CAGRs were derived from regression analysis of substitution elasticities between polystyrene and bio-based alternatives, incorporating feedstock price series and retailer mandate compliance timelines as industry-specific forecast inputs.
Caveats apply where EU Green Deal packaging reduction targets, REACH registration delays for novel additives, or composting infrastructure deployment gaps could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag on Valve Technology Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Woven Bags Market
Bags and Containers
Bag-In-Box Filler Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Loop Handle Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Bin Liners Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Pasted Valve Bags Market