
 Camcorder Market | 2026-2036
Camcorder Market Size, Share, and Industry Trends Forecast 2026-2036
Camcorder Market Analysis
REACH compliance is decoupling European market access from legacy manufacturing footprints. Sony Group Corporation anchors professional broadcast supply through sensor fabrication dominance. Canon Inc. leverages cinema-grade lens ecosystems to differentiate in the content creator segment. Panasonic Holding Corporation sustains broadcast infrastructure relationships across live production verticals.
A camcorder is a handheld or shoulder-mounted video recording device utilizing optical zoom lenses, CMOS or CCD image sensors, and digital storage media to capture moving images for commercial, industrial, or consumer applications. Professional camcorders command the highest margin pools due to cinema broadcast certification requirements, while action camcorders represent the fastest-growing product type as adventure sports creators expand output. The end user base tilts toward content creators and educational institutions, which now outpace traditional home user demand for 4K-capable units with optical image stabilization.
The FCC governs wireless transmission protocols for live broadcast camcorders in the United States, while the EU AI Act introduces algorithmic transparency requirements for automated tracking and focus systems. Japan's METI coordinates domestic standards with JIS certification for professional imaging equipment. Stakeholders must monitor how regulatory divergence in AI-enabled autofocus and wireless spectrum allocation reshapes product development roadmaps and regional certification budgets.
Market Dynamics
The EU's F-Gas Regulation is forcing refrigerant phase-out in broadcast equipment thermal systems, while content creator demand for 4K streaming capability pulls sensor and lens supply chains toward higher-margin professional configurations.
Growth Catalysts
- Streaming platform proliferation:Content creators on Twitch, YouTube, and TikTok require dedicated 4K camcorders with optical image stabilization for professional output quality.
- Japan's METI imaging standards:JIS certification for professional equipment creates exportable quality benchmarks that elevate global product specifications.
- Educational institutional procurement:Universities and media schools replace aging HD fleets with 4K-capable units for student production facilities.
Market Restraints
- CMOS sensor supply concentration:Fabrication capacity clusters in Japan and South Korea, creating single-source vulnerability for professional-grade chips.
- F-Gas Regulation compliance costs:Broadcast equipment manufacturers face refrigerant redesign expenses for thermal management in live production rigs.
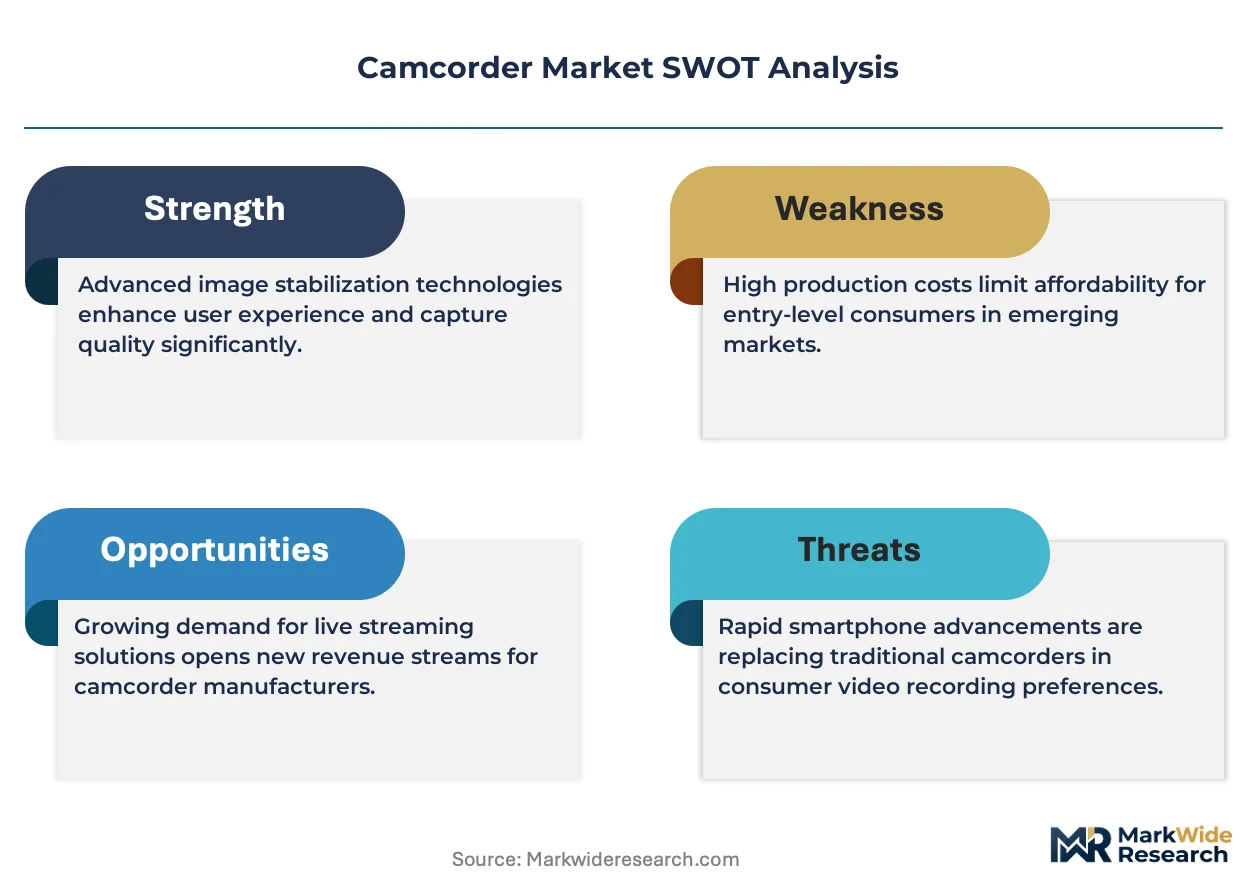
- Smartphone 4K substitution:Mobile devices with computational photography erode casual consumer camcorder demand in sub-$500 price bands.
Strategic Opportunities
- India's PLI scheme for electronics:Production-linked incentives attract assembly investment for mid-tier professional camcorders targeting South Asian educational markets.
- AI-enabled autofocus convergence:Machine learning algorithms paired with depth sensors enable real-time subject tracking for solo content creators.
- Direct-to-creator distribution:Manufacturers bypass traditional broadcast dealers through B2B e-commerce portals serving freelance videographers.
Industry Challenges
- Optical engineering talent scarcity:Precision lens design expertise concentrates in Germany and Japan, constraining R&D expansion elsewhere.
- EU AI Act certification timelines:Algorithmic transparency documentation for automated tracking systems delays product launches by 8-14 months.
- Legacy broadcast infrastructure integration:New 4K units must maintain backward compatibility with SDI and HDMI workflows in existing production trucks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Camcorder Market |
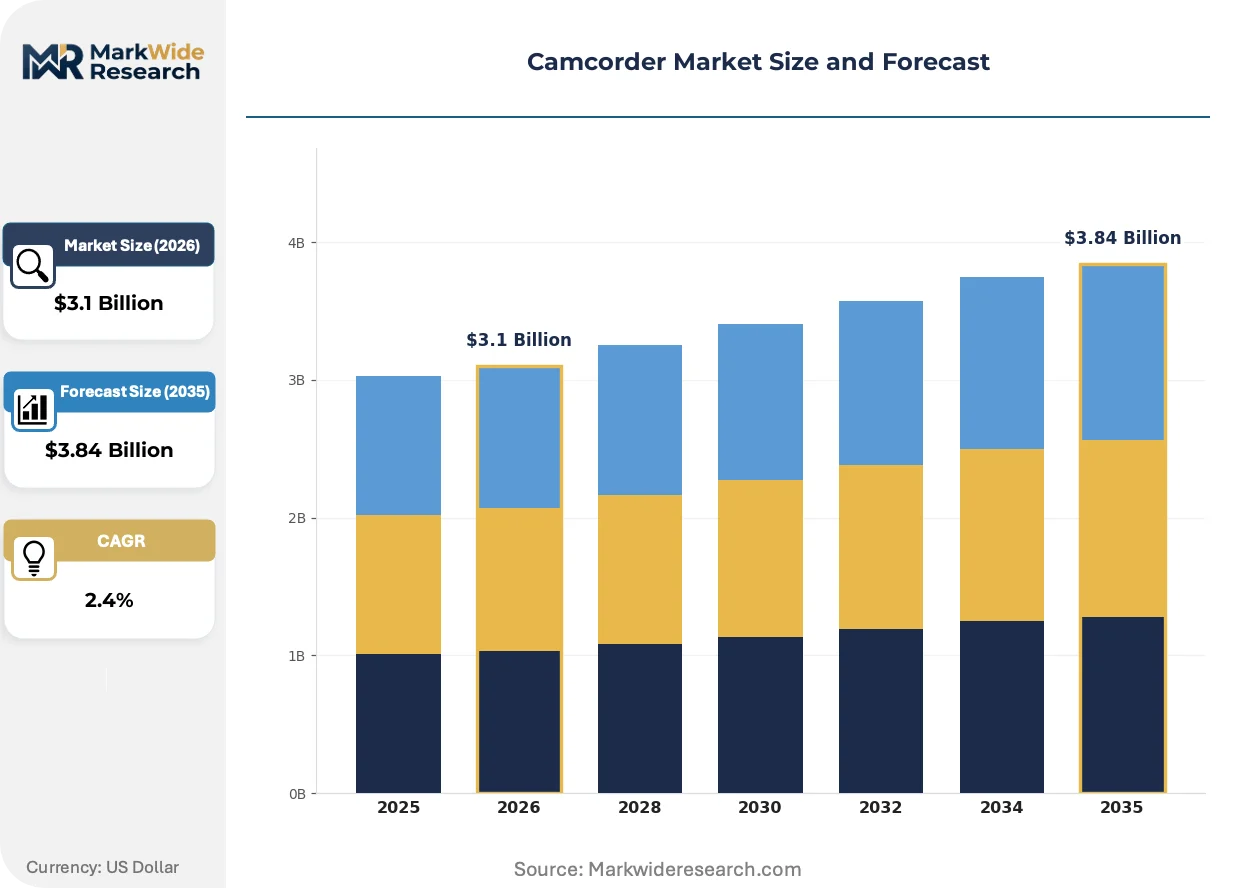
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $3.84 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Camcorders, Mini-DV Camcorders, Professional Camcorders, Action Camcorders End User: Home Users, Professionals, Educational Institutions, Content Creators Feature: High Definition, 4K Capability, Optical Zoom, Image Stabilization Distribution Channel: Online Retailers, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Canon Inc., Sony Group Corporation, Panasonic Holding Corporation, JVCKENWOOD Corporation, GoPro Inc., Samsung Electronics, Blackmagic Design Pty Ltd, Nikon Corporation, FUJIFILM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Camcorder Market Emerging Trajectories
Image processing workflows are fragmenting across edge devices and cloud platforms, compressing traditional post-production timelines while elevating in-camera computational requirements.
Computational photography is decentralizing color grading and noise reduction from desktop suites into real-time camera pipelines. Wedding videographers and documentary crews now capture broadcast-ready footage without external recorders. This compression of the post chain is reshaping crew size norms on location shoots.
The EU AI Act mandates algorithmic disclosure for automated focus and tracking systems deployed in European markets. Manufacturers must document training data provenance and decision logic for regulatory files. Professional camcorder lines with AI autofocus now carry separate SKU variants for EU compliance versus other markets.
Subscription-based firmware access is replacing perpetual license models for codec and feature unlocks. Freelance creators in North America now rent LOG gamma profiles and RAW output capabilities monthly rather than purchasing tiered hardware SKUs. This shift compresses initial equipment outlays while extending manufacturer revenue visibility across product lifecycles.
Camcorder Market Segmentation
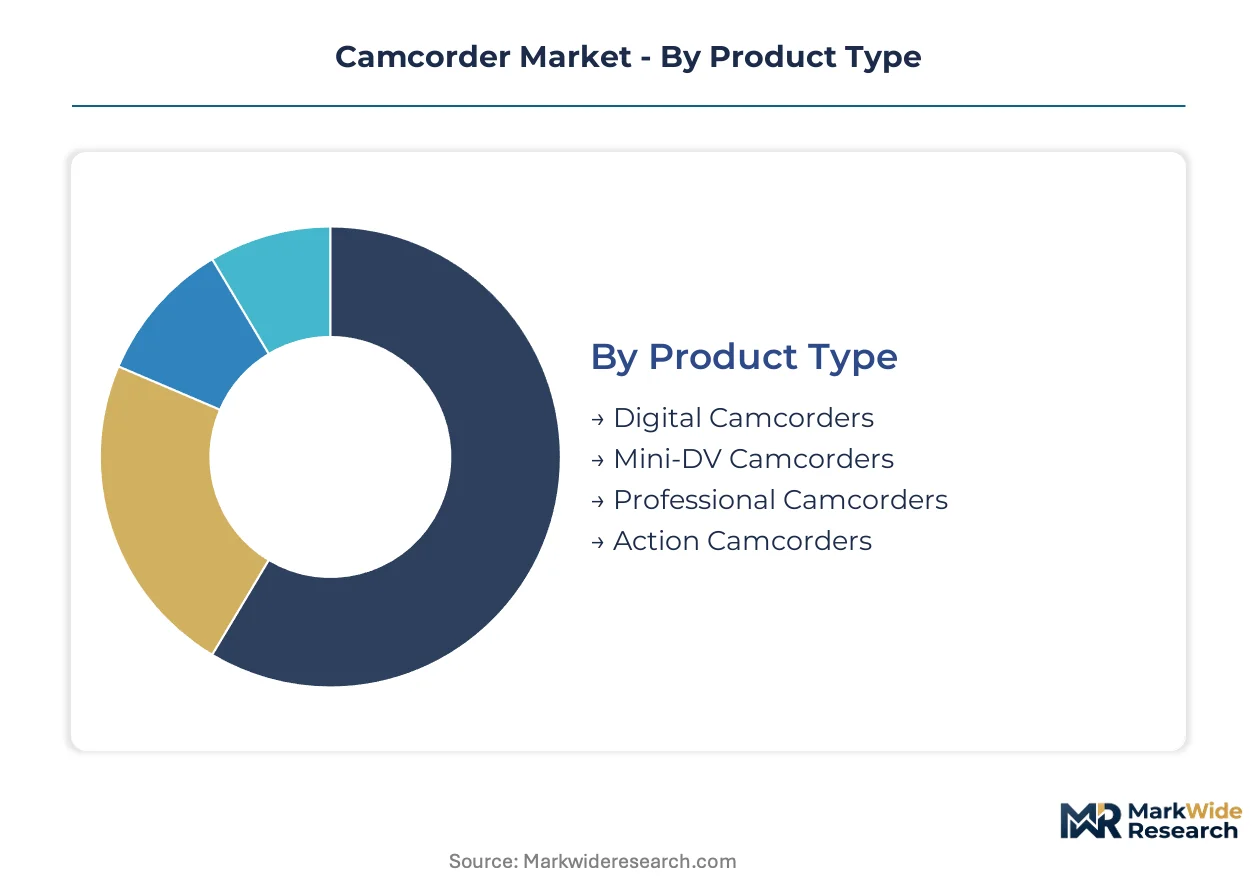
Camcorder procurement patterns diverge sharply across user sophistication tiers, with feature requirements and channel preferences creating distinct margin profiles that manufacturers must navigate through differentiated SKU architectures.
Product Type:
Upgrade cycles vary dramatically across product tiers, with institutional buyers replacing equipment on predictable depreciation schedules while creator segments chase sensor and codec advances on compressed timelines.
- Digital Camcorders:All-in-one recording units with integrated lenses and storage targeting general consumer and prosumer workflows. Educational institutions in Japan favor these for student training fleets due to simplified maintenance protocols and standardized lens mounts. Demand concentrates in replacement waves tied to JIS certification renewals for media school accreditation.
- Professional Camcorders:Shoulder-mounted or cinema-configured units with interchangeable lens systems, broadcast-grade codecs, and SDI output for live production integration. Broadcast networks in Germany and Japan drive specification requirements through EBU and ARIB standards compliance. Thermal management redesigns for F-Gas Regulation adherence are elevating unit costs in European procurement.
- Mini-DV Camcorders:Tape-based recording systems with FireWire output for legacy archival workflows. Archival digitization services and documentary preservation units sustain residual demand despite format obsolescence.
- Action Camcorders:Ruggedized compact units with waterproof housings and wide-angle fixed lenses for POV capture. Adventure sports creators and automotive documentation crews drive volume in this category.
Volume placements concentrate in Digital Camcorders; the faster expansion belongs to Action Camcorders.
End User:
Customer archetypes stratify around production scale and technical sophistication, with procurement authority shifting from centralized IT departments toward individual creator budgets.
- Content Creators:Freelance videographers, streamers, and social media producers operating as sole proprietors or micro-studios. Twitch and YouTube monetization thresholds in the United States and United Kingdom drive 4K capability requirements as baseline competitive equipment. Solo operators prioritize autofocus reliability and single-operator ergonomics over studio connectivity.
- Professionals:Broadcast engineers, wedding videographers, and corporate production houses with established client relationships and equipment rental infrastructure. Live production trucks in Japan and Germany require backward compatibility with existing SDI router configurations and intercom systems.
- Educational Institutions:Universities, media schools, and vocational training centers maintaining student production facilities. India's expanding media education sector under PLI scheme incentives is accelerating fleet refresh cycles for 4K-capable training equipment.
- Home Users:Casual family documentarians and hobbyist videographers. Smartphone substitution has compressed this segment to specialty use cases requiring optical zoom or extended recording duration.
Procurement volume clusters with Educational Institutions; Content Creators are climbing the fastest as a demand source.
Feature:
Specification thresholds now function as market access gates, with certain capabilities table stakes for channel placement while others command explicit price premiums.
- 4K Capability:UHD resolution capture at 3840x2160 or cinema 4K formats with sufficient bit depth for color grading headroom. Educational procurement in South Korea and Japan now mandates 4K as minimum viable specification for accreditation compliance.
- Image Stabilization:Optical or sensor-shift systems compensating for handheld motion without resolution loss. Run-and-gun documentary crews in the United Kingdom prioritize this capability for location shooting without gimbal support.
- High Definition:1080p capture specifications now relegated to entry-tier positioning and legacy infrastructure compatibility. Remaining demand concentrates in secondary classroom installations and backup equipment roles.
- Optical Zoom:Motorized lens systems with variable focal length maintaining image quality across magnification range. Sports and wildlife documentation in German-speaking markets sustains premium positioning for extended zoom ratios.
Shipment volume still concentrates in High Definition specifications; 4K Capability is gaining share fastest across all end-user categories.
Distribution Channel:
Channel economics are fragmenting as manufacturer-direct relationships displace traditional dealer networks in creator-facing segments.
- Online Retailers:E-commerce platforms with comparison tools, user reviews, and expedited fulfillment. Content creators in the United States and United Kingdom increasingly bypass specialty dealers for standardized professional configurations with transparent pricing.
- Direct Sales:Manufacturer-operated B2B portals and account-managed relationships for volume purchasers. Broadcast networks in Japan negotiate fleet pricing through direct METI-facilitated procurement frameworks.
- Specialty Stores:Dealer networks with demonstration facilities and technical consultation services. Professional camcorder lines with complex lens ecosystem requirements still route through these channels in Germany and Japan.
- Mass Merchants:Big-box retailers with limited SKU breadth targeting casual consumer segments. Action camcorders and entry digital units maintain placement here for gift and impulse purchase occasions.
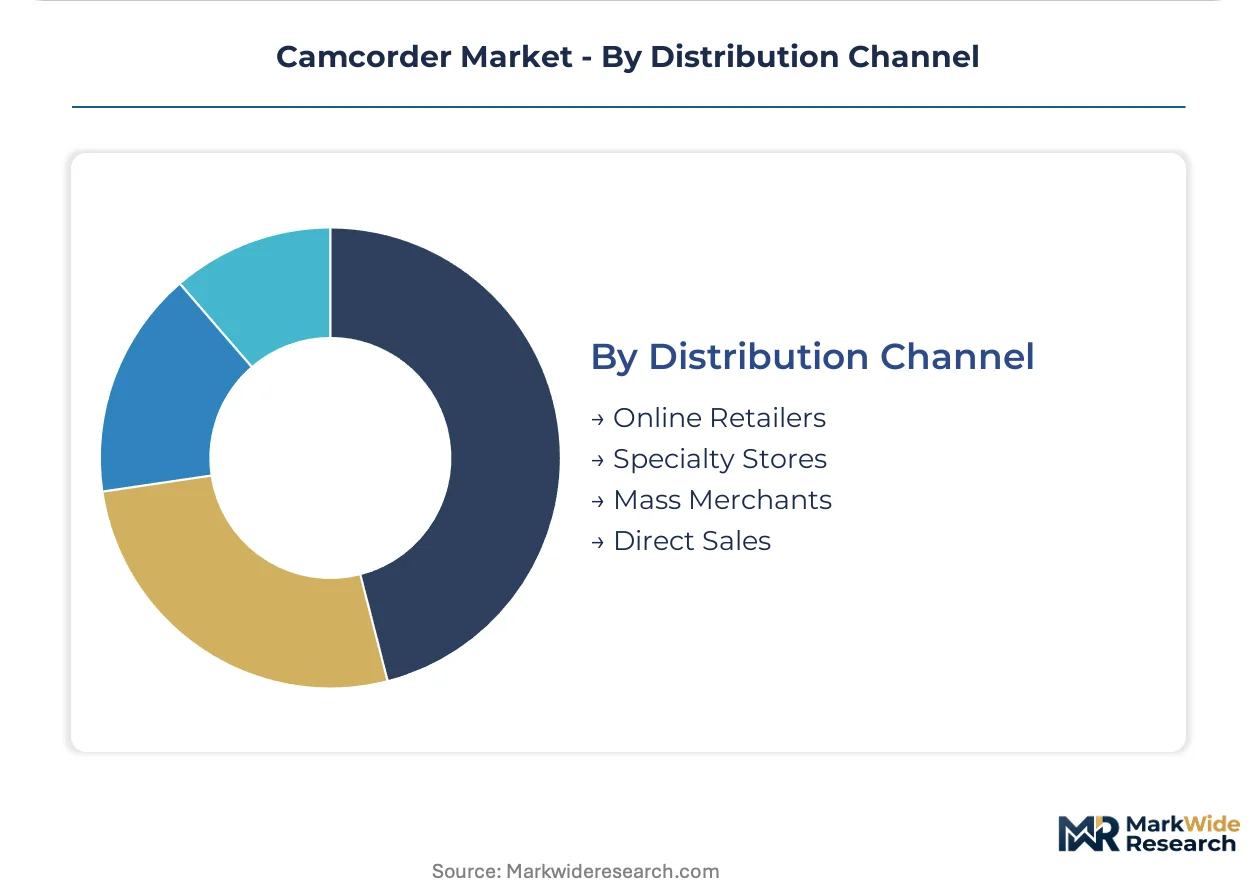
Transaction volume concentrates in Online Retailers; Direct Sales channels are expanding most quickly as manufacturers build creator-facing e-commerce infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates professional camcorder demand through its broadcast technology cluster, while content creator procurement in the United States and Germany drives 4K specification adoption across educational and streaming verticals.
Japan
Broadcast networks and media schools sustain replacement cycles for shoulder-mounted professional units. METI coordinates JIS certification standards that elevate export specifications for domestic manufacturers. Tokyo anchors sensor fabrication and precision lens engineering clusters serving global broadcast infrastructure.
United States
Twitch and YouTube monetization thresholds compel freelance creators toward dedicated 4K camcorders with optical stabilization. FCC wireless transmission protocols govern live broadcast equipment certification. Los Angeles and New York production hubs concentrate rental fleet operators serving documentary and wedding videography markets.
Germany
EBU standards compliance drives specification requirements for live production trucks and broadcast infrastructure. The EU F-Gas Regulation forces refrigerant phase-out in thermal management systems for professional rigs. Munich and Hamburg anchor broadcast engineering clusters integrating legacy SDI workflows with 4K upgrade cycles.
South Korea
Educational procurement mandates 4K capability for media school accreditation compliance. National broadcasters upgrade studio fleets to match regional streaming quality benchmarks. Seoul anchors CMOS sensor fabrication capacity supplying professional imaging equipment across Asia-Pacific markets.
India
Expanding media education sector under PLI scheme incentives accelerates fleet refresh for training facilities. Central electronics manufacturing incentives attract assembly investment for mid-tier professional units. Maharashtra and Karnataka concentrate educational procurement decisions for 4K-capable student production equipment.
Camcorder Market Vendor Landscape
Japanese producers anchor the premium tier through sensor fabrication and broadcast certification dominance; Chinese and South Korean electronics groups hold volume positions in prosumer and action segments. The vendor structure concentrates around three strategic archetypes: vertically integrated imaging conglomerates with lens ecosystem control, specialized broadcast equipment fabricators with live production integration expertise, and action-focused ruggedized hardware specialists. Competitive moves center on AI-enabled autofocus technology licensing and direct-to-creator distribution portal construction.
Within the vertically integrated tier, Sony Group Corporation and Canon Inc. exemplify archetypes combining sensor fabrication with optical engineering depth. Panasonic Holding Corporation occupies a position bridging broadcast infrastructure relationships and creator-facing product lines. These Japanese entities represent the concentration of professional imaging technology expertise that shapes global specification standards.
| Leading Market Players |
|---|
| Canon Inc. |
| Sony Group Corporation |
| Panasonic Holding Corporation |
| JVCKENWOOD Corporation |
| GoPro Inc. |
| Samsung Electronics |
| Blackmagic Design Pty Ltd |
| Nikon Corporation |
| FUJIFILM Corporation |
| Others |
Supply Flow & Price Mechanics
CMOS sensor fabrication migration toward stacked architectures is compressing die yields while concentrating advanced capacity in Japanese and South Korean foundries, simultaneously elevating input costs for professional-tier units and pricing mid-tier manufacturers out of broadcast-certification races. This technical transition feeds directly into how procurement officers negotiate fleet contracts across educational and broadcast verticals.
Pricing Analysis
Volume placements cluster in sub-broadcast HD specifications where price sensitivity among educational buyers enforces thin margins, while professional camcorders with EBU and ARIB certification command substantial premiums due to sensor-grade differentiation and thermal management compliance costs. Three-tier pricing structure across premium cinema, standard broadcast, and economy prosumer levels reflects certification tier and lens ecosystem depth as primary price differentiation drivers. Cost compression in the economy tier intensifies because smartphone substitution erodes casual demand, forcing manufacturers to absorb F-Gas Regulation redesign expenses without passing full costs to institutional buyers. Educational institutions exhibit highest price sensitivity due to depreciated fleet replacement cycles, whereas broadcast networks prioritize specification compliance over unit cost.
Supply Chain Analysis
JIS certification and EU AI Act algorithmic disclosure requirements gate component qualification, forcing module suppliers to maintain dual compliance documentation tracks for professional imaging subassemblies. Fabrication of broadcast-grade CMOS sensors draws from Japan, South Korea, and Taiwan, while precision optical glass and motorized lens assemblies rest on German and Japanese engineering clusters. Single-source vulnerability concentrates in advanced sensor lithography equipment, where ASML-dependent foundries create chokepoints for professional-grade chip supply. Distribution runs through manufacturer-direct B2B portals for broadcast fleet procurement, bypassing traditional dealer networks in volume transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act and F-Gas Regulation together construct a cost-of-compliance moat that favors incumbents with established certification infrastructure and dedicated regulatory affairs capacity, raising effective barriers for capital-constrained challengers.
For Market Incumbents: To counter smartphone computational photography erosion in the sub-broadcast tier, deepen backward integration into sensor fabrication partnerships in Japan and South Korea while expanding direct-to-creator distribution portals that bypass dealer margin extraction. Prioritize AI-enabled autofocus patent licensing to capture recurring revenue from new entrant feature development. For New Entrants and Emerging Players: AI-powered real-time subject tracking algorithms present a technology-first wedge for penetrating the solo content creator segment in India and Southeast Asia, where PLI scheme incentives reduce assembly cost bases and educational procurement mandates 4K capability without specifying brand heritage. Pursue white-label partnerships with regional electronics assemblers to circumvent broadcast certification overhead while targeting mid-tier professional specifications. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated imaging conglomerates possessing captive sensor supply and broadcast infrastructure relationships, given AI Act compliance timelines that delay competitor product launches by 8-14 months. Long-term viability hinges on firmware-as-a-service revenue streams extending equipment lifecycle monetization. Monitor JIS certification renewal waves as inflection indicators for replacement demand timing.| Strategic Initiative | Industry Significance |
|---|---|
| AI Autofocus Patent Licensing | Creates recurring royalty streams from new entrant feature development in EU and North American markets. |
| Direct-to-Creator Portal Launch | Bypasses dealer margin extraction while capturing Twitch and YouTube monetization-driven procurement decisions. |
| Backward Integration into Sensor Partnerships | Secures allocation priority at Japanese and South Korean foundries during capacity constraints. |
| F-Gas Regulation Thermal Redesign | Maintains European market access while elevating unit costs that filter price-sensitive competitors. |
| Subscription Firmware Model Expansion | Compresses initial equipment outlays for freelance creators while extending manufacturer revenue visibility. |
Methodological Framework
Document review covered SEC 10-K filings, METI technical standards publications, EU regulatory impact assessments, and broadcast equipment procurement databases, complemented by interviews with broadcast engineering directors, educational media school procurement officers, content creator equipment reviewers, and thermal management subsystem suppliers. Bottom-up triangulation across sensor shipment data and top-down validation through broadcast network fleet replacement schedules anchored volume estimates.
Unit and value outputs across the projection horizon reflect segmentation by product type, end-user sophistication tier, feature specification threshold, and regional regulatory cluster, with CAGRs derived from replacement cycle analysis and content creator penetration modeling. Forecast inputs incorporated PLI scheme incentive trajectories, JIS certification renewal calendars, and AI Act implementation timelines without specifying calendar years.
Several conditions sit outside the modeled scope, including unannounced smartphone computational photography breakthroughs, geopolitical disruption of sensor fabrication capacity, and abrupt wireless spectrum reallocation by national regulators. A model refresh is warranted upon material change in EU AI Act enforcement interpretation or F-Gas Regulation refrigerant substitution technology availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
PET Scanners Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
China Electron Microscopy Market
Imaging
360-Degree Camera Market
Imaging
Global Digital Photography Market
Imaging
Global 3D Imaging Market
Imaging
Photoacoustic Tomography Market
Imaging
North America IP Camera Market
Imaging
Global Microbolometer Market
Imaging
Specific Imaging Solution Market
Imaging
Photography Equipment Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Global Mobile Image Sensor Market
Imaging
Global AI in Computer Vision Market
Imaging
North America Multi Camera Vision Inspection Systems Market