
 Fine Blanking Tools Market | 2026-2036
Fine Blanking Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Fine Blanking Tools Market Foresight
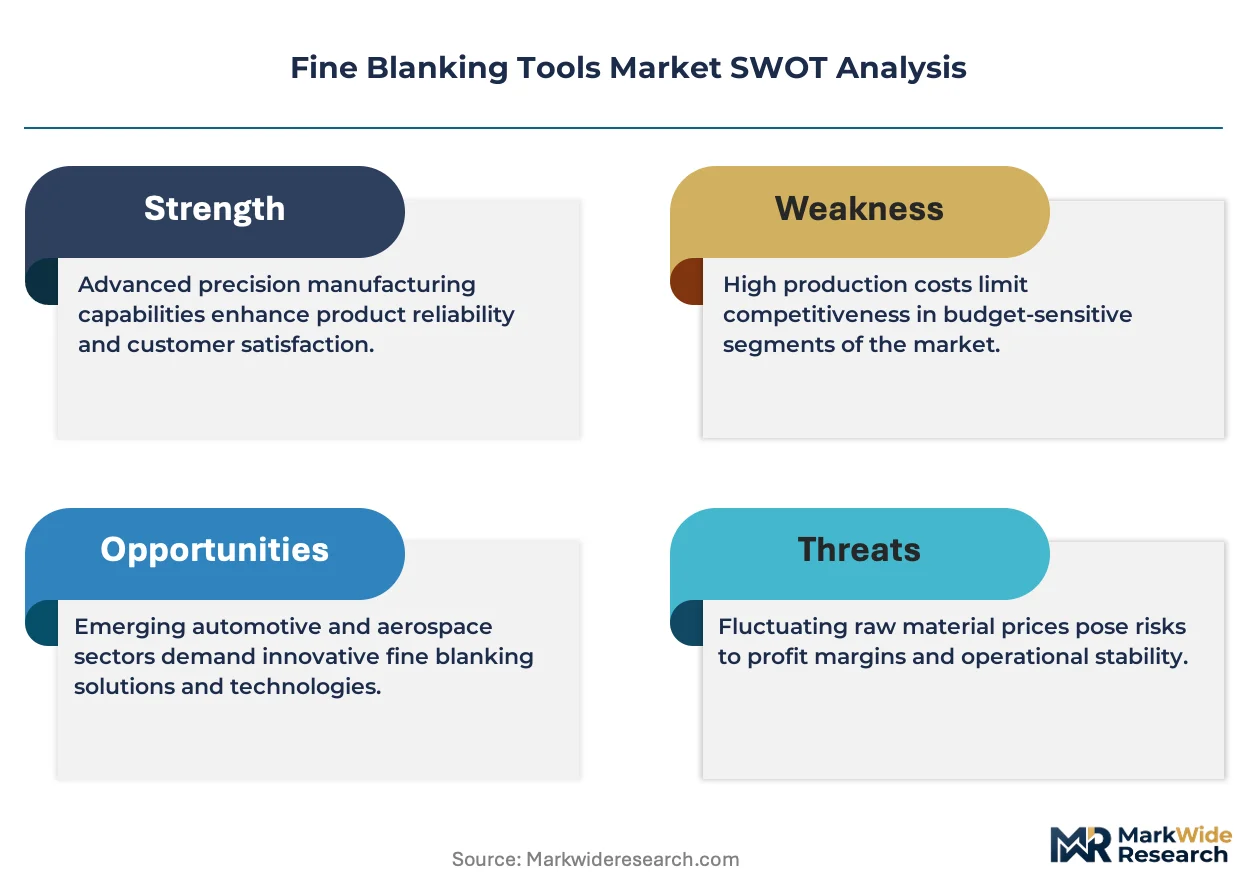
Tool-and-die machinist availability is unwinding capacity expansion timelines across European and East Asian fine blanking corridors. Feintool International Holding leverages its Swiss-German engineering base to sustain high-precision die production for electrified powertrain stampings. Schuler Group anchors large-press system supply through its Weingarten manufacturing complex, while Amada Co., Ltd. competes on servo-electric press technology leadership in Asian markets. Precision Resource differentiates through captive heat-treatment capabilities that control tooling life variance.
Fine blanking tools are hardened steel dies and punch assemblies engineered to 0.01 mm positional tolerances, operating within triple-action presses that apply constrictive counterpressure to produce shear-edge quality unattainable through conventional stamping. These tools enable net-shape manufacture of transmission plates, brake pads, and connector housings without secondary machining. Dies and presses capture the dominant value share, with dies commanding recurring replacement revenue and presses representing lumpy capital deployment; automotive components absorb the majority of output, though electronic parts for connector terminals are gaining share as miniaturization tightens dimensional requirements. Steel remains the default die material, though aluminum workpiece processing is expanding press specification complexity.
EMA's Machinery Directive and CE marking govern press safety integration in European installations, while REACH restricts certain surface coating chemistries used in die finishing. EPA hazardous waste rules shape U.S. tool regrinding and recoating economics, pressuring domestic fabricators toward closed-loop coolant systems. China's GB standards on mechanical press safety, administered by SAMR, create compliance cost asymmetries for imported toolsets. Stakeholders must monitor how battery-electric vehicle platform standardization alters blanking tool changeover frequency and die inventory strategies.
Market Dynamics
Powertrain electrification is compressing die changeover cycles across automotive stamping operations as battery-electric platforms demand novel component geometries with tighter tolerances than internal combustion architectures required.
Growth Catalysts
- EU Green Deal material traceability mandates:Procurement departments now require certified steel provenance documentation, redirecting tool sourcing toward audited supply chains with embedded carbon accounting.
- Miniaturization in electronic connector terminals:Dimensional tolerances below 0.05 mm are expanding fine blanking penetration into semiconductor packaging substrates previously machined.
- Baden-Württemberg tooling cluster density:Proximity between press manufacturers, heat-treatment specialists, and steel distributors compresses prototype-to-production timelines for European OEMs.
Market Restraints
- Tool-and-die machinist scarcity:Apprenticeship pipeline gaps across Germany, Switzerland, and Japan are extending die fabrication lead times by 30-40% versus 2019 baselines.
- Specialized alloy supply concentration:Premium tool steel production clusters in Sweden and Austria create single-source vulnerability for high-wear die applications.
- REACH surface coating restrictions:Chromium VI and certain PVD chemistries face phase-out timelines, forcing reformulation of die finishing processes with unproven wear characteristics.
Strategic Opportunities
- Servo-electric press retrofits in Southeast Asia:Thailand and Vietnam automotive component plants are upgrading mechanical presses, opening tool specification windows for precision die suppliers.
- Closed-loop coolant system integration:EPA hazardous waste rules are creating aftermarket service contracts for tool regrinding and recoating with environmental compliance bundled.
- Aluminum workpiece processing expansion:Battery tray and structural extrusion demand is pressuring die designers to develop geometries optimized for softer, gummier material flow.
Industry Challenges
- Triple-action press synchronization calibration:Counterpressure timing tolerances below 2 milliseconds require technicians with mechatronics expertise rarely available outside Swiss-German engineering centers.
- CE marking documentation burden:EMA's Machinery Directive compliance files for press-tool integration now average 14 months from specification to installation clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fine Blanking Tools Market |
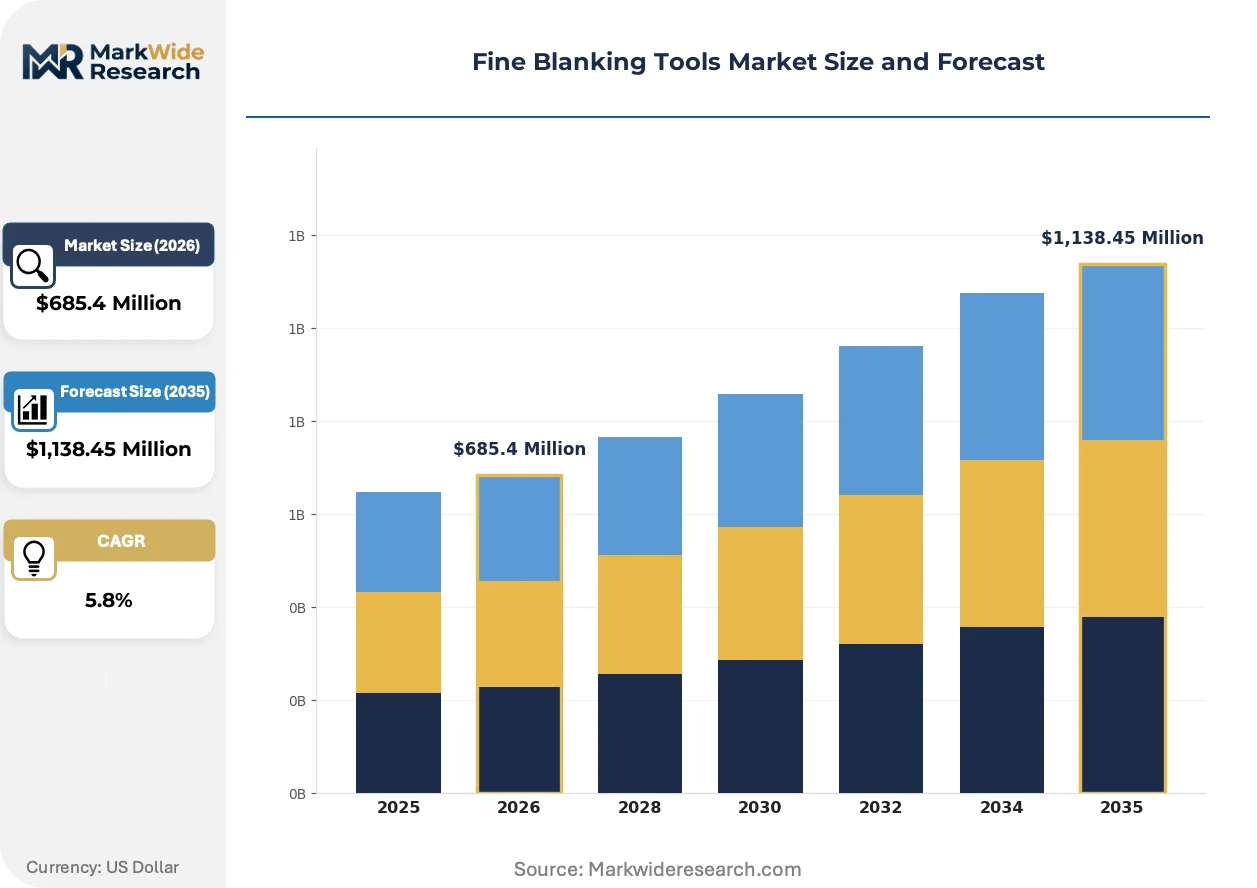
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dies, Presses, Systems, Accessories Application: Automotive Components, Electronic Parts, Appliances, Industrial Machinery Material: Steel, Aluminum, Copper, Alloys End User: OEMs, Tier-1 Suppliers, Fabricators, Aftermarket Providers |
| Companies Covered | Fagor Arrasate, Haco, Feintool International Holding, Aida Engineering, Ltd., Amada Co., Ltd., Schuler Group, Komatsu NTC, Precision Resource, Schneeberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fine Blanking Tools Market Shifts & Advancements
Digital die monitoring and predictive wear algorithms are migrating from aerospace into automotive stamping operations, compressing maintenance windows and reshaping spare parts inventory economics.
Carbide-insert die technologies are displacing through-hardened steel for high-volume transmission plate applications. Tier 1 suppliers in Stuttgart and Nagoya have adopted hybrid steel-carbide constructions for runs exceeding 5 million strokes. This material transition is displacing conventional heat-treatment suppliers from the highest-wear die segments.
REACH authorization requirements for chromium compounds are forcing PVD coating houses to validate tungsten-disulfide and diamond-like carbon alternatives. Die finishing operations in Solingen and Sheffield face reformulation costs without guaranteed friction coefficient equivalence. Surface engineering specialists are responding with multi-layer deposition protocols that extend qualification timelines.
Automotive OEMs are consolidating tool procurement under long-term service agreements that bundle die design, press maintenance, and per-part pricing. Tier 2 stampers in Ontario and Lower Saxony report margin compression as volume commitments replace spot-order relationships. This contractual shift is most pronounced where battery-electric platform volumes remain uncertain.
Fine Blanking Tools Market Segmentation
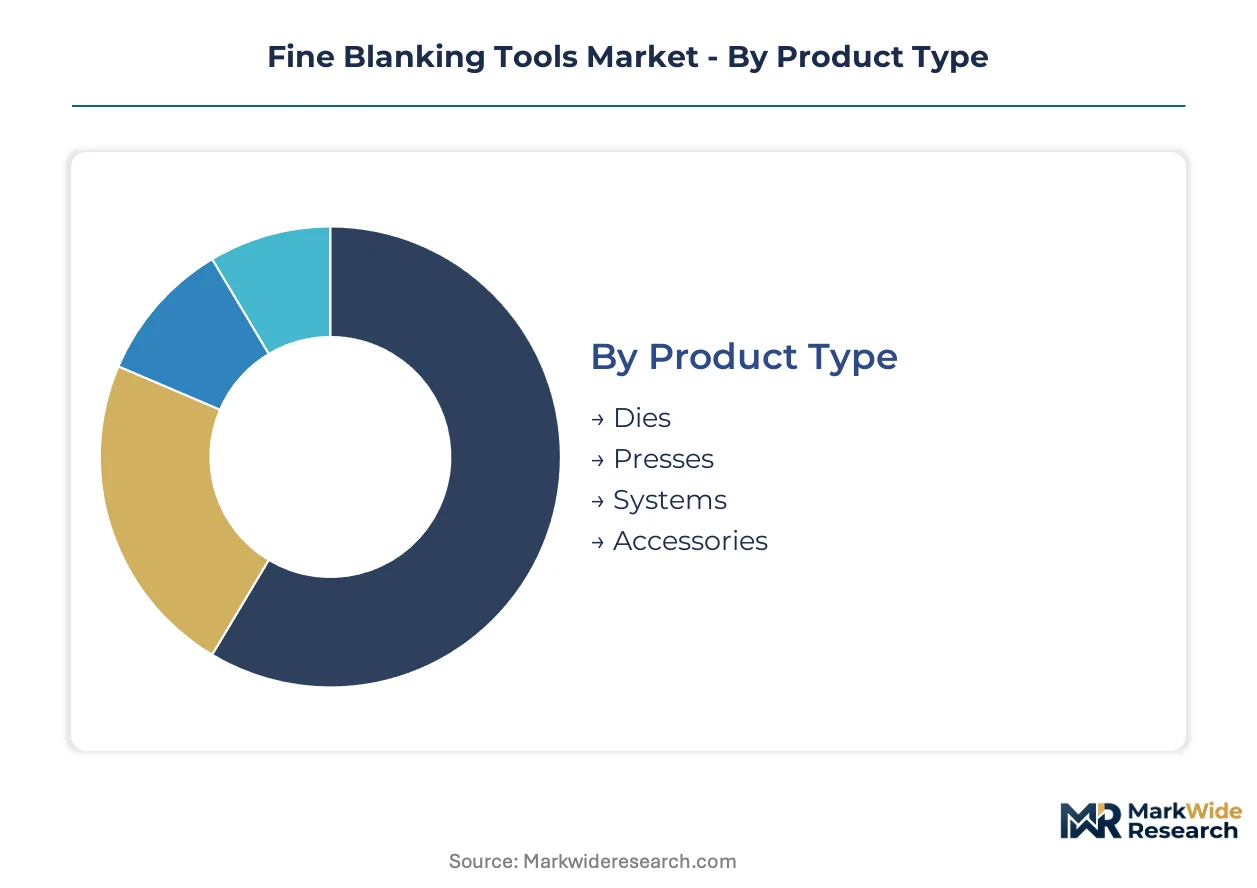
Fine blanking tool segmentation reveals how value pools concentrate in recurring die replacement versus lumpy press capital deployment. Understanding margin distribution across product tiers and end-user channels sharpens procurement and competitive positioning strategies for stakeholders navigating electrification-driven demand shifts.
Product Type:
Margin pools concentrate in precision dies, where recurring replacement revenue and captive heat-treatment capabilities sustain pricing power against commoditized press hardware.
- Dies:Hardened steel punch and die assemblies engineered to 0.01 mm positional tolerances, generating recurring replacement revenue streams as wear limits approach after 2-5 million strokes. Demand concentrates in Germany's Baden-Württemberg cluster, where proximity between Feintool's engineering base and automotive OEM technical centers compresses prototype iteration cycles for electrified powertrain stampings.
- Presses:Triple-action mechanical and servo-electric systems applying constrictive counterpressure for shear-edge quality unattainable through conventional stamping. Schuler Group's Weingarten manufacturing complex anchors European supply, while Amada Co., Ltd. competes on servo-electric technology leadership in Asian markets where energy efficiency specifications are tightening.
- Systems:Integrated press-die-feeder configurations with synchronized automation for high-volume production environments. Japanese and Swiss suppliers dominate this tier through mechatronics integration expertise.
- Accessories:Die changeover carts, lubrication systems, and monitoring sensors supporting operational efficiency. This segment expands with digital die monitoring adoption.
Dies hold installed capacity. Systems are rotating up the share rankings as automotive OEMs consolidate procurement under bundled service agreements.
Application:
Volume distribution tracks automotive platform electrification, with battery-electric architectures demanding novel component geometries that compress die changeover cycles versus internal combustion baselines.
- Automotive Components:Transmission plates, brake pads, and structural stampings absorbing the majority of fine blanking output. Powertrain electrification is reshaping demand profiles as battery tray and motor housing geometries require softer aluminum workpiece processing capabilities.
- Electronic Parts:Connector terminals and semiconductor packaging substrates with dimensional tolerances below 0.05 mm. Miniaturization trends are expanding fine blanking penetration into machined component territories previously served by precision machining centers.
- Appliances:Precision metal housings and structural elements for consumer durable manufacturers. Cost pressures in this segment favor standardized die configurations over custom engineering.
- Industrial Machinery:Specialized components for equipment builders requiring net-shape manufacture without secondary machining. Demand fragments across diverse end-use specifications.
Automotive Components anchor volume. Electronic Parts are climbing the fastest as connector miniaturization tightens dimensional requirements.
Material:
Steel maintains default status for die construction, while workpiece material expansion into aluminum and copper alloys is pressuring press specification complexity and die geometry optimization.
- Steel:Premium tool steels from Swedish and Austrian production clusters dominate high-wear die applications. REACH compliance and EU Green Deal material traceability mandates are redirecting procurement toward certified suppliers with embedded carbon accounting documentation.
- Aluminum:Battery tray and structural extrusion processing demands die geometries optimized for softer, gummier material flow characteristics. This workpiece expansion is driving servo-electric press retrofits in Southeast Asian automotive component plants.
- Copper:Electrical conductivity applications in connector terminals and busbar stampings. Miniaturization trends favor fine blanking over machining for complex copper geometries.
- Alloys:Specialized material combinations for extreme wear or corrosion resistance requirements. Supply concentration creates single-source vulnerability for Tier 2 stampers.
Steel holds installed capacity. Aluminum is rotating up the share rankings with battery-electric platform proliferation.
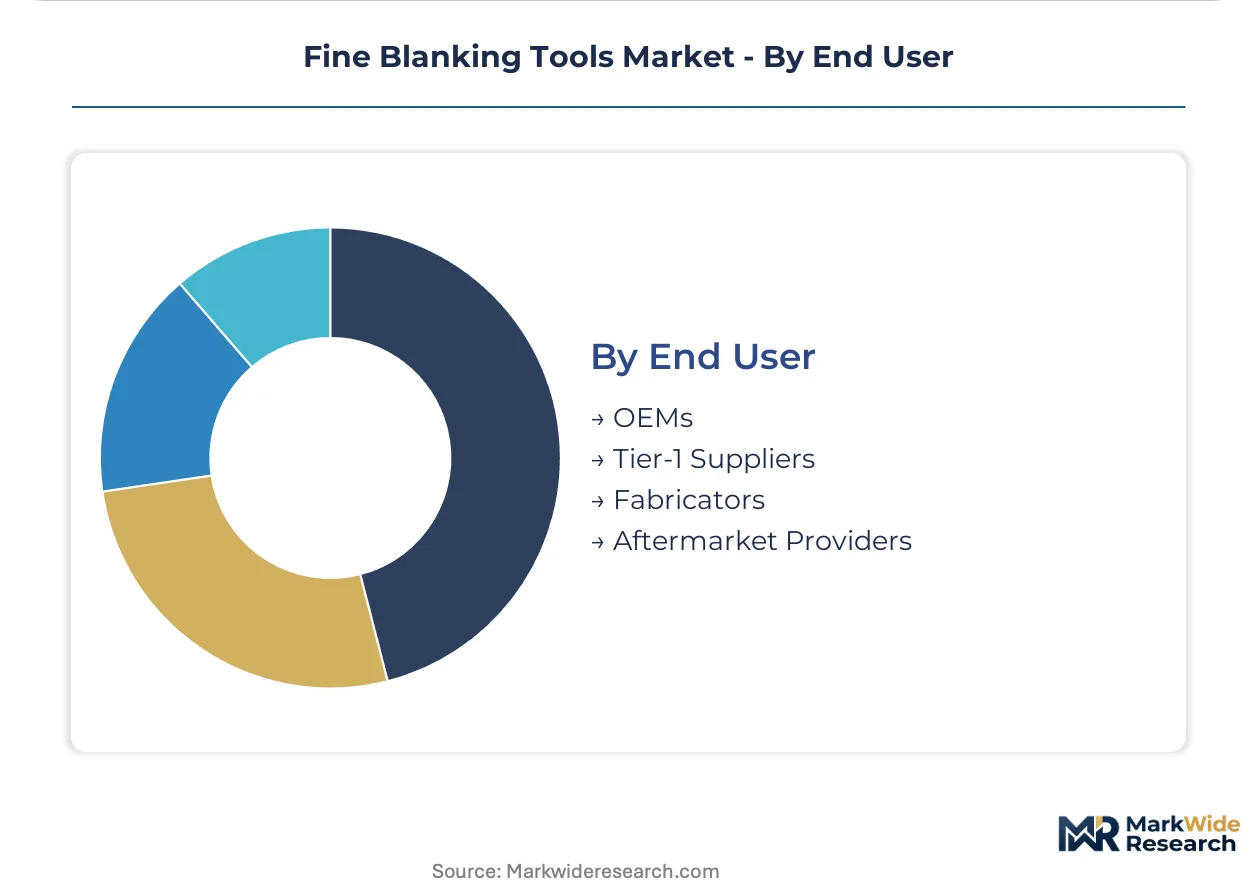
End User:
Procurement authority is consolidating under long-term service agreements that bundle die design, press maintenance, and per-part pricing, compressing margins for Tier 2 stampers.
- OEMs:Automotive and electronics original equipment manufacturers with direct tool ownership and captive stamping operations. These buyers leverage volume scale for bundled service agreements that shift inventory risk to suppliers.
- Tier-1 Suppliers:Contract manufacturers serving OEM assembly lines with dedicated production capacity. Margin compression is most pronounced where battery-electric platform volumes remain uncertain and volume commitments replace spot-order relationships.
- Fabricators:Independent metal stampers serving diverse industrial end-uses with flexible capacity. These operators prioritize die changeover speed and standardized tooling configurations.
- Aftermarket Providers:Tool regrinding, recoating, and refurbishment services. EPA hazardous waste rules are creating environmental compliance bundling opportunities in closed-loop coolant system integration.
OEMs hold installed capacity. Tier-1 Suppliers are rotating up the share rankings as outsourcing consolidates captive stamping operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors European procurement compliance, redirecting tool sourcing toward certified steel suppliers with embedded carbon accounting documentation across multiple jurisdictions.
Germany
Powertrain electrification is compressing die changeover cycles at Stuttgart and Wolfsburg OEM technical centers. EU Green Deal material traceability mandates require documented steel provenance from mill to finished die. Baden-Württemberg's tooling cluster concentrates Feintool's engineering base with Schuler's Weingarten manufacturing complex and regional heat-treatment specialists.
Japan
Miniaturization in electronic connector terminals is expanding fine blanking penetration into semiconductor packaging substrates. METI's energy efficiency specifications are tightening press retrofit requirements across Nagoya and Osaka industrial corridors. Chubu region mechatronics integration expertise sustains synchronized automation leadership for high-volume production environments.
United States
EPA hazardous waste rules are pressuring domestic fabricators toward closed-loop coolant systems for tool regrinding operations. Tier 1 stampers in Michigan and Ontario report margin compression under bundled service agreements with uncertain battery-electric platform volumes. Detroit-area automotive OEMs are consolidating procurement authority under long-term die design and maintenance contracts.
China
GB standards on mechanical press safety administered by SAMR create compliance cost asymmetries for imported toolsets. Battery tray and structural extrusion demand for electric vehicles is driving aluminum workpiece processing expansion. Yangtze River Delta automotive component plants are upgrading mechanical presses, opening specification windows for precision die suppliers.
Switzerland
Swissmedic's quality system requirements reinforce precision engineering standards for medical device stampings with sub-0.05 mm tolerances. Apprenticeship pipeline gaps across German-speaking regions are extending die fabrication lead times. Swiss-German engineering centers retain scarce mechatronics expertise for triple-action press synchronization calibration below 2 millisecond tolerances.
Fine Blanking Tools Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with die manufacturers commanding recurring replacement revenue against lumpy press capital deployment. The structure concentrates precision engineering capabilities in Swiss-German and Japanese industrial corridors where apprenticeship traditions sustain technical workforce pipelines. Two archetypes dominate: captive heat-treatment specialists controlling tooling life variance, and servo-electric technology leaders competing on energy efficiency specifications. Competitive moves center on bundled service agreements that shift inventory risk to suppliers, and geographic expansion through Southeast Asian automotive component plant retrofits.
Among the integrated tier, Feintool International Holding and Schuler Group anchor European supply through Swiss-German engineering density, while Amada Co., Ltd. occupies a position within Asian servo-electric press technology leadership. These three exemplify how regional industrial clustering sustains competitive differentiation—Feintool through proximity to Baden-Württemberg automotive OEM technical centers, Schuler through its Weingarten manufacturing complex scale, and Amada through responsiveness to tightening energy efficiency specifications in Japanese and Southeast Asian markets. Precision Resource represents the captive capability archetype, with heat-treatment integration controlling variance in high-wear applications.
| Leading Market Players |
|---|
| Fagor Arrasate |
| Haco |
| Feintool International Holding |
| Aida Engineering, Ltd. |
| Amada Co., Ltd. |
| Schuler Group |
| Komatsu NTC |
| Precision Resource |
| Schneeberger |
| Others |
Supply & Pricing Matrix
Long-term service agreements that bundle die design, press maintenance, and per-part pricing lock in supply access for automotive OEMs while compressing margin visibility for Tier 2 stampers facing uncertain battery-electric platform volumes.
Pricing Analysis
German and Swiss suppliers command 15-25% premiums over Southeast Asian competitors due to apprenticeship-sustained mechatronics expertise for triple-action press calibration. Three-tier pricing structure across premium certified-steel dies, standard through-hardened configurations, and economy retrofit kits tracks REACH compliance documentation and heat-treatment integration depth. Cost compression in the standard tier intensifies as servo-electric press retrofits in Thailand and Vietnam open specification windows for price-competitive entrants. Tier 1 suppliers exhibit highest price sensitivity due to bundled contract margin pressure, while OEMs with captive stamping operations prioritize tooling life variance control over unit cost.
Supply Chain Analysis
Sweden and Austria anchor premium tool steel production for high-wear die applications, while Germany's Baden-Württemberg cluster concentrates Feintool's engineering base with Schuler's Weingarten manufacturing complex and regional heat-treatment specialists. Die fabrication draws from specialized alloy feedstock, precision machining capacity, and PVD coating services concentrated in Solingen and Sheffield. Single-source vulnerability in Swedish-Austrian steel production creates supply chain risk for Tier 2 stampers without qualified secondary sources. Distribution runs through OEM technical centers in Stuttgart and Wolfsburg, Tier 1 supplier plants in Lower Saxony and Ontario, and independent fabricators serving diverse industrial end-uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fine blanking tools represent a cyclical recovery play as powertrain electrification forces die changeover cycle compression and automotive OEMs consolidate procurement under bundled service agreements.
For Market Incumbents: Shield recurring replacement revenue streams in precision dies by deepening captive heat-treatment capabilities that control tooling life variance against carbide-insert displacement threats. Backward integration into certified steel sourcing with embedded carbon accounting documentation defends position against REACH-compliant European competitors while extending lead time advantages over Asian challengers. For New Entrants and Emerging Players: Anchor in Southeast Asian servo-electric press retrofit demand across Thailand and Vietnam automotive component plants, where specification windows are opening for precision die suppliers without entrenched supplier relationships. Target aluminum workpiece processing capabilities for battery tray stampings as the most penetrable application segment, leveraging local technical partnerships for triple-action press synchronization expertise. For Investors and Strategic Acquirers: Capital is best deployed toward captive heat-treatment specialists controlling tooling life variance in high-wear applications, with long-term viability hinging on electrification-driven die changeover frequency sustained across the next decade. Watch battery-electric platform standardization progress as the critical signal for inflection in die inventory strategies and bundled service agreement pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Press Retrofit | Thailand and Vietnam automotive plants upgrade mechanical presses, opening specification windows for precision die suppliers. |
| Certified Steel Supply Integration | EU Green Deal traceability mandates redirect procurement toward audited supply chains with embedded carbon accounting. |
| Carbide-Insert Die Technology | Hybrid steel-carbide constructions displace conventional heat-treatment suppliers from highest-wear transmission plate segments. |
| Closed-Loop Coolant System Deployment | EPA hazardous waste rules create aftermarket service contracts bundling environmental compliance with tool regrinding operations. |
| Aluminum Workpiece Processing Capability | Battery tray and structural extrusion demand pressures die designers to optimize geometries for softer material flow characteristics. |
Research Methodology
The analysis maps dies, presses, systems, and accessories segments, each validated through tool-and-die machinists, OEM platform engineers, Tier 1 supplier procurement leads, and heat-treatment specialists across primary interviews. Secondary sources include ECHA REACH filings, EPA hazardous waste rule documentation, SAMR GB standards, SEC 10-K disclosures from listed press manufacturers, and automotive production databases. Bottom-up die replacement frequency modeling triangulates against top-down fine blanking capacity estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across product type, application, material, and end-user dimensions plus regional regulatory cluster differentiation. CAGRs derive from electrification-driven die changeover cycle compression rates, miniaturization penetration curves for electronic connector terminals, and servo-electric press retrofit adoption patterns. Forecast inputs incorporate apprenticeship pipeline gap projections for German-Swiss-Japanese machining corridors and REACH authorization timelines for chromium compound phase-outs.
Material uncertainties — battery-electric platform volume realization, specialized alloy supply disruption, and PVD coating reformulation performance — sit outside the modeled envelope. Forecasts reflect assumptions about sustained automotive OEM consolidation of procurement authority and continued Baden-Württemberg cluster density advantages. Recalibration cycles align with material shifts in powertrain electrification penetration and EU Green Deal enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Vertical Milling Machine Market
Tools
Garden Digging Tools Market
Tools
Powder Compacting Pressers Market
Tools
Squeegee Market
Tools
Global DC Torque Tool Market
Tools
Tool Hammer Market
Tools
Sander Market
Tools
Flooring Tools Market
Tools
Floor Saw Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Global Scarifiers Market
Tools
Wire Cutters Market
Tools
Riveting Tools Market
Tools
Power Tool Accessories Market
Tools
Mortiser Market