
 Cordless Planer Market | 2026-2036
Cordless Planer Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Planer Market Analytics
Brushless-motor tier upgrades is redrawing competitive boundaries in cordless planers. Makita leverages its battery-platform ecosystem to sustain repeat purchases across professional trades. DeWalt anchors the North American contractor channel with deep retail penetration and service-network density. Bosch differentiates through vibration-dampening engineering and precision-depth mechanisms aimed at European finish carpenters.
A cordless planer is a handheld or portable surfacing tool powered by rechargeable battery packs, typically operating at 18V to 20V with no-load speeds between 10,000 and 16,000 RPM, designed to shave thin layers from wood stock for dimensional smoothing or edge chamfering. The tool serves professional carpenters, furniture makers, and renovation contractors who require jobsite mobility without generator tethering or cord hazards. Handheld planers dominate volume shipments due to their utility in trim installation and door-hanging workflows, while bench planers command higher price points in dedicated woodworking shops. Battery-powered configurations are displacing corded electric variants as lithium-cell energy density improves and platform interoperability becomes standard across major brands.
FCC equipment authorization governs electromagnetic emissions from cordless planer battery chargers sold in the United States, while EPA hazardous waste rules affect end-of-life lithium-ion cell disposal obligations for manufacturers and commercial users. OSHA silica exposure standards indirectly shape dust-collection feature prioritization, as contractors face jobsite air-quality enforcement. Stakeholders must monitor battery-platform lock-in dynamics and evolving cell-chemistry regulations that could alter replacement-part economics and brand-switching costs.
Market Dynamics
Battery-platform interoperability is restructuring cordless planer purchasing patterns. Contractors now prioritize tool ecosystems over individual unit specifications, locking procurement into single-brand battery architectures that extend runtime and reduce charger redundancy across jobsites.
Growth Catalysts
- OSHA silica exposure enforcement:Contractors face escalating jobsite air-quality inspections, accelerating dust-collection feature prioritization in cordless planer specifications.
- Lithium-ion cell density improvements:Energy storage advances extend per-charge runtime, reducing mid-project battery swaps for residential renovation crews.
- German precision woodworking traditions:Premium cordless tool demand concentrates in Bavarian and Baden-Württemberg furniture manufacturing clusters.
Market Restraints
- Cobalt supply concentration:Battery cell production depends on Democratic Republic of Congo mining operations, exposing manufacturers to geopolitical disruption and price volatility.
- Platform lock-in economics:Proprietary battery architectures create switching costs that deter brand migration even when superior performance emerges.
- End-of-life disposal obligations:EPA hazardous waste rules impose compliance burdens on commercial users and manufacturers managing spent lithium-ion cells.
Strategic Opportunities
- India woodworking SME segment:Untapped demand exists among Bangalore and Pune furniture startups seeking cordless mobility without generator infrastructure.
- Brushless motor convergence with smart sensors:Integration of load-sensing electronics enables automatic speed adjustment, reducing user fatigue and extending blade life.
- EU Green Deal circularity mandates:Battery remanufacturing requirements create service-revenue streams for authorized repair networks.
Industry Challenges
- Skilled technician scarcity:Brushless motor diagnostics and battery management system repair require electronics expertise absent from traditional tool-and-die training programs.
- Certification timeline compression:FCC equipment authorization for new charger designs delays product launches in the United States market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Planer Market |
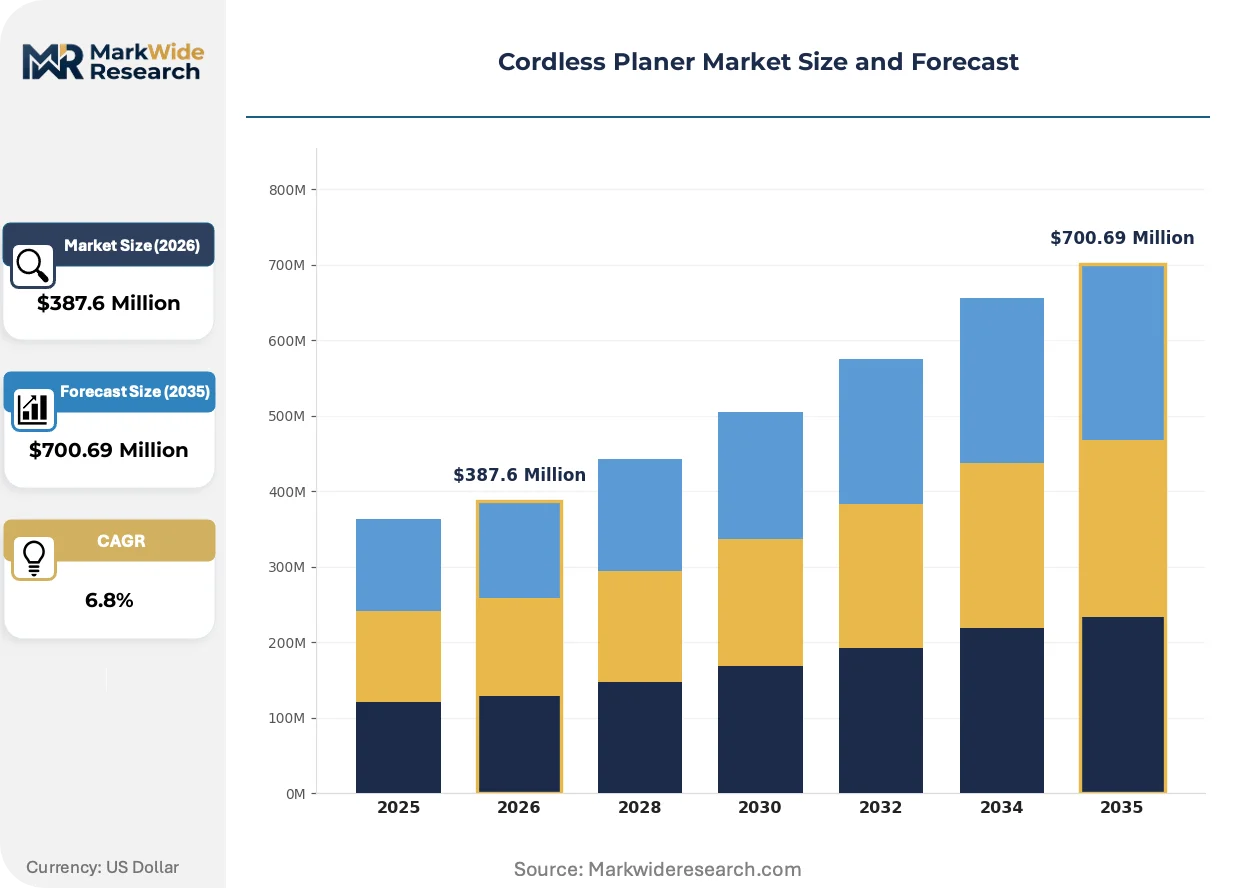
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Planer, Portable Planer, Bench Planer, Electric Planer Power Source: Battery Powered, Corded Electric, Hybrid, Solar Powered Application: Woodworking, Carpentry, DIY, Furniture Production Feature: Variable Speed Control, Dust Collection, Adjustable Depth, Lightweight Design |
| Companies Covered | DeWalt, Makita, Bosch, Milwaukee, Metabo HPT, Ryobi, Black & Decker Corporation, C. & E. Fein GmbH, Craftsman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Planer Market Evolving Landscape
Tool intelligence and connectivity are redefining cordless planer value propositions. Sensor integration, platform software, and predictive maintenance capabilities are shifting competitive differentiation from hardware specifications to ecosystem stickiness and data-enabled service models.
Brushless motor architectures are fragmenting cordless planer performance tiers. These electronically commutated systems eliminate carbon brush friction losses, delivering higher torque-to-weight ratios for finish carpenters. Professional trades in Germany and Japan adopt premium configurations fastest, compressing the addressable market for brushed-motor economy units.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant recovery tool integration. Cordless planer manufacturers serving HVAC-adjacent carpentry must certify compatibility with fluorinated gas handling protocols. Finish contractors in France and Italy now specify dual-use tools that bridge woodworking and mechanical system installation.
Subscription-based fleet management is displacing unit ownership among multi-trade contractors. Large renovation firms in the United States negotiate tool-plus-service bundles that include automatic battery replacement and blade sharpening. This procurement model concentrates purchasing power with national account managers, marginalizing independent dealer networks.
Cordless Planer Market Segmentation
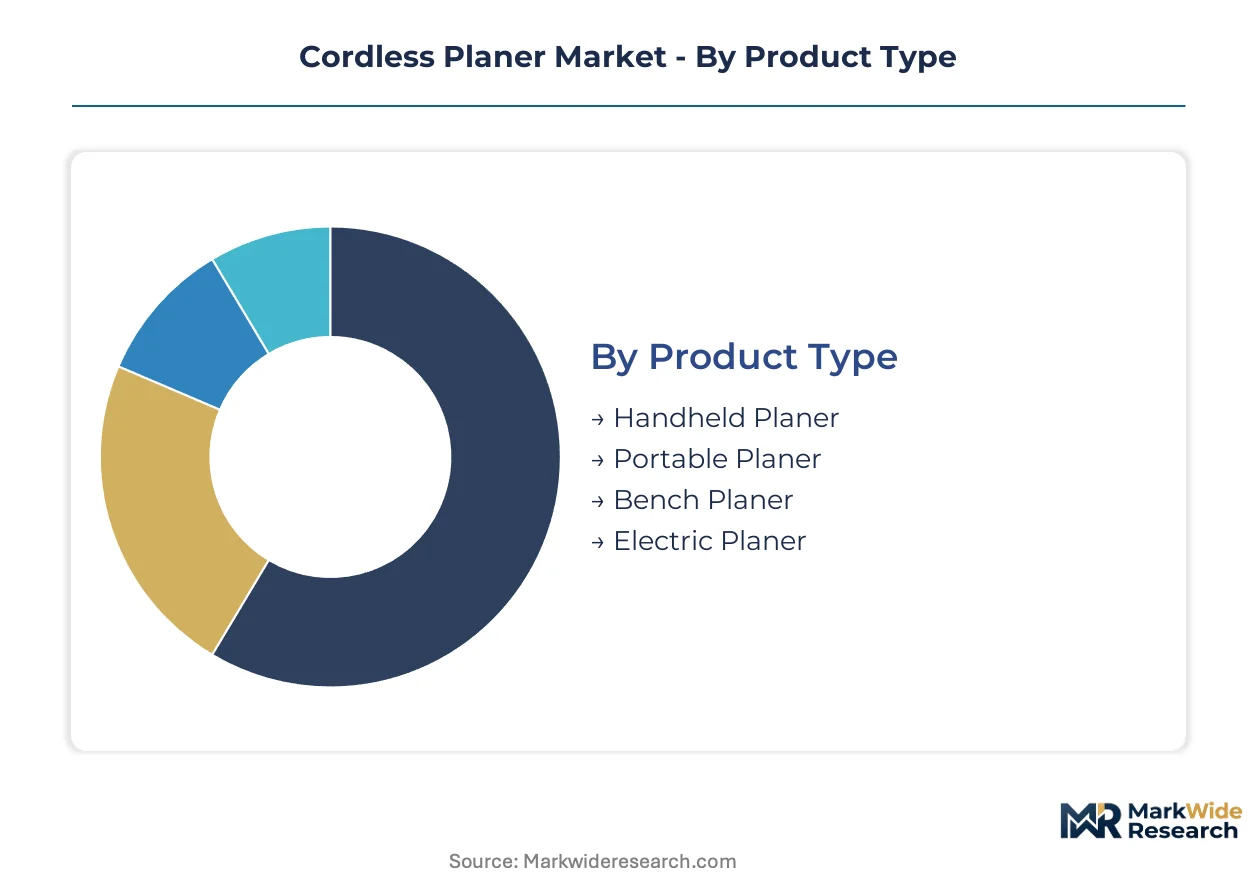
Cordless planer purchasing patterns fragment sharply across tool configurations and user workflows. Battery-platform economics and jobsite mobility requirements reshape which segments capture contractor spend versus hobbyist budgets.
Product Type:
Handheld configurations face the strongest substitution pressure from corded alternatives in stationary shop environments where outlet access is guaranteed.
- Handheld Planer:Compact 18V-20V units weighing under 7 pounds dominate trim carpentry and door-hanging workflows in residential renovation. German finish contractors in Bavaria drive premium-specification demand for vibration-dampened housings.
- Portable Planer:Mid-size battery-powered surfacing tools bridge jobsite mobility with stock removal capacity for flooring installers. Demand concentrates among US multi-trade contractors seeking single-platform compatibility across drilling and cutting tools.
- Bench Planer:Stationary workshop units with extended infeed tables serve furniture production clusters in Baden-Württemberg and North Carolina.
- Electric Planer:Corded variants retain cost-sensitive hobbyist segments where runtime certainty outweighs mobility value.
Handheld planers anchor the volume base while portable configurations gain share at the steepest rate.
Power Source:
Cost tier stratification separates professional battery ecosystems from entry-level corded purchases in emerging markets.
- Battery Powered:Lithium-ion cell architectures at 18V, 20V, and 40V max platforms enable cordless mobility without generator tethering. OSHA silica enforcement in US construction accelerates dust-integrated battery tool specifications.
- Corded Electric:AC-powered units retain price-sensitive DIY segments and dedicated shop environments with reliable grid access.
- Hybrid:Dual-power tools accepting battery or corded operation serve contractors bridging jobsite and workshop workflows.
- Solar Powered:Photovoltaic-charged configurations address off-grid renovation projects in rural India and remote Australian construction sites.
Battery powered systems anchor the volume base while hybrid configurations expand most quickly among fleet-managed contractor accounts.
Application:
Customer type maturity separates established professional trades from emerging hobbyist segments with diverging feature priorities.
- Woodworking:Precision surfacing for hardwood stock in furniture manufacturing demands micro-adjustable depth stops and spiral cutterheads. Japanese master craftsmen in Gifu Prefecture sustain premium tool specifications.
- Carpentry:Rough framing and finish trim installation prioritize runtime duration and blade durability over surface quality metrics.
- DIY:Home improvement enthusiasts purchase through retail channels with price sensitivity and bundled battery incentives driving selection.
- Furniture Production:SME manufacturers in Bangalore and Pune seek cordless mobility without captive generator infrastructure.
Carpentry applications anchor the volume base while furniture production climbs the fastest among Asian manufacturing clusters.
Feature:
Supply concentration in brushless motor controllers and sensor modules shapes which performance tiers achieve scale economics.
- Variable Speed Control:Electronic load-sensing modules adjust RPM between 10,000 and 16,000 based on stock density, extending blade life in hardwood applications.
- Dust Collection:Integrated vacuum ports and chip ejection systems address OSHA silica exposure enforcement in US commercial construction.
- Adjustable Depth:Precision depth mechanisms with 0.1mm increments serve European finish carpentry traditions in Germany and Switzerland.
- Lightweight Design:Magnesium housings and composite bases reduce operator fatigue during extended overhead work.
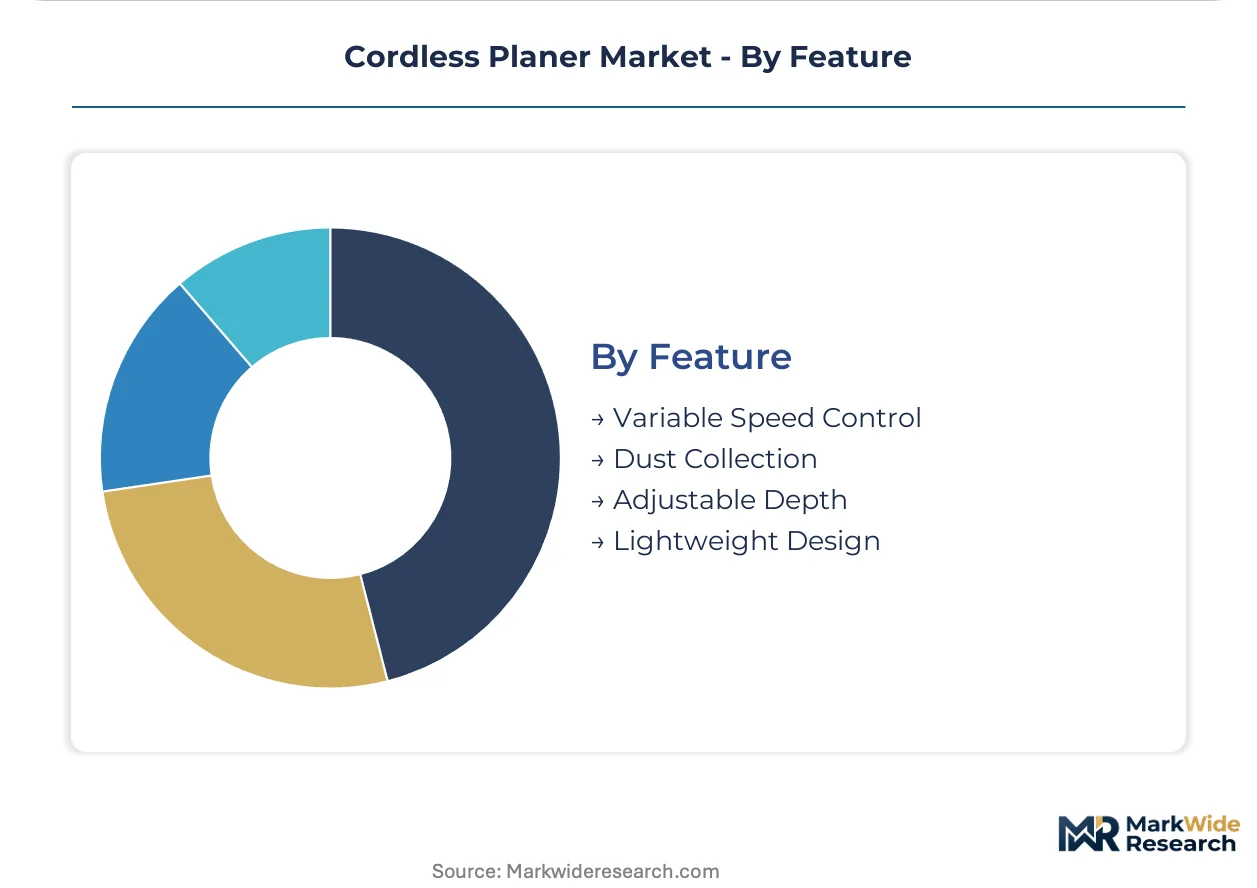
Dust collection features anchor the volume base while variable speed control gains share fastest among professional-tier specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor purchasing power varies sharply across geographies. German finish carpenters absorb 40% price premiums for vibration-dampened housings, while Indian furniture startups prioritize bare-tool economics over feature depth.
United States
Multi-trade renovation contractors drive cordless planer volume through battery-platform standardization across drilling and cutting tools. OSHA silica exposure enforcement accelerates dust-collection feature prioritization in commercial construction specifications. Demand concentrates in Texas and Florida residential construction corridors where generator-free mobility reduces jobsite setup time.
Germany
Precision woodworking traditions in Bavaria and Baden-Württemberg sustain premium cordless tool purchases with micro-adjustable depth requirements. EU Green Deal circularity mandates create battery remanufacturing service revenue streams for authorized repair networks. Stuttgart-area furniture manufacturing clusters specify brushless motor configurations with 0.1mm depth precision.
Japan
Master craftsmen in Gifu Prefecture maintain demand for premium surfacing tools with spiral cutterhead specifications. METI industrial standards shape battery management system interoperability requirements across professional tool platforms. Nagoya-area woodworking SMEs adopt variable speed control modules for hardwood density adaptation.
India
Furniture production startups in Bangalore and Pune seek cordless mobility without captive generator infrastructure. BIS certification requirements for lithium-ion cell imports create compliance barriers for budget tool distributors. Maharashtra woodworking clusters demonstrate fastest adoption growth among Asian manufacturing SMEs.
Australia
Remote construction sites in Western Australia and Queensland drive solar-powered tool configurations for off-grid renovation projects. TGA-equivalent electrical safety standards govern battery charger electromagnetic emissions certification. Sydney and Melbourne metropolitan contractors prioritize lightweight magnesium housing designs for overhead installation work.
Cordless Planer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with brushless motor specialists commanding premium positioning against brushed-motor economy suppliers. The market structure consolidates around battery-platform ecosystems rather than individual unit manufacturers, locking contractors into single-brand procurement patterns. Three archetypes dominate: integrated power-tool conglomerates with cross-category battery interoperability, specialized surfacing equipment manufacturers with precision engineering heritage, and private-label assemblers serving price-sensitive retail channels. Competitive moves center on platform lock-in expansion and dust-collection feature differentiation.
Within the integrated power-tool tier, DeWalt and Makita exemplify battery-ecosystem dominance, while C. & E. Fein GmbH represents precision-engineering specialization for European finish trades. These anchors demonstrate how geographic origin and corporate structure shape competitive positioning—American and Japanese conglomerates leverage scale-driven platform economics, while German GmbH-format specialists command premium positioning through vibration-dampening engineering traditions.
| Leading Market Players |
|---|
| DeWalt |
| Makita |
| Bosch |
| Milwaukee |
| Metabo HPT |
| Ryobi |
| Black & Decker Corporation |
| C. & E. Fein GmbH |
| Craftsman |
| Others |
Value Network & Pricing Analysis
OSHA silica exposure enforcement gates both supplier qualification and price differentiation in cordless planers, as contractors now mandate dust-integrated configurations that separate premium-tier manufacturers from brushed-motor economy assemblers. Battery-platform lock-in creates switching costs that insulate incumbent pricing power while cobalt supply volatility feeds through to cell replacement economics.
Pricing Analysis
After-sales revenue from battery replacement cycles and authorized service networks drives lifetime value capture for cordless planer manufacturers. Three-tier pricing structure across premium brushless, standard brushed-motor, and economy private-label tiers reflects motor architecture and depth-precision certification levels. Pricing pressure stems from lithium-ion cell commodity volatility and cobalt supply disruption risk. DIY retail channels exhibit highest price sensitivity, while German finish contractors absorb substantial premiums for vibration-dampened housings with micro-adjustable depth mechanisms.
Supply Chain Analysis
Inventory lead times for brushless motor controllers and lithium-ion cells extend procurement cycles for cordless planer assemblers. Manufacturing concentrates in China for battery cells, Japan for precision motor components, and Germany for vibration-dampening engineering. Raw material dependencies center on cobalt from the Democratic Republic of Congo, lithium from Australia and Chile, and rare-earth magnets from China. Single-source vulnerability in cobalt mining operations exposes producers to geopolitical disruption. Distribution runs through national account managers serving multi-trade contractors and independent dealer networks supplying residential renovation crews.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordless planer market expansion qualifies as high-growth disruption driven by lithium-ion energy density improvements and brushless motor convergence with load-sensing electronics. OSHA silica enforcement and EU Green Deal circularity mandates create simultaneous regulatory tailwinds and compliance thresholds.
For Market Incumbents: Shield platform ecosystem value through backward integration into battery management system design and captive brushless motor production capacity in Vietnam or Mexico. Defend against emerging private-label assemblers by deepening authorized repair network density in Texas and Florida construction corridors. Prioritize dust-collection feature certification to maintain specification advantage in commercial construction procurement.
For New Entrants and Emerging Players: Differentiate on solar-powered configurations for off-grid renovation segments in rural India and remote Australian construction sites. Target furniture production startups in Bangalore and Pune seeking cordless mobility without generator infrastructure. Pursue bare-tool economics with BIS-certified battery compatibility to circumvent platform lock-in barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant precision surfacing equipment divisions and established European repair networks. Five-to-ten-year viability hinges on battery remanufacturing service revenue streams and smart sensor integration roadmaps. Monitor brushless motor controller supply concentration as inflection indicator for margin compression or vertical integration imperatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Expansion | Cross-category interoperability locks contractors into single-brand procurement across drilling and cutting tools. |
| Brushless Motor Convergence | Load-sensing electronics enable automatic speed adjustment for hardwood density adaptation in Japanese and German markets. |
| Dust-Collection Certification | OSHA silica compliance separates specification-compliant manufacturers from brushed-motor economy suppliers. |
| Authorized Repair Network Density | EU Green Deal remanufacturing mandates create recurring service revenue streams in Stuttgart-area clusters. |
| Solar-Powered Configuration Launch | Photovoltaic-charged tools address off-grid demand in Western Australia and Maharashtra woodworking clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cordless tool product managers, battery platform engineers, residential renovation contractors, and authorized service network heads. Secondary validation drew from FCC equipment authorization filings, EPA hazardous waste rule dockets, customs trade data for lithium-ion cell imports, and SEC 10-K disclosures from power-tool conglomerates. Bottom-up shipment estimates by product configuration and top-down market sizing by battery platform economics were triangulated to converge on volume and value outputs.
Across the analysis window, forecasts employed a segmented analytical framework spanning motor architecture tier, battery voltage platform, depth precision specification, and regional contractor purchasing power cluster. CAGRs were derived from regression analysis against construction spending indices and lithium-ion cell cost curves. Industry-specific inputs included OSHA silica enforcement timeline assumptions and EU Green Deal remanufacturing mandate implementation schedules.
Decision-makers should treat outputs as directional under assumptions of continued lithium-ion energy density improvement and stable cobalt supply from Democratic Republic of Congo mining operations; material deviation in cell chemistry transitions or geopolitical disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodworking Circular Saw Blades Market
Tools
Structural Wood Screws Market
Tools
Woodworking Power Tools Market
Tools
Rivet Busters Market
Tools
Floor Polishing Machine Market
Tools
End Mill Holder Market
Tools
Ripper Market
Tools
Broaching Tools Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Allen Key Market
Tools
Handheld Pipe Cutter Market
Tools
Rotary Hammer Drill Market
Tools
Pruning Saw Market
Tools
Adoption of Benelux Power Tools Market
Tools
Cold and Hot Tool Steel Market
Tools
Global Construction Camera Market