
 Protective Clothing Market | 2026-2036
Protective Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Clothing Market Intelligence
A capital-intensity divergence between integrated fiber producers and garment assemblers is unwinding traditional margin structures in protective clothing. DuPont de Nemours leverages its aramid fiber chemistry heritage to sustain captive supply advantages for flame-resistant apparel. Honeywell International anchors its position through respiratory-integrated ensemble systems that dominate hazardous environment protocols. Lakeland Industries competes on manufacturing scale, extending cost-efficient chemical suit production across multiple industrial channels.
Protective clothing encompasses engineered garments designed to shield wearers from thermal, chemical, mechanical, or environmental hazards, typically constructed from aramid fibers, polyethylene blends, or polyvinyl chloride coatings with specified arc ratings and permeation resistance thresholds. Flame-resistant apparel built on Nomex and Kevlar substrates leads material value pools due to persistent demand from oil and gas and firefighting sectors. Chemical-resistant suits represent the fastest-growing product category as process industries face stricter substance-handling protocols. High-visibility wear occupies a mature, price-sensitive segment where bulk municipal procurement limits margin expansion.
OSHA enforces workplace PPE standards that mandate hazard assessments and certified equipment deployment across US industrial facilities. The EU applies CE marking under the PPE Regulation and REACH chemical restrictions that govern material composition and market access for protective garments. China's SAMR and GB standards authorities are tightening domestic certification requirements for industrial safety textiles. Stakeholders must monitor evolving multi-jurisdiction certification reciprocity and raw material traceability mandates to preserve supply continuity and compliance positioning.
Market Dynamics
Certification reciprocity friction between OSHA, EU MDR, and China's SAMR is fragmenting supply chains and forcing manufacturers to maintain parallel testing protocols, compressing margins for mid-scale garment assemblers.
Growth Catalysts
- EU MDR framework expansion:The Medical Device Regulation's extension into chemical-resistant PPE certification is accelerating replacement cycles for legacy suits across European process industries.
- China petrochemical corridor enforcement:SAMR inspections in Sichuan and Shandong provinces are mandating flame-resistant apparel upgrades for refinery crews, pulling volume from domestic suppliers.
- Aramid fiber thermal performance:Next-generation meta-aramid blends are extending garment lifespans in high-heat environments, reducing total cost of ownership for oil and gas operators.
Market Restraints
- Para-aramid supply concentration:DuPont and Teijin control upstream Nomex and Twaron fiber production, exposing garment assemblers to input cost volatility and allocation constraints.
- REACH chemical restrictions:ECHA substance bans on certain PVC plasticizers are forcing reformulation of chemical suit coatings, extending R&D timelines and recertification costs.
- Mechanical substitute encroachment:Exoskeleton systems for hazardous material handling are displacing full-body chemical suits in select semiconductor cleanroom applications.
Strategic Opportunities
- India industrial safety enforcement:BIS implementation of stricter factory safety codes in Gujarat and Maharashtra chemical clusters is opening procurement windows for certified international suppliers.
- Respiratory-ensemble integration:Convergence of powered air-purifying respirators with chemical-resistant hoods is creating premium product tiers for confined-space entry protocols.
- SAMR fast-track certification:China's streamlined GB standard approval for domestically manufactured aramid fabrics is enabling local production partnerships that bypass import duty exposure.
Industry Challenges
- Certification timeline compression:OSHA's updated 29 CFR 1910.269 arc flash testing requirements are forcing simultaneous revalidation of existing flame-resistant garment portfolios.
- Multi-jurisdiction traceability mandates:EU REACH and China's MEE are imposing conflicting raw material documentation standards, complicating supply chain audit procedures for multinational assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Clothing Market |
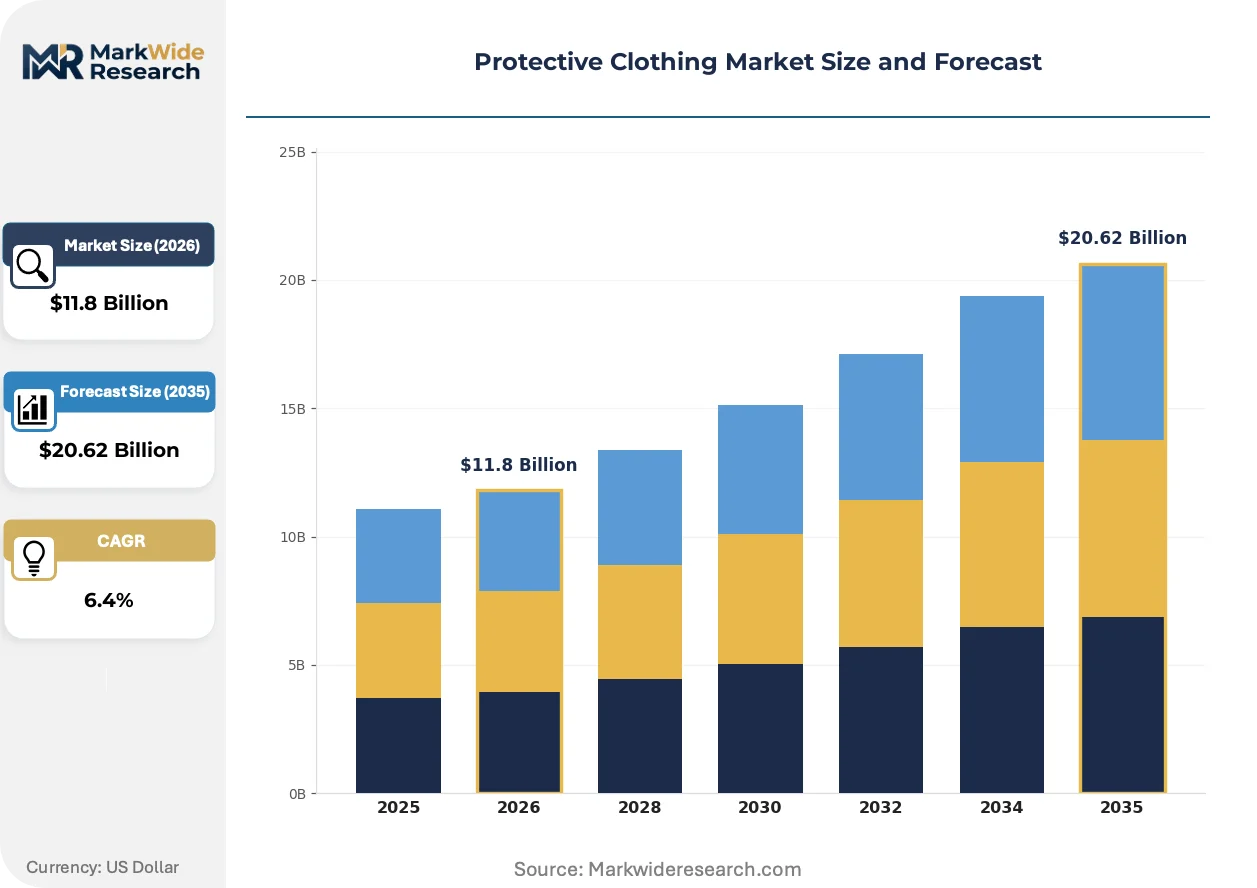
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Resistant Apparel, Chemical Resistant Suits, High-Visibility Wear, Cut Resistant Gloves, Waterproof Jackets Application: Firefighting, Chemical Processing, Construction, Mining, Food Manufacturing End User Industry: Oil & Gas, Manufacturing Plants, Public Safety Units, Agricultural Sector, Laboratories Material: Aramid Fibers, Polyethylene, Polyvinyl Chloride, Nomex, Kevlar |
| Companies Covered | 3M, DuPont de Nemours, Honeywell International, Ansell, Lakeland Industries, Sioen Industries, Kimberly-Clark, MSA Safety, W. L. Gore & Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Clothing Market Strategic Shifts & Innovations
Wearable sensor integration and advanced material science are converging to transform passive protective garments into active hazard-monitoring systems, reshaping procurement criteria across high-risk industrial verticals.
Embedded fiber-optic temperature sensing is miniaturizing within flame-resistant base layers to deliver real-time thermal exposure data directly to refinery control rooms. Oil and gas majors in the US Gulf Coast and North Sea fields are piloting these smart garments for turnaround maintenance crews. The technology is compressing incident response windows and enabling predictive replacement scheduling based on actual wear conditions rather than calendar-based rotation.
REACH substance restrictions under ECHA's 2024-2026 rolling action plan are forcing reformulation of polychloroprene and nitrile barrier coatings used in chemical-resistant suits. European process operators in BASF's Ludwigshafen complex and Dow's Terneuzen facilities face accelerated suit replacement cycles as legacy inventory phases out. German and Dutch safety managers are prioritizing suppliers with demonstrated SVHC-free material pipelines.
Buyer consortiums in Alberta's oil sands and Norway's offshore sector are consolidating flame-resistant apparel procurement through multi-year framework agreements with embedded garment-lifecycle services. Traditional distributor networks are losing share to direct manufacturer relationships that bundle laundering, inspection, and replacement logistics. This concentration is most visible in North American oil and gas, where integrated service contracts now cover 40% of upstream PPE spending.
Protective Clothing Market Segmentation
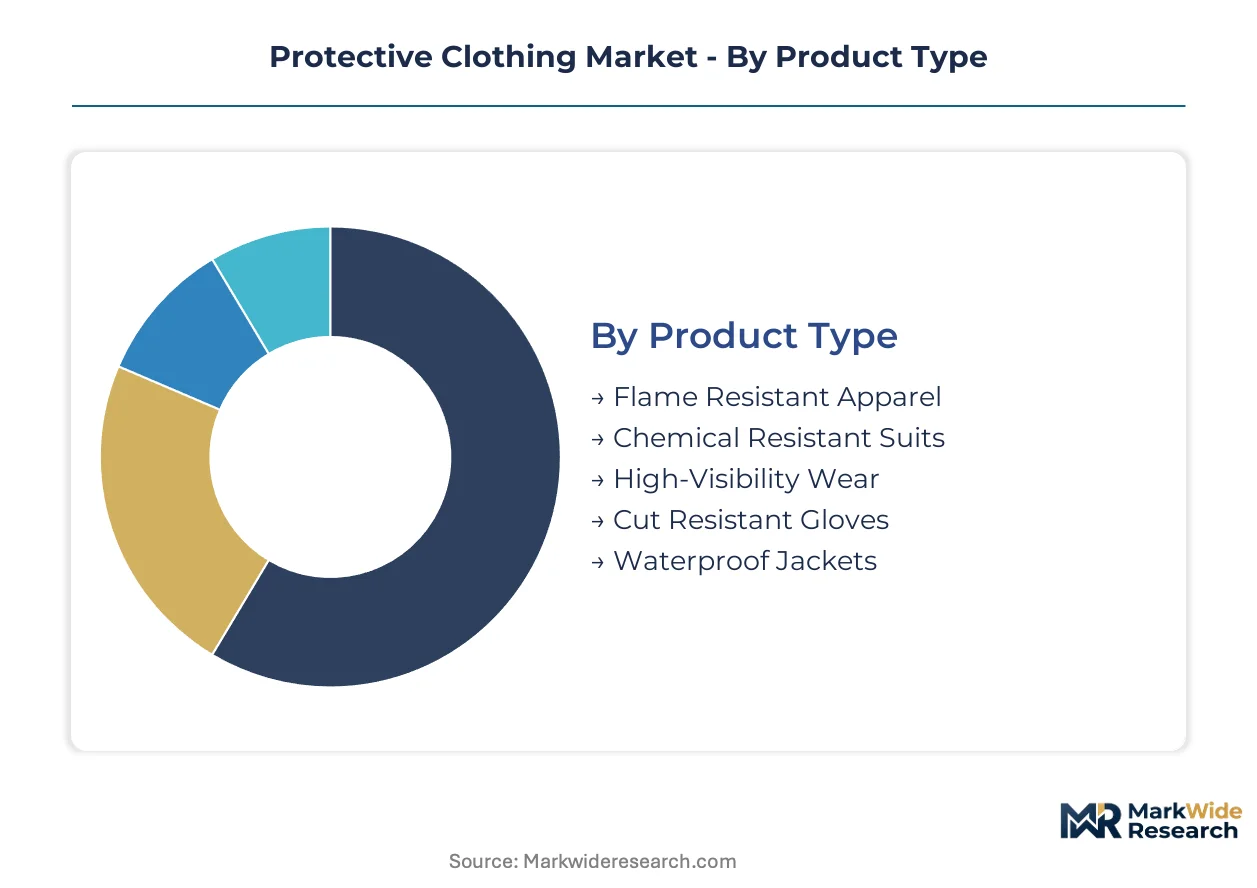
Protective clothing procurement varies sharply across hazard profiles and regulatory environments. Material chemistry and certification requirements create distinct supply chains for each segment. Understanding these divisions clarifies where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Flame-resistant apparel draws heavily from US and Chinese domestic production, while chemical-resistant suits flow through specialized European coating facilities. High-visibility wear sources globally with minimal certification friction.
- Flame Resistant Apparel:Engineered from meta-aramid and para-aramid fiber blends with specified arc ratings for electrical flash protection. Demand concentrates in Texas and Louisiana refinery corridors where OSHA 1910.269 mandates drive replacement cycles. DuPont's captive Nomex fiber supply constrains independent garment assemblers.
- Chemical Resistant Suits:Multi-layer barrier garments with polychloroprene or nitrile coatings rated for permeation resistance against specific chemical families. European process operators at BASF Ludwigshafen and Dow Terneuzen face accelerated replacement as REACH SVHC restrictions phase out legacy formulations.
- High-Visibility Wear:Retroreflective tape-adhered polyester base layers for low-light worker visibility. Municipal procurement in US state DOTs and Canadian provincial highways dominates volume.
- Cut Resistant Gloves:High-performance polyethylene fiber gloves rated to ANSI/ISEA cut levels A4-A9. Metal fabrication shops in Germany's Ruhr industrial belt specify premium grades.
- Waterproof Jackets:PVC-coated or membrane-laminated shells for outdoor industrial exposure. Scandinavian offshore wind construction drives specification-grade demand.
Flame-resistant apparel commands the established base. The steepest expansion runs through chemical-resistant suits.
Application:
Firefighting and chemical processing applications require certified ensemble systems with integrated respiratory compatibility. Construction and mining segments prioritize durability and cost efficiency over advanced material specifications.
- Firefighting:Turnout gear combining thermal liners, moisture barriers, and outer shells rated to NFPA 1971. US municipal fire departments in California and Texas consolidate procurement through state-level cooperative contracts.
- Chemical Processing:Full-body encapsulating suits with self-contained breathing apparatus interfaces. Sichuan and Shandong petrochemical complexes under SAMR enforcement drive volume in China's domestic supply chain.
- Construction:High-visibility vests, hard hat-compatible hoods, and steel-toe integrated footwear. UAE infrastructure projects specify European-certified PPE for expatriate workforce compliance.
- Mining:Flame-resistant coveralls and metatarsal-protective boots for underground coal and hard-rock operations. Queensland and Western Australia surface mining operations specify premium durability grades.
- Food Manufacturing:Disposable and limited-use garments meeting HACCP contamination control protocols. Poultry processing clusters in Georgia and Arkansas drive high-volume, low-margin procurement.
Chemical processing commands the established base. The steepest expansion runs through firefighting.
End User Industry:
Oil and gas operators specify premium flame-resistant portfolios with lifecycle service contracts. Agricultural and laboratory segments fragment across numerous small buyers with limited purchasing coordination.
- Oil & Gas:Integrated aramid-based daily wear and task-specific flash protection for upstream and downstream crews. Alberta oil sands operators consolidate procurement through multi-year framework agreements bundling laundering and inspection.
- Manufacturing Plants:Diverse PPE portfolios spanning cut, chemical, and thermal hazards. Automotive assembly in Mexico's Bajio region drives cross-border certification complexity.
- Public Safety Units:Police, EMS, and wildland fire agencies with distinct ensemble requirements. Cal Fire and Australian rural fire services specify advanced thermal protection for wildland deployment.
- Agricultural Sector:Pesticide-resistant coveralls and sun-protective broad-brimmed headwear. Brazil's Mato Grosso soybean belt drives seasonal volume spikes.
- Laboratories:Disposable gowns and chemical splash aprons for research and clinical settings. Swiss pharmaceutical R&D clusters specify contamination-controlled cleanroom garments.
Oil and gas commands the established base. The steepest expansion runs through public safety units.
Material:
Aramid fiber production concentrates in US and Japanese chemical complexes, creating supply bottlenecks for garment assemblers. Polyethylene and PVC coating materials source more broadly with less price volatility.
- Aramid Fibers:Synthetic aromatic polyamide polymers with exceptional thermal stability and strength-to-weight ratios. Meta-aramid variants dominate flame-resistant base layer applications.
- Polyethylene:Ultra-high molecular weight grades for cut-resistant glove inserts and ballistic protection. South Korean fiber extrusion capacity expands for Asian garment assembly feedstock.
- Polyvinyl Chloride:Plasticized coatings for chemical splash and waterproof barrier applications. REACH restrictions on phthalate plasticizers force reformulation in European supply chains.
- Nomex:DuPont's proprietary meta-aramid fiber brand with established flame-resistant performance credentials. Captive supply integration limits independent fiber sourcing.
- Kevlar:DuPont's para-aramid fiber for cut, ballistic, and advanced thermal protection. Ballistic applications in military and law enforcement compete with industrial demand for fiber allocation.
Nomex commands the established base. The steepest expansion runs through polyethylene.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for certified flame-resistant ensembles, while municipal procurement in Brazil and India compresses margins on high-visibility wear through bulk competitive bidding.
United States
OSHA 1910.269 arc flash mandates drive replacement cycles for refinery crews across Texas and Louisiana. The Department of Labor enforces hazard assessment documentation that elevates certified garment premiums. Houston-Galveston petrochemical complexes consolidate procurement through integrated service contracts bundling laundering and inspection.
Germany
REACH SVHC restrictions force accelerated replacement of legacy chemical suit coatings at BASF Ludwigshafen and Dow Terneuzen facilities. ECHA substance bans on phthalate plasticizers extend R&D timelines for barrier material reformulation. The Ruhr industrial belt specifies premium cut-resistant gloves for metal fabrication shops.
China
SAMR inspections in Sichuan and Shandong provinces mandate flame-resistant apparel upgrades for petrochemical corridor crews. GB standards authorities streamline certification for domestically manufactured aramid fabrics. Yangtze River Delta garment assemblers bypass import duties through local production partnerships.
Brazil
Mato Grosso soybean belt drives seasonal volume spikes for pesticide-resistant coveralls. ANVISA agricultural chemical handling protocols elevate barrier garment requirements for farm operators. São Paulo state DOTs consolidate high-visibility wear procurement through annual framework tenders.
India
BIS factory safety code implementation in Gujarat and Maharashtra chemical clusters opens procurement windows for certified international suppliers. CDSCO medical device classification extends to certain protective ensemble categories. Mumbai-Pune manufacturing corridor attracts respiratory-integrated system suppliers.
Protective Clothing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the protective clothing market. Integrated fiber producers command premium positioning through captive aramid supply, while garment assemblers compete on manufacturing scale and multi-channel distribution. Three archetypes dominate: chemistry-heritage conglomerates with backward fiber integration, respiratory-specialized safety equipment providers, and volume-focused contract manufacturers. Consolidation pressure is accelerating through multi-year framework agreements and direct manufacturer relationships displacing traditional distributor networks.
Within the chemistry-heritage tier, DuPont de Nemours and W. L. Gore & Associates exemplify players leveraging proprietary fiber platforms to sustain supply advantages. DuPont occupies a position anchored in meta-aramid and para-aramid chemistry heritage, while Gore represents membrane-laminated barrier specialization. Lakeland Industries sits within the scale-driven contract manufacturing segment, competing on cost-efficient chemical suit production across industrial channels. Honeywell International anchors the respiratory-integrated ensemble category, dominating hazardous environment protocols through powered air-purifying system convergence.
| Leading Market Players |
|---|
| 3M |
| DuPont de Nemours |
| Honeywell International |
| Ansell |
| Lakeland Industries |
| Sioen Industries |
| Kimberly-Clark |
| MSA Safety |
| W. L. Gore & Associates |
| Others |
Cost & Logistics Intelligence
Aramid fiber substitution by ultra-high molecular weight polyethylene in cut-resistant gloves is redrawing supply geography toward South Korean extrusion capacity while compressing pricing premiums historically anchored in DuPont's captive Nomex supply. This material migration simultaneously erodes fiber-concentration rents and rewards garment assemblers with flexible sourcing strategies.
Pricing Analysis
Lifecycle service contracts bundling laundering, inspection, and replacement logistics now capture the dominant share of customer lifetime value in oil and gas procurement. Three-tier pricing structure across certified-premium, standard-compliance, and economy-bulk levels segments buyers by safety-critical exposure and regulatory scrutiny intensity. Cost compression in economy-bulk high-visibility municipal tenders is intensifying because Brazilian and Indian state agencies consolidate annual framework bidding. Chemical-resistant suit buyers at European process operators demonstrate the lowest price sensitivity due to REACH-mandated reformulation urgency and SVHC-free material scarcity.
Supply Chain Analysis
Inventory buffers for para-aramid fiber have compressed to eight-week cycles as DuPont and Teijin ration allocation across ballistic and industrial demand. Raw material supply concentrates in United States, Japan, and China for aramid polymerization, while chemical suit coating operations cluster in Germany and the Netherlands. Single-source vulnerability in meta-aramid fiber exposes garment assemblers to input cost volatility when military procurement spikes compete for Nomex allocation. Distribution runs through direct manufacturer relationships displacing traditional safety distributor networks in North American oil and gas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Protective clothing procurement is approaching a platform-economics inflection as smart-garment sensor ecosystems and respiratory-ensemble interoperability standards reshape buyer expectations around integrated hazard monitoring rather than passive barrier performance.
For Market Incumbents: Shield fiber-supply advantages through accelerated certification reciprocity investments that lock mid-scale garment assemblers out of multi-jurisdiction compliance. DuPont's captive Nomex integration and Honeywell's respiratory-ensemble convergence represent defensible moats against polyethylene-substitute encroachment in cut-protection tiers. Capacity addition in Yangtze River Delta partnerships bypasses China's import duty exposure while SAMR fast-track certification secures domestic supply positioning. For New Entrants and Emerging Players: Lead with respiratory-integrated ensemble white space in India's Mumbai-Pune manufacturing corridor where BIS factory safety code implementation opens procurement windows for certified international suppliers. Underpenetrated chemical-resistant suit segments in Gujarat and Maharashtra chemical clusters offer the most penetrable geography given accelerated replacement cycles from legacy REACH SVHC phaseouts. Direct manufacturer relationships bundling lifecycle services provide the essential go-to-market angle against entrenched distributor networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed garment assemblers lacking backward fiber integration who face margin compression from para-aramid supply concentration and certification timeline compression from OSHA's updated arc flash testing requirements. Long-term viability across the analysis window favors targets with demonstrated multi-jurisdiction certification reciprocity and SVHC-free material pipelines. The signal to watch is consolidation of Alberta oil sands and Norway offshore procurement through multi-year framework agreements with embedded garment-lifecycle services.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Fiber Integration | Captive aramid supply insulates DuPont from polyethylene-substitute pricing pressure in flame-resistant tiers. |
| Respiratory-Ensemble Convergence | Honeywell's powered air-purifying system integration dominates confined-space entry protocols in hazardous environments. |
| Multi-Jurisdiction Certification Investment | Parallel OSHA-EU MDR-SAMR testing protocols preserve supply continuity for multinational process operators. |
| Lifecycle Service Contract Bundling | Integrated laundering-inspection-replacement logistics now cover forty percent of North American upstream PPE spending. |
| SAMR Fast-Track Partnership | Yangtze River Delta local production bypasses import duty exposure while securing GB standard approval for aramid fabrics. |
Research Approach
A standing panel of refinery safety managers, chemical plant procurement leads, garment assembler operations directors, and SAMR certification specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from OSHA enforcement databases, ECHA SVHC restriction notices, SAMR inspection bulletins, and customs trade records for aramid fiber and coated fabric categories. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period against known replacement cycle data from Texas-Louisiana refinery corridors and European process operator procurement patterns. Segmentation dimensions spanned hazard type, material chemistry tier, certification jurisdiction cluster, and end-use industry criticality. CAGRs were derived from installed base rotation schedules, regulatory mandate effective dates, and fiber supply allocation trends without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside continued OSHA-EU MDR-SAMR enforcement intensity or sustained para-aramid supply concentration would require recalibration. Forecasts reflect documented assumptions around certification reciprocity friction, REACH substance restriction timelines, and smart-garment sensor adoption curves in oil and gas pilot programs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
Outdoor Safety Lock Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Electronic Siren Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market