
 Hand Geometry Biometrics Market | 2026-2036
Hand Geometry Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Geometry Biometrics Market Foresight
Multi-source component sourcing is hardening among established hand geometry vendors as supply chain resilience becomes a procurement priority. ZKTeco Co., Ltd. leverages its manufacturing scale across Asian production hubs to maintain cost competitiveness in standalone device categories. Suprema Inc. anchors its position through integrated systems that combine hand geometry with multi-modal biometric platforms for enterprise clients. IDEMIA Group differentiates via government-facing certifications and specialized channel control for high-security installations.
Hand geometry biometrics measures the three-dimensional structure of human hands—including finger length, width, thickness, and knuckle geometry—to create unique identification templates stored as encrypted mathematical representations. These systems operate through near-infrared imaging arrays and pressure-sensitive platen surfaces, serving primarily as frictionless authentication tools for high-throughput physical access environments. Touchless systems are gaining structural momentum as hygiene-conscious installations displace legacy contact-based platen devices in healthcare and food processing facilities. Integrated systems command the deepest margin pools by bundling software management platforms with hardware, while standalone devices remain the volume base in small commercial deployments.
FDA oversight of biometric data in clinical settings, NIST testing protocols for false acceptance rates, and GDPR consent frameworks for biometric data processing collectively elevate compliance costs while filtering out uncertified market entrants. The EU AI Act's risk classification for biometric identification systems will further constrain deployment options in European public spaces. Stakeholders must monitor evolving interoperability standards between hand geometry and emerging contactless modalities to preserve installed base value.
Market Dynamics
Touchless hand geometry systems are absorbing capital flows as hygiene mandates displace legacy contact-based installations across healthcare and food processing facilities, compressing replacement cycles and reshaping vendor R&D priorities.
Growth Catalysts
- Federal Facility Modernization:United States government building upgrades mandate biometric access controls under HSPD-12 directives, accelerating procurement of certified hand geometry readers for secure perimeter management.
- GDPR Consent Frameworks:European data protection rules legitimize biometric deployments through explicit consent protocols, reducing legal friction for enterprise physical access installations in Germany and France.
- Near-Infrared Imaging Arrays:Advanced sensor technology enables sub-second authentication throughput, satisfying high-volume requirements at airport security checkpoints in Dubai and Singapore.
Market Restraints
- EU AI Act Risk Classification:Biometric identification systems face restricted deployment options in European public spaces, forcing vendors to reconfigure product architectures for compliance.
- Silicon Supply Concentration:Specialized image sensor fabrication concentrates in East Asian foundries, exposing hardware vendors to geopolitical supply interruptions and extended lead times.
- Contactless Modalities:Facial recognition and iris scanning platforms capture enterprise budgets previously allocated to hand geometry, particularly in premium security installations.
Strategic Opportunities
- Healthcare Underpenetration:Hospital pharmacy vaults and surgical suite access points in India remain largely unprotected by biometric controls, presenting greenfield installation potential.
- Multi-Modal Convergence:Integration of hand geometry with fingerprint and card credentials creates bundled authentication platforms commanding premium pricing in financial services.
- US Infrastructure Investment:IIJA-funded transportation hub renovations specify biometric passenger verification, opening procurement channels for touchless hand geometry at regional airports.
Industry Challenges
- Interoperability Engineering:Legacy Wiegand and OSDP protocol systems require complex middleware development to interface with modern IP-based hand geometry readers, extending deployment timelines.
- NIST Certification Timelines:False acceptance rate testing under Fingerprint Vendor Technology Evaluation protocols consumes 14-18 months, delaying product commercialization and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Geometry Biometrics Market |
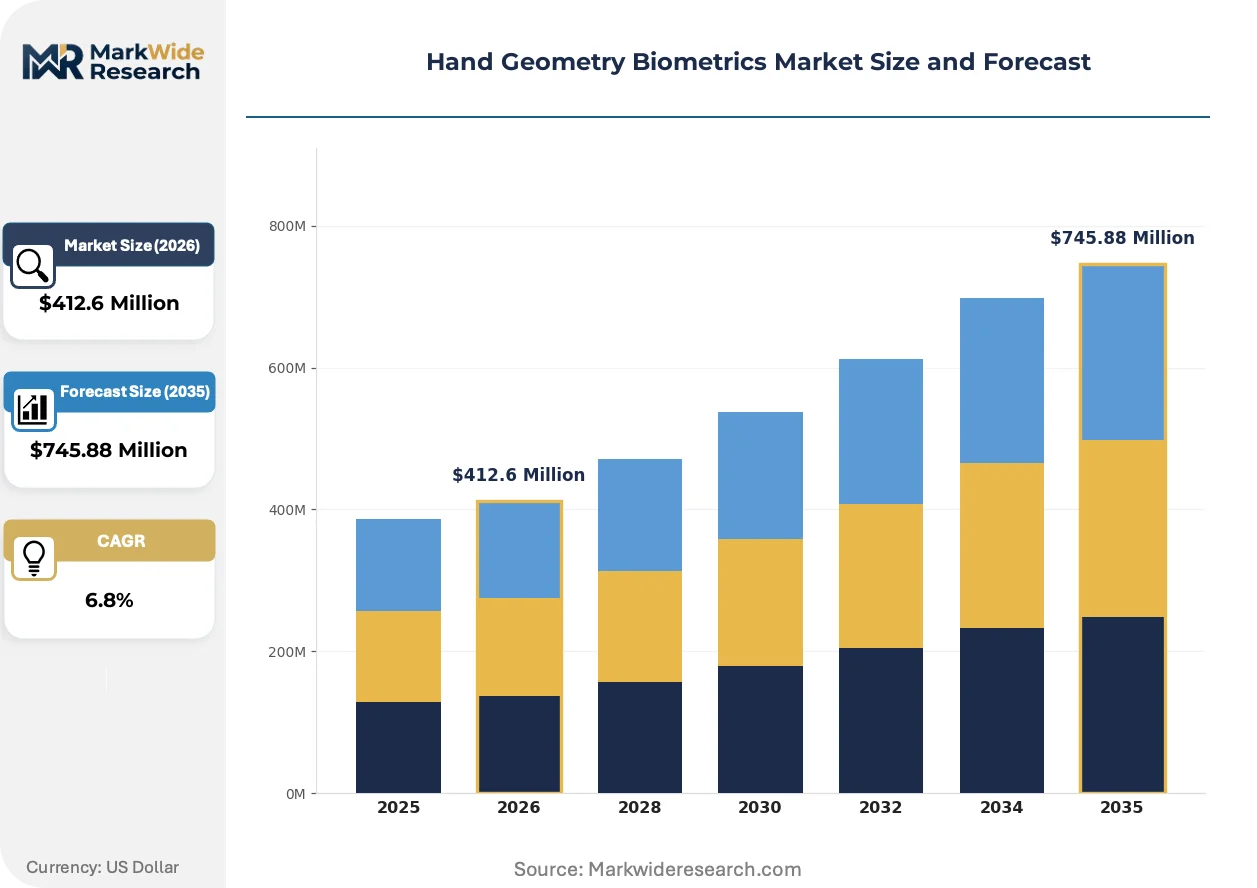
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Access Control, Time & Attendance, Identification, Security Systems Product Type: Standalone Devices, Integrated Systems, Biometric Scanners, Touchless Systems End User: Commercial, Government, Educational Institutions, Healthcare Installation Type: On-premises, Cloud-based, Hybrid Systems, Remote |
| Companies Covered | Ingersoll Rand (Schlage), IdentyTech Solutions Ltd., ZKTeco Co., Ltd., BioSec Group Ltd., Mantra Softech, Suprema Inc., Recognition Systems, Inc., IDEMIA Group, HID Global Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Geometry Biometrics Market Shifts & Advancements
Authentication architectures are pivoting toward hygiene-centric designs as pandemic-conditioned buyers reject shared surface contact. Vendors race to deploy camera-based hand geometry that eliminates physical platen interaction.
Time-of-flight depth sensors are absorbing development resources as the dominant capture mechanism for touchless hand geometry. Healthcare networks in Texas and California deploy these systems for operating room access control. The technology is absorbing market share from capacitive and pressure-based legacy platforms by eliminating cleaning protocols and reducing device maintenance intervals.
GDPR Article 9 processing restrictions and the EU AI Act's biometric surveillance prohibitions are tightening deployment permissions across European member states. Vendors must implement explicit consent workflows and data minimization architectures to maintain market access. German industrial facilities and Dutch logistics hubs now require legal review of biometric processing impact assessments before procurement authorization.
Buyers are unbundling hardware acquisition from software licensing and maintenance contracts, treating authentication platforms as separable procurement categories. System integrators and value-added resellers capture margin previously retained by original equipment manufacturers. This pattern concentrates in United States commercial real estate and university campus deployments where facilities managers demand modular, multi-vendor ecosystem compatibility.
Hand Geometry Biometrics Market Segmentation
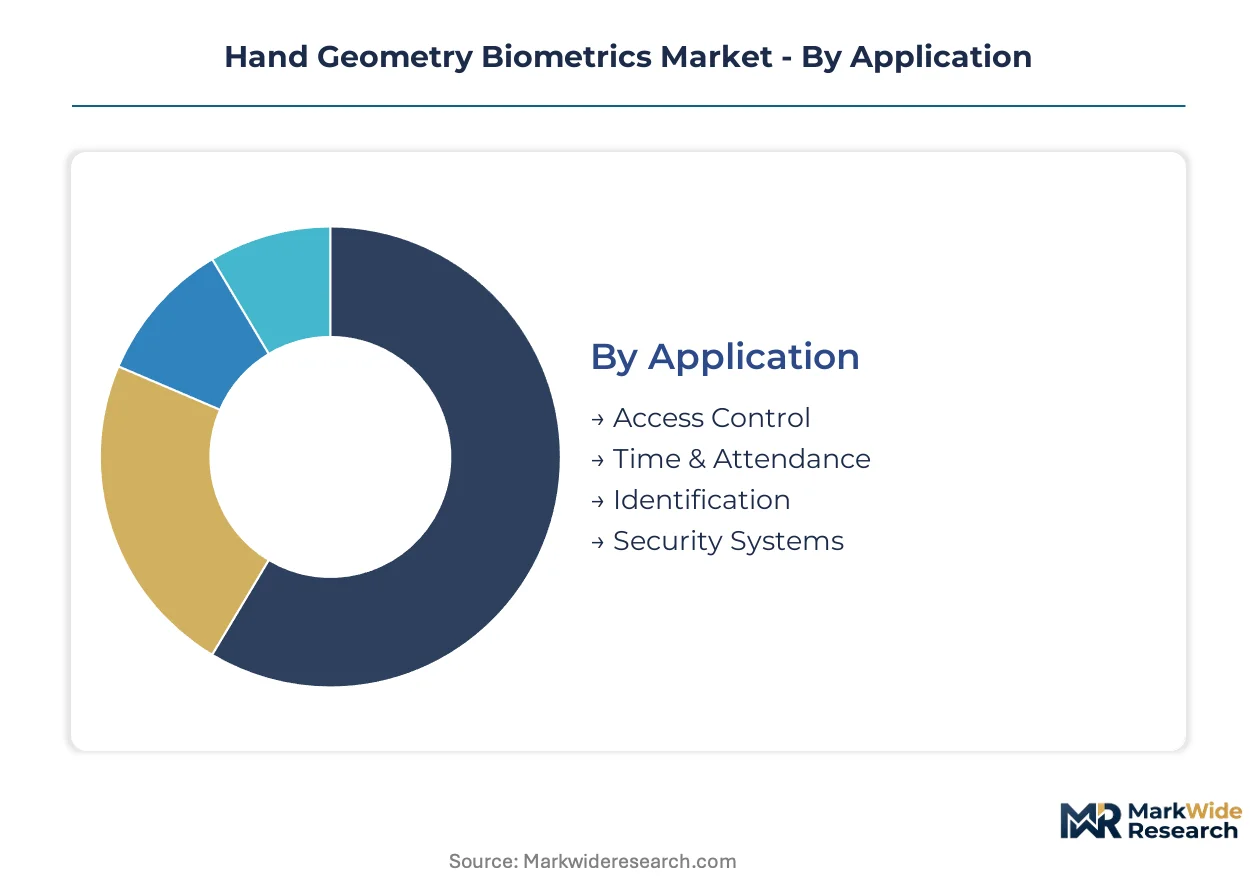
Segmentation in hand geometry biometrics reveals distinct procurement patterns across security environments. Buyers prioritize authentication throughput, integration complexity, and compliance architecture differently based on facility type and threat profile.
Application:
Procurement decisions hinge on transaction volume requirements and regulatory exposure.
- Access Control:Near-infrared imaging arrays authenticate personnel at perimeter gates and secure zone entry points. Demand concentrates in United States federal facilities upgrading under HSPD-12 mandates, where sub-second throughput and FIPS 201 compliance are non-negotiable.
- Time & Attendance:Pressure-sensitive platen devices track workforce entry and exit with tamper-resistant audit trails. Manufacturing plants in Germany and automotive assembly lines in Michigan deploy these systems to eliminate buddy-punching fraud and satisfy payroll verification requirements.
- Identification:One-to-many matching against enrolled templates supports forensic and civil identity applications. National ID programs and correctional facilities represent primary deployment venues.
- Security Systems:Multi-layered authentication combining hand geometry with card credentials protects high-value assets. Data centers and pharmaceutical vaults drive specification of redundant verification protocols.
Access Control leads on scale; Touchless Systems within Security Systems leads on momentum.
Product Type:
Capital allocation splits between replacement cycles and greenfield platform investments.
- Standalone Devices:Self-contained units with embedded processing and local template storage serve small commercial deployments. Independent retailers and professional service firms in France and Spain favor these for cost containment and minimal IT dependency.
- Integrated Systems:Software management platforms bundled with hardware command premium pricing through centralized administration and API connectivity. Enterprise campuses and multi-site healthcare networks in California standardize on these for unified credential lifecycle management.
- Biometric Scanners:Modular capture components designed for OEM integration into third-party kiosks and turnstiles. Airport terminal renovation projects in Dubai and Singapore specify these for custom passenger processing workflows.
- Touchless Systems:Camera-based depth sensing eliminates physical contact through time-of-flight or structured light capture. Hospital networks in Texas and food processing facilities in the Netherlands accelerate replacement of legacy platen devices to satisfy hygiene protocols.
Integrated Systems lead on scale; Touchless Systems leads on momentum.
End User:
Compliance burden and integration sophistication vary sharply across buyer categories.
- Commercial:Corporate headquarters, retail chains, and logistics hubs prioritize frictionless throughput and modular expansion. Financial services firms in London and Frankfurt specify multi-modal platforms combining hand geometry with card credentials.
- Government:Federal, state, and municipal facilities mandate certified devices under national biometric standards. United States GSA schedules and European defense procurement frameworks filter vendor eligibility through formal accreditation processes.
- Educational Institutions:University campuses and K-12 districts balance security enhancement against privacy litigation exposure. Residence hall access and dining hall payment systems represent entry-point deployments.
- Healthcare:HIPAA-covered entities and clinical environments impose stringent data protection and infection control requirements. Surgical suite access and pharmacy vault protection in India present underpenetrated installation opportunities.
Commercial leads on scale; Healthcare leads on momentum.
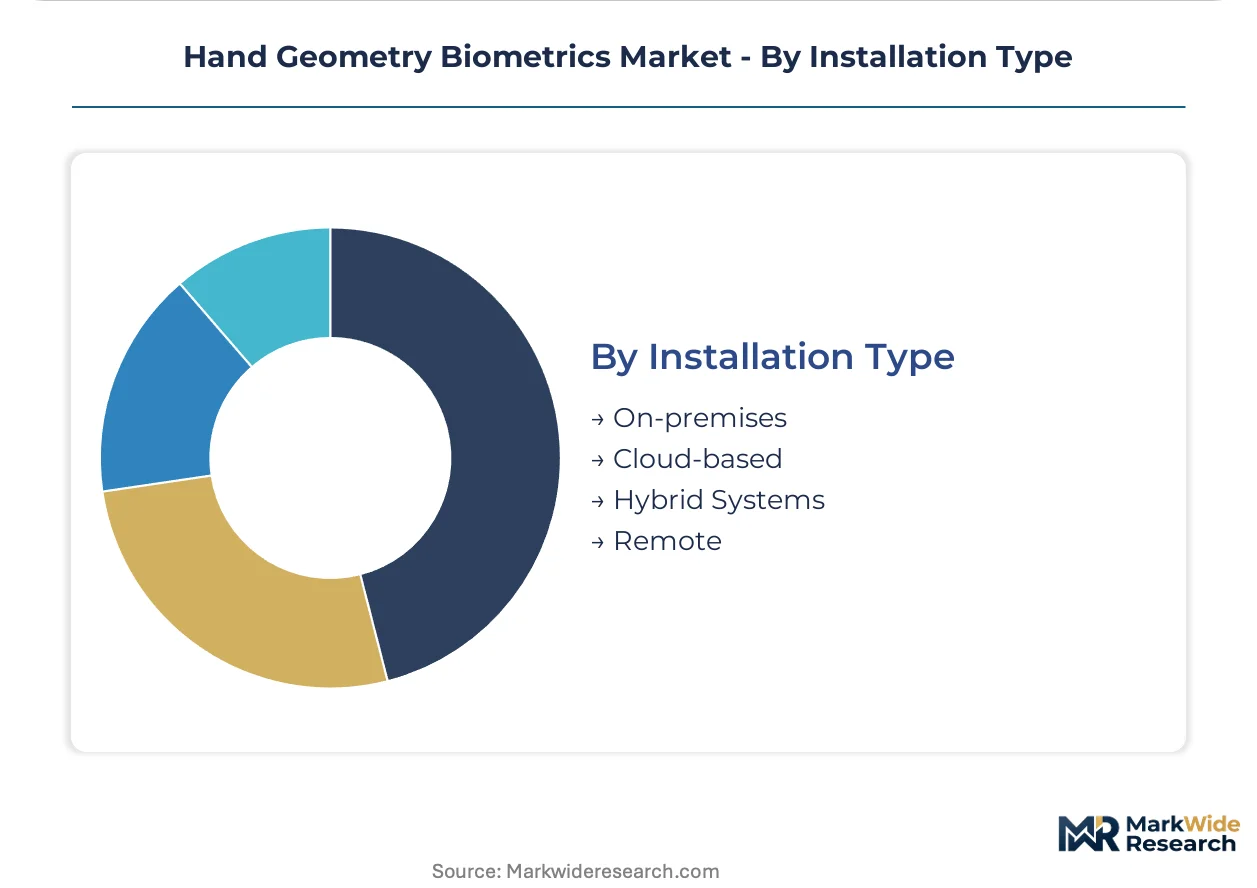
Installation Type:
IT infrastructure maturity determines architecture selection across facility portfolios.
- On-premises:Local server deployment with dedicated network segmentation satisfies air-gapped security requirements. Defense contractors and critical infrastructure operators in the United States reject external connectivity for biometric template repositories.
- Cloud-based:Centralized authentication-as-a-service reduces capital expenditure and enables rapid multi-site rollout. Commercial real estate portfolios and franchise networks favor subscription models with automatic feature updates.
- Hybrid Systems:Edge processing for authentication events with cloud synchronization for administration and reporting. Enterprises with mixed legacy and modern infrastructure adopt these for transitional flexibility.
- Remote:Satellite or cellular-connected units serving distributed field operations and temporary installations. Construction sites and remote utility substations deploy these where fixed infrastructure is unavailable.
On-premises leads on scale; Cloud-based leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal facilities anchor procurement volume for hand geometry biometrics, with HSPD-12 compliance mandates accelerating replacement cycles at secure perimeters. Airport security checkpoints in Dubai and Singapore deploy near-infrared imaging arrays for sub-second passenger verification throughput. European data protection frameworks reshape product architectures as vendors adapt to explicit consent requirements.
United States
GSA schedules and federal facility modernization programs drive certified reader procurement for secure perimeter management. HSPD-12 directives mandate biometric access controls at government buildings, filtering vendor eligibility through FIPS 201 accreditation. Dallas-Fort Worth airport terminals and California healthcare networks deploy touchless systems for high-throughput authentication.
Germany
Industrial facilities and automotive assembly lines in Baden-Württemberg adopt pressure-sensitive platen devices for workforce time-and-attendance tracking. GDPR Article 9 processing restrictions require explicit consent workflows and data minimization architectures before procurement authorization. Frankfurt financial services firms specify multi-modal platforms combining hand geometry with card credentials for premium security installations.
India
Hospital pharmacy vaults and surgical suite access points present underpenetrated installation opportunities for biometric controls. The country's national biometric standards and data protection frameworks elevate compliance costs for hardware vendors. Maharashtra healthcare networks and Karnataka commercial campuses drive early touchless system trials as hygiene protocols tighten.
United Arab Emirates
Dubai International Airport and Abu Dhabi transportation hubs specify biometric passenger verification systems for terminal renovation projects. The country's data protection authority mandates explicit consent for biometric processing in public infrastructure deployments. UAE government facilities and logistics hubs in Jebel Ali Free Zone prioritize frictionless authentication for high-volume workforce management.
Netherlands
Food processing facilities and logistics hubs accelerate replacement of legacy platen devices to satisfy hygiene protocols and infection control requirements. Dutch data protection regulators require legal review of biometric processing impact assessments before enterprise procurement. Rotterdam port facilities and Eindhoven industrial parks deploy camera-based depth sensing for touchless access control.
Hand Geometry Biometrics Market Competitive Landscape
Global majors compete with regional champions across certification depth and channel specialization, producing a tiered structure where government-facing accreditation separates premium vendors from volume players. The vendor base clusters around three strategic archetypes: integrated platform providers bundling software with hardware, standalone device manufacturers competing on cost, and multi-modal specialists converging biometric modalities. Dominant competitive moves include capacity expansion across Asian production hubs and strategic partnerships with system integrators to capture unbundled procurement flows.
Within the integrated platform tier, Suprema Inc. and IDEMIA Group exemplify archetypes anchoring enterprise and government segments respectively. ZKTeco Co., Ltd. occupies a position among scale-driven manufacturers leveraging production breadth for cost competitiveness in standalone categories. Recognition Systems, Inc. sits within the legacy specialist tier, while HID Global Corporation represents the security conglomerate archetype extending biometric portfolios through channel integration.
| Leading Market Players |
|---|
| Ingersoll Rand (Schlage) |
| IdentyTech Solutions Ltd. |
| ZKTeco Co., Ltd. |
| BioSec Group Ltd. |
| Mantra Softech |
| Suprema Inc. |
| Recognition Systems, Inc. |
| IDEMIA Group |
| HID Global Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across South Korea and Taiwan anchor component fabrication for hand geometry sensors, translating concentrated ownership into disciplined capacity planning and stable contract pricing for downstream hardware vendors. Their conservative balance sheet management limits speculative inventory builds, tightening supply availability during demand surges while preserving margin structures across tiered customer segments.
Pricing Analysis
Near-infrared sensor module costs pass through directly to finished reader pricing, with East Asian foundry rate adjustments compressing margins on economy-tier standalone devices within six-month lags. Three-tier pricing structure across premium, standard, and economy levels separates FIPS 201-certified government units from commercial integrated platforms and basic platen-based time clocks. Pricing pressure stems from contactless modality substitution as facial recognition vendors undercut hand geometry in enterprise security RFPs. Small commercial buyers in France and Spain exhibit highest price sensitivity, while United States federal procurement officers prioritize certification compliance over unit cost.
Supply Chain Analysis
Freight cost volatility from East Asian hub ports to North American distribution centers absorbs working capital at hardware vendors managing trans-Pacific component flows. Specialized image sensor fabrication concentrates in Taiwan, South Korea, and Japan, while pressure-sensitive platen manufacturing draws from Chinese metalworking clusters and German precision-engineering facilities. Raw material dependencies span silicon wafers, near-infrared LED arrays, and tempered glass surfaces. Single-source vulnerability concentrates in time-of-flight depth sensor modules where qualified secondary suppliers remain scarce. Distribution runs through security systems integrators and value-added resellers capturing margin from unbundled procurement patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand geometry biometrics functions as a stable compounder anchored by federal compliance mandates that institutionalize replacement cycles regardless of macroeconomic oscillation. Infrastructure-driven demand from transportation hub modernization and healthcare facility upgrades sustains predictable revenue visibility.
For Market Incumbents: To counter contactless modality displacement in premium enterprise accounts, double down on multi-modal platform bundling that embeds hand geometry within broader credential ecosystems. Accelerate NIST certification pipelines to maintain government eligibility while adding touchless variants that satisfy healthcare hygiene mandates. Channel control through exclusive integrator partnerships protects margin pools from unbundling pressures.
For New Entrants and Emerging Players: System integrators represent the critical entry pathway for specialized vendors lacking brand recognition in government procurement channels. Target underpenetrated hospital pharmacy vaults in Maharashtra and Karnataka where incumbent presence remains thin and local compliance consulting creates differentiation. Pursue OEM supply relationships with kiosk manufacturers serving airport terminal renovation projects in Dubai and Singapore.
For Investors and Strategic Acquirers: Physical security conglomerates are the most active acquirer in this space, seeking biometric capabilities to round out access control portfolios. Five-to-ten-year viability rests on touchless technology transition execution and multi-modal integration depth rather than standalone hardware scale. Monitor NIST evaluation queue lengths as an inflection indicator—extended certification timelines signal vendor distress and acquisition opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Touchless Product Line Launch | Camera-based depth sensing captures healthcare procurement budgets shifting from legacy platen devices. |
| NIST Certification Investment | FIPS 201 compliance maintains eligibility for United States federal facility modernization programs. |
| Multi-Modal Platform Integration | Hand geometry bundled with card credentials commands premium pricing in Frankfurt financial services. |
| System Integrator Partnership | Channel alliances capture margin from unbundled procurement patterns in commercial real estate. |
| Healthcare Vertical Expansion | Surgical suite access installations in Texas and California absorb touchless system production capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with physical security directors, biometric system integrators, federal procurement officers, and healthcare facilities managers with secondary validation against NIST test reports, GSA schedule pricing databases, SEC filings of listed security conglomerates, and European data protection authority guidance documents. Bottom-up unit shipment estimates by product category triangulated against top-down market value reconstructions.
Historical reference periods anchored volume and value trajectories across the modeling period, with CAGRs derived from segment-level growth rate distributions weighted by end-user procurement intensity. Segmentation dimensions modeled include product architecture, installation type, application environment, and regional regulatory cluster. Forecast inputs incorporated HSPD-12 mandate implementation schedules, EU AI Act risk classification timelines, and touchless technology adoption curves in healthcare networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to contactless modality substitution rates and silicon supply concentration disruptions. Forecasts reflect documented assumptions about federal procurement continuity and certification protocol stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Biometric Point-Of-Sale Terminals Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
Biometric ATM Market
Biometrics & Identity Management
Biometric Bike Locks Market
Biometrics & Identity Management
United States Biometrics Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
Next Generation Biometric Market
Biometrics & Identity Management
Airport Biometrics Market
Biometrics & Identity Management
Biometric Authentication Solution Market
Biometrics & Identity Management
Physical Identity and Access Management (PIAM) Market
Biometrics & Identity Management
Mobile Biometrics Market
Biometrics & Identity Management
Global Mobile User Authentication Market
Biometrics & Identity Management
Europe Enterprise Biometrics Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
United States Facial Recognition Market
Biometrics & Identity Management
Global Biometrics Middleware Market