
 Biometric Point-Of-Sale Terminals Market | 2026-2036
Biometric Point-Of-Sale Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Biometric Point-Of-Sale Terminals Market Outlook
PCI DSS 4.0 compliance tier is unwinding legacy terminal deployments across merchant acquirers. IDEMIA leverages its government biometric credentials division to anchor enterprise POS contracts in regulated sectors. Fujitsu Ltd. sustains Japanese manufacturing scale for capacitive sensor modules that dominate Asia-Pacific supply chains. PAX Technology competes on integrated Android terminals with built-in fingerprint readers for developing-market banks.
Biometric point-of-sale terminals combine payment card acceptance hardware with live biometric capture sensors to authenticate cardholders through unique biological identifiers rather than PINs or signatures. Optical and capacitive fingerprint modules currently occupy the majority of installed units due to lower per-unit cost and mature supply chains, while ultrasonic sensor technology is gaining ground in premium deployments where spoof resistance justifies higher hardware expenditure. Retail and banking end users represent the primary demand pool, with hospitality trailing due to transaction speed requirements and customer throughput priorities. Cloud-based integration levels are capturing disproportionate growth as merchant acquirers shift terminal management from on-premise estates to centrally monitored platforms.
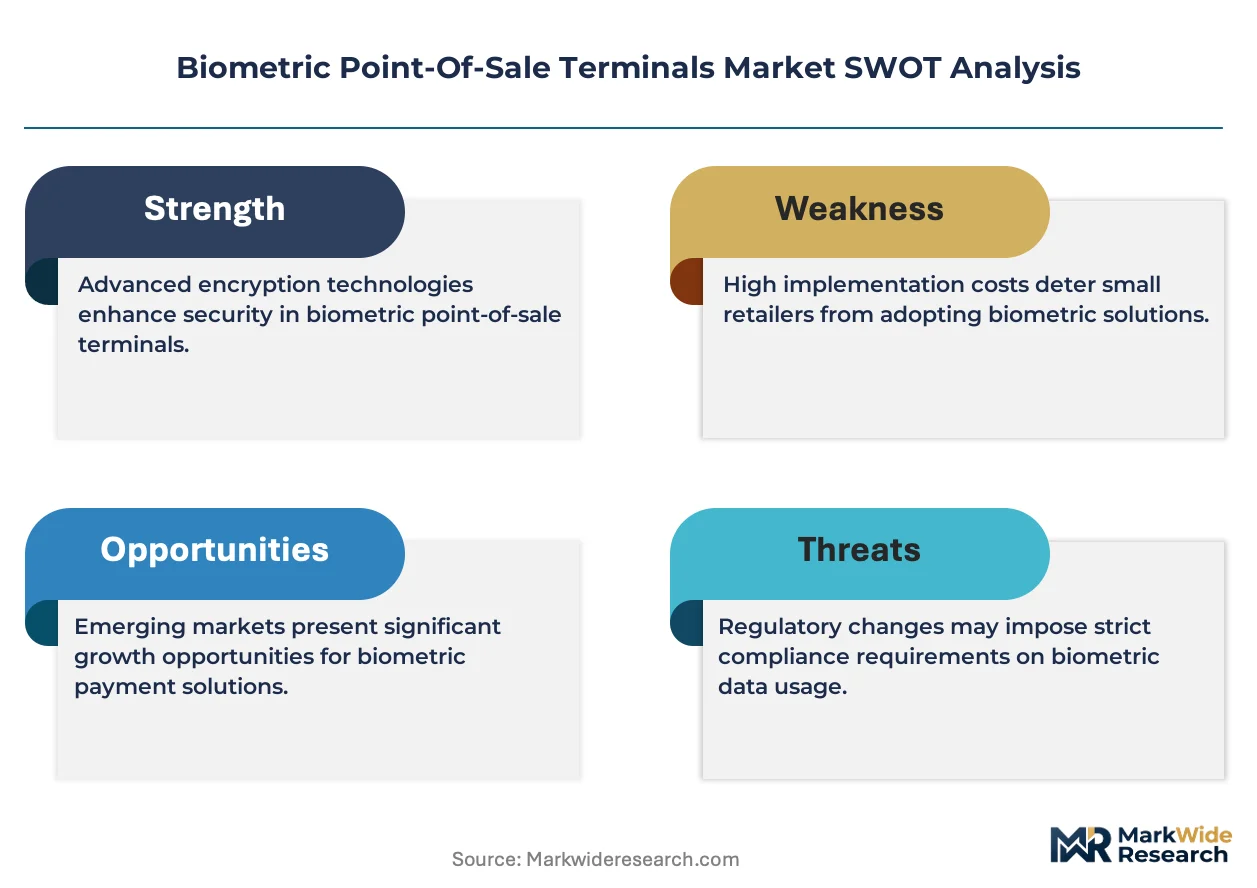
FDA guidance on biometric data security in healthcare payment contexts, EBA PSD2 Strong Customer Authentication technical standards, and RBI tokenization mandates collectively shape product certification requirements and market access conditions for terminal vendors. ISO 30107-3 presentation attack detection standards increasingly determine which sensor technologies qualify for regulated procurement channels. Stakeholders must monitor evolving national biometric data protection laws that could restrict cross-border template storage or mandate local server residency for authentication records.
Market Dynamics
PCI DSS 4.0 compliance deadlines are forcing merchant acquirers to retire legacy magnetic-stripe terminals and replace them with biometric-enabled hardware that satisfies multi-factor authentication requirements for card-present transactions.
Growth Catalysts
- EBA Strong Customer Authentication:European payment processors must deploy biometric verification for high-value transactions under PSD2 technical standards, creating hardware replacement cycles across acquiring banks.
- Capacitive fingerprint modules:Mature supply chains and declining per-unit costs are enabling mass deployment across price-sensitive retail segments in Southeast Asia and Latin America.
- Jan Dhan financial inclusion:India's rural banking expansion is accelerating merchant adoption of Aadhaar-linked POS terminals for last-mile financial service delivery.
Market Restraints
- Ultrasonic sensor cost premium:Spoof-resistant hardware remains 3-4x more expensive than optical alternatives, limiting deployment to high-security verticals.
- Asia-Pacific sensor concentration:Capacitive module fabrication clusters heavily in East Asian manufacturing zones, exposing supply chains to geopolitical friction and logistics bottlenecks.
- Biometric data localization mandates:Emerging national data protection laws in multiple jurisdictions are restricting cross-border template storage and complicating cloud-terminal architectures.
Strategic Opportunities
- Cloud-based terminal management:Merchant acquirers are shifting from on-premise estates to centrally monitored platforms, opening recurring revenue streams for terminal-as-a-service models.
- Hospitality throughput optimization:Fast-casual restaurants and quick-service chains represent underpenetrated demand for contactless biometric payment to reduce queue abandonment.
- ISO 30107-3 certification:Presentation attack detection standards are creating procurement qualification barriers that favor vendors with certified sensor technologies.
Industry Challenges
- Integration complexity with legacy POS software:Merchant acquirers face extended deployment timelines reconciling biometric authentication APIs with decades-old payment processing stacks.
- Biometric enrollment friction:First-time user registration at checkout creates throughput delays that conflict with retail customer experience benchmarks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometric Point-Of-Sale Terminals Market |
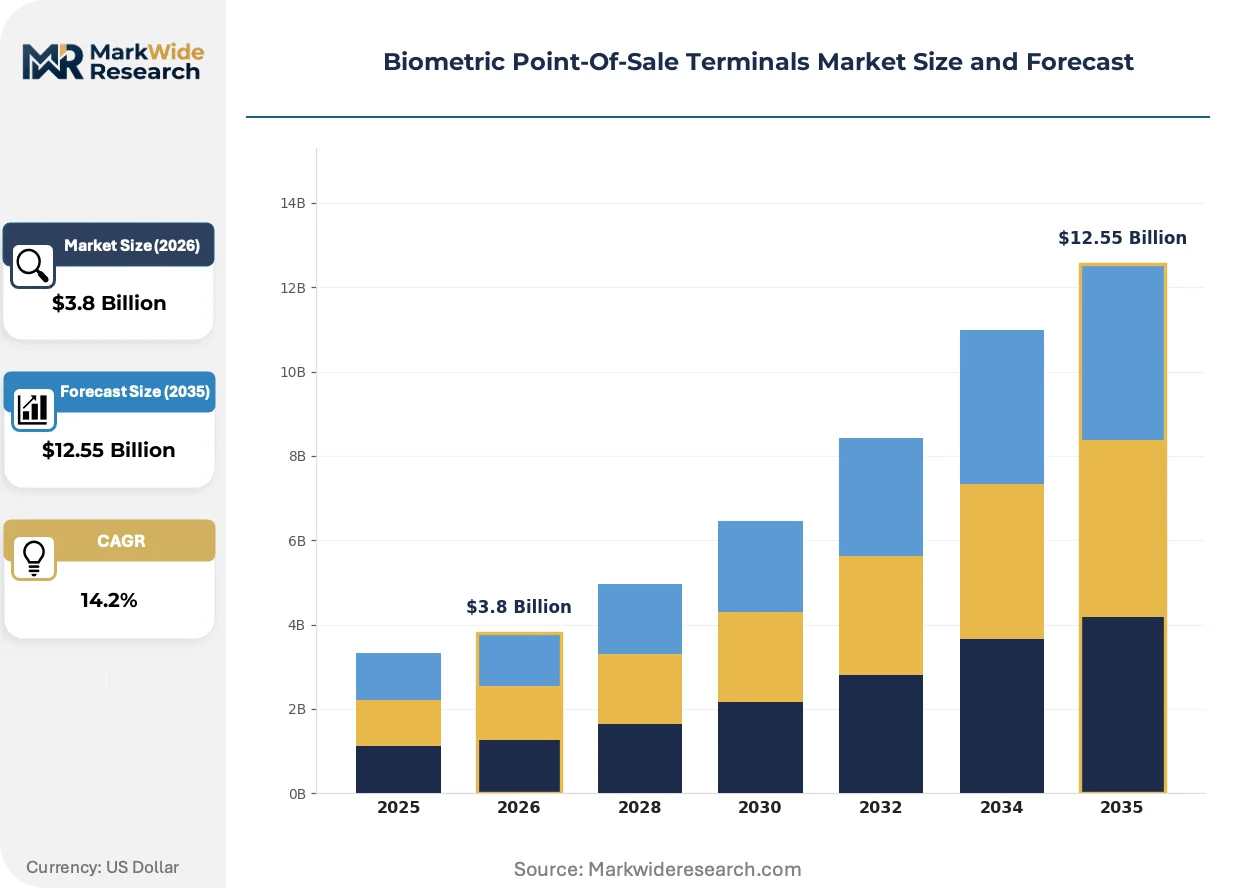
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint, Facial Recognition, Iris Scan, Voice Recognition End User: Retail, Hospitality, Banking, Healthcare Integration Level: Standalone, Integrated, Cloud-Based, Mobile Technology: Optical, Capacitive, Thermal, Ultrasonic |
| Companies Covered | IDEMIA, Ingenico (Worldline), NEC Corporation, Fujitsu Ltd., Suprema Inc., Verifone, PAX Technology, Zwipe, Fingerprint Cards AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometric Point-Of-Sale Terminals Market Strategic Shifts
Terminal hardware is converging with identity verification infrastructure as payment networks and government credential systems interoperate through standardized biometric templates.
Ultrasonic fingerprint sensing is miniaturizing from premium smartphones into compact POS form factors. High-end retail and banking deployments in Japan and South Korea are adopting these modules for their superior liveness detection. The technology is miniaturizing the trade-off between security tier and device footprint, enabling countertop terminals to match the spoof resistance previously reserved for branch-based hardware.
India's RBI tokenization guidelines are mandating end-to-end encryption for card data transmitted through biometric terminals. Payment processors must recertify hardware stacks to comply with de-tokenization protocols at the acquiring host. Domestic terminal vendors with pre-certified integration paths are capturing merchant procurement preference over import-dependent competitors.
Acquiring banks are unbundling terminal hardware from merchant service contracts. Independent software vendors and fintech platforms now procure biometric devices directly from manufacturers, bypassing traditional bank distribution channels. This pattern is most visible in India's urban merchant segments, where payment aggregators bundle biometric authentication with working capital and inventory management software.
Biometric Point-Of-Sale Terminals Market Segmentation
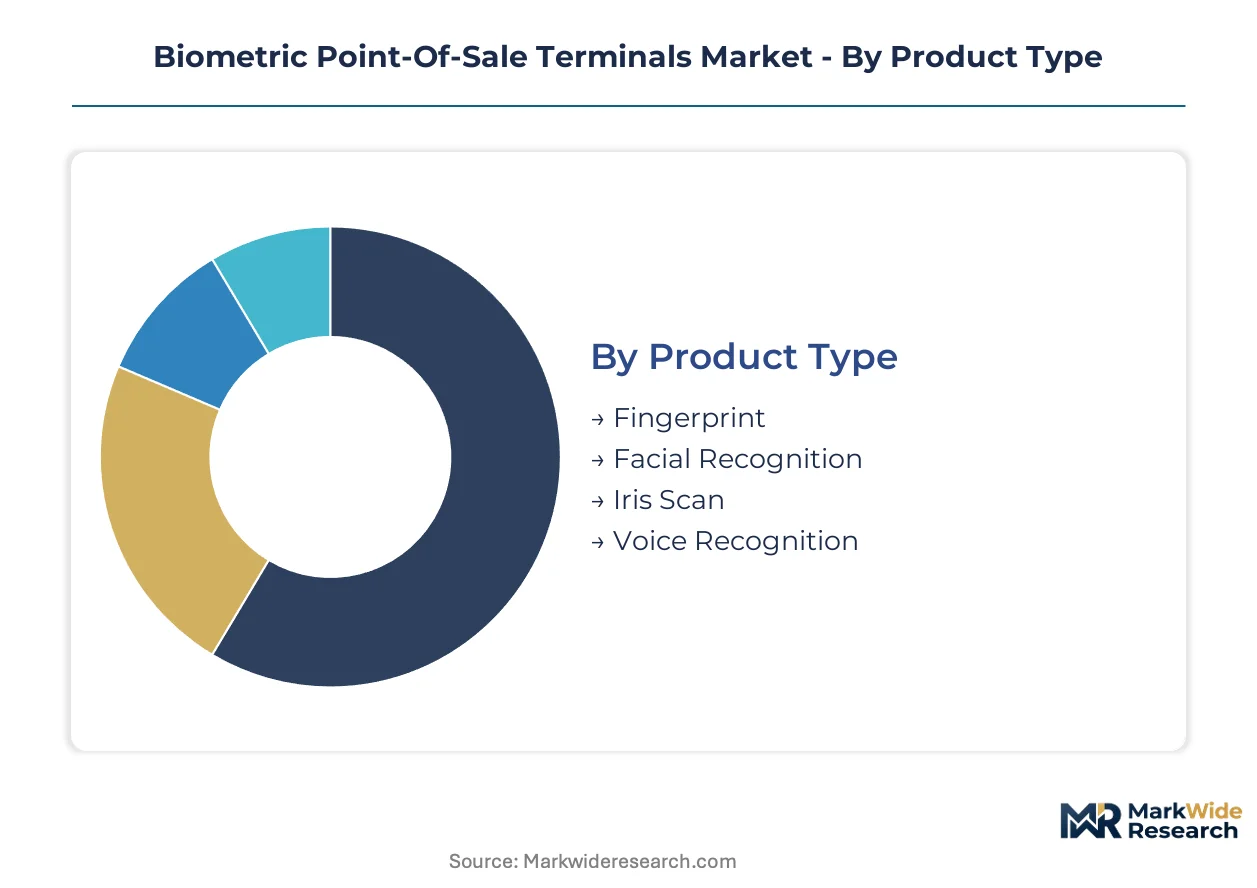
Biometric POS terminal segmentation reveals divergent margin structures across authentication modalities and deployment architectures. Product type and integration level categories command premium pricing tiers, while technology segments stratify by security certification requirements and manufacturing concentration.
Product Type:
Fingerprint modules capture the deepest margin pools due to mature supply chains and volume scale in retail banking deployments.
- Fingerprint:Optical and capacitive sensors authenticate cardholders through ridge pattern matching at transaction speeds under 300 milliseconds. Mass merchant adoption across India's Jan Dhan banking corridors and Southeast Asian retail chains drives procurement concentration in price-optimized hardware tiers.
- Facial Recognition:3D structured light and infrared depth mapping enable contactless authentication without physical sensor contact. Premium quick-service restaurants in Japan and South Korea are piloting these systems to reduce queue abandonment while satisfying EBA PSD2 Strong Customer Authentication mandates for high-value transactions.
- Iris Scan:Near-infrared imaging of unique stromal patterns delivers higher spoof resistance for healthcare payment contexts under FDA biometric data security guidance.
- Voice Recognition:Speaker verification algorithms authenticate through vocal biometric templates, finding niche deployment in drive-through and telephonic payment channels where hands-free operation is essential.
Fingerprint holds installed capacity. Facial recognition is rotating up the share rankings.
End User:
Application-specific compliance burdens reshape profitability across vertical deployment patterns.
- Retail:Supermarket chains and department stores deploy countertop and handheld terminals with fingerprint modules for card-present fraud reduction. RBI tokenization guidelines in India and EBA PSD2 mandates in Europe are accelerating replacement cycles for magnetic-stripe infrastructure.
- Banking:Branch-based and merchant-acquiring deployments require ISO 30107-3 certified presentation attack detection for regulatory procurement qualification. Ultrasonic sensor integration dominates this tier due to superior liveness detection requirements.
- Hospitality:Fast-casual restaurants prioritize transaction throughput over biometric enrollment, limiting penetration to premium segments where queue abandonment costs justify authentication friction.
- Healthcare:FDA guidance on biometric data security shapes terminal certification requirements for patient payment processing, with iris and fingerprint modalities preferred for HIPAA-aligned access control integration.
Banking commands premium pricing. Retail is expanding most quickly through developing-market financial inclusion programs.
Integration Level:
Cloud-connected architectures are displacing on-premise terminal estates and unlocking recurring revenue models.
- Cloud-Based:Centrally monitored platforms enable remote firmware updates, transaction analytics, and biometric template management across distributed merchant fleets. Payment aggregators in India's urban corridors bundle these capabilities with working capital software.
- Integrated:Android-based terminals with built-in fingerprint readers consolidate payment acceptance and merchant applications on single hardware stacks. Developing-market banks favor these units for reduced total cost of ownership.
- Standalone:Dedicated biometric peripherals connect to legacy POS systems through standardized APIs, serving merchant acquirers with extended deployment timelines reconciling authentication protocols with decades-old processing stacks.
- Mobile:Smartphone-attached readers and soft-POS applications extend biometric acceptance to micro-merchants and field sales operations, though enrollment friction limits adoption in high-throughput environments.
Cloud-based integration is climbing the fastest. Standalone maintains legacy installed base.
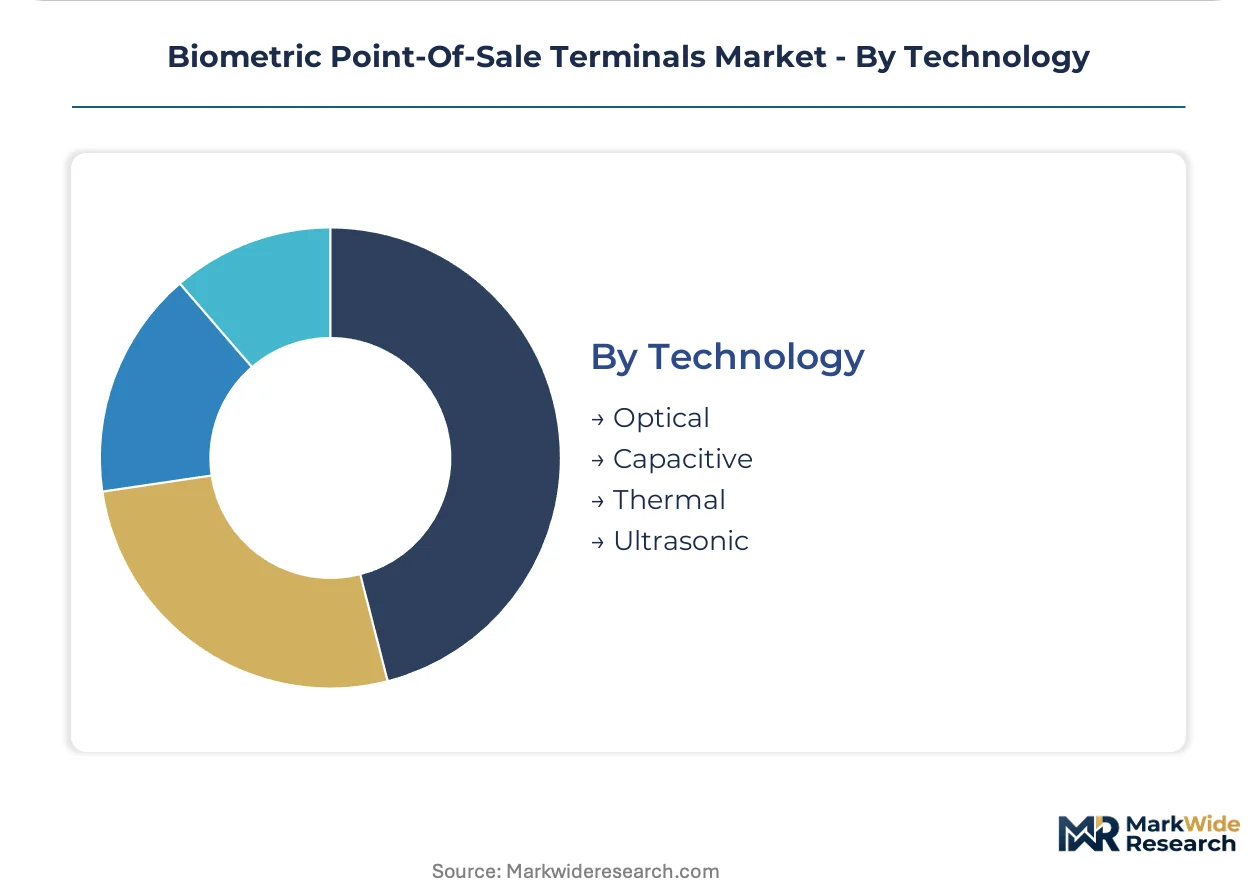
Technology:
Sensor fabrication concentration in East Asian manufacturing zones exposes supply chains to geopolitical friction and logistics bottlenecks.
- Capacitive:Silicon-based fingerprint sensing dominates unit volumes through mature semiconductor fabrication and declining per-unit costs. Supply chains cluster heavily in Japanese and South Korean manufacturing zones serving Asia-Pacific merchant acquirers.
- Ultrasonic:Piezoelectric transducers map fingerprint ridges through acoustic impedance differences, delivering superior spoof resistance for high-security banking and premium retail deployments. Miniaturization from smartphone supply chains is enabling compact POS form factors.
- Optical:Visible-light imaging sensors occupy entry-level price tiers where cost sensitivity outweighs presentation attack detection requirements.
- Thermal:Temperature differential sensing captures subcutaneous blood flow patterns for liveness verification, finding limited deployment in specialized healthcare and government credentialing contexts.
Capacitive holds installed capacity. Ultrasonic is gaining share fastest through premium banking certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capacitive sensor fabrication clusters heavily in Japanese and South Korean manufacturing zones, exposing procurement channels to logistics friction while India's regulatory mandates accelerate merchant hardware replacement cycles across distributed retail networks.
United States
Merchant acquirers face PCI DSS 4.0 compliance deadlines forcing magnetic-stripe terminal retirements. FDA guidance on biometric data security in healthcare payment contexts shapes certification requirements for patient-facing terminals. Silicon Valley fintech platforms and Atlanta payment processing hubs drive cloud-based terminal management adoption.
India
Jan Dhan financial inclusion programs and RBI tokenization guidelines accelerate Aadhaar-linked POS deployment across rural banking corridors. The central bank's de-tokenization protocol mandates are recertifying domestic hardware stacks. Mumbai and Bangalore payment aggregators bundle biometric authentication with working capital software for urban merchants.
Japan
High-end retail and banking deployments adopt ultrasonic fingerprint modules for superior liveness detection. METI industrial standards support sensor miniaturization from smartphone supply chains into compact POS form factors. Osaka and Nagoya manufacturing zones sustain capacitive module production for Asia-Pacific merchant acquirers.
Germany
EBA PSD2 Strong Customer Authentication technical standards compel payment processors to deploy biometric verification for high-value transactions. KBA oversight intersects with financial sector procurement requirements. Frankfurt and Munich banking technology clusters anchor enterprise POS contract negotiations for regulated European deployments.
South Korea
Premium quick-service restaurants pilot facial recognition systems to reduce queue abandonment while satisfying authentication mandates. MFDS regulatory frameworks align with financial sector biometric data handling protocols. Seoul and Suwon semiconductor fabrication zones supply capacitive sensor modules across developing-market retail segments.
Biometric Point-Of-Sale Terminals Market Competitive Environment
Concentration sits with diversified payment technology conglomerates and specialized biometric sensor manufacturers. The vendor base stratifies across three tiers: government credentialing specialists anchoring regulated sector contracts, scale-oriented terminal fabricators serving mass merchant deployments, and component-focused sensor suppliers capturing upstream margin pools. M&A activity concentrates payment network integration capabilities while strategic partnerships align hardware certification with evolving regulatory mandates.
Within the government credentialing tier, IDEMIA exemplifies enterprise positioning through its public-sector biometric infrastructure relationships. Fujitsu Ltd. and PAX Technology occupy distinct manufacturing scale positions—Japanese semiconductor fabrication against Chinese Android-integrated terminal production—each representing supply chain archetypes for capacitive sensor and all-in-one device procurement respectively.
| Leading Market Players |
|---|
| IDEMIA |
| Ingenico (Worldline) |
| NEC Corporation |
| Fujitsu Ltd. |
| Suprema Inc. |
| Verifone |
| PAX Technology |
| Zwipe |
| Fingerprint Cards AB |
| Others |
Value Chain & Pricing Dynamics
Capacitive sensor module substitution for optical alternatives simultaneously reshapes supply geography toward East Asian semiconductor clusters and compresses pricing economics across entry-level merchant tiers. This input transition concentrates procurement leverage with Japanese and South Korean fabricators while eroding margins for vendors locked into legacy optical supply chains.
Pricing Analysis
PCI DSS 4.0 dictates the pricing tier structure across merchant acquirer procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates ISO 30107-3 certified ultrasonic deployments from capacitive mid-tier hardware and optical entry-level units. Cost compression in the optical tier is intensifying because Indian and Southeast Asian price-sensitive retail segments prioritize per-unit acquisition cost over spoof resistance. Micro-merchants and rural banking correspondents exhibit the highest price sensitivity, while regulated European banking deployments show the least.
Supply Chain Analysis
Inventory cycles for capacitive sensor modules currently stretch 12-16 weeks as merchant acquirers pre-position hardware ahead of RBI tokenization compliance deadlines. Module fabrication draws from Japanese and South Korean manufacturing zones, with final assembly concentrating in Chinese and Taiwanese production facilities. Single-source vulnerability sits with East Asian semiconductor foundries exposed to geopolitical friction and logistics chokepoints at regional ports. Distribution runs through payment network-authorized distributors and direct procurement by merchant acquirers bypassing traditional bank channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric POS terminal incumbents face substitution defense against soft-POS and smartphone-attached readers that displace dedicated hardware among micro-merchants. This threat demands strategic repositioning around certification moats and cloud-service bundling.
For Market Incumbents: Shield core merchant acquirer relationships by accelerating ISO 30107-3 certification roadmaps for ultrasonic sensor portfolios before regulatory deadlines harden procurement barriers. Anchor cloud-based terminal management platforms with recurring revenue streams that offset hardware margin compression from payment aggregator competition. Backward integration into capacitive sensor supply through Japanese semiconductor partnerships reduces exposure to East Asian logistics bottlenecks.
For New Entrants and Emerging Players: Cloud-terminal software layers represent the most penetrable white-space where incumbent hardware vendors under-serve independent software vendors and fintech platforms. India's urban payment aggregator corridors offer the fastest route to scale through biometric-authentication bundling with working capital software. Target hospitality throughput optimization with facial recognition pilots in premium quick-service chains where queue abandonment costs justify authentication friction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed payment terminal conglomerates seeking cloud-platform capabilities to complete hardware-to-software transitions. Long-term viability hinges on regulatory certification depth rather than unit volume scale. Watch EBA PSD2 enforcement intensity across European acquiring banks as the inflection indicator for premium hardware demand.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 30107-3 Certification Investment | Presentation attack detection standards create procurement qualification barriers favoring certified sensor vendors. |
| Cloud Platform Integration | Centrally monitored terminal estates unlock recurring revenue from merchant acquirers shifting from on-premise hardware. |
| Capacitive Sensor Supply Partnership | Japanese and South Korean semiconductor fabrication anchoring reduces logistics exposure and secures volume pricing. |
| Payment Aggregator Channel Development | Direct procurement relationships with India's fintech platforms bypass traditional bank distribution chokepoints. |
| Ultrasonic Module Miniaturization | Smartphone-derived piezoelectric transducer technology enables compact POS form factors with superior liveness detection. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and payment network certification records. Merchant acquirer procurement directors, terminal hardware engineering leads, biometric sensor manufacturing executives, and fintech platform integration specialists contributed structured input. Bottom-up unit shipment modeling triangulates against top-down payment transaction volume analysis across the analysis window.
Segmentation dimensions modeled include authentication modality, integration architecture, end-user vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, compliance deadline sequencing, and financial inclusion program expansion trajectories. Forecast inputs incorporate RBI tokenization protocol mandates, EBA PSD2 technical standard enforcement patterns, and capacitive sensor cost curve assumptions.
Underlying assumptions cover regulatory deadline adherence, supply chain logistics continuity, and merchant hardware refresh cadence, with deviation risk concentrated in biometric data localization mandate proliferation and East Asian manufacturing zone disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Global Biometric-As-A-Service Market
Biometrics & Identity Management
AI-Enabled Biometrics Market
Biometrics & Identity Management
Signature Verification Market
Biometrics & Identity Management
Biometric Services Platform (Biosp) Market
Biometrics & Identity Management
Consumer Biometrics Market
Biometrics & Identity Management
Europe Biometrics Market
Biometrics & Identity Management
Military Biometrics Market
Biometrics & Identity Management
Europe Biometrics in Government Market
Biometrics & Identity Management
Automated Fingerprint Identification Systems (AFIS) Market
Biometrics & Identity Management
Vein Recognition Biometrics Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Global Biometric Identification Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Biometric Scan Software Market
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Asia Pacific Biometrics in Government Market