
 United States Poultry Meat Market | 2026-2036
United States Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
United States Poultry Meat Market Analytics
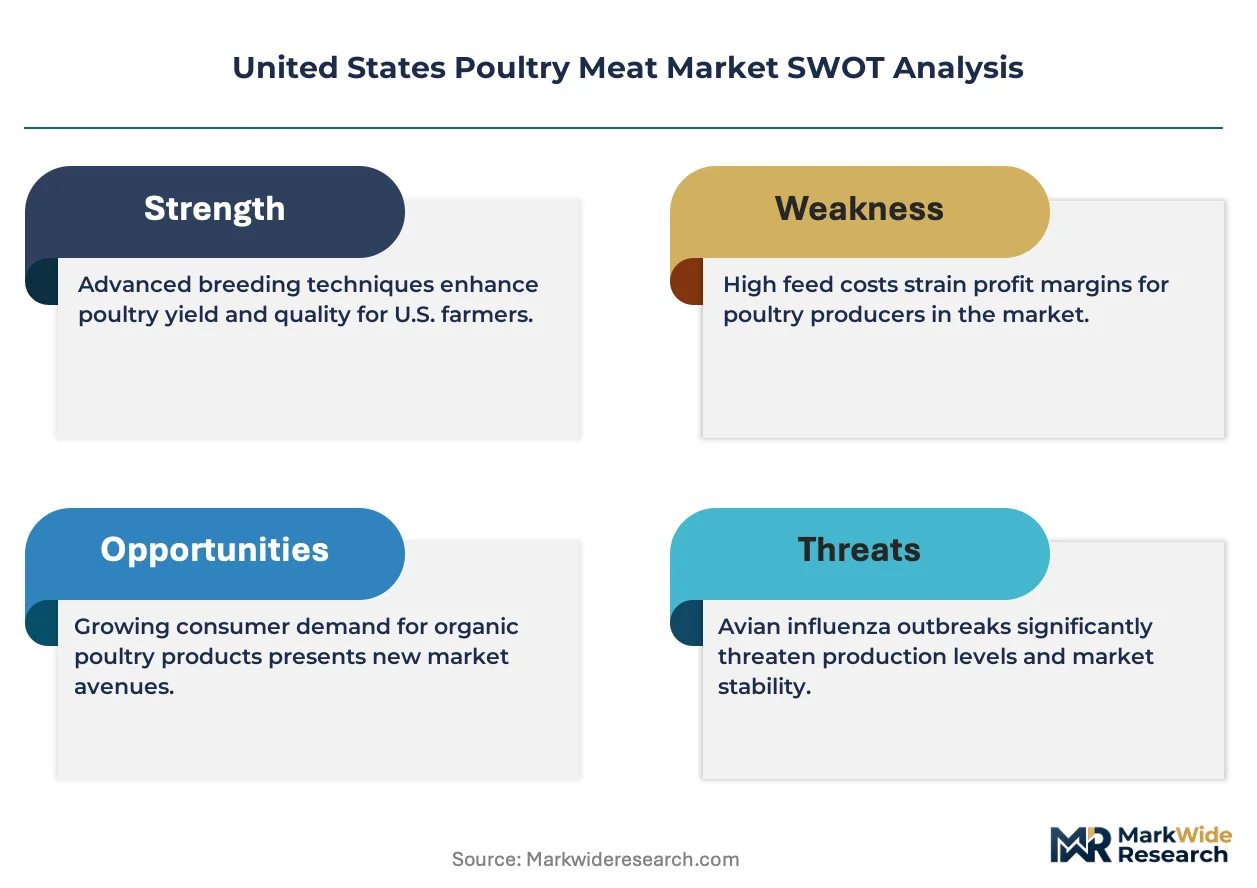
Processing plant labor availability is collapsing across the rural Midwest and Southeast, forcing automation investments and wage escalation that reshape unit economics. Tyson Foods Inc. leverages vertical integration from feed mills to distribution to buffer margin pressure. Sanderson Farms Inc. sustains cost discipline through breeder stock control and dedicated grower networks. Perdue Farms Inc. differentiates via antibiotic-reduced product lines and branded retail positioning.
United States poultry meat encompasses avian muscle tissue processed for human consumption, typically slaughtered under USDA-FSIS inspection with carcass chilling to below 40°F within specified timeframes to inhibit microbial proliferation. The primary commercial purpose centers on delivering affordable, high-protein nutrition to retail consumers and institutional food operators. Chicken dominates volume across product type segments due to feed conversion efficiency and processing flexibility. The food service distribution channel captures expanding share as quick-service chains and casual dining operators reformulate menus around poultry-centric offerings. Premium and organic price tiers extract disproportionate margin despite smaller volume bases, reflecting consumer willingness to pay for welfare and label claims.
USDA-FSIS inspection protocols and the National Poultry Improvement Plan shape processing standards, while FDA oversight of feed additives and veterinary drugs constrains production inputs. State-level environmental regulations, particularly nutrient management rules in Delaware, Maryland, and Arkansas, limit expansion of concentrated feeding operations. Stakeholders must monitor evolving cage-free and slow-growth commitments from major food service buyers, as these sourcing specifications threaten to outpace supply chain adaptation and create allocation bottlenecks for compliant product.
Market Dynamics
Labor scarcity across the rural Southeast and Midwest is forcing accelerated automation adoption and wage restructuring that fundamentally alters processing plant economics and competitive positioning.
Growth Catalysts
- USDA-FSIS Pathogen Reduction Standards:Tightening inspection mandates drive capital investment in antimicrobial interventions and rapid chilling systems that elevate food safety benchmarks industry-wide.
- Food Service Menu Reformulation:Quick-service chains and casual dining operators are expanding poultry-centric offerings as operators seek cost-efficient protein alternatives amid beef price volatility.
- Georgia and Arkansas Production Clusters:Integrated supply networks concentrated in these states deliver feed-to-processing cost advantages that sustain margin competitiveness against alternative proteins.
Market Restraints
- Soybean and Corn Input Volatility:Feed grain price fluctuations compress grower margins and create working capital stress across contract production networks.
- Delaware-Maryland Nutrient Management Rules:State-level environmental regulations constrain expansion of concentrated feeding operations and impose compliance costs on existing facilities.
- Plant-Based Protein Substitution:Alternative meat products capture share in food service and premium retail segments where taste and texture gaps have narrowed.
Strategic Opportunities
- Cage-Free and Slow-Growth Specifications:Major food service buyers' welfare commitments create allocation premiums for compliant supply that currently outpaces certified production capacity.
- Antibiotic-Reduced Product Lines:Branded positioning around reduced antibiotic use extracts margin premiums in retail channels where label claims drive purchase decisions.
- Direct-to-Food-Service Distribution:Bypassing traditional wholesale layers through dedicated supply agreements captures value previously extracted by intermediaries.
Industry Challenges
- Automation Integration Complexity:Robotics deployment in live-hang and cut-up departments requires retraining existing workforces and retrofitting legacy line configurations.
- Certification Timeline Compression:Third-party welfare and organic audits create bottlenecks as demand for verified claims outstocks accredited inspector availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Poultry Meat Market |
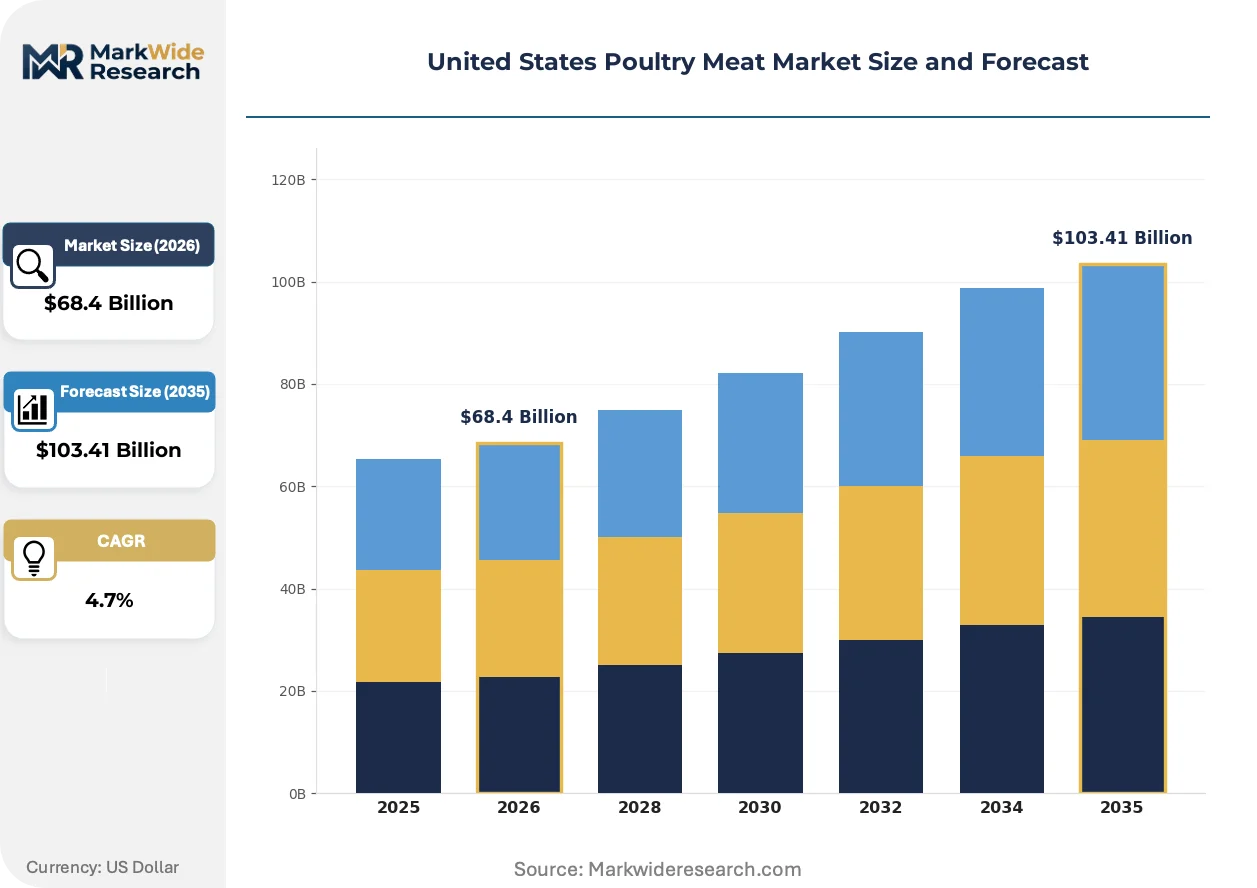
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chicken, Turkey, Duck, Goose Distribution Channel: Retail, Wholesale, Food Service, Online Price Tier: Economy, Mid-Range, Premium, Organic End User: Household, Restaurants, Institutions, Food Manufacturers |
| Companies Covered | Cargill Inc., Sanderson Farms Inc., Tyson Foods Inc., Foster Farms, Wayne Farms LLC, Pilgrim's Pride Corporation, Koch Foods, House of Raeford Farms Inc., Perdue Farms Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Poultry Meat Market Evolving Landscape
Processing technology and sourcing specifications are converging to reshape how poultry moves from farm to plate, with automation and welfare standards emerging as the primary axes of competitive differentiation.
Computer vision-guided robotic cut-up systems are displacing manual labor in breast and thigh deboning operations. Large integrated processors deploy these systems in greenfield plants across Alabama and Mississippi. The technology is displacing traditional skilled-cutter roles while compressing yield variation and throughput bottlenecks that previously constrained line speeds.
USDA-FSIS has finalized updated Salmonella performance standards for raw chicken products effective across slaughter establishments. The rule mandates enhanced sampling protocols and establishes enforceable contamination limits that trigger regulatory response. Further-processing operations serving retail and food service channels are investing in pre-chill interventions and post-chill antimicrobial applications to maintain compliance.
Quick-service chains are consolidating supplier relationships around dedicated supply agreements that specify genetics, housing standards, and processing parameters. This procurement consolidation is displacing spot-market purchasing and commodity-grade product flows. The shift is most visible in Southeast regional supply chains where integrated processors have invested in segregated production streams to capture contracted volume commitments.
United States Poultry Meat Market Segmentation
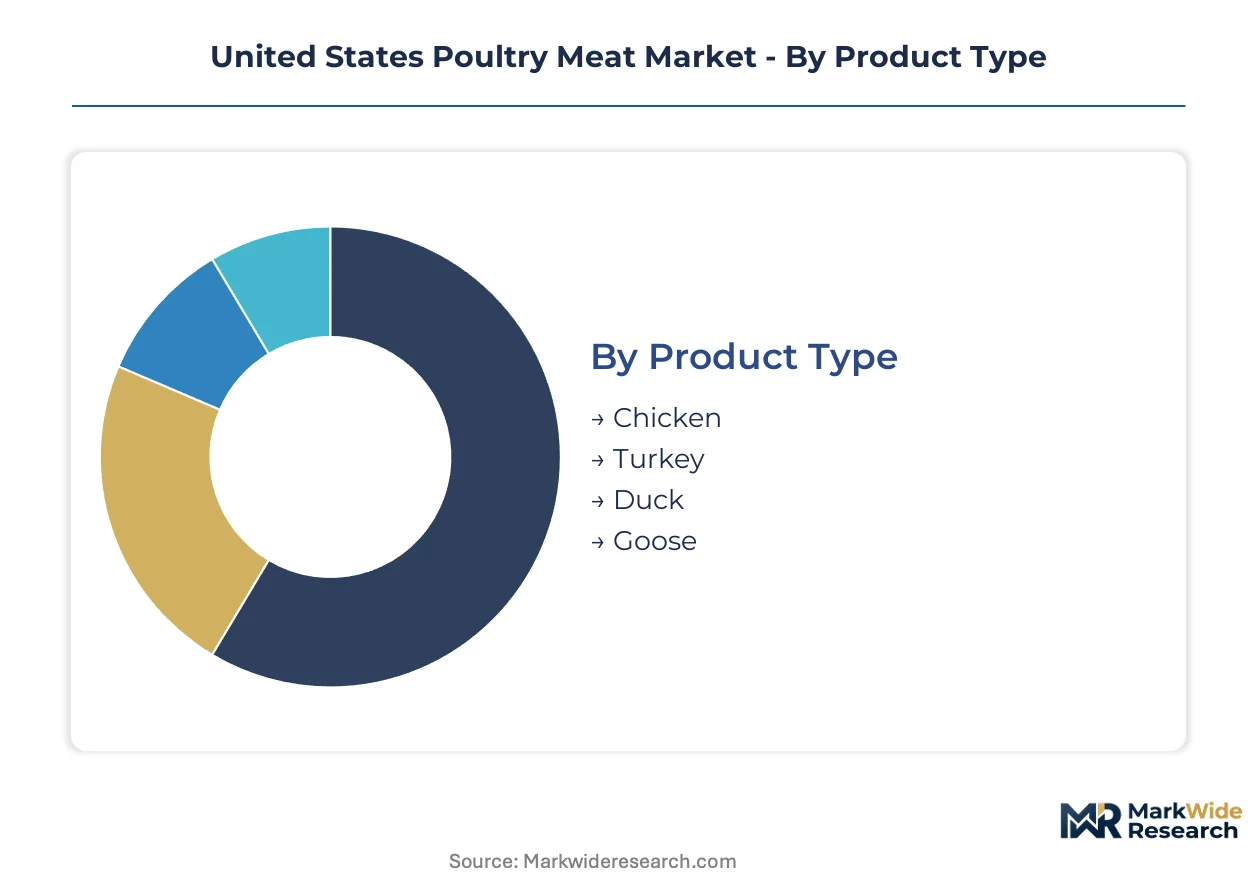
Poultry meat segmentation in the United States reflects divergent supply chain economics across channels. Each dimension—product type, distribution channel, price tier, and end user—carries distinct margin profiles and regulatory exposure that shape processor investment priorities.
Product Type:
Channel mix varies sharply by avian species, with chicken flowing predominantly through high-volume retail and food service pipelines while specialty birds command dedicated distribution infrastructure.
- Chicken:Broiler carcasses and component cuts constitute the volume foundation of the industry. Breast meat concentrates in quick-service chain supply agreements across the Southeast, where Tyson Foods and Sanderson Farms maintain dedicated processing lines for contracted food service volume.
- Turkey:Whole birds and further-processed deli items serve seasonal retail demand and institutional prepared foods. Ground turkey and breast cutlets are gaining placement in retail cases across the Midwest as beef price volatility drives protein substitution in household purchasing.
- Duck:Specialty processing for ethnic food service and fine dining channels operates through smaller regional facilities concentrated in California and New York.
- Goose:Minimal commercial volume serves holiday retail and niche restaurant applications with limited processing infrastructure outside traditional agricultural regions.
Chicken dominates installed base. Turkey is where expansion concentrates for value-added processed products.
Distribution Channel:
Cost tier alignment determines channel profitability, with premium product flows bypassing traditional wholesale markups through direct relationships.
- Retail:Supermarket and club store channels move case-ready and tray-packed product under private label and branded programs. Walmart and Kroger procurement consolidation is forcing processor investment in case-ready automation to meet exacting specification tolerances.
- Wholesale:Traditional broadline distributors serve independent restaurants and smaller retail accounts with commodity-grade bulk product. This channel faces margin compression as direct procurement from integrated processors displaces intermediary layers.
- Food Service:Quick-service chains and contract dining operators source through dedicated supply agreements specifying genetics and welfare standards. McDonald's and Chick-fil-A procurement teams are consolidating supplier relationships around single-source accountability for Salmonella compliance.
- Online:Direct-to-consumer and meal-kit channels remain nascent but growing for premium and organic positioning. Perdue Farms and smaller regional processors are testing cold-chain fulfillment for subscription poultry boxes in urban Northeast markets.
Food service captures the steepest expansion trajectory. Wholesale faces structural compression as direct sourcing accelerates.
Price Tier:
Application requirements separate pricing strata, with institutional buyers prioritizing cost control while retail premium tiers extract margin through label differentiation.
- Economy:Commodity-grade whole birds and random-cut portions serve price-sensitive institutional and value retail segments. School nutrition programs and correctional facilities procure through USDA Foods and state cooperative purchasing agreements.
- Mid-Range:Standard branded products with basic quality assurances dominate household volume. This tier faces the greatest pressure from private label substitution as retailers consolidate around captive brands.
- Premium:Enhanced welfare claims and breed specifications command shelf price multiples in specialty retail. Whole Foods Market and regional co-op procurement standards are driving processor investment in slower-growing genetics and enriched housing systems.
- Organic:Certified organic production with verified feed sourcing and outdoor access requirements serves the highest-margin retail niche. Supply constraints in certified organic feed grain and processing capacity limit expansion despite sustained demand premiums.
Economy tier moves the largest physical volume. Organic is climbing the fastest on a percentage basis despite small base.
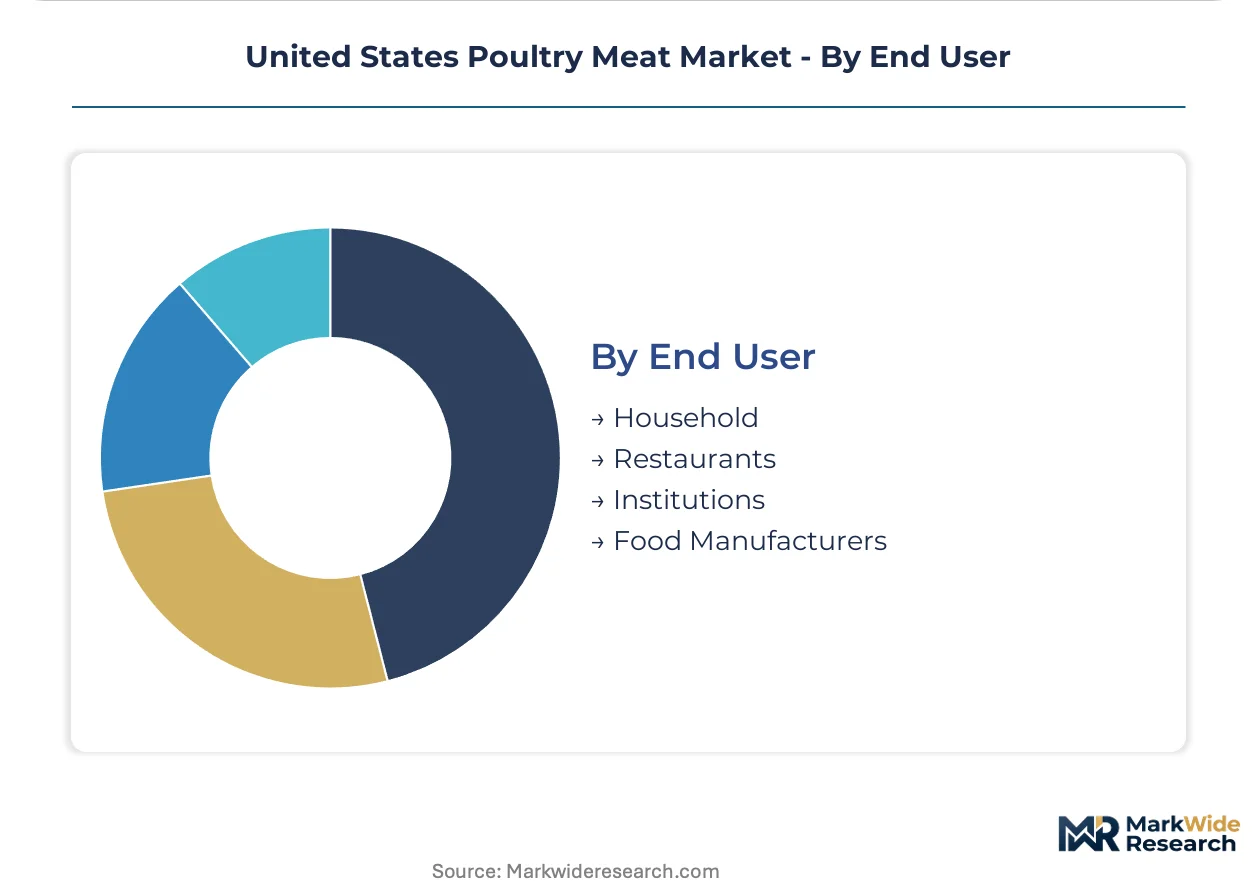
End User:
Volume scale separates customer types, with household purchasing spread across millions of discrete transactions while institutional buyers concentrate demand in large contracts.
- Household:Individual consumers purchasing for home preparation drive retail channel design and packaging formats. E-commerce penetration in fresh poultry remains limited by cold-chain complexity and perishability concerns.
- Restaurants:Full-service and limited-service operators reformulate menus around poultry as beef and pork cost volatility persists. Wing and tenderloin specifications dominate quick-service procurement conversations.
- Institutions:Healthcare, education, and government feeding programs prioritize cost containment and nutritional compliance over sensory attributes. USDA Foods distribution and state procurement contracts structure this segment.
- Food Manufacturers:Further-processors of canned soup, frozen entrees, and pet food ingredients purchase mechanically separated meat and trim for formulation input. This industrial channel operates on thin margins with exacting specification tolerances.
Household demand anchors volume base. Food manufacturers represent the most concentrated procurement leverage for commodity trim and mechanically separated product.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Georgia commands pricing premiums over the Midwest due to integrated feed-to-processing density, while Arkansas growers absorb margin compression from environmental compliance costs. This regional asymmetry concentrates investment flows and shapes competitive positioning across state boundaries.
Southeast
Quick-service chain procurement teams source contracted volume from Georgia and Alabama processing clusters. USDA-FSIS inspection mandates drive capital deployment in antimicrobial intervention systems across the region. The Georgia poultry corridor anchors national breast meat supply through Tyson Foods and Sanderson Farms integrated operations.
Mid-Atlantic
Delaware and Maryland operations face constrained expansion from nutrient management rules limiting concentrated feeding operation permits. Perdue Farms maintains breeder stock control and dedicated grower networks to sustain cost discipline. The Delmarva Peninsula processes specialty birds for ethnic food service channels in Philadelphia and New York metro markets.
Midwest
Illinois and Ohio facilities supply mechanically separated meat to frozen entree manufacturers and pet food formulators. Labor scarcity forces accelerated automation adoption in deboning departments. The Ohio River Valley corridor concentrates further-processing capacity for retail case-ready programs serving Walmart and Kroger distribution centers.
Southwest
Texas operations leverage proximity to Mexico for cross-border feed grain sourcing and export market access. State environmental regulations impose lower compliance burdens than coastal jurisdictions. The East Texas pine belt hosts expanding processing capacity targeting quick-service chain specifications for wing and tenderloin products.
West Coast
California specialty processors serve fine dining and ethnic restaurant channels with duck and premium chicken products. State Proposition 12 housing standards drive sourcing specification divergence from national commodity flows. The Central Valley maintains limited broiler production due to water constraints and air quality regulations.
United States Poultry Meat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around integrated processors with captive feed mill networks and dedicated grower contracts, while smaller regional operators occupy specialty and ethnic channel niches. Strategic archetypes include vertically integrated volume leaders, cost-disciplined mid-tier specialists, and premium-positioned branded players. Dominant competitive moves center on backward integration into breeder stock control and forward integration into direct food service distribution agreements.
Among integrated volume leaders, Tyson Foods Inc., Sanderson Farms Inc., and Perdue Farms Inc. exemplify the three dominant strategic positions in the market. Tyson Foods represents the archetype of full vertical integration from feed production through distribution. Sanderson Farms occupies a position defined by disciplined cost control and dedicated contract grower networks. Perdue Farms anchors the premium-tier vector through antibiotic-reduced product lines and branded retail positioning that extracts margin premiums from label-conscious consumers.
| Leading Market Players |
|---|
| Cargill Inc. |
| Sanderson Farms Inc. |
| Tyson Foods Inc. |
| Foster Farms |
| Wayne Farms LLC |
| Pilgrim's Pride Corporation |
| Koch Foods |
| House of Raeford Farms Inc. |
| Perdue Farms Inc. |
| Others |
Value Network & Pricing Analysis
Feed mill capacity utilization above 85% across Georgia and Arkansas clusters compresses per-unit fixed costs and anchors regional price floors that Midwest competitors struggle to match without equivalent scale density.
Pricing Analysis
The customization-premium spread between standard commodity carcasses and configured-to-order product lines for quick-service chains spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on welfare certification grade and volume scale commitments in dedicated supply agreements. Pricing pressure stems from soybean and corn input volatility that compresses grower contract margins. Institutional buyers in USDA Foods programs exhibit highest price sensitivity, while premium retail channels at Whole Foods Market show least sensitivity due to label claim premiums.
Supply Chain Analysis
Strategic stockpiling of breeder stock and parent flocks dominates inventory strategy given the 40-week production cycle from egg to processing weight. Geographic supply concentration centers on Georgia, Arkansas, and Alabama where integrated operations control feed-to-processing density. The supply chain draws from corn and soybean meal inputs, live bird inventories, and specialized genetics. Single-source vulnerability in breeder stock supply creates structural risk. Distribution runs through dedicated food service agreements and retail case-ready programs that displace traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food service menu reformulation around poultry-centric offerings signals early-cycle expansion with penetration tailwinds from quick-service chain procurement consolidation.
For Market Incumbents: Secure breeder stock control and dedicated grower network expansion to defend against plant-based protein substitution in premium channels. Accelerate automation deployment in deboning departments to offset labor scarcity margin pressure. USDA-FSIS inspection mandates create compliance leverage for scale players with capital reserves. For New Entrants and Emerging Players: Differentiate on cage-free and slow-growth welfare specifications where certified production capacity lags buyer commitments. Target organic price tier supply gaps in Northeast urban markets. Pursue direct-to-food-service distribution agreements that bypass incumbent wholesale relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated processors with captive feed mill networks and long-term quick-service chain contracts. Long-term viability favors operators with backward integration into genetics and forward integration into branded retail positioning. Watch for inflection when Delaware-Maryland nutrient management rules trigger facility relocation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Deployment in Deboning | Tyson Foods and Sanderson Farms retrofit Alabama and Mississippi plants with computer vision-guided robotic cut-up systems. |
| Cage-Free Production Stream Segregation | Perdue Farms invests in slower-growing genetics and enriched housing to capture Chick-fil-A welfare specification premiums. |
| Direct Food Service Supply Agreements | McDonald's procurement consolidation around single-source accountability displaces spot-market commodity flows. |
| Antimicrobial Intervention Capital Deployment | USDA-FSIS Salmonella performance standards trigger investment in pre-chill and post-chill treatment systems. |
| Organic Feed Grain Supply Integration | Certified organic production expansion faces constraints from limited accredited feed sourcing and processing capacity. |
Research Methodology
Cross-validation between USDA-ERS production surveys and FSIS inspection volume data anchors the qualitative findings from primary stakeholder engagement. The research combined interviews with poultry processing plant managers, quick-service chain procurement directors, contract grower operators, and feed mill supply planners with secondary validation from USDA-FSIS regulatory filings, SEC 10-K disclosures, state environmental permit databases, and trade association production statistics. Bottom-up volume triangulation against top-down value estimates calibrated segment-level outputs.
Sensitivity analysis around feed grain price assumptions and labor cost escalation scenarios tested forecast robustness across the projection horizon. The analytical framework modeled segmentation dimensions including product type, distribution channel, price tier, and end user with regional production cluster overlays. CAGRs derived from trend extrapolation adjusted for regulatory compliance cost inflections and technology adoption S-curves. Industry-specific inputs included breeder stock inventory cycles, USDA-FSIS inspection capacity constraints, and quick-service chain menu reformulation timelines.
The analysis sits within stated boundaries; outcomes outside sustained feed grain price stability and labor automation deployment rates would require recalibration. Forecasts reflect documented assumptions regarding welfare specification adoption curves and environmental regulation enforcement intensity. Revision becomes warranted when plant-based protein taste-texture parity thresholds cross adoption inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
GCC Edible Meat Market
Meat Products
Sausage Premixes Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
North America Red Meat Market
Meat Products
Global Beef Market
Meat Products
United States Frozen Meat Market
Meat Products
Grass Fed Beef Market
Meat Products
Grass-Fed Meat Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Global Poultry Meat Market
Meat Products
Canned Chicken Market
Meat Products
Chicken Fat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Beef Fat Powder Market