
 Global Duck Meats Market | 2026-2036
Global Duck Meats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duck Meats Market Analysis
Subscription-based cold-chain logistics is consolidating how premium duck products reach institutional buyers. Maple Leaf Farms leverages vertical integration across hatcheries and processing plants to sustain consistent supply to North American foodservice accounts. Charoen Pokphand Foods anchors Southeast Asian production capacity through integrated feed-to-table operations. Gressingham Foods differentiates via heritage breed specialization and controlled-atmosphere packaging for UK retail channels.
Duck meat comprises the muscle tissue of domesticated Anas platyrhynchos and Cairina moschata species, typically yielding 15-25% fat content with distinctive red-muscle myoglobin profiles that require precise temperature control during processing to prevent oxidative rancidity. The primary commercial purpose centers on protein provision for foodservice and retail sectors where flavor intensity commands premium positioning over conventional poultry. Whole Duck and Duck Breast segments capture the dominant margin pools in premium channels, while Processed Duck expands fastest in convenience-oriented Asian markets where marinated and pre-cooked formats reduce kitchen labor. Organic and Free-range grades attract disproportionate shelf-space investment in European supermarkets, though Conventional production retains volume leadership across global foodservice procurement.
USDA grading standards and FDA HACCP protocols govern slaughter and processing compliance for US-exported product, while EFSA microbiological criteria and REACH-packaging rules shape European market access requirements. China's SAMR enforces GB standards for fresh and frozen poultry labeling that directly affect import eligibility for foreign duck meat suppliers. Stakeholders must monitor evolving antibiotic residue thresholds across multiple jurisdictions and assess cold-chain infrastructure investments before committing to premium grade expansion.
Market Dynamics
Specialty foodservice channels in France and China are absorbing more premium duck cuts, tightening cold-chain requirements and consolidating procurement around vertically integrated suppliers capable of consistent breed traceability and temperature-controlled fulfillment.
Growth Catalysts
- EU Hygiene Regulations:Tighter EFSA microbiological criteria are accelerating facility upgrades among processors seeking export eligibility, filtering out smaller operators and concentrating volume among compliant suppliers.
- Heritage Breed Specialization:Controlled-atmosphere packaging advances are extending shelf life for premium retail channels in the United Kingdom, enabling wider distribution of fresh duck breast products.
- Yangtze River Delta Demand:China's GB standards enforcement is redirecting institutional procurement toward certified cold-chain operators capable of dual-carbon-aligned logistics.
Market Restraints
- Feed Input Volatility:Soybean and grain price fluctuations directly compress margins for integrated feed-to-table operations, particularly affecting Southeast Asian production clusters.
- Antibiotic Residue Thresholds:Diverging maximum residue limits between USDA, EFSA, and SAMR jurisdictions create compliance fragmentation for exporters serving multiple markets simultaneously.
- Substitute Proteins:Plant-based analogs and cultivated poultry alternatives are capturing premium protein shelf space in European supermarkets, pressuring duck positioning in the alternative-meat narrative.
Strategic Opportunities
- Marinated Pre-Cooked Formats:Convenience-oriented Asian markets show absorption capacity for value-added duck products that reduce foodservice kitchen labor and waste.
- Subscription Cold-Chain Logistics:Institutional buyers in North American foodservice are consolidating procurement around temperature-guaranteed delivery models that premium duck suppliers can anchor.
- Organic Grade Expansion:REACH-compliant sustainable packaging combined with free-range certification is opening disproportionate shelf-space investment in German and French retail channels.
Industry Challenges
- HACCP Specialist Scarcity:Qualified food safety auditors capable of multi-jurisdictional compliance verification command premium compensation, constraining processor expansion timelines.
- Cold-Chain Capex Intensity:Controlled-atmosphere storage and blockchain-enabled traceability systems require substantial capital deployment before premium grade eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duck Meats Market |
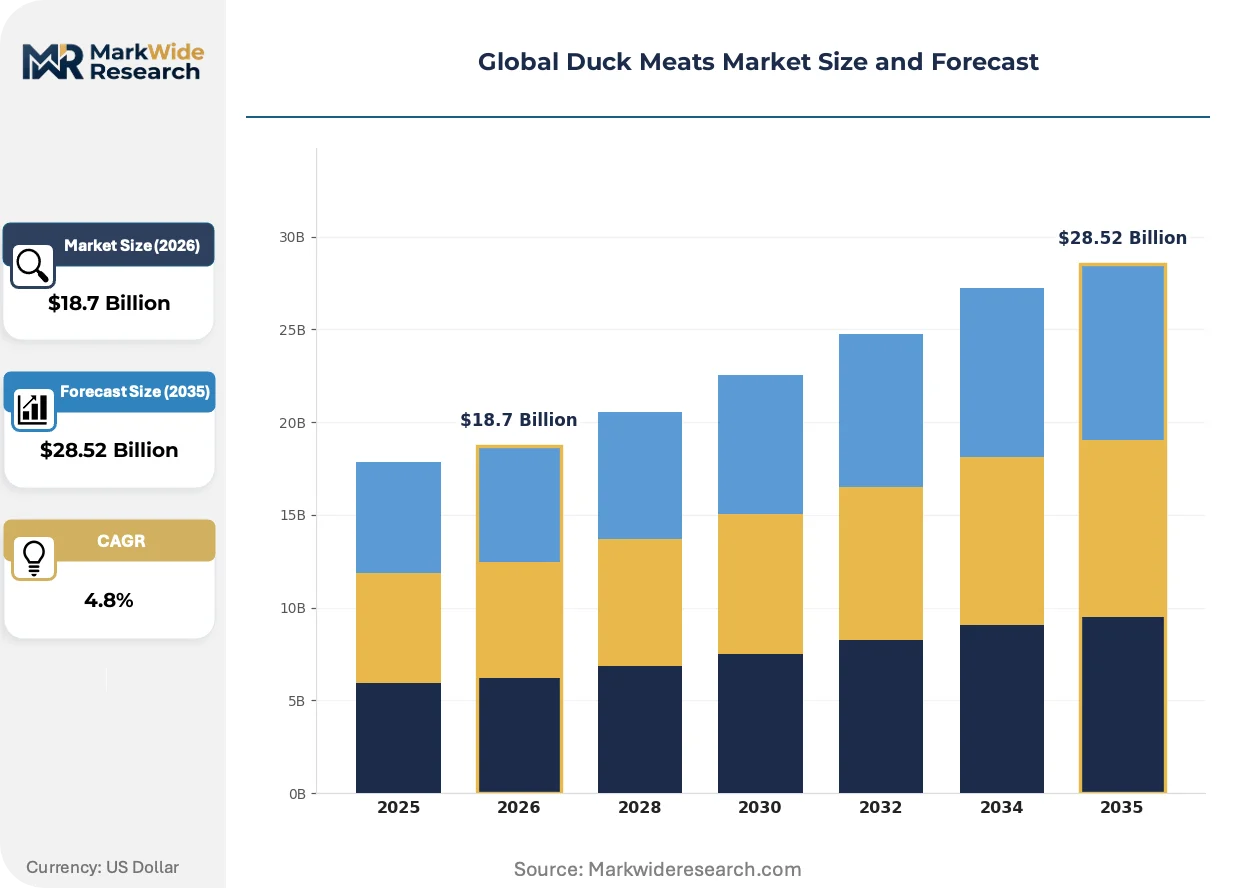
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Duck Breast, Duck Legs, Whole Duck, Processed Duck Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Food Service End User: Households, Restaurants, Hotels, Caterers Grade: Organic, Free-range, Conventional, Others |
| Companies Covered | Charoen Pokphand Foods, AJC International, Maple Leaf Farms, Luv-a-Duck, Gressingham Foods, Culver Duck Farms, Joe Jurgielewicz & Son, Pepe's Ducks, New Hope Liuhe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duck Meats Market Emerging Trajectories
Processing technology and regulatory alignment are compressing the gap between harvest and premium-channel placement, while procurement consolidation favors suppliers with captive cold-chain capabilities.
Controlled-atmosphere packaging systems using modified gas compositions are extending fresh duck product shelf life from days to weeks without freezing. High-end retailers in France and the United Kingdom are adopting these formats for whole duck and breast cuts. The technology is expanding into foodservice pre-portioning operations, enabling just-in-time delivery models that reduce inventory carrying costs for institutional buyers.
REACH packaging rules and EU Green Deal circularity mandates are forcing material transitions away from conventional plastics toward compostable barrier films. Processors serving European markets must validate migration limits and end-of-life disposal pathways. Organic and free-range grade suppliers face the tightest compliance windows, as their buyer profiles demand simultaneous sustainability certification across packaging and production.
Foodservice procurement teams are consolidating vendor lists around suppliers offering integrated hatchery-to-delivery traceability. Large-scale restaurant groups in China's Yangtze River Delta and France's Brittany region now require batch-level blockchain documentation. This concentration pattern favors vertically integrated operators with captive breeding programs and dedicated logistics assets over fragmented assembly models.
Global Duck Meats Market Segmentation
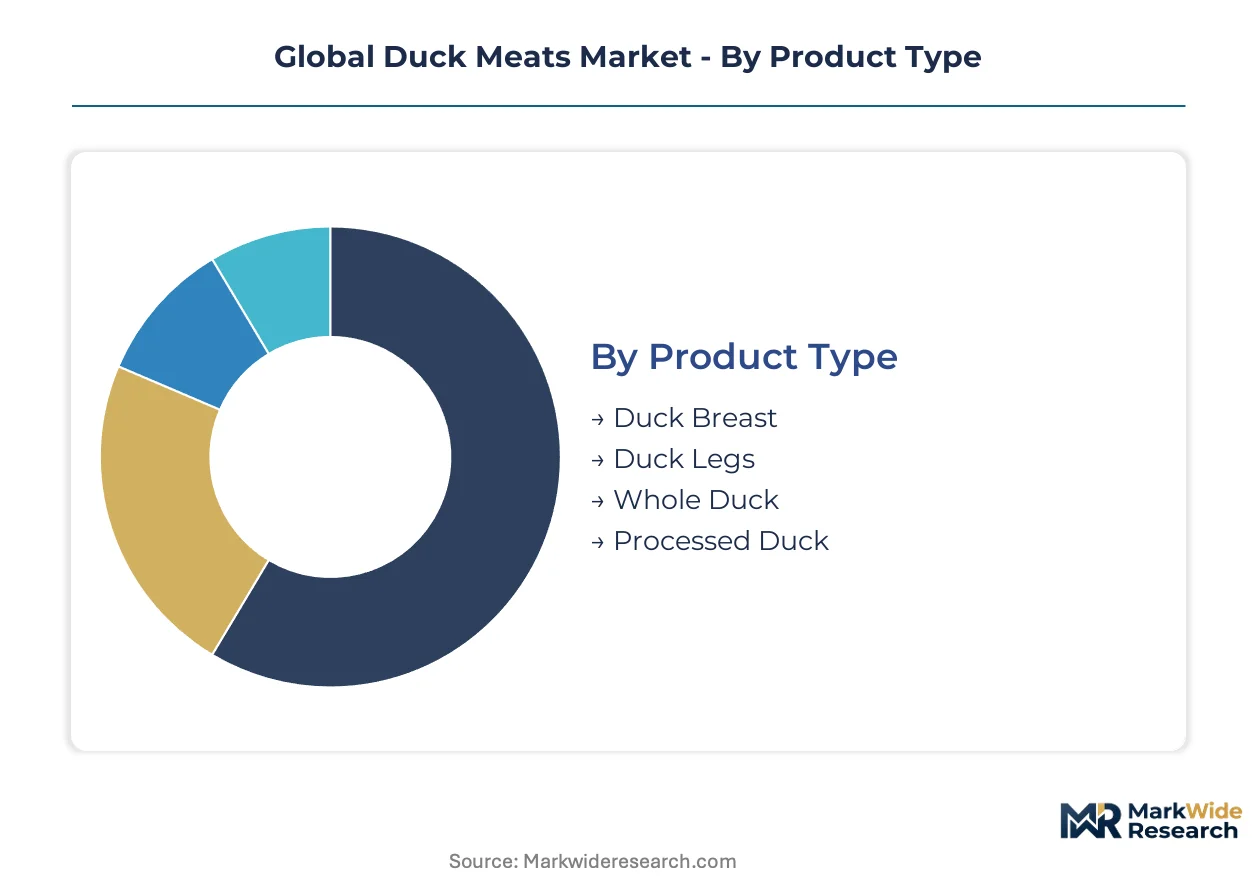
Product differentiation across the Global Duck Meats Market follows distinct specification axes that determine margin capture and channel access. Breed traceability, fat content profiles, and temperature-controlled handling requirements create tiered value pools that processors must align with buyer procurement standards.
Product Type:
Specification intensity varies by anatomical cut, with myoglobin density and fat distribution dictating processing protocols and shelf-life parameters.
- Whole Duck:Carcass integrity demands precise evisceration and rapid chilling to preserve skin quality for roasting applications. French and Chinese specialty foodservice channels absorb the dominant volume, where breed certification and cold-chain documentation command premium placement.
- Duck Breast:Magret cuts with higher myoglobin concentration require controlled-atmosphere packaging to prevent oxidative discoloration. UK retailers and North American foodservice accounts concentrate procurement around fresh-never-frozen specifications with blockchain-enabled batch tracking.
- Duck Legs:Confit-ready subcuts with higher collagen content suit slow-cooking formats in European institutional kitchens.
- Processed Duck:Marinated and pre-cooked formats reduce labor inputs in Asian convenience channels where kitchen staffing constraints intensify.
Mature deployment sits with Whole Duck. Newer deployment is concentrated in Processed Duck.
Distribution Channel:
Channel selection determines compliance burden and margin structure, with cold-chain liability shifting at each transfer point.
- Food Service:Direct procurement from vertically integrated suppliers eliminates intermediary handling, preserving temperature integrity for high-volume restaurant and hotel accounts in France and China's Yangtze River Delta. EFSA and SAMR documentation requirements filter supplier eligibility.
- Supermarkets:Controlled-atmosphere packaging and REACH-compliant barrier films enable fresh duck placement in German and French retail, where organic and free-range grades attract disproportionate shelf-space investment.
- Specialty Stores:Heritage breed positioning and breed-specific provenance claims support premium pricing in UK and French gourmet retail.
- Online Retailers:Subscription cold-chain logistics models consolidate institutional procurement in North America, with temperature-guaranteed delivery anchoring vendor selection.
Volume concentrates in Food Service. Margin expansion runs fastest in Online Retailers.
End User:
User type dictates specification stringency, with commercial kitchens demanding batch-level traceability absent from household procurement.
- Restaurants:Specialty foodservice accounts in France and China require consistent breed traceability and dual-carbon-aligned logistics documentation, consolidating procurement around vertically integrated suppliers with captive breeding programs.
- Hotels:Banquet and room-service operations in China's Yangtze River Delta specify pre-portioned cuts with just-in-time delivery models that reduce inventory carrying costs.
- Households:Retail purchase patterns in UK and German supermarkets favor whole bird formats for home roasting occasions.
- Caterers:Volume-scale procurement emphasizes yield optimization and standardized portion control for event-service applications.
Procurement consolidation centers on Restaurants. Emerging specification intensity characterizes Hotels.
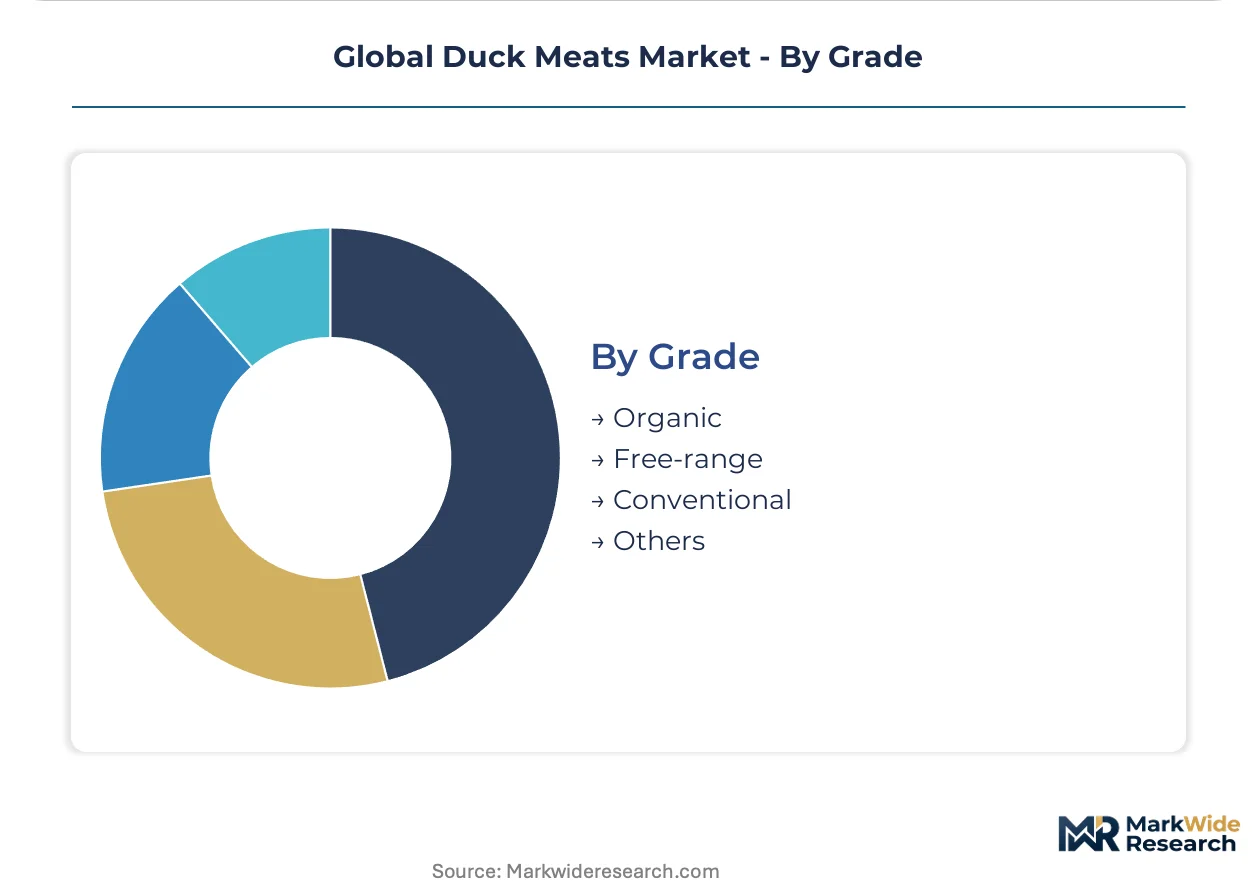
Grade:
Certification tier determines regulatory exposure and packaging compliance burden, with organic and free-range grades facing the tightest sustainability validation windows.
- Organic:Feed-source verification and antibiotic-free protocols align with EU Green Deal circularity mandates and REACH packaging rules, opening disproportionate shelf-space investment in German and French retail channels where buyer profiles demand simultaneous sustainability certification.
- Free-range:Outdoor access documentation and stocking density limits satisfy EFSA welfare criteria, supporting premium positioning in UK supermarkets.
- Conventional:Standard production protocols retain volume leadership across global foodservice procurement, with USDA and FDA HACCP compliance governing US export eligibility.
- Others:Heritage breed and regional designation grades serve niche gourmet channels with limited scale.
Volume leadership rests with Conventional. Certification-driven expansion characterizes Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta foodservice clusters absorb premium duck volumes through vertically integrated cold-chain networks that connect Shanghai procurement hubs to certified breeding operations in Jiangsu and Zhejiang provinces.
China
Specialty restaurant groups in Shanghai and Hangzhou consolidate procurement around SAMR-certified suppliers with dual-carbon logistics documentation. GB standards enforcement tightens import eligibility for foreign processors while redirecting institutional demand toward domestic cold-chain operators. Breeding and processing capacity concentrates in Jiangsu province's Nantong corridor.
France
Brittany's heritage duck producers supply Parisian fine-dining channels through EFSA-compliant facilities with breed-traceability systems. EU Green Deal circularity mandates accelerate packaging transitions toward compostable barrier films. Rennes and Nantes processing clusters anchor export capacity for UK and German retail.
United States
North American foodservice accounts consolidate vendor selection around USDA-graded suppliers with HACCP-verified cold-chain guarantees. FDA residue protocols filter import eligibility while domestic hatchery-to-delivery traceability becomes standard for large restaurant groups. Processing gravity sits with Indiana and California operations.
United Kingdom
Controlled-atmosphere packaging adoption extends fresh duck shelf life for Tesco and Waitrose placement, where organic and free-range grades attract disproportionate investment. EFSA welfare criteria and REACH packaging rules shape supplier compliance windows. East Anglia breeding operations feed retail-ready processing in Suffolk.
Thailand
Charoen Pokphand Foods anchors Southeast Asian production through integrated feed-to-table operations serving domestic foodservice and regional export. Feed input volatility from soybean and grain price swings compresses margins for integrated operators. Processing clusters concentrate in Bangkok's peripheral industrial zones.
Global Duck Meats Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated feed-to-table operators hold volume leadership while specialty breeders capture premium margins. Market concentration favors vertically integrated players with captive cold-chain assets and multi-jurisdictional compliance certification. Three archetypes dominate: heritage breed specialists, scale-driven integrated processors, and regional cold-chain logistics operators. Competitive dynamics center on facility upgrade cycles for EFSA and SAMR eligibility, plus strategic partnerships with institutional foodservice procurement teams.
Among Southeast Asian integrated processors, Charoen Pokphand Foods exemplifies the feed-to-table archetype through captive supply chain control. North American vertically integrated operators include Maple Leaf Farms, which occupies a position spanning hatchery operations through foodservice distribution. UK heritage positioning is represented by Gressingham Foods, sitting within the premium retail channel specialist tier.
| Leading Market Players |
|---|
| Charoen Pokphand Foods |
| AJC International |
| Maple Leaf Farms |
| Luv-a-Duck |
| Gressingham Foods |
| Culver Duck Farms |
| Joe Jurgielewicz & Son |
| Pepe's Ducks |
| New Hope Liuhe |
| Others |
Supply Flow & Price Mechanics
Organic-freegrade-conventional certification divergence bifurcates the Global Duck Meats Market into parallel pricing and sourcing tracks, with EU Green Deal compliance costs and SAMR cold-chain mandates reshaping procurement economics for premium tiers while commodity foodservice volumes anchor spot-market dynamics.
Pricing Analysis
Margin tightening in heritage-grade segments reflects REACH packaging compliance and controlled-atmosphere technology investments, while conventional volumes trade on feed-input spot markets. Three-tier pricing structure across organic, free-range, and conventional levels separates EFSA-certified suppliers from commodity processors. Cost-down pressure on Southeast Asian integrated operators accelerates because soybean and grain price volatility compresses feed-to-table margins. Quick-service restaurant procurement teams in China's Yangtze River Delta exhibit highest price sensitivity, whereas Parisian fine-dining accounts absorb premium markups for breed-traceable magret cuts.
Supply Chain Analysis
Domestic-content rules in China's GB standards enforcement are redirecting institutional procurement toward Jiangsu and Zhejiang breeding corridors, displacing import-reliant assembly models. Production gravity sits with France's Brittany region, China's Yangtze River Delta, and Thailand's Bangkok periphery. Raw material flows draw from soybean crushing capacity in Argentina, specialized duck feed formulations, and compostable barrier film suppliers. Single-source vulnerability concentrates in cold-chain logistics nodes serving Shanghai procurement hubs. Distribution runs through vertically integrated hatchery-to-delivery networks that bypass intermediary handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere packaging technology is displacing conventional modified-atmosphere systems, compressing shelf-life extension timelines from weeks to months and forcing facility upgrade cycles across European and North American processing clusters.
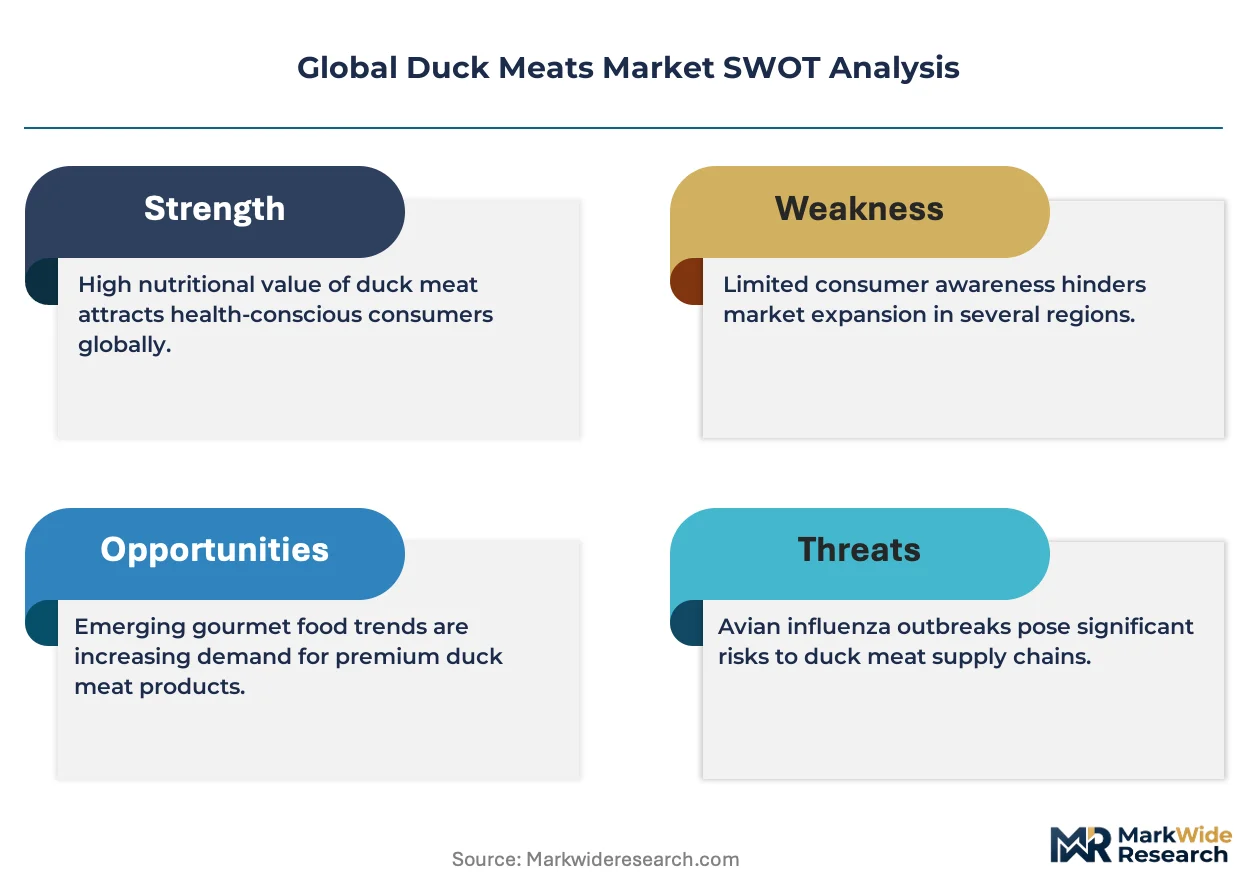
For Market Incumbents: To counter substitute protein encroachment in European retail, anchor premium positioning through EFSA welfare certification and captive breeding program documentation. Prioritize backward integration into compostable barrier film supply to satisfy EU Green Deal circularity mandates ahead of compliance windows. Lock in long-term offtake agreements with Yangtze River Delta restaurant groups to secure volume visibility against domestic Chinese processor expansion. For New Entrants and Emerging Players: Direct-to-foodservice subscription models offer the lowest barrier entry path, particularly for temperature-guaranteed delivery capabilities targeting North American institutional buyers underserved by legacy distributors. White-space concentration sits with marinated pre-cooked formats for Asian convenience channels where kitchen labor constraints intensify. Pursue private-label partnerships with UK supermarket chains seeking controlled-atmosphere packaged duck breast alternatives to incumbent heritage suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap processors given EFSA and SAMR eligibility upgrade cycles filtering sub-scale competitors from premium channel access. Long-term viability frames around 5-10 year cold-chain infrastructure deployment windows. Target acquisition archetypes combine captive breeding assets with blockchain-enabled traceability systems. Monitor antibiotic residue threshold convergence between USDA, EFSA, and SAMR jurisdictions as inflection signal for export-oriented processor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Temperature-guaranteed delivery capabilities unlock Yangtze River Delta and Brittany premium foodservice procurement consolidation. |
| Heritage Breed Certification Program | EFSA-compliant breed traceability systems differentiate Parisian fine-dining supply against commodity duck processors. |
| Controlled-Atmosphere Packaging Scale-Up | Modified gas composition technology extends fresh duck shelf life for Tesco and Waitrose placement without freezing. |
| Backward Integration into Feed Supply | Captive soybean and grain sourcing insulates Southeast Asian operations from commodity price volatility compressing margins. |
| Blockchain Traceability Implementation | Batch-level documentation satisfies Shanghai restaurant group procurement requirements for dual-carbon-aligned logistics verification. |
Methodological Framework
Multi-period observation of cold-chain infrastructure deployment, regulatory compliance upgrade cycles, and breed-specialization capacity additions anchored the trend analysis, supplemented by interviews with duck processing plant managers, EFSA food safety auditors, SAMR certification specialists, and procurement directors at Yangtze River Delta restaurant groups. Secondary validation drew from customs trade records, EFSA microbiological criteria updates, SAMR GB standards filings, and REACH packaging rule amendments. Bottom-up facility capacity tallies triangulated against top-down foodservice procurement spend estimates.
Segment-weighting across product type, distribution channel, end user, and grade certification dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression against protein substitution elasticities, cold-chain penetration curves, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated feed-input price volatility indices and dual-carbon logistics adoption rates in Chinese institutional procurement.
The model holds under stable regulatory enforcement trajectories and intact cold-chain infrastructure investment schedules; deviation in antibiotic residue threshold divergence or soybean supply disruption would shift volume and value outputs. Forecasts reflect documented assumptions regarding EFSA and SAMR eligibility filtration rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Middle East Edible Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Pork Meat Market
Meat Products
Organic Chicken Market
Meat Products
Vegan Meatball Market
Meat Products
Beef Extract Market
Meat Products
Europe Bacon Market
Meat Products
Beef Bone Broth Market
Meat Products
Meat Tenderizer Market
Meat Products
Low-Fat Chorizo Market
Meat Products
United States Frozen Meat Market
Meat Products
Global Red Meat Market
Meat Products
Beef Bouillon Market
Meat Products
United States Animal Protein Market