
 Pancytopenia Market | 2026-2036
Pancytopenia Market Size, Share, and Industry Trends Forecast 2026-2036
Pancytopenia Market Analytics
High-efficacy biologic-grade treatment standards is collapsing the gap between first-line supportive care and curative interventions. F. Hoffmann-La Roche leverages its hematology portfolio depth to sustain leadership in growth factor development. Amgen anchors its competitive position through in-house production of recombinant proteins. Novartis differentiates via channel control across specialty clinic networks.
Pancytopenia denotes a hematologic condition characterized by simultaneous deficiency of erythrocytes, leukocytes, and platelets below standard clinical thresholds, typically confirmed through bone marrow aspiration showing hypocellular marrow with fatty replacement. The condition serves as both a diagnostic endpoint for marrow failure syndromes and a therapeutic target requiring multimodal blood component restoration. Pharmacological interventions occupy the largest revenue pool given chronic administration requirements across aplastic anemia and myelodysplastic syndrome patient cohorts. Stem cell transplantation represents the fastest-growing treatment type as haploidentical matching protocols expand donor availability. Hospital end users dominate procedure volume while oncology centers capture premium-margin complex cases requiring combined immunotherapy protocols.
FDA orphan drug incentives and EMA's Committee for Orphan Medicinal Products shape clinical trial investment and market exclusivity timelines for pancytopenia-targeted therapies. The EU MDR and FDA's cGMP standards enforce manufacturing rigor for blood-derived and recombinant biologic products, directly influencing production cost structures and facility certification requirements. Stakeholders must monitor evolving reimbursement pathways for stem cell transplantation as health technology assessment bodies in Germany and Japan recalibrate cost-effectiveness thresholds for curative versus chronic management approaches.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while simultaneously accelerating adoption of high-efficacy biologic therapies for marrow failure syndromes.
Growth Catalysts
- FDA Orphan Drug Designation:The incentive structure accelerates clinical trial investment for pancytopenia-targeted therapies by granting market exclusivity extensions and tax credits for qualified sponsors.
- Haploidentical Stem Cell Protocols:Expanded donor matching availability is supplanting traditional HLA-identical requirements, broadening curative intervention access across previously excluded patient cohorts.
- Germany:Health technology assessment recalibration by the Federal Joint Committee is reshaping reimbursement pathways for stem cell transplantation versus chronic management.
Market Restraints
- Recombinant Protein Production Costs:Mammalian cell culture infrastructure requirements and cGMP certification timelines inflate manufacturing overhead for growth factor therapies.
- EU MDR Compliance Burden:The Medical Device Regulation's enhanced clinical evidence requirements extend certification timelines for blood-derived biologic products by 18-24 months.
- Allogeneic Transplant Substitution:Gene therapy vectors for inherited marrow failure syndromes threaten long-term demand for pharmacological pancytopenia management.
Strategic Opportunities
- Japan:Underpenetrated haploidentical transplant protocols present white space for protocol licensing and center certification programs.
- Home-Based Growth Factor Administration:Subcutaneous delivery device innovation enables channel shift from infusion centers to patient self-management.
- IRA Price Negotiation Exclusions:Orphan-designated therapies for conditions affecting under 200,000 patients retain protected pricing status through 2031.
Industry Challenges
- Hematopathologist Workforce Scarcity:Specialized marrow interpretation expertise concentrates at academic medical centers, creating diagnostic bottleneck.
- Biorepository Cold Chain Integrity:Stem cell product viability demands continuous cryogenic monitoring across multi-node logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancytopenia Market |
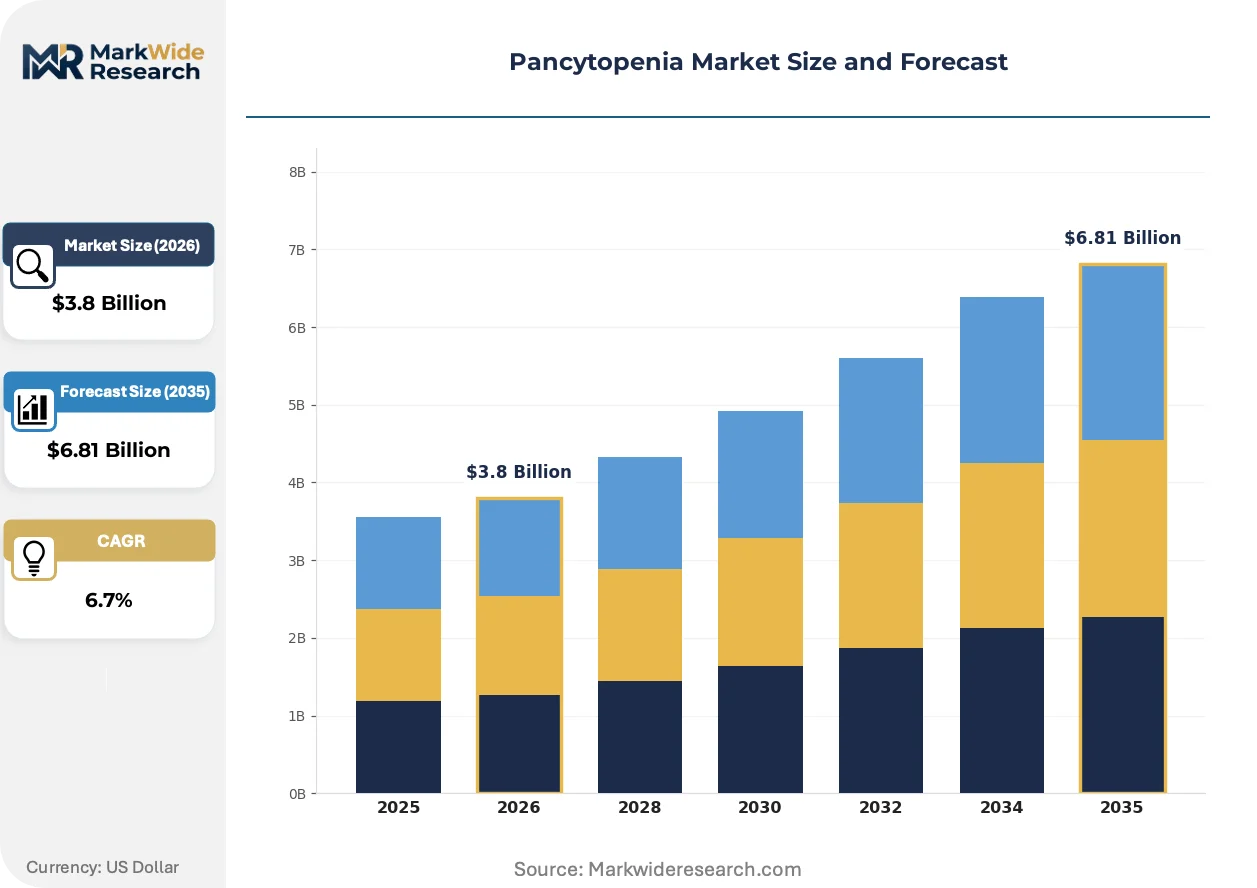
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bone Marrow Biopsies, Blood Transfusions, Growth Factors, Immunosuppressants End User: Hospitals, Oncology Centers, Diagnostic Labs, Specialty Clinics Treatment Type: Pharmacological Interventions, Stem Cell Transplantation, Immunotherapy, Supportive Care Indication: Aplastic Anemia, Myelodysplastic Syndromes, Leukemias, Hemolytic Disorders |
| Companies Covered | F. Hoffmann-La Roche, GSK, Sanofi, Novartis, Merck & Co., Pfizer, Bristol-Myers Squibb, Amgen, Regeneron Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancytopenia Market Evolving Landscape
Next-generation sequencing integration is collapsing diagnostic latency while synthetic biology advances are compressing recombinant protein production cycles.
CRISPR-based ex vivo stem cell editing is supplanting traditional immunosuppressive conditioning regimens for severe aplastic anemia. Academic medical centers in the United States and Germany are piloting these protocols through FDA and EMA expanded access pathways. The structural consequence is a compression in lifetime treatment cost curves as single-intervention curative potential displaces chronic pharmacological dependency.
EMA's Committee for Orphan Medicinal Products has streamlined parallel scientific advice procedures with FDA, reducing protocol amendment cycles for multinational pancytopenia trials. Sponsors now receive consolidated feedback on primary endpoint selection within 90 days versus historical 180-day sequential reviews. The hematologic malignancy segment has responded by consolidating phase I/II trial execution at EU-US dual-compliant sites in Switzerland and the Netherlands.
Oncology centers are unbundling after-transplant care from procedure billing, creating discrete service lines for graft-versus-host disease management. This procurement model evolution displaces comprehensive bundled reimbursement with episode-based contracting. The United States exhibits the most pronounced shift, with Medicare Advantage plans in Florida and Texas piloting 90-day post-transplant accountability structures.
Pancytopenia Market Segmentation
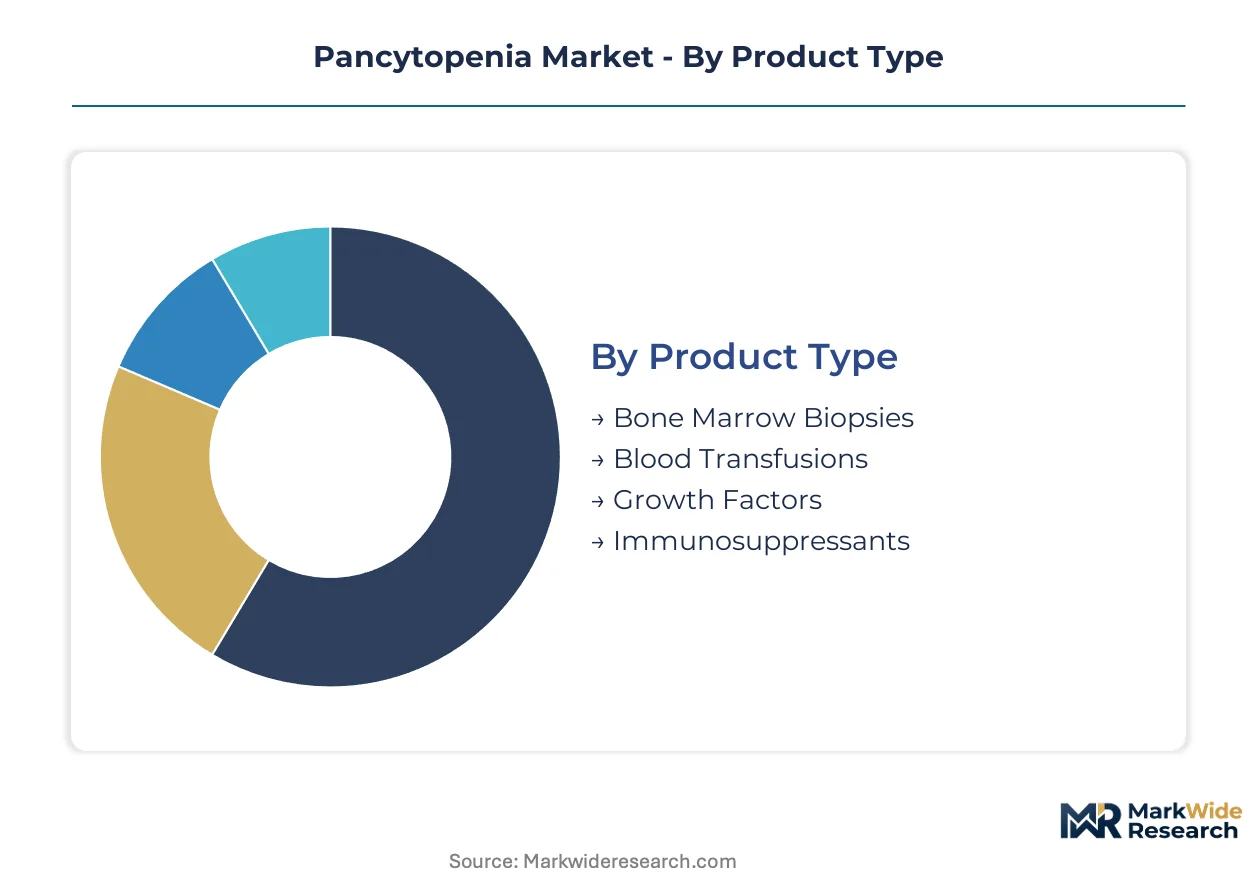
Segmentation in pancytopenia care reveals how diagnostic, therapeutic, and procedural components distribute across institutional settings and clinical pathways. Each category exposes distinct procurement patterns, reimbursement dependencies, and technology adoption curves that shape vendor strategy and investment allocation.
Product Type:
Domestic manufacturing concentrates growth factor and immunosuppressant production in the United States and Germany, while blood transfusion products flow through regional blood banking networks with limited cross-border trade.
- Growth Factors:Recombinant erythropoietin and granulocyte colony-stimulating factor preparations require mammalian cell culture infrastructure under FDA and EMA cGMP standards. Hospital formularies in the United States and Japan concentrate demand for pegylated formulations with extended half-life profiles.
- Immunosuppressants:Calcineurin inhibitors and anti-thymocyte globulin regimens target T-cell mediated marrow suppression. German and French transplant centers drive volume for conditioning protocols ahead of allogeneic stem cell procedures.
- Bone Marrow Biopsies:Disposable needle systems and aspiration kits flow through specialty distributor networks to academic medical centers.
- Blood Transfusions:Irradiated and CMV-negative component specifications dominate oncology center procurement in Japan and the United States.
Growth factors command the established base. The steepest expansion runs through immunosuppressants as conditioning intensity escalates.
End User:
Cost tier stratification separates high-complexity curative procedures at premium-margin facilities from chronic management delivered through standardized reimbursement channels.
- Hospitals:General medical centers handle emergency pancytopenia presentations and transfusion-dependent stabilization. Volume concentrates in Medicare-dependent systems across Texas and Florida where sepsis protocols trigger rapid hematology consultation.
- Oncology Centers:Comprehensive cancer institutes manage combined modality therapy requiring simultaneous chemotherapy and growth factor support. German university hospitals and Japanese national cancer centers capture the most complex myelodysplastic syndrome cases.
- Specialty Clinics:Dedicated marrow failure centers coordinate transplant evaluation and long-term immunosuppression monitoring.
- Diagnostic Labs:Reference laboratories perform flow cytometry and cytogenetic analysis for clonal evolution assessment.
Hospitals anchor procedure volume. Oncology centers gain share fastest as care migrates toward centralized expertise.
Treatment Type:
Application urgency distinguishes acute life-sustaining interventions from elective curative procedures with extended preparation timelines.
- Pharmacological Interventions:Chronic administration of growth factors, immunosuppressants, and antimicrobials constitutes the dominant revenue pool. Patient registries in Germany and Japan track long-term thrombopoietin agonist exposure in myelodysplastic syndromes.
- Stem Cell Transplantation:Allogeneic and autologous procedures offer curative potential for severe aplastic anemia and select leukemias. Haploidentical protocol adoption is expanding fastest at United States academic centers with dedicated transplant units.
- Immunotherapy:Checkpoint inhibitors and CAR-T cell therapies address immune-mediated marrow failure in specialized protocols.
- Supportive Care:Transfusion, infection prophylaxis, and nutritional support underlie all active treatment phases.
Pharmacological interventions retain the largest revenue footprint. Stem cell transplantation shows the steepest volume trajectory as donor matching barriers fall.
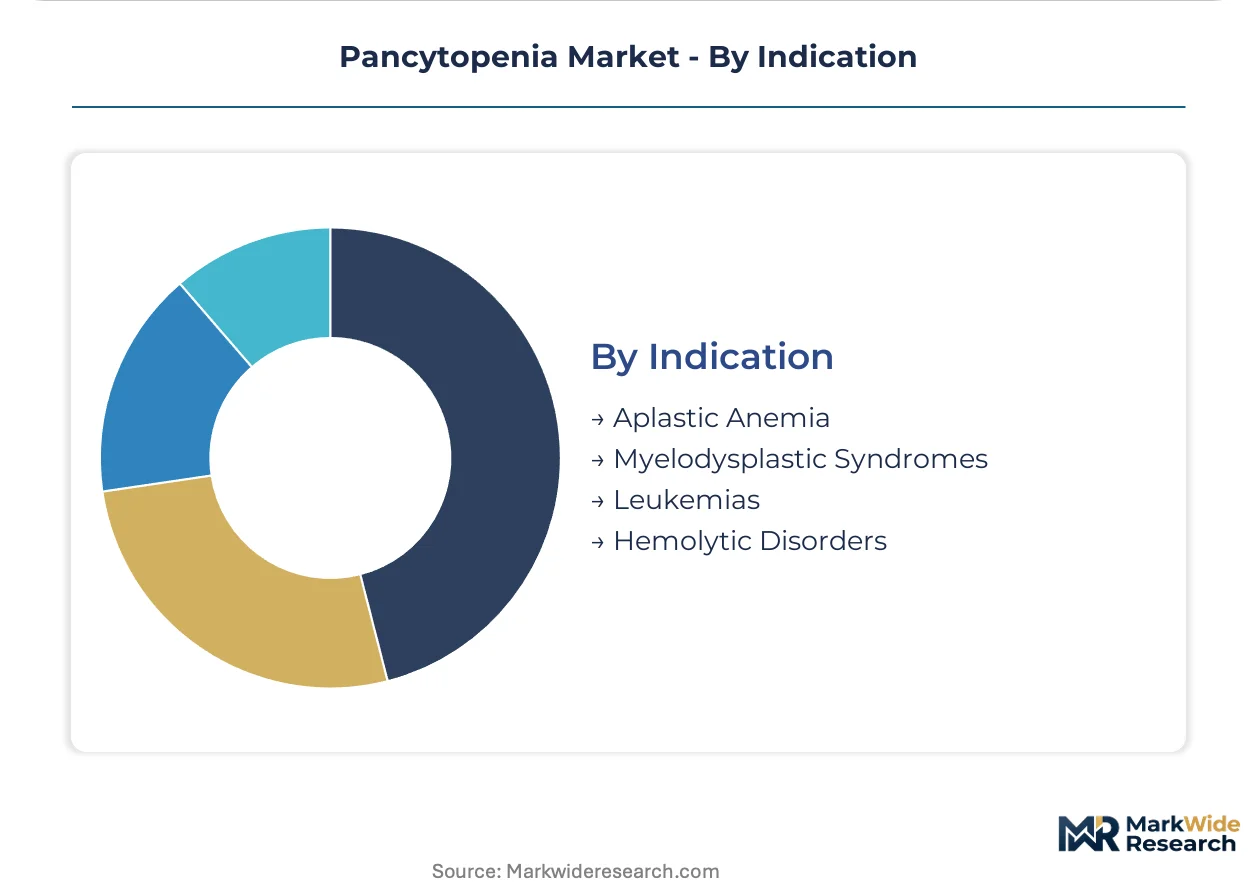
Indication:
Customer type segmentation separates transplant-eligible candidates from chronically managed populations with divergent lifetime value profiles.
- Aplastic Anemia:Immune-mediated bone marrow failure in younger patients drives immunosuppressive therapy and transplant evaluation. German and Japanese referral networks concentrate severe case volume at designated excellence centers.
- Myelodysplastic Syndromes:Clonal hematopoietic disorders in older adults require risk-stratified therapy ranging from supportive care to hypomethylating agents. United States Medicare spending patterns reflect prolonged transfusion dependency in lower-risk categories.
- Leukemias:Chemotherapy-induced pancytopenia demands intensive growth factor and transfusion support during induction.
- Hemolytic Disorders:Paroxysmal nocturnal hemoglobinuria and related conditions require complement inhibition alongside marrow support.
Myelodysplastic syndromes generate the largest chronic revenue base. Aplastic anemia offers the most concentrated curative procedure opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade in biologic-grade growth factors and stem cell transplant services tilts toward import dependency in Japan and surplus capacity in Germany. Currency-adjusted procurement costs diverge sharply across national reimbursement systems.
United States
Medicare Advantage pilots in Florida and Texas drive episode-based contracting for post-transplant care. FDA orphan drug incentives compress trial timelines for pancytopenia-targeted therapies. Academic medical centers in Boston and Houston concentrate haploidentical protocol development.
Germany
Federal Joint Committee recalibration of cost-effectiveness thresholds shifts reimbursement toward curative interventions. EMA parallel scientific advice with FDA accelerates multinational trial execution. University hospitals in Heidelberg and Munich anchor marrow failure excellence networks.
Japan
PMDA streamlined review pathways for regenerative medicines expand stem cell product availability. National cancer centers in Tokyo and Osaka capture complex myelodysplastic syndrome volumes. Underpenetrated haploidentical protocols present licensing opportunities for foreign protocol developers.
Switzerland
Swissmedic dual-compliant trial sites attract EU-US consolidated phase I/II execution. Basel and Zurich clusters host hematology-focused contract research organizations. Re-export of certified biologics to EU member states leverages bilateral mutual recognition agreements.
United Kingdom
NHS England specialized commissioning for rare diseases concentrates severe aplastic anemia referrals at designated centers. MHRA post-Brexit divergence from EMA creates parallel submission requirements for growth factor approvals. London and Manchester academic centers lead CAR-T conditioning protocol trials.
Pancytopenia Market Competitive Landscape
Concentration sits with diversified biopharmaceutical conglomerates controlling mammalian cell culture infrastructure and hematology portfolio depth. Three to five multinational firms capture the majority of growth factor and immunosuppressant revenue. Strategic archetypes include integrated recombinant protein manufacturers, specialty hematology franchise holders, and transplant service consolidators. Competitive moves center on in-house production capacity expansion and specialty clinic network acquisition.
Among Swiss and German pharmaceutical conglomerates, F. Hoffmann-La Roche and Novartis occupy positions reflecting hematology portfolio breadth. Amgen represents the recombinant protein manufacturing archetype with captive biologic production infrastructure. These three firms exemplify distinct competitive positioning around channel control, manufacturing integration, and therapeutic franchise depth.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| GSK |
| Sanofi |
| Novartis |
| Merck & Co. |
| Pfizer |
| Bristol-Myers Squibb |
| Amgen |
| Regeneron Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Synthetic biology-derived growth factor production is displacing traditional mammalian cell culture methods, simultaneously shifting manufacturing geography toward United States and German biotech clusters while compressing unit economics for recombinant erythropoietin and granulocyte colony-stimulating factor therapies.
Pricing Analysis
Hospital procurement managers anchor pricing negotiations through consolidated formulary contracts. Three-tier pricing structure across premium pegylated formulations, standard recombinant proteins, and economy-tier biosimilars reflects FDA and EMA certification stratification. Cost compression in the biosimilar tier is intensifying because of IRA price negotiation exclusions for orphan-designated therapies. Oncology centers exhibit the lowest price sensitivity due to bundled reimbursement protocols, while general hospitals face acute budget constraints from Medicare sepsis protocol triggers.
Supply Chain Analysis
Just-in-time inventory management dominates growth factor distribution, though stem cell biorepositories maintain strategic cryogenic stockpiles for transplant scheduling flexibility. Manufacturing concentrates in the United States, Germany, and Switzerland under FDA and EMA cGMP standards. Production draws from recombinant DNA platforms, mammalian cell culture media, and specialized cold-chain logistics infrastructure. Single-source vulnerability concentrates in cryogenic transport providers for stem cell viability. Distribution runs through specialty hematology distributors to hospital formularies and oncology center pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pancytopenia market sits in early-cycle expansion as haploidentical stem cell protocols broaden curative intervention access beyond traditional HLA-matched donor limitations, creating new addressable patient cohorts previously excluded from transplant eligibility.
For Market Incumbents: Consolidate manufacturing scale through in-house mammalian cell culture capacity expansion in Basel and Boston clusters. Lock in channel control via long-term oncology center partnership agreements before gene therapy vectors mature as allogeneic transplant substitutes. Prioritize FDA and EMA parallel scientific advice submissions to compress multinational trial timelines.
For New Entrants and Emerging Players: Differentiate on subcutaneous delivery device innovation for home-based growth factor administration. Target Japan's underpenetrated haploidentical transplant protocol licensing market. Pursue center certification partnerships with Tokyo and Osaka academic medical centers as the most penetrable geographic entry point.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty hematology franchise holders lacking recombinant protein manufacturing infrastructure. Five-to-ten year viability hinges on curative versus chronic management substitution curves. Watch FDA expanded access pathway approvals for CRISPR-edited stem cell protocols as the inflection signal for gene therapy displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA and EMA incentives compress trial timelines and secure market exclusivity extensions for qualified pancytopenia therapies. |
| Haploidentical Protocol Licensing | Japan's underpenetrated transplant networks offer first-mover advantage for foreign protocol developers seeking center certification partnerships. |
| Subcutaneous Delivery Device Development | Home-based growth factor administration enables channel shift from infusion centers to patient self-management and reimbursement capture. |
| Dual-Compliant Trial Site Consolidation | Swissmedic-certified facilities in Switzerland attract EU-US parallel phase I/II execution for accelerated regulatory pathways. |
| Specialty Clinic Network Acquisition | Oncology center control secures premium-margin complex case volumes requiring combined immunotherapy and transplant protocols. |
Research Methodology
Operator-level perspectives from hematology department heads, hospital formulary directors, stem cell transplant coordinators, and payer access specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov protocol registries, and German Federal Joint Committee reimbursement assessments. Bottom-up patient volume modeling and top-down revenue triangulation across treatment type and indication segments ensured cross-verification.
Sensitivity analysis tested forecast robustness across the projection horizon against regulatory approval delays and gene therapy substitution scenarios. Segmentation dimensions modeled include treatment type, product category, end-user facility tier, and regional regulatory cluster. CAGRs derived from procedure volume trajectories and pricing evolution assumptions specific to growth factor chronic administration versus stem cell transplantation curative intervention economics.
The analysis sits within stated boundaries; outcomes outside sustained orphan drug incentive structures and haploidentical protocol adoption curves would require recalibration. Forecasts reflect documented assumptions regarding reimbursement pathway stability and biologic manufacturing capacity expansion. Revision becomes warranted when gene therapy clinical readouts cross efficacy thresholds that trigger accelerated allogeneic transplant substitution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Global Hematologic Malignancies Treatment Market
Hematology
Global Hematology Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Follicular Lymphoma Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Malignant Lymphoma Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Febrile Neutropenia Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Blood Plasma Market
Hematology
Hemocytometer Market
Hematology
Multiple Myeloma Treatment Market