
 Myelodysplastic Syndrome (MDS) Treatment Market | 2026-2036
Myelodysplastic Syndrome (MDS) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Myelodysplastic Syndrome (MDS) Treatment Market Outlook
North American biopharmaceutical manufacturing is pivoting toward expanded fill-finish capacity for injectable hematology therapies. Bristol-Myers Squibb leverages its integrated oncology infrastructure to sustain azacitidine supply continuity across multiple continents. Novartis anchors its MDS portfolio through deep clinical trial networks in hematologic malignancies. Amgen competes on biosimilar and supportive care positioning within myeloid disorder treatment protocols.
Myelodysplastic Syndrome treatment encompasses therapeutic interventions targeting clonal hematopoietic stem cell disorders characterized by peripheral blood cytopenias, dysplasia in one or more myeloid lineages, and risk of progression to acute myeloid leukemia; these therapies function to modify disease trajectory, reduce transfusion dependence, and delay leukemic transformation. Hypomethylating agents occupy the dominant revenue position due to their established efficacy in higher-risk disease categories, while immunotherapies represent the fastest-expanding segment as checkpoint inhibitors and engineered cellular therapies advance through late-stage hematology pipelines. The intravenous administration route maintains the largest volume share, though subcutaneous delivery formats are gaining traction in outpatient clinic and homecare settings where patient convenience drives protocol selection.
The FDA maintains stringent chemistry, manufacturing, and controls requirements for MDS therapies through its Office of Oncologic Diseases, while the EMA's Committee for Medicinal Products for Human Use applies centralized hematology assessment pathways that standardize market access across EU member states. Japan's PMDA operates accelerated review frameworks for serious hematologic conditions, compressing evaluation timelines for therapies addressing unmet needs in myeloid malignancies. Stakeholders must monitor evolving biomarker-driven eligibility criteria across these regulatory systems, as companion diagnostic requirements increasingly determine reimbursement and prescribing pathways for novel MDS interventions.
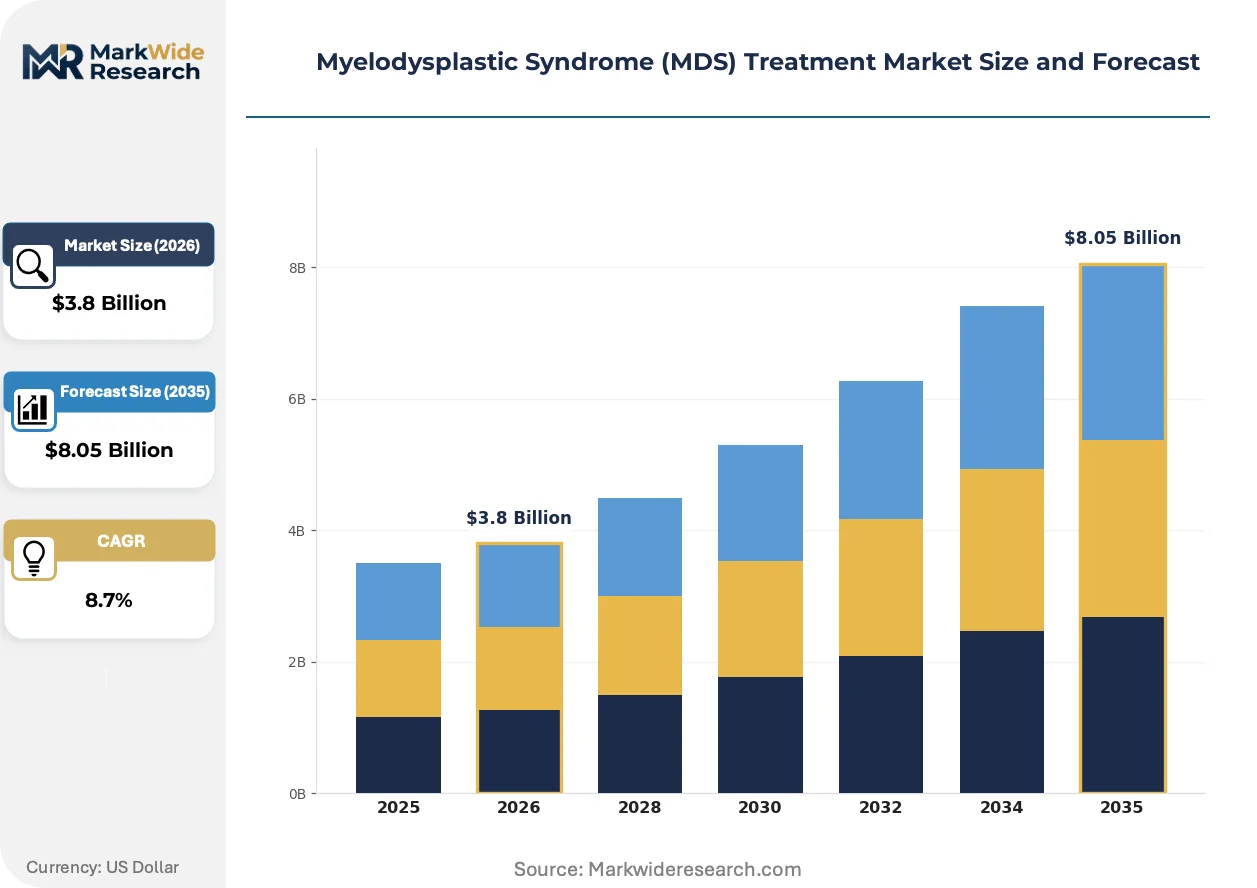
Market Dynamics
FDA's accelerated approval pathways for hematologic malignancies are compressing commercialization timelines and reshaping how developers prioritize MDS pipeline assets. This regulatory velocity is forcing sponsors to front-load manufacturing scale-up and biomarker validation investments.
Growth Catalysts
- Hypomethylating agent expansion:Hospital-based oncology departments are expanding adoption of combination protocols that pair azacitidine or decitabine with novel agents, driving protocol complexity and treatment duration.
- PMDA accelerated review frameworks:Japan's compressed evaluation timelines for serious hematologic conditions are attracting sponsors to prioritize Japanese market entry alongside US and EU filings.
- Injectable fill-finish capacity buildout:North American biopharmaceutical manufacturing investment in aseptic processing infrastructure is securing supply continuity for parenteral MDS therapies.
Market Restraints
- Companion diagnostic dependency:Evolving biomarker-driven eligibility criteria across FDA, EMA, and PMDA systems are fragmenting addressable patient populations and complicating trial design.
- Transfusion infrastructure concentration:Heavy reliance on specialized hematology centers in the United States, Germany, and Japan limits patient access in regions lacking blood banking and apheresis capabilities.
- High manufacturing complexity:Chemistry, manufacturing, and controls requirements for parenteral cytotoxics create capital intensity barriers that deter new entrants from building commercial-scale capacity.
Strategic Opportunities
- Subcutaneous delivery formats:Outpatient clinic and homecare settings are driving protocol selection toward patient-administered alternatives that reduce infusion chair time and facility overhead.
- EMA centralized hematology pathways:Standardized market access across EU member states creates predictable reimbursement timelines for sponsors able to navigate the Committee for Medicinal Products for Human Use process.
- Immunotherapy convergence:Checkpoint inhibitors and engineered cellular therapies advancing through late-stage pipelines represent whitespace beyond hypomethylating agent dominance in higher-risk disease.
Industry Challenges
- Hematopathology expertise scarcity:Accurate MDS diagnosis and risk stratification require specialized morphologic assessment and cytogenetic interpretation that outpaces training pipeline output.
- Legacy EHR integration friction:Electronic health record systems at community oncology practices lack structured fields for International Prognostic Scoring System data, complicating real-world evidence collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Myelodysplastic Syndrome (MDS) Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hypomethylating Agents, Chemotherapy, Growth Factors, Immunotherapies Administration Route: Intravenous, Subcutaneous, Oral, Topical End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Oncology, Hematology, Palliative Care, Supportive Care |
| Companies Covered | Bristol-Myers Squibb Company, Novartis International AG, Amgen Inc., Takeda Pharmaceutical Company Limited, Roche Holding AG, AbbVie Inc., Celgene Corporation, Otsuka Pharmaceutical Co., Ltd., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Myelodysplastic Syndrome (MDS) Treatment Market Strategic Shifts
Cellular engineering and biomarker-guided patient selection are converging to transform how clinicians sequence MDS interventions. These shifts are compressing the gap between diagnostic confirmation and targeted therapy initiation.
Chimeric antigen receptor T-cell platforms are unifying manufacturing and clinical workflows through centralized vein-to-vein logistics networks. Academic medical centers with FACT accreditation are adopting these models fastest. The technology is unifying previously fragmented apheresis, cryopreservation, and lymphodepletion scheduling into coordinated treatment calendars that reduce time-to-infusion.
EMA's centralized hematology assessment pathways are standardizing companion diagnostic requirements across EU member states. This harmonization reduces regulatory friction for sponsors but forces diagnostic manufacturers to prioritize CE-IVD certification timelines. High-risk MDS segments with TP53 or complex karyotype abnormalities are most affected, with laboratories scrambling to validate next-generation sequencing panels.
Site-of-care migration is redirecting hypomethylating agent administration from inpatient infusion suites to community oncology practices with pharmacy capabilities. Hospital-based departments are losing volume to ambulatory networks that offer more flexible scheduling. This displacement is most visible in United States metropolitan markets where Medicare reimbursement differentials favor outpatient administration.
Myelodysplastic Syndrome (MDS) Treatment Market Segmentation
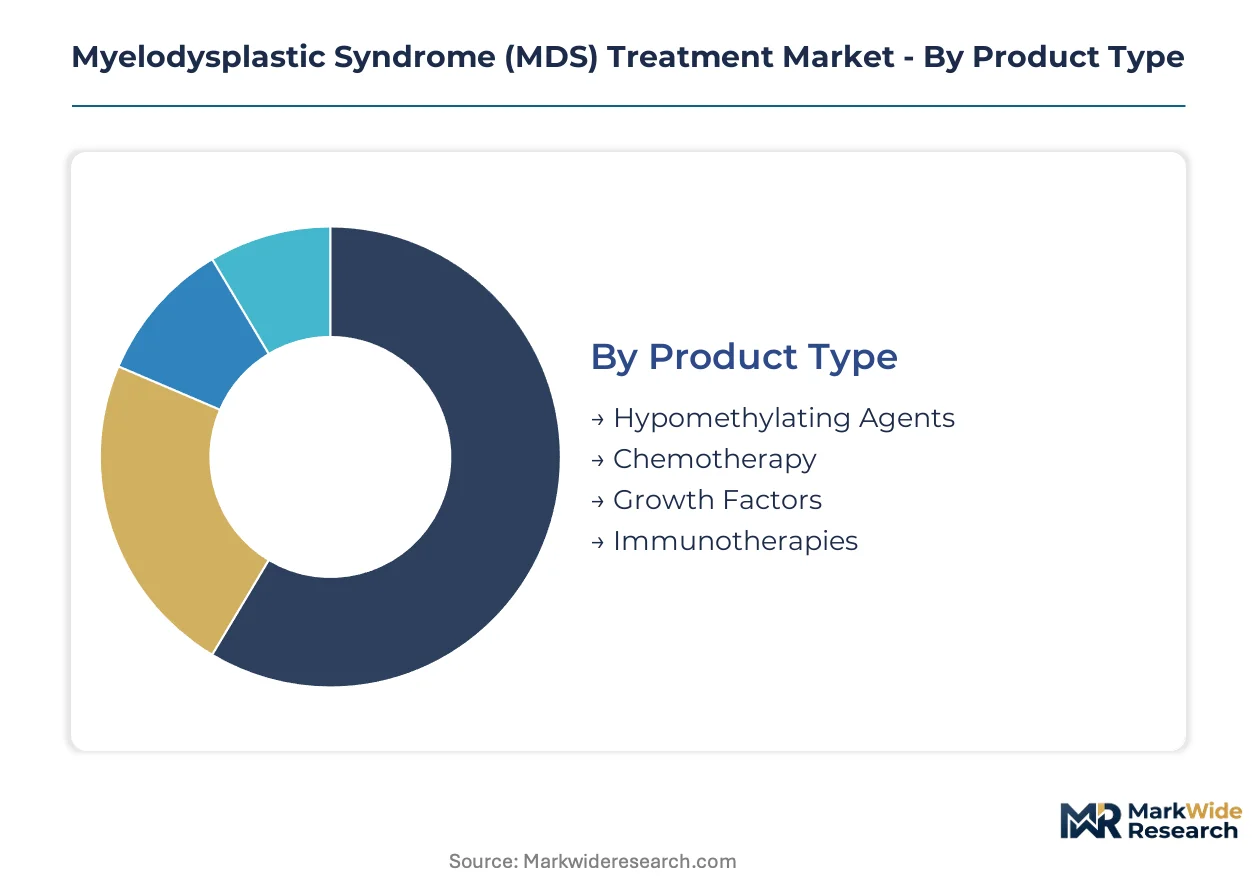
MDS treatment segmentation reveals how therapy delivery, clinical setting, and therapeutic mechanism intersect to determine patient access and commercial viability. Understanding these divides helps stakeholders identify where infrastructure investments and regulatory navigation yield the highest returns.
Product Type:
Hypomethylating agents function as standalone backbone therapies requiring specialized compounding infrastructure, while immunotherapies embed into combination protocols demanding biomarker screening capabilities.
- Hypomethylating Agents:Azacitidine and decitabine form the pharmacologic foundation through DNA methyltransferase inhibition, inducing cell cycle arrest and differentiation in malignant clones. Demand concentrates in tertiary hematology centers across the United States, Germany, and Japan where transfusion support and cytogenetic laboratories enable risk-stratified patient selection. These agents anchor combination protocols that extend treatment duration and protocol complexity.
- Immunotherapies:Checkpoint inhibitors and engineered cellular platforms target immune evasion mechanisms in higher-risk disease categories. Clinical trial networks at academic medical centers in Boston, Heidelberg, and Tokyo are driving investigational demand as sponsors evaluate sequencing strategies beyond hypomethylating failure. Manufacturing scale-up for autologous cellular products remains the binding constraint.
- Chemotherapy:Cytotoxic regimens retain role in transformation to acute myeloid leukemia, administered primarily in inpatient settings with intensive monitoring.
- Growth Factors:Erythropoiesis-stimulating agents and granulocyte colony-stimulating factors address cytopenia complications in lower-risk categories.
Hypomethylating agents lead volumes today; immunotherapies are climbing the fastest.
Administration Route:
Route selection tracks site-of-care migration, with intravenous formats tied to facility-based infrastructure and alternative routes enabling decentralized delivery.
- Intravenous:Parenteral infusion remains the dominant delivery format for hypomethylating agents and cytotoxic chemotherapy, requiring infusion chair capacity and nursing oversight. Hospital-based oncology departments and dedicated hematology centers in the United States maintain the highest throughput, though Medicare reimbursement differentials are accelerating volume shift toward community-based ambulatory networks.
- Subcutaneous:Self-administered injection formats reduce facility dependency and enable homecare protocols. Outpatient clinics in German metropolitan markets are adopting subcutaneous azacitidine to optimize scheduling efficiency and reduce overhead. Patient training programs and refrigeration logistics determine adoption velocity.
- Oral:Decitabine-cedazuridine fixed-dose combinations and investigational hypomethylating formulations target convenience-driven protocols.
- Topical:Limited application for cutaneous manifestations in rare MDS subtypes with extramedullary disease.
Intravenous administration retains the largest volume share; subcutaneous delivery is expanding most quickly.
End User:
End-user segmentation maps to acuity levels and reimbursement structures, with high-complexity cases concentrating in institutional settings and stable patients shifting to lower-cost environments.
- Hospitals:Inpatient hematology units manage high-risk MDS, transformation to acute myeloid leukemia, and complications requiring transfusion support. Academic medical centers with FACT accreditation dominate cellular therapy administration. Japanese designated cancer hospitals and German university hospitals anchor regional referral networks.
- Clinics:Community oncology practices with pharmacy capabilities are capturing hypomethylating agent volume through 340B pricing advantages and flexible scheduling. United States metropolitan markets show the most pronounced site-of-care displacement.
- Homecare:Subcutaneous administration and oral formulations enable patient-managed therapy, supported by specialty pharmacy nursing services.
- Pharmacies:Retail and specialty pharmacy channels handle oral supportive care agents and limited distribution drugs under risk evaluation and mitigation strategies.
Hospitals anchor high-acuity case volumes; clinics are capturing the fastest share growth in stable disease management.
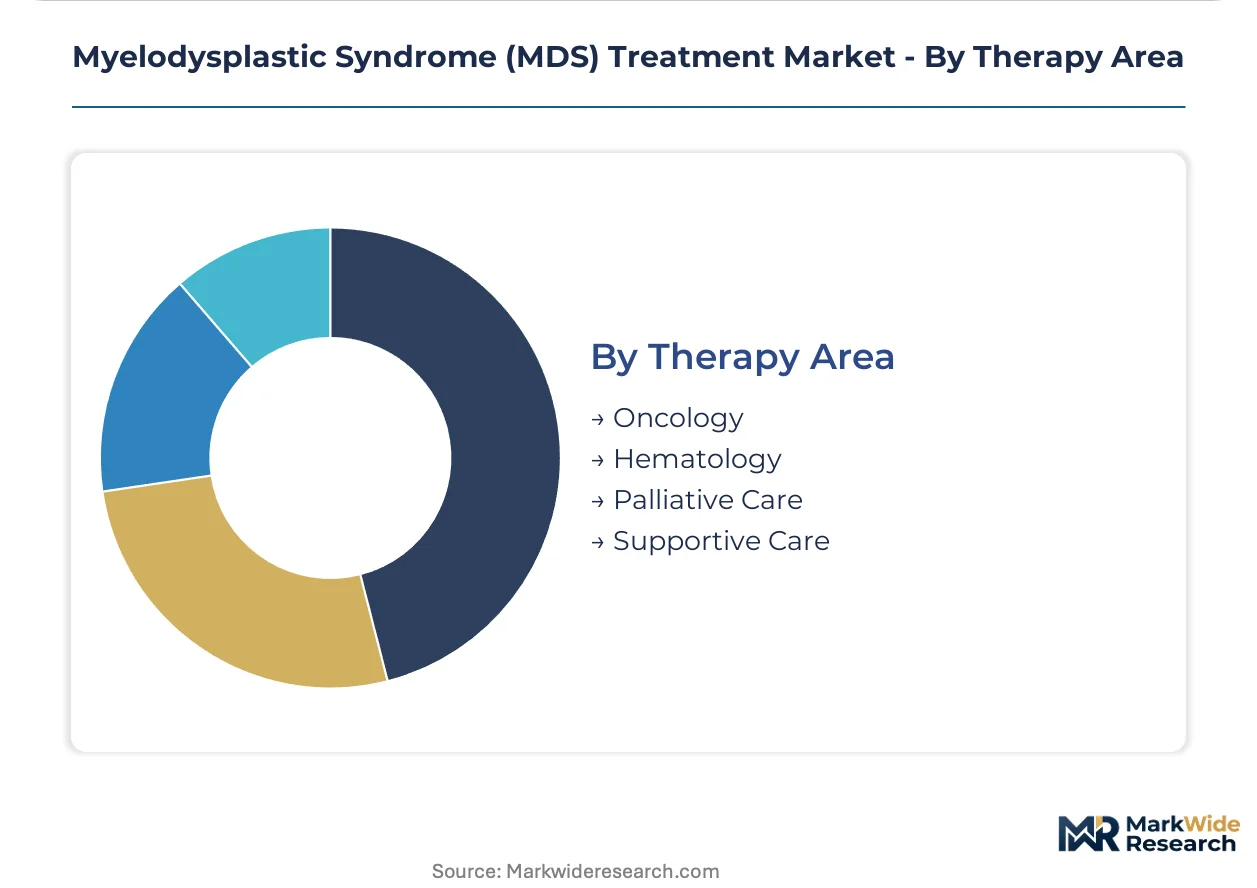
Therapy Area:
Therapeutic focus determines prescriber specialty, referral patterns, and the intensity of supportive care infrastructure required for safe delivery.
- Hematology:Specialized hematopathology expertise drives accurate diagnosis, risk stratification via International Prognostic Scoring System, and treatment sequencing. Demand concentrates in centers with integrated cytogenetic and molecular laboratories. Fellowship-trained hematologists in the United States, Germany, and Japan control access to novel protocols.
- Oncology:Medical oncologists manage MDS within broader myeloid malignancy portfolios, particularly at community practices lacking dedicated hematology divisions. Cross-coverage models complicate continuity of care.
- Supportive Care:Transfusion medicine, infectious disease prophylaxis, and growth factor support enable prolonged hypomethylating therapy.
- Palliative Care:Symptom management and goals-of-care discussions integrate in higher-risk and elderly populations with limited therapeutic options.
Hematology specialization leads therapeutic decision-making; oncology channels are expanding fastest as site-of-care decentralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in hematologic oncology is redirecting clinical trial investment toward jurisdictions with compressed review timelines and harmonized reimbursement pathways. Manufacturers calibrate manufacturing scale-up against the cost-of-compliance gap between accelerated FDA pathways and EMA centralized procedures.
United States
Hospital-based oncology departments in Boston, Houston, and Seattle are expanding dedicated MDS treatment centers with integrated cytogenetic laboratories. The FDA's Office of Oncologic Diseases maintains stringent chemistry, manufacturing, and controls requirements that favor sponsors with established fill-finish infrastructure. Academic medical centers with FACT accreditation anchor cellular therapy networks across the Northeast and West Coast corridors.
Germany
University hospitals in Heidelberg, Munich, and Hamburg concentrate specialized hematopathology expertise for accurate risk stratification. The EMA's Committee for Medicinal Products for Human Use applies centralized hematology assessment pathways that standardize market access across EU member states. Baden-Württemberg and Bavaria host the densest clusters of tertiary hematology referral networks.
Japan
Designated cancer hospitals in Tokyo, Osaka, and Nagoya are building regional referral capacity for higher-risk disease categories. PMDA accelerated review frameworks compress evaluation timelines for serious hematologic conditions, attracting parallel filings with US submissions. The Kanto region anchors the majority of specialized transfusion and apheresis infrastructure.
United Kingdom
NHS specialized commissioning frameworks concentrate MDS diagnostics within London, Manchester, and Birmingham hematology hubs. MHRA alignment with EMA centralized pathways streamlines post-Brexit market access for novel hypomethylating combinations. The Southeast and Midlands regions show the fastest adoption of subcutaneous administration formats.
Switzerland
Swissmedic operates streamlined review procedures for hematologic malignancies that attract early-access programs from multinational sponsors. Basel and Zurich anchor clinical trial networks with cross-border patient recruitment into German and French sites. The country's blood banking infrastructure supports extended hypomethylating therapy protocols.
Myelodysplastic Syndrome (MDS) Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue immunotherapy convergence and subcutaneous delivery innovation. The market structure consolidates around integrated oncology infrastructure with deep hematology expertise, while mid-scale specialists compete on biosimilar positioning and supportive care integration. Three archetypes dominate: global biopharmaceutical conglomerates with fill-finish manufacturing scale, mid-cap hematology specialists with clinical trial network density, and biosimilar developers targeting transfusion-dependent patient segments. Competitive moves center on manufacturing capacity expansion and biomarker-driven companion diagnostic partnerships.
Within the integrated infrastructure tier, Bristol-Myers Squibb Company and Novartis International AG exemplify archetypes with established supply continuity across multiple continents. Amgen Inc. occupies a position representing biosimilar and supportive care positioning within myeloid disorder protocols. These three anchors demonstrate how geographic origin and company structure correlate with strategic emphasis: US-based conglomerates leverage integrated oncology infrastructure, Swiss AG-format entities anchor deep clinical trial networks, and California-incorporated specialists compete on biosimilar market entry.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Novartis International AG |
| Amgen Inc. |
| Takeda Pharmaceutical Company Limited |
| Roche Holding AG |
| AbbVie Inc. |
| Celgene Corporation |
| Otsuka Pharmaceutical Co., Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Captive fill-finish manufacturing by Bristol-Myers Squibb and Novartis anchors supply security for hypomethylating agents while insulating pricing power from third-party contract volatility. This backward integration into aseptic processing infrastructure concentrates cost control among incumbents with multi-continent manufacturing footprints, compressing margin flexibility for competitors dependent on external CDMO capacity.
Pricing Analysis
Distributor margins on parenteral cytotoxics compress as hospital systems consolidate procurement through 340B pricing programs and GPO contracts. Three-tier pricing structure across branded originators, authorized generics, and biosimilar entrants stratifies by risk category and transfusion dependence. Pricing pressure stems from Medicare reimbursement differentials favoring outpatient administration over inpatient infusion. Community oncology practices exhibit highest price sensitivity; academic medical centers with research funding show lowest.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on specialized chemical producers in India, China, and the United States with validated DMFs for azacitidine and decitabine. Cold-chain distribution for parenteral formulations draws from temperature-controlled logistics networks anchored by specialty pharmacy hubs. Single-source vulnerability concentrates in fill-finish capacity for lyophilized cytotoxics. Distribution runs through hospital-based pharmacies, specialty distributors, and limited distribution networks under REMS protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA accelerated approval pathways for hematologic malignancies compress development timelines and concentrate value capture among sponsors with pre-built manufacturing scale.
For Market Incumbents: Acquire cellular therapy manufacturing assets with FACT-accredited vein-to-vein logistics capabilities. Consolidate companion diagnostic partnerships to lock biomarker-driven eligibility pathways ahead of checkpoint inhibitor launches. Defend against biosimilar erosion by deepening subcutaneous formulation patents and homecare nursing networks that raise switching costs for payers.
For New Entrants and Emerging Players: Engineered cellular platforms with TP53-targeting mechanisms offer technology-first wedge into higher-risk MDS segments where hypomethylating agents fail. Target Japanese designated cancer hospitals where PMDA accelerated review compresses time-to-revenue versus EU timelines. Lead with subcutaneous delivery innovation to bypass incumbent infusion chair infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale thresholds exclude mid-cap hematology specialists from commercial viability. Five-to-ten year viability favors sponsors with integrated fill-finish capacity and deep clinical trial networks in Boston, Heidelberg, and Tokyo. Acquisition target archetype: late-stage immunotherapy developers with validated biomarker strategies. Watch FDA breakthrough therapy designations for MDS indications as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive aseptic fill-finish capacity secures supply continuity for azacitidine across FDA, EMA, and PMDA jurisdictions. |
| Companion Diagnostic Partnership | TP53 and complex karyotype NGS panel validation locks biomarker-driven prescribing pathways for novel immunotherapies. |
| Subcutaneous Formulation Development | Patient-administered delivery formats capture site-of-care migration from hospital infusion suites to community clinics. |
| Clinical Trial Network Expansion | FACT-accredited academic medical centers in Boston and Heidelberg accelerate cellular therapy patient recruitment. |
| Regulatory Approval Pathway | FDA accelerated approval and PMDA priority review compress commercialization timelines for higher-risk MDS segments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation cross-checked segmentation outputs across therapy line, administration route, and regional regulatory cluster.
Comparable-period anchoring tied projection assumptions to historical adoption curves for hypomethylating agents and immunotherapy convergence patterns. The analytical framework modeled treatment duration, protocol complexity, and site-of-care migration across the projection horizon. CAGRs derived from segment-level volume builds and price trajectory assumptions. Forecast inputs incorporated transfusion infrastructure density, companion diagnostic penetration rates, and reimbursement differential evolution.
The model holds under stable regulatory approval velocity and continued Medicare outpatient reimbursement preference; deviation in FDA guidance shifts or 340B program restructuring would shift volume and value trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Blood Plasma Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Lymphopenia Therapeutics Market
Hematology
Global Hodgkin Lymphoma Treatment Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Hemocytometer Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Global Immunohematology Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Global Sickle Cell Disease Treatment Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Aplastic Anemia Treatment Market