
 Hair Growth Supplements Market | 2026-2036
Hair Growth Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Growth Supplements Market Analytics
Good Manufacturing Practice certification for dietary supplements is rotating as the primary gatekeeper for market access, filtering out contract manufacturers with inadequate quality systems. Nutrafol leverages clinically studied botanical complexes to sustain premium positioning in the women's segment. Viviscal anchors European distribution through pharmacy partnerships. Hims competes aggressively on price while controlling telehealth prescription flows that bundle supplements with dermatology consultations.
Hair growth supplements are oral nutritional formulations containing biotin, collagen peptides, amino acid complexes, or standardized herbal extracts delivered in bioavailable matrices, manufactured through spray-drying, tableting, or pectin-based gelling processes depending on final dosage form. Their commercial purpose centers on modulating the anagen phase of the hair follicle cycle and correcting micronutrient deficiencies linked to telogen effluvium. Biotin and collagen ingredient types dominate current revenue pools due to consumer familiarity and established supply chains, while amino acid formulations represent the fastest-growing category as sports nutrition brands cross-pollinate into hair health. Gummies have captured disproportionate shelf space in online retail and supermarket channels, though liquid formats command higher per-unit margins in professional and clinic-directed sales.
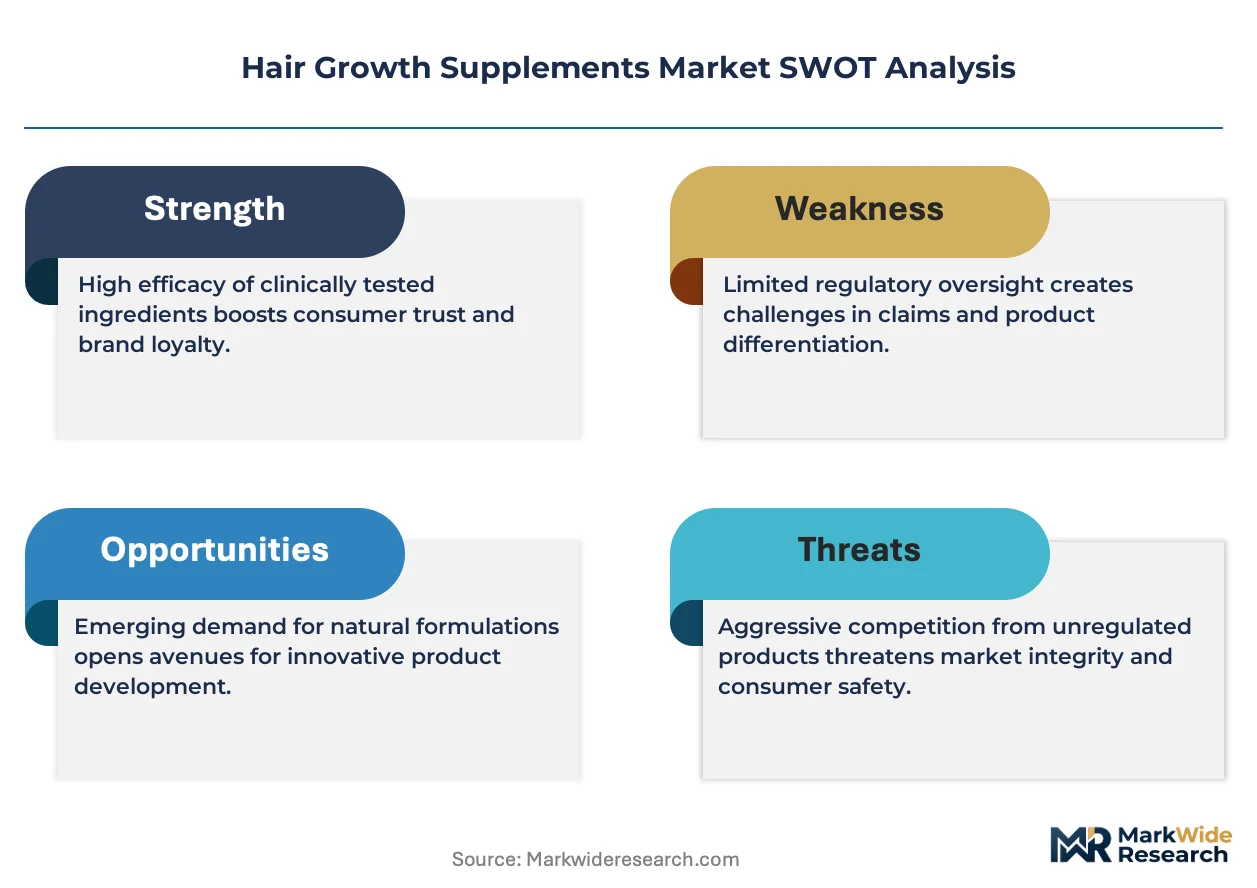
FDA oversees New Dietary Ingredient notifications and structure-function claim enforcement in the United States, while EFSA evaluates health claim substantiation for European market access, and FSSAI mandates ingredient disclosure and heavy metal testing for products distributed in India. These frameworks elevate compliance costs but simultaneously protect incumbent brands with established regulatory affairs capabilities from commodity competition. Stakeholders must monitor evolving substantiation requirements for collagen peptides and adapt clinical trial investments accordingly.
Market Dynamics
Telehealth platforms are compressing the path between supplement brands and early-stage alopecia patients, collapsing traditional pharmacy intermediaries while FDA New Dietary Ingredient notifications raise substantiation barriers for new entrants.
Growth Catalysts
- Telehealth Subscription Models:Direct-to-consumer platforms bundle dermatology consultations with recurring supplement deliveries, locking in patient adherence and lifetime value metrics that traditional retail cannot replicate.
- EFSA Health Claim Pathways:European brands investing in randomized controlled trials for collagen peptides gain differentiated positioning in pharmacy channels where clinical substantiation commands shelf priority.
- Amino Acid Crossover:Sports nutrition formulators migrating into hair health applications leverage existing bioavailability research and manufacturing infrastructure to accelerate product development cycles.
Market Restraints
- Marine Collagen Supply Concentration:Peptide sourcing depends on fisheries in Southeast Asia and North Atlantic zones where climate volatility and quota restrictions create input cost instability.
- FDA Notification Burden:New Dietary Ingredient pre-market submissions require 75-day review windows and safety documentation that filters out undercapitalized entrants lacking dedicated regulatory affairs teams.
- Topical Minoxidil Substitution:FDA-approved pharmaceutical alternatives with established efficacy data capture price-sensitive consumers before they trial nutritional interventions.
Strategic Opportunities
- India Pharmacy Modernization:FSSAI-mandated heavy metal testing and ingredient disclosure requirements favor organized brands with quality systems as modern trade and e-pharmacy channels expand in tier-2 cities.
- Professional Clinic Channels:Liquid format supplements command margin premiums when distributed through trichology clinics and medical spas seeking differentiated retail assortments.
- CSRD Supply Chain Reporting:European corporate sustainability disclosure rules create procurement preference for brands with traceable botanical sourcing and carbon-accounted manufacturing.
Industry Challenges
- Clinical Trial Talent Scarcity:Hair follicle biology expertise concentrates in academic dermatology departments, forcing brands to compete for limited principal investigators capable of designing regulator-acceptable endpoint studies.
- Multi-Format Manufacturing Complexity:Gummy, liquid, and capsule production lines require distinct equipment trains and stability testing protocols that strain contract manufacturers without dedicated nutraceutical capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Growth Supplements Market |
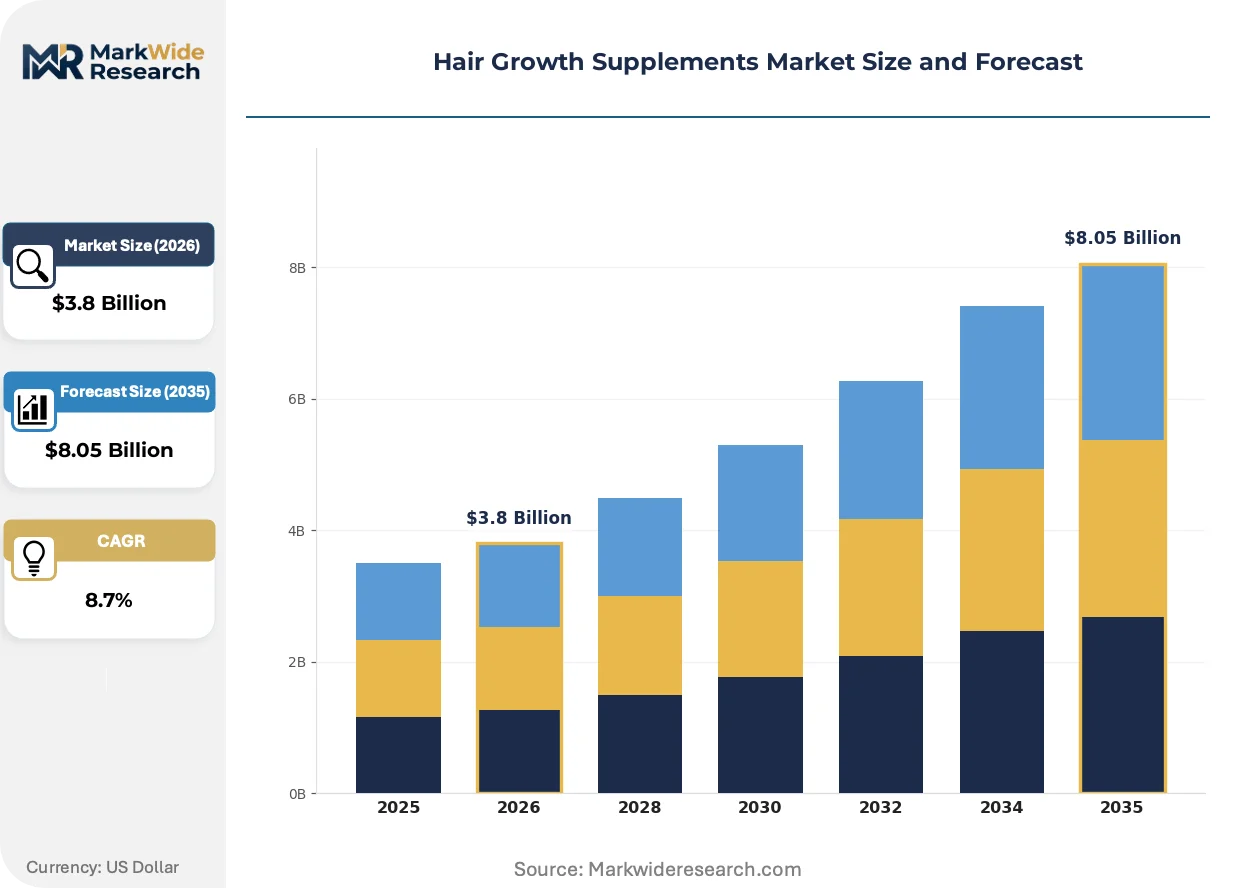
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Biotin, Collagen, Amino Acids, Herbal Extracts Form: Pills, Gummies, Powders, Liquids Target Audience: Women, Men, Seniors, Athletes Distribution Channel: Online Retail, Supermarkets, Pharmacies, Health Stores |
| Companies Covered | Omi Well Beauty, MaryRuth's, Nutrafol, Hers, Hims, Viviscal, Healthy Hair Vitamins, Happy Head, Nature's Bounty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Growth Supplements Market Evolving Landscape
Liposomal delivery systems and precision fermentation are redrawing ingredient bioavailability benchmarks while regulatory substantiation requirements harden across major jurisdictions.
Encapsulation technology is miniaturizing. Liposomal biotin and collagen peptide matrices protect actives through gastric transit, improving serum concentration curves. Premium-positioned brands in the United States and Germany are adopting these systems to justify price multiples over standard tablets. This technology is miniaturizing the efficacy gap between nutritional and pharmaceutical interventions in consumer perception.
REACH microplastic restrictions are forcing formulation changes. The European Chemicals Agency's pending limitations on synthetic polymer use in cosmetics and supplements are accelerating migration toward pectin-based gelling agents. Gummy manufacturers with legacy gelatin and synthetic colorant dependencies face reformulation timelines that compress margin recovery windows.
Subscription bundling is displacing single-unit purchases. Telehealth platforms and specialized e-commerce operators are locking consumers into 90-day auto-ship commitments with consultation access and progress tracking apps. This model concentrates in the United States and United Kingdom where recurring revenue metrics attract venture financing and enable customer acquisition spend levels that standalone retail brands cannot match.
Hair Growth Supplements Market Segmentation
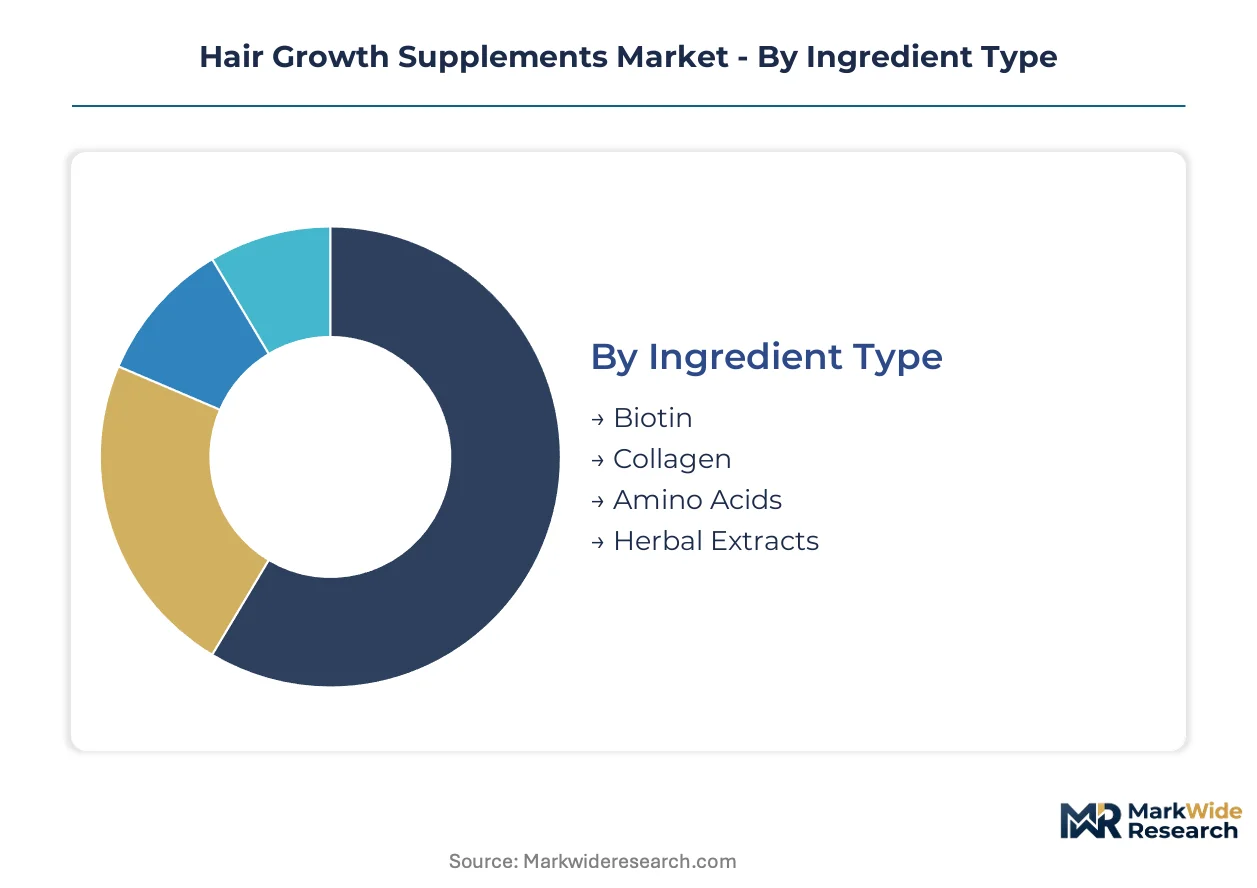
Ingredient formulation and dosage format determine bioavailability profiles, regulatory pathways, and margin structures across the hair growth supplements market. Segmentation reveals how telehealth platforms and pharmacy modernization are reshaping channel priorities by audience type.
Ingredient Type:
Biotin and collagen concentrate in domestic United States manufacturing, while amino acid sourcing pulls toward export-led supply chains in Southeast Asian fisheries and European fermentation facilities.
- Biotin:Water-soluble B7 vitamin dosed at 2,500-10,000 mcg in standard matrices. Demand clusters in United States direct-to-consumer subscriptions where familiarity drives trial-to-purchase conversion despite limited clinical substantiation for non-deficient populations.
- Collagen:Hydrolyzed peptide chains from marine or bovine sources, standardized to specific molecular weights for absorption. European pharmacy channels prioritize collagen with EFSA-aligned health claims, creating a dual-track market split between premium substantiated products and commodity-grade alternatives.
- Amino Acids:L-cysteine, L-methionine, and L-lysine complexes supporting keratin synthesis. Sports nutrition cross-pollination accelerates formulation innovation.
- Herbal Extracts:Standardized saw palmetto, ashwagandha, and curcumin concentrates targeting androgenetic pathways. Supply concentrates in Indian botanical extraction facilities.
Biotin holds the largest share; momentum sits with amino acids as sports nutrition brands migrate expertise into hair health applications.
Form:
Cost tier stratification separates premium liquid formats from mass-market gummies, with manufacturing complexity determining which contract manufacturers can serve each tier.
- Pills:Compressed tablets and hard-shell capsules using standard excipient bases. United States contract manufacturers with NSF certification dominate production for telehealth platforms requiring batch-level documentation.
- Gummies:Pectin or gelatin-based matrices with flavor masking systems. European REACH microplastic restrictions are forcing pectin migration and synthetic colorant elimination, compressing margin recovery timelines for legacy manufacturers.
- Powders:Spray-dried or agglomerated formulations for beverage integration. Gym and wellness channel distribution in Germany and United Kingdom favors this format.
- Liquids:Liposomal or micellar delivery systems in unit-dose vials. Trichology clinics in United States medical spas command per-unit premiums for bioavailability-optimized formats.
Gummies hold the largest share; liquid formats are climbing the fastest as professional channel distribution expands.
Target Audience:
Volume concentration varies sharply by geography, with men driving United States telehealth subscription growth while women sustain European pharmacy throughput.
- Women:Formulations addressing postpartum telogen effluvium and age-related thinning. Nutrafol and similar brands anchor premium positioning through clinically studied botanical complexes in United States subscription models.
- Men:Early-stage androgenetic alopecia interventions bundled with dermatology consultations. Hims and Roman platforms capture this segment through price-aggressive positioning combined with prescription flow control.
- Seniors:Micronutrient repletion targeting age-associated follicle miniaturization. Pharmacy channel concentration in Japan and Western Europe.
- Athletes:Protein-collagen hybrids addressing exercise-induced hair stress. Cross-pollination from sports nutrition brands with existing bioavailability research infrastructure.
Women hold the largest share; men are gaining share fastest as direct-to-consumer platforms collapse traditional consultation barriers.
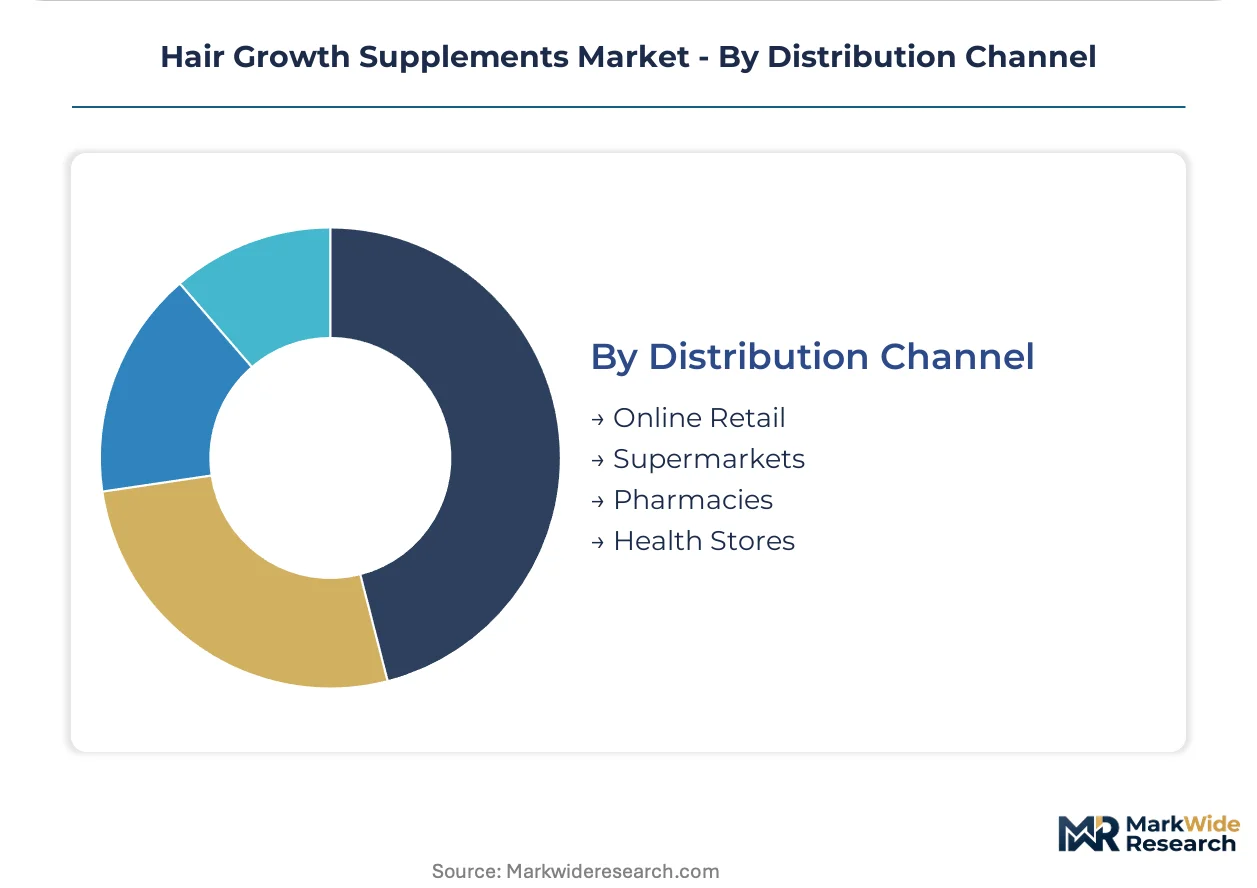
Distribution Channel:
Customer acquisition economics separate subscription-heavy online retail from transaction-driven supermarket and pharmacy channels, with margin profiles inversely correlated to intermediation depth.
- Online Retail:Direct-to-consumer platforms and specialized e-commerce operators with auto-ship infrastructure. United States venture-backed telehealth brands concentrate here, using 90-day commitments and progress-tracking apps to lock lifetime value metrics.
- Supermarkets:Mass-market gummy and pill formats in limited SKU assortments. Shelf space compression favors brands with national advertising support and established supply chain scale.
- Pharmacies:Professional-grade collagen and amino acid formulations with clinical substantiation. European pharmacy modernization and Indian e-pharmacy expansion in tier-2 cities drive channel growth.
- Health Stores:Specialist retailers emphasizing organic and clean-label positioning. Concentrated in Germany, United Kingdom, and United States coastal markets.
Online retail holds the largest share; pharmacies are expanding most quickly as regulatory disclosure requirements favor organized brands with quality systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telehealth subscription models concentrate buyer archetypes in the United States, while pharmacy modernization and clean-label regulatory shifts reshape demand patterns across Germany, India, United Kingdom, and Japan.
United States
Direct-to-consumer platforms bundle dermatology consultations with recurring supplement deliveries, locking in patient adherence metrics that traditional retail cannot replicate. FDA New Dietary Ingredient notifications require 75-day review windows and safety documentation that filters out undercapitalized entrants. San Francisco and New York City host venture-backed telehealth operators controlling prescription flows that bundle supplements with clinical consultations.
Germany
Pharmacy channel concentration favors collagen formulations with EFSA-aligned health claims, creating dual-track market splits between substantiated premium products and commodity alternatives. REACH microplastic restrictions accelerate migration toward pectin-based gelling agents, compressing margin recovery timelines for legacy manufacturers. Munich and Hamburg anchor professional-grade distribution networks serving trichology clinics and medical spas seeking differentiated retail assortments.
India
Modern trade and e-pharmacy expansion in tier-2 cities drives organized brand penetration as consumer purchasing shifts from unorganized retail. FSSAI mandates ingredient disclosure and heavy metal testing for distributed products, favoring quality-system-compliant manufacturers. Maharashtra and Karnataka concentrate botanical extraction facilities supplying standardized herbal concentrates to domestic and export markets.
United Kingdom
Subscription bundling displaces single-unit purchases as specialized e-commerce operators lock consumers into 90-day auto-ship commitments with progress-tracking applications. CSRD supply chain reporting rules create procurement preference for brands with traceable botanical sourcing. London anchors venture financing flows that enable customer acquisition spend levels standalone retail brands cannot match.
Japan
Senior-focused micronutrient repletion targeting age-associated follicle miniaturization sustains pharmacy channel throughput in an aging demographic. METI standards and PMDA oversight elevate substantiation requirements for functional food claims. Tokyo and Osaka metropolitan areas concentrate specialist retailers emphasizing organic and clean-label positioning for discerning consumer segments.
Hair Growth Supplements Market Competitive Landscape
Player mix skews toward direct-to-consumer specialists with telehealth integration capabilities, creating a tiered structure where subscription infrastructure separates premium-positioned brands from mass-market commodity suppliers. Three archetypes dominate: venture-backed telehealth platforms controlling prescription bundling, established nutraceutical houses with pharmacy distribution depth, and sports nutrition crossovers leveraging bioavailability research infrastructure. Competitive moves concentrate on geographic licensing partnerships and formulation technology acquisitions that secure liposomal delivery capabilities.
Among subscription-integrated platforms, Hims and Hers exemplify the telehealth-bundling archetype through dermatology consultation flows that lock recurring revenue. Nutrafol occupies a position within the clinically substantiated botanical tier, leveraging randomized controlled trial investments to sustain premium positioning. Viviscal anchors European pharmacy channel presence through distribution partnerships that prioritize regulatory-compliant health claims.
| Leading Market Players |
|---|
| Omi Well Beauty |
| MaryRuth's |
| Nutrafol |
| Hers |
| Hims |
| Viviscal |
| Healthy Hair Vitamins |
| Happy Head |
| Nature's Bounty |
| Others |
Value Network & Pricing Analysis
Pectin migration from gelatin gelling agents simultaneously redraws European manufacturing footprints and compresses margin recovery timelines as REACH microplastic restrictions force reformulation investments before price premiums materialize. This substitution dynamic concentrates pricing power with pectin-ready contract manufacturers while legacy gelatin-dependent producers absorb transitional cost shocks.
Pricing Analysis
Cost-plus contracts with marine collagen indexation dominate procurement between Southeast Asian fisheries and European peptide processors. Three-tier pricing structure across liposomal liquid, gummy, and standard tablet formats separates trichology clinic premiums from mass-market economy tiers. Pricing pressure stems from telehealth subscription bundling that aggregates buyer volume and demands volume discounts. Price-sensitive supermarket channels resist premium tiers while clinic-directed buyers absorb bioavailability-optimized premiums.
Supply Chain Analysis
North Atlantic and Southeast Asian fisheries transit chokepoints anchor marine collagen peptide sourcing before hydrolysis processing. Hydrolyzed peptide chains, pectin gelling agents, and liposomal encapsulation phospholipids draw from geographically dispersed extraction and fermentation facilities. Single-source vulnerability concentrates in Indonesian and Vietnamese marine collagen harvesting zones exposed to climate volatility. Distribution runs through direct-to-consumer subscription platforms, pharmacy wholesale networks, and health store specialty channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through telehealth platform consolidation, with venture-backed subscription operators aggregating patient volumes that extract preferential pricing and exclusive formulation access from incumbent suppliers.
For Market Incumbents: Fortify regulatory affairs capabilities against FDA New Dietary Ingredient notification burdens that filter undercapitalized competitors. Deepen backward integration into marine collagen sourcing through long-term offtake agreements with North Atlantic fisheries, insulating input cost volatility that threatens margin stability. Channel control through exclusive pharmacy partnerships in Germany and India defends positioning against telehealth price aggression. For New Entrants and Emerging Players: Differentiate on amino acid formulation expertise borrowed from sports nutrition bioavailability research. Target India's tier-2 e-pharmacy expansion where FSSAI disclosure requirements favor organized quality-system-compliant brands over unorganized retail alternatives. Professional clinic channel entry through liquid format liposomal delivery systems captures margin premiums unavailable in saturated gummy mass markets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with venture-backed telehealth platforms controlling prescription bundling workflows and recurring revenue infrastructure. Long-term viability hinges on regulatory substantiation durability across multiple jurisdictions rather than single-market approval depth. Watch FDA enforcement patterns on structure-function claims as inflection indicators for compliance cost escalation that favors scaled incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Liposomal Delivery Technology Acquisition | Secures bioavailability differentiation for clinic-directed premium tiers against standard tablet commoditization. |
| EFSA-Aligned Health Claim Investment | Unlocks pharmacy channel shelf priority in Germany where clinical substantiation commands retail access. |
| Direct-to-Consumer Subscription Launch | Replicates Hims and Hers patient adherence locking through bundled dermatology consultation workflows. |
| Marine Collagen Supply Agreement | Tethers input security to North Atlantic fisheries quotas amid Southeast Asian climate volatility exposure. |
| Pectin Formulation Transition | Preempts REACH microplastic enforcement that would eliminate gelatin-dependent gummy manufacturers. |
Research Methodology
Desk research of FDA New Dietary Ingredient notifications, EFSA health claim submissions, and FSSAI regulatory filings preceded structured interviews with regulatory affairs directors, contract manufacturing procurement leads, telehealth platform operators, and trichology clinic owners. Secondary validation drew from customs trade data on marine collagen imports, pharmacy distribution databases, and telehealth venture financing disclosures. Bottom-up demand modeling triangulated against top-down market sizing across ingredient type, dosage format, and distribution channel dimensions.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation layer. The analytical framework models biotin, collagen, amino acid, and herbal extract ingredient categories alongside gummy, liquid, pill, and powder formats through pharmacy, online retail, supermarket, and health store channels. CAGRs derive from patient population growth, telehealth penetration curves, and regulatory approval timelines without year-specific anchoring. Forecast inputs incorporate marine collagen supply quota restrictions and REACH formulation compliance deadlines.
Material uncertainties — FDA enforcement intensity on structure-function claims, marine fisheries quota revisions, and telehealth platform consolidation outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions about patient adherence rates and subscription renewal patterns. Practitioners should keep alternative scenarios live as regulatory substantiation requirements and supply chain climate exposure evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
Microalgae DHA Market
Nutritional Supplements
Japan Whey Protein Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Asia-Pacific Amino Acid in Dietary Supplements Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Microencapsulated Fish Oil Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Lutein Market