
 Europe Digestive Health Supplements Market | 2026-2036
Europe Digestive Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Digestive Health Supplements Market Foresight
Subscription-based replenishment programs is rebalancing how digestive health brands monetize consumer relationships, shifting from one-time transactions to recurring revenue anchored by personalized microbiome testing. Bayer AG leverages its pharmaceutical heritage to sustain pharmacist trust across German and French pharmacy networks. Nestlé S.A. differentiates through specialized probiotic strains developed via Chr. Hansen Holding A/S partnerships. Danone S.A. dominates the fermented dairy-adjacent supplement space with science-backed strain positioning.
Europe digestive health supplements comprise ingestible products containing live microorganisms, non-digestible fibers, or hydrolytic enzymes formulated to modulate gut flora, enhance nutrient absorption, or alleviate functional gastrointestinal disturbances. These products typically require refrigeration-stable CFU counts exceeding 10 billion per serving and acid-resistant capsule coatings to ensure proximal small intestine delivery. Probiotics occupy the largest value share due to established clinical validation for irritable bowel syndrome management, while enzyme supplements represent the fastest-expanding margin pool as consumers seek post-meal digestive support. Gummies within the formulation dimension are capturing incremental shelf space in supermarket channels by converting pediatric and young adult trial.
EFSA nutrition and health claims regulation shapes permissible marketing language, forcing reformulation investments where generic "gut health" statements lack approved Article 13.5 or 14 substantiation. The EU Green Deal packaging requirements are pressuring manufacturers toward mono-material blister packs and reduced plastic bottles, with ECHA REACH compliance adding raw material traceability costs. Stakeholders must monitor EMA's evolving stance on live biotherapeutic products classification, as reclassification would trigger pharmaceutical-grade manufacturing standards and reshape competitive economics.
Market Dynamics
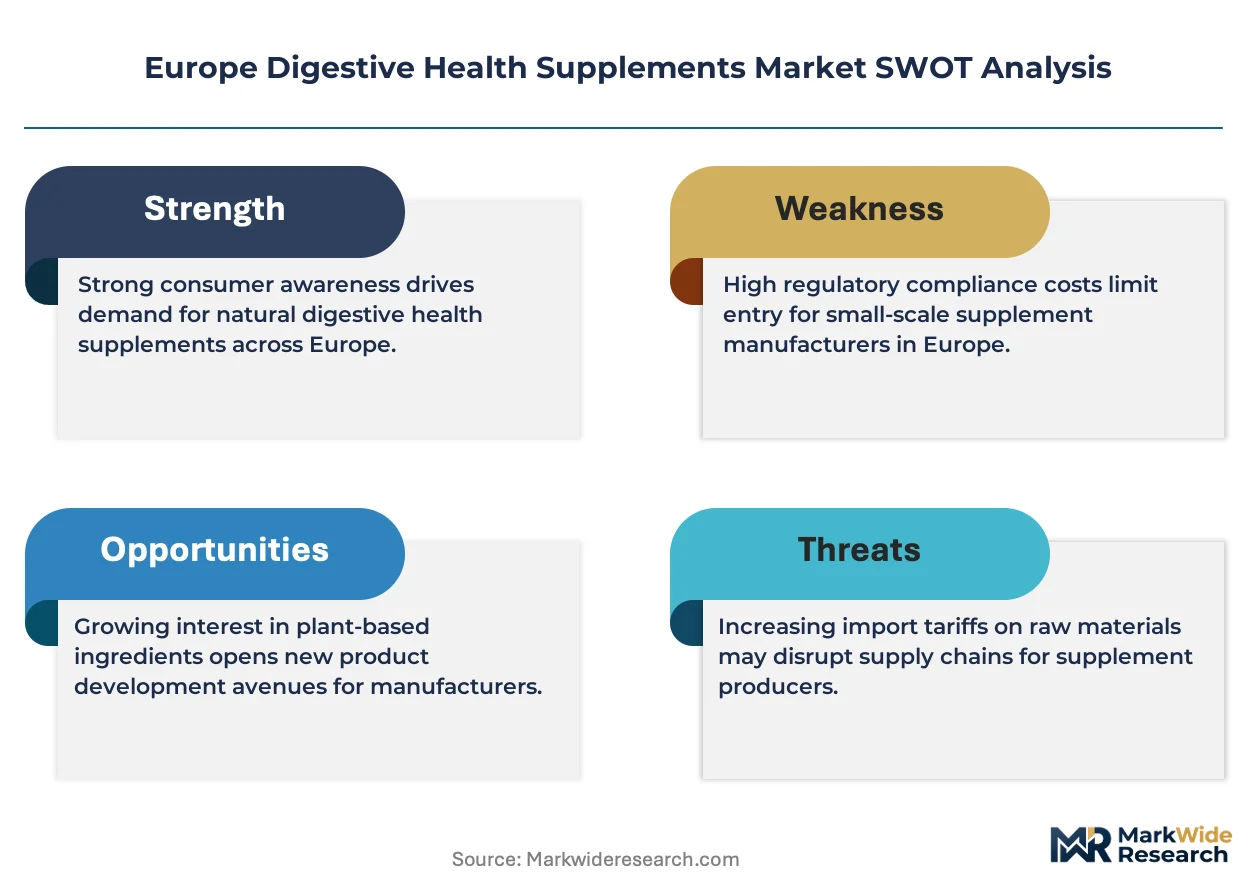
EFSA's tightening Article 13.5 and 14 health claims substantiation requirements are forcing manufacturers toward costly clinical trials and reformulation cycles, compressing margins for generic probiotic and prebiotic portfolios while advantaging pharmaceutical-backed players with existing research infrastructure.
Growth Catalysts
- Geriatric microbiome awareness:Consumers aged 65+ in Germany and France now prioritize gut flora maintenance as preventive health, expanding pharmacy channel penetration for clinically validated strains.
- EU Green Deal packaging mandates:Mono-material blister pack requirements are accelerating sustainable format innovation, creating first-mover advantages for compliant suppliers in Western European retail.
- Enzyme post-meal positioning:Functional gastrointestinal support claims for hydrolytic enzymes are capturing trial among working-age consumers seeking immediate digestive relief after irregular eating patterns.
Market Restraints
- Live culture cold chain costs:Refrigeration-stable CFU preservation requirements add 15-25% to finished goods logistics expenses, disadvantaging smaller entrants without pharmaceutical distribution partnerships.
- Strain IP concentration:Proprietary probiotic strain development remains captive to Chr. Hansen Holding A/S and select Danish biotech clusters, limiting independent formulation options.
- EFSA claims rejection backlog:Pending Article 13.5 generic health claims evaluations create marketing language uncertainty, forcing conservative positioning that blunts product differentiation.
Strategic Opportunities
- Eastern European pharmacy expansion:Poland and Romania exhibit underpenetrated probiotic adoption relative to Western European per-capita consumption, offering volume growth through pharmacist education programs.
- Pediatric gummy formats:Supermarket channel shelf space for chewable digestive supplements remains sparse outside UK and German urban centers, presenting format innovation white space.
- Live biotherapeutic reclassification monitoring:EMA's evolving pharmaceutical-grade manufacturing standards discussion creates regulatory arbitrage windows for early compliance investors.
Industry Challenges
- Microbiome testing integration:Subscription personalization models require bioinformatics talent scarce in traditional supplement manufacturers, forcing expensive partnerships or capability acquisitions.
- REACH raw material traceability:ECHA compliance documentation for enzyme and prebiotic sourcing adds administrative burden that delays new product introduction timelines by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Digestive Health Supplements Market |
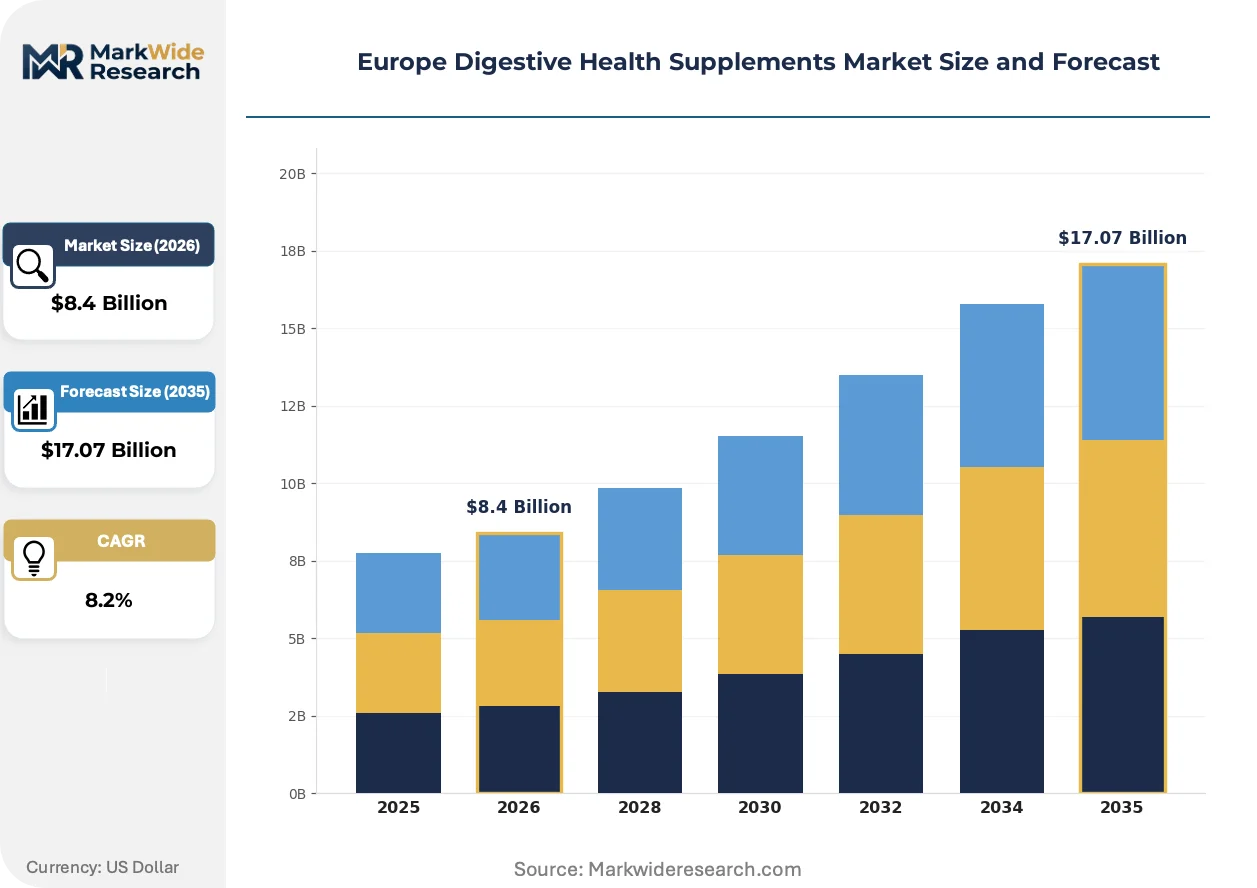
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Enzymes, Fiber Supplements Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Formulation: Capsules, Powders, Liquids, Gummies End User: Adults, Seniors, Children, Athletes |
| Companies Covered | Bayer AG, Nestlé S.A., Amway Corporation, Danone S.A., ADM, BioGaia AB, BASF SE, Chr. Hansen Holding A/S, Sanofi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Digestive Health Supplements Market Shifts & Advancements
Acid-resistant capsule engineering and at-home microbiome diagnostics are converging to transform how digestive health products demonstrate efficacy and retain consumer loyalty beyond initial trial.
Dual-layer capsule technology with enteric coatings is electrifying proximal small intestine delivery guarantees for live probiotic cultures. German pharmacy networks are prioritizing shelf-stable formats with verified acid resistance over traditional refrigerated alternatives. This engineering advance is compressing the perceived efficacy gap between mass-market and clinical-grade probiotic positioning.
EFSA's pending guidance on live biotherapeutic products classification is reshaping manufacturing investment priorities across European production facilities. Stricter pharmaceutical-grade standards would disqualify existing dietary supplement lines from certain strain claims. French and Italian contract manufacturers are accelerating quality system upgrades to preempt regulatory reclassification.
Subscription replenishment anchored by personalized microbiome testing is displacing one-time retail purchases among urban professionals aged 30-45. Direct-to-consumer platforms in UK and Netherlands are bundling quarterly biome reports with strain-matched probiotic shipments. This behavioral pivot is most visible in London and Amsterdam metropolitan areas where digital health adoption outpaces traditional pharmacy loyalty.
Europe Digestive Health Supplements Market Segmentation
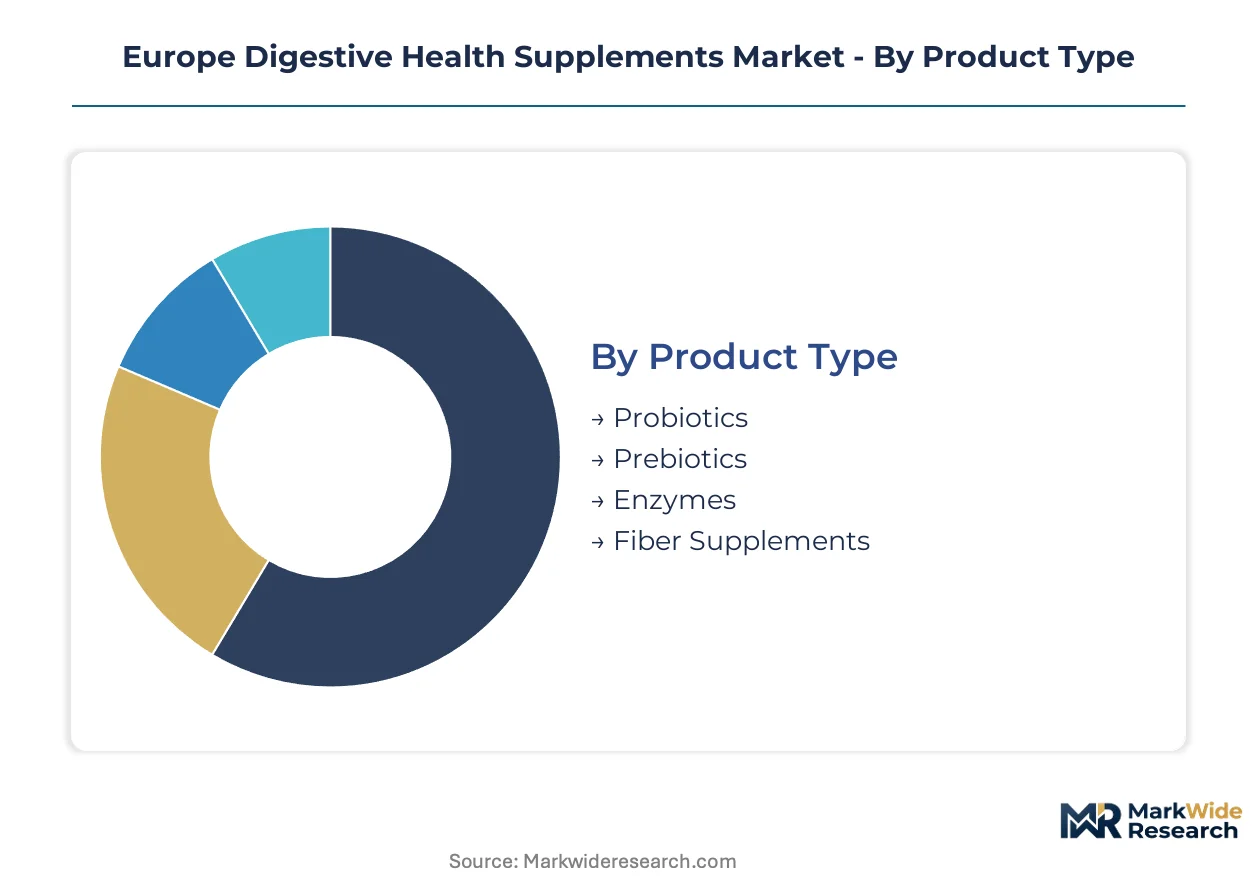
Digestive health supplement purchasing patterns diverge sharply across product formats, channel preferences, and user life stages. Manufacturers must align strain development, packaging formats, and retail partnerships to match these distinct consumption contexts.
Product Type:
Upgrade cycles in this category track clinical validation milestones rather than equipment replacement schedules, with consumers switching formulations as new strain research reshapes efficacy perceptions.
- Probiotics:Live microbial cultures formulated to exceed 10 billion CFU per serving with acid-resistant delivery systems. German and French pharmacy networks concentrate demand for refrigerated clinical-grade strains targeting irritable bowel syndrome management. EFSA Article 13.5 substantiation requirements compress margins for generic formulations lacking approved health claims.
- Enzymes:Hydrolytic proteins including amylase, lipase, and protease designed for post-meal digestive support. Working-age consumers in UK urban centers drive trial for immediate relief positioning after irregular eating patterns. This segment captures the steepest expansion trajectory as functional gastrointestinal claims bypass probiotic regulatory complexity.
- Prebiotics:Non-digestible fibers including inulin and fructooligosaccharides that selectively feed beneficial gut bacteria.
- Fiber Supplements:Psyllium husk and methylcellulose formulations targeting bowel regularity without live culture stability concerns.
Probiotics sit at the top of the volume ranking, with enzymes climbing the fastest.
Distribution Channel:
Channel selection in this market maps directly to consumer trust requirements and regulatory comfort levels, with pharmacist-mediated purchase dominating high-consideration strain categories.
- Pharmacies:German and French pharmacy networks anchor premium probiotic distribution through pharmacist recommendation. Cold chain infrastructure and clinical credibility sustain this channel's grip on geriatric consumers seeking validated gut microbiome maintenance.
- Online Retail:Direct-to-consumer platforms in Netherlands and UK metropolitan areas bundle subscription replenishment with at-home microbiome testing. Personalized strain matching displaces one-time retail purchases among professionals aged 30-45.
- Health Stores:Specialist retailers emphasizing organic and non-GMO positioning for wellness-focused consumers.
- Supermarkets:Mass-market shelf space concentrates on gummy formats and pediatric-oriented packaging in UK and German urban centers.
Pharmacies command the highest value per transaction, though online retail gains share fastest among urban demographics.
Formulation:
Format innovation tracks delivery precision requirements and pediatric palatability demands, with acid-resistant engineering separating clinical-grade from commodity positioning.
- Capsules:Dual-layer enteric coatings ensure proximal small intestine release for live culture viability. German pharmacy procurement prioritizes acid resistance verification over traditional refrigerated alternatives.
- Gummies:Chewable formats with flavor masking capture supermarket shelf space for pediatric and young adult trial conversion. UK retail networks lead format penetration outside pharmacy channels.
- Powders:Sachet formats enabling dose flexibility and beverage integration for adult consumers.
- Liquids:Ready-to-drink formulations targeting senior consumers with swallowing difficulties.
Capsules dominate pharmacy dispensing volumes, while gummies expand most quickly into mass retail.
End User:
User segmentation reflects life-stage health priorities and performance demands, with geriatric preventive positioning commanding premium pricing against athletic recovery applications.
- Seniors:Consumers aged 65+ in Germany and France prioritize gut flora maintenance as preventive health, expanding pharmacy channel penetration for clinically validated strains with refrigeration-stable CFU guarantees.
- Adults:Working-age professionals aged 30-50 drive subscription model adoption through microbiome testing integration in London and Amsterdam metropolitan areas.
- Children:Pediatric formats concentrate in gummy and liquid presentations with supermarket channel distribution.
- Athletes:Performance-oriented consumers seeking digestive optimization for nutrient absorption and recovery support.
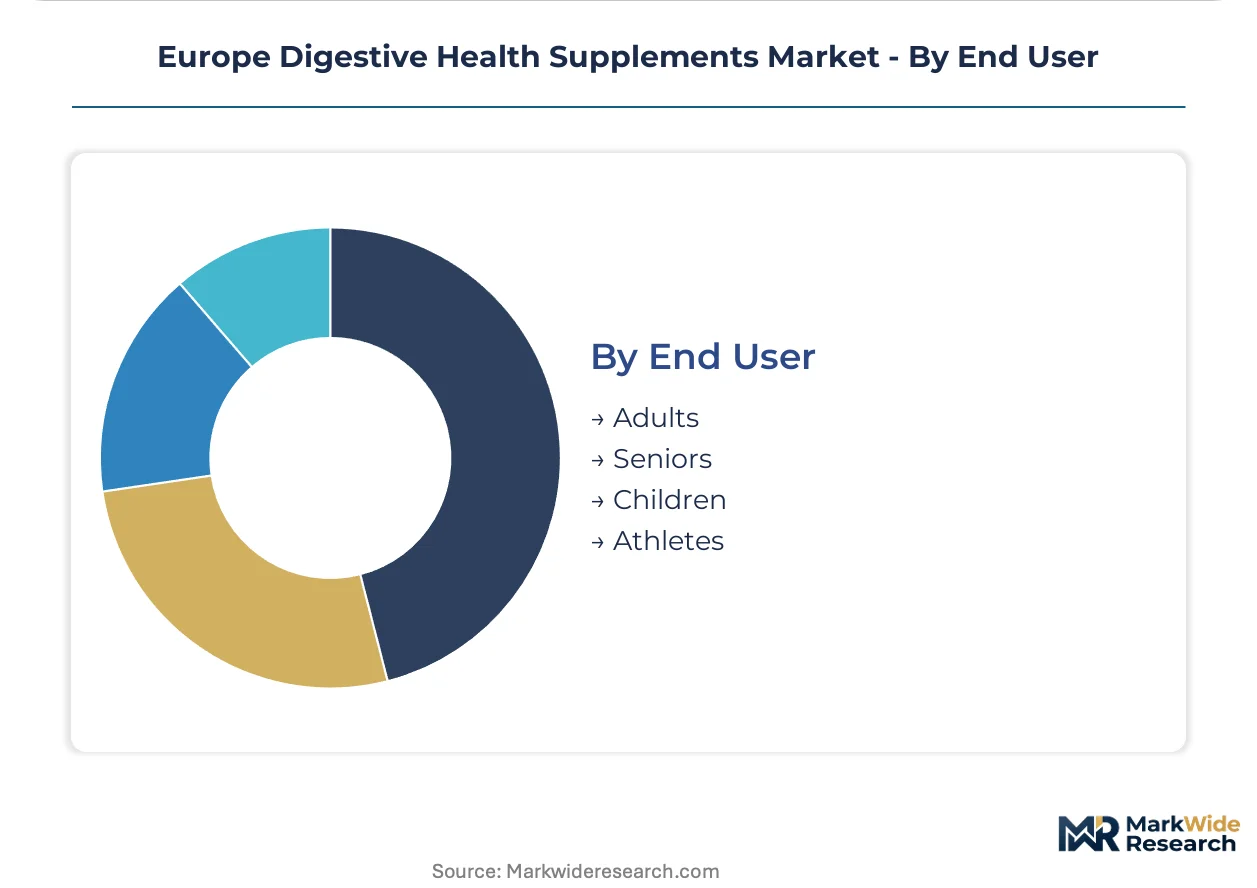
Seniors generate the highest per-capita expenditure, with adult subscription models scaling most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing investment gravitates toward jurisdictions where EFSA substantiation costs diverge from pharmaceutical-grade compliance burdens. French and German producers absorb clinical trial expenses that Polish and Romanian entrants avoid through generic positioning. This arbitrage sustains a two-tier supply structure across the region.
Germany
Pharmacy channel dominance anchors demand for refrigerated clinical-grade strains among consumers aged 65+. EFSA Article 13.5 health claims requirements compress margins for generic formulations lacking approved substantiation. Berlin and Munich metropolitan clusters concentrate contract manufacturing capacity for dual-layer enteric capsule engineering.
France
Urban professionals in Paris and Lyon drive subscription replenishment bundled with at-home microbiome testing services. ANSM pharmaceutical regulator discussions on live biotherapeutic classification accelerate quality system upgrades among Lyon-based contract manufacturers. French pharmacy networks sustain pharmacist-mediated purchase for premium probiotic strains.
United Kingdom
London and Amsterdam metropolitan areas lead direct-to-consumer platform adoption for personalized strain-matched shipments. ECHA REACH compliance documentation for enzyme sourcing delays new product introductions by administrative burden. UK supermarket channels concentrate gummy format shelf space for pediatric trial conversion.
Poland
Underpenetrated probiotic adoption relative to Western European per-capita consumption creates volume growth through pharmacist education programs. EU Green Deal packaging mandates accelerate mono-material blister pack adoption among Warsaw-based suppliers. Polish retail pharmacy expansion captures incremental geriatric gut flora maintenance demand.
Netherlands
Randstad urban corridor anchors digital health adoption outpacing traditional pharmacy loyalty among professionals aged 30-45. EFSA pending guidance on live biotherapeutic products classification shapes manufacturing investment priorities. Dutch direct-to-consumer platforms pioneer quarterly biome report bundling with strain-specific replenishment.
Europe Digestive Health Supplements Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-backed players commanding pharmacy channel trust while pure-play supplement firms capture supermarket and online trial. Market structure tilts toward consolidation among strain-IP holders and formulation engineers, leaving commodity probiotic assemblers in fragmented competition. Three archetypes dominate: heritage pharmaceutical conglomerates with existing research infrastructure, specialized Danish biotech clusters holding proprietary strain libraries, and agile direct-to-consumer platforms integrating microbiome diagnostics. Competitive moves concentrate on pharmacist network exclusivity arrangements and sustainable packaging format innovation ahead of EU Green Deal deadlines.
Among pharmaceutical heritage conglomerates, Bayer AG and Sanofi occupy positions leveraging existing clinical research infrastructure for EFSA substantiation compliance. Nestlé S.A. and Danone S.A. represent the consumer packaged goods archetype, anchoring fermented dairy-adjacent supplement positioning through science-backed strain development partnerships. Chr. Hansen Holding A/S exemplifies the specialized biotech tier, sitting within Danish industrial clusters that concentrate proprietary probiotic strain IP and limit independent formulation options for rival manufacturers.
| Leading Market Players |
|---|
| Bayer AG |
| Nestlé S.A. |
| Amway Corporation |
| Danone S.A. |
| ADM |
| BioGaia AB |
| BASF SE |
| Chr. Hansen Holding A/S |
| Sanofi |
| Others |
Supply & Pricing Matrix
Acid-resistant capsule engineering is compressing cost economics for clinical-grade probiotics while concentrating formulation expertise in German and Danish manufacturing clusters. This technological transition simultaneously elevates quality thresholds for pharmacy channel entry and consolidates supply relationships around pharmaceutical heritage players with captive R&D infrastructure.
Pricing Analysis
Pharmacist-mediated channel margins absorb substantial markup layers for refrigerated clinical-grade strains in German and French networks. Three-tier pricing structure across premium clinical strains, standard pharmacy-grade formulations, and economy supermarket gummies stratifies by EFSA substantiation status and cold chain requirements. Pricing pressure stems from generic probiotic commoditization as unvalidated strains flood Eastern European retail. Pediatric gummy buyers in UK supermarkets exhibit highest price sensitivity, while geriatric pharmacy consumers in Berlin and Munich prioritize efficacy verification over cost.
Supply Chain Analysis
Direct-to-consumer channels handle subscription replenishment demand through Netherlands and UK digital health platforms, bypassing traditional pharmaceutical distribution. Manufacturing concentrates in Germany, France, and Denmark where EFSA compliance infrastructure and strain IP development clusters coexist. Raw material sourcing draws from Chr. Hansen Holding A/S proprietary libraries, Indian enzyme suppliers, and Chinese prebiotic fiber producers. Single-source vulnerability around Danish strain IP creates supply concentration risk for independent formulators. Distribution runs through pharmacy networks for premium positioning and supermarket mass retail for format trial conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA substantiation cost differentials between Western and Eastern Europe create geographic-arbitrage opportunities for manufacturers willing to accept generic positioning in underpenetrated markets. Poland and Romania offer volume expansion with reduced clinical trial burdens relative to German or French compliance requirements.
For Market Incumbents: Lock in pharmacist network exclusivity arrangements across German and French pharmacy channels before live biotherapeutic reclassification triggers pharmaceutical-grade manufacturing standards. Acquire bioinformatics capabilities for microbiome testing integration to defend subscription revenue streams against pure-play digital health entrants. Prioritize mono-material blister pack compliance ahead of EU Green Deal enforcement deadlines to secure first-mover shelf space advantages.
For New Entrants and Emerging Players: Urban professionals aged 30-45 in Amsterdam and London represent an underserved buyer archetype for personalized strain-matching services without incumbent pharmaceutical heritage constraints. Capture this segment through direct-to-consumer platforms bundling at-home microbiome diagnostics with quarterly replenishment cycles. Target Polish pharmacy networks with pharmacist education programs as the most penetrable geography for volume build.
For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers with EFSA-compliant quality systems but lacking proprietary strain IP. Long-term viability in this market hinges on regulatory arbitrage windows closing as EMA pharmaceutical-grade standards converge with dietary supplement manufacturing. Acquisition candidates with dual-layer enteric capsule engineering capabilities and existing REACH documentation offer defensive positioning. Monitor EMA live biotherapeutic classification guidance as the critical inflection signal for manufacturing asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Article 13.5 Health Claims Investment | Clinical trial substantiation secures pharmacy channel preference and blocks generic competitors. |
| Microbiome Testing Platform Integration | Subscription personalization anchored to bioinformatics capabilities displaces one-time retail purchases. |
| Mono-Material Sustainable Packaging Transition | EU Green Deal compliance creates first-mover shelf space advantages in Western European retail. |
| Eastern European Pharmacy Network Expansion | Polish and Romanian pharmacist education programs capture underpenetrated geriatric gut health demand. |
| Live Biotherapeutic Manufacturing Pre-Compliance | Early pharmaceutical-grade quality system upgrades preempt EMA reclassification disruption. |
Research Methodology
Coverage spans Western Europe, Eastern Europe, and Nordic regions, with primary inputs from each market cluster. The analysis combines structured interviews with pharmacy category managers, contract manufacturing executives, regulatory affairs specialists at EFSA-experienced firms, and direct-to-consumer platform operators. Secondary validation draws from EFSA health claims register entries, EMA live biotherapeutic guidance documents, EU Green Deal packaging directive texts, and REACH compliance databases. Bottom-up strain-level demand modeling and top-down channel revenue estimates were triangulated to derive market sizing.
Granularity-level modeling tracked probiotics, enzymes, prebiotics, and fiber supplements by formulation format, distribution channel, and end-user life stage across the projection horizon. Geographic segmentation captured Germany, France, United Kingdom, Poland, and Netherlands with distinct regulatory and channel characteristics. CAGRs were derived from historical trajectory analysis and forward-looking adoption curve modeling for subscription services and pediatric gummy formats. Forecast inputs incorporated EFSA claims approval timelines and EMA reclassification probability assessments.
Underlying measurement precision varies by segment; pharmacy channel data carries tighter precision than emerging direct-to-consumer subscription volumes. Forecasts reflect assumptions regarding EFSA substantiation backlog resolution, cold chain infrastructure expansion, and live biotherapeutic regulatory classification outcomes. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty and evolving microbiome science validation standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Nutraceutical Oral Thin Films Market
Nutritional Supplements
Global Digestive Enzyme Supplements Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Global Coq10 Supplement Market
Nutritional Supplements
Isolate Whey Protein Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Krill Oil Phospholipid Market
Nutritional Supplements
Tocotrienol Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Omega-3 Fatty Acids Market
Nutritional Supplements
Pregnenolone Supplements Market