
 Inactivated Vaccines Market | 2026-2036
Inactivated Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Inactivated Vaccines Market Foresight
The EU Green Deal is shifting procurement criteria toward sustainable cold-chain logistics and reduced environmental footprint in vaccine distribution. Sanofi leverages its integrated manufacturing network across multiple continents to secure supply continuity for inactivated polio and influenza vaccines. GSK plc anchors its position through sustained R&D investment in adjuvant technologies that enhance immunogenicity of inactivated formulations. Serum Institute of India Pvt. Ltd dominates volume production by operating the world's largest vaccine manufacturing facility, supplying affordable inactivated vaccines to UNICEF and Gavi-eligible markets.
Inactivated vaccines contain pathogens rendered non-infectious through heat, chemicals, or radiation while preserving immunogenic surface antigens, requiring adjuvants to stimulate adequate immune responses. These formulations serve as foundational tools for preventable disease control in populations where live-attenuated vaccines pose safety constraints. Intramuscular delivery leads volume due to established clinical protocols and healthcare worker familiarity, while nanoparticle formulations represent the fastest-growing product type as carriers improve antigen presentation and dose-sparing potential. Among applications, outbreak control commands premium pricing during emergency procurement, whereas preventive care programs generate stable, recurring demand through national immunization schedules.
FDA and EMA stringently evaluate inactivated vaccine lot consistency, potency, and stability data before licensure, directly shaping development timelines and manufacturing validation requirements. WHO prequalification opens procurement access to United Nations agencies and donor-funded programs, creating a dual-track regulatory environment where manufacturers must satisfy both national and international standards. Stakeholders should monitor evolving adjuvant platform regulations and mRNA manufacturing scale-up, as these forces will reshape competitive dynamics and capital allocation priorities for inactivated vaccine portfolios.
Market Dynamics
Adjuvant platform innovation is compressing dose requirements and reshaping manufacturing economics across inactivated vaccine portfolios, forcing capital reallocation toward nanoparticle delivery systems.
Growth Catalysts
- Pediatric program expansion:National universal immunization schedules in India and Nigeria are scaling procurement volumes for polio and pentavalent formulations through Gavi co-financing mechanisms.
- WHO prequalification acceleration:The streamlined assessment pathway is compressing registration timelines for emerging market manufacturers seeking UNICEF supply contracts.
- Cell-culture manufacturing:Serum-free production platforms are displacing egg-based methods for influenza vaccines, reducing batch-to-batch variability and allergen risks.
Market Restraints
- Adjuvant raw material concentration:Squalene and aluminum salt supply chains concentrate among three specialty chemical suppliers, exposing manufacturers to input cost volatility.
- Cold-chain infrastructure gaps:Last-mile distribution in tropical climates requires 2-8°C maintenance across fragmented health networks, elevating wastage rates.
- Live-attenuated substitution:Viral vector and mRNA platforms are capturing indication expansions where immunogenicity constraints previously favored inactivated formats.
Strategic Opportunities
- Sub-Saharan Africa penetration:Underimmunized birth cohorts in Ethiopia and the Democratic Republic of Congo present volume expansion potential for pentavalent and rotavirus combinations.
- EU Green Deal procurement criteria:Sustainable cold-chain logistics mandates are creating first-mover advantage for manufacturers with carbon-neutral distribution certification.
- Combination vaccine convergence:Hexavalent formulations integrating hepatitis B and Haemophilus influenzae type b antigens are consolidating administration visits and improving coverage metrics.
Industry Challenges
- Adjuvant formulation expertise scarcity:Qualified immunologists capable of optimizing toll-like receptor agonist combinations command premium compensation, constraining R&D team scaling.
- Lot-to-lot consistency validation:FDA potency testing requirements for inactivated viral vaccines extend release timelines by 4-6 weeks, compressing working capital cycles.
- Legacy equipment integration:Single-use bioreactor adoption requires revalidation of downstream purification trains originally designed for stainless-steel vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inactivated Vaccines Market |
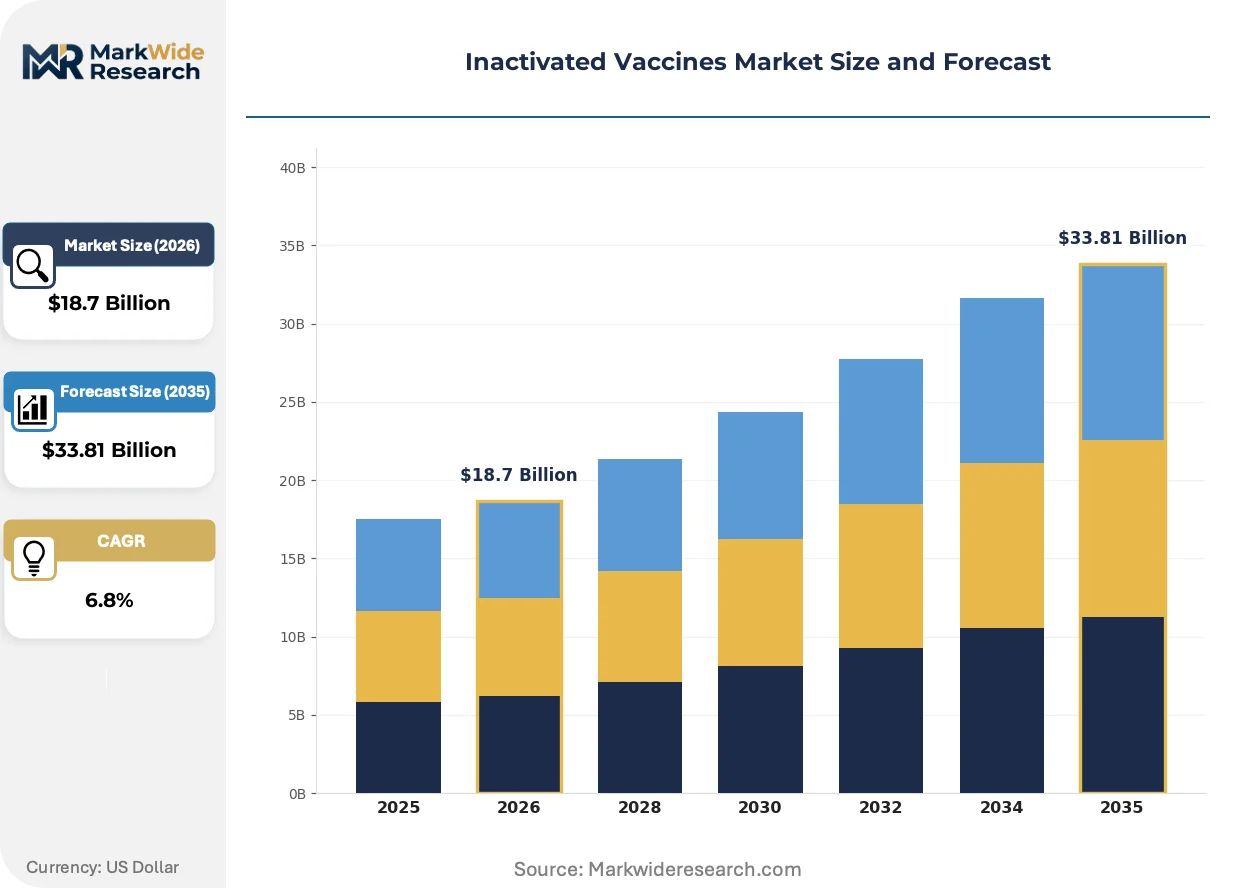
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intramuscular, Subcutaneous, Oral, Nanoparticle Delivery Mode: Syringe, Auto-Injector, Vial, Pre-filled Syringe End User: Hospitals, Clinics, Research Laboratories, Public Health Units Application: Preventive Care, Travel Vaccination, Pediatric Use, Outbreak Control |
| Companies Covered | Sanofi, GSK plc, Merck & Co., Inc., Pfizer Inc., Bharat Biotech, Serum Institute of India Pvt. Ltd, Sinovac Biotech Ltd., Sinopharm, Valneva SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inactivated Vaccines Market Shifts & Advancements
Nanoparticle carrier systems and continuous manufacturing methods are restructuring production economics while regulatory agencies accelerate pathways for pandemic-responsive platforms.
Microneedle array patches are decentralizing delivery infrastructure for inactivated influenza and polio boosters. Community health workers in rural India and Kenya are piloting thermostable formulations that eliminate refrigeration requirements. This technology is decentralizing administration from centralized clinics to village-level distribution points, compressing the cost per fully immunized child by eliminating transport logistics.
The EU Green Deal is embedding carbon footprint thresholds into vaccine procurement specifications for EMA-authorized suppliers. Cold-chain logistics providers must now document refrigerant leakage rates and renewable energy sourcing across distribution networks. European public health systems are responding by consolidating tenders around manufacturers with ISO 14001-certified production facilities.
Direct-to-government contracting is displacing multilateral agency intermediation for outbreak stockpile procurement. Brazil's Ministry of Health and Saudi Arabia's SFDA are establishing bilateral purchase agreements for emergency yellow fever and meningococcal reserves. This pattern is most visible in middle-income countries with mature national regulatory authorities seeking supply security outside UNICEF allocation frameworks.
Inactivated Vaccines Market Segmentation
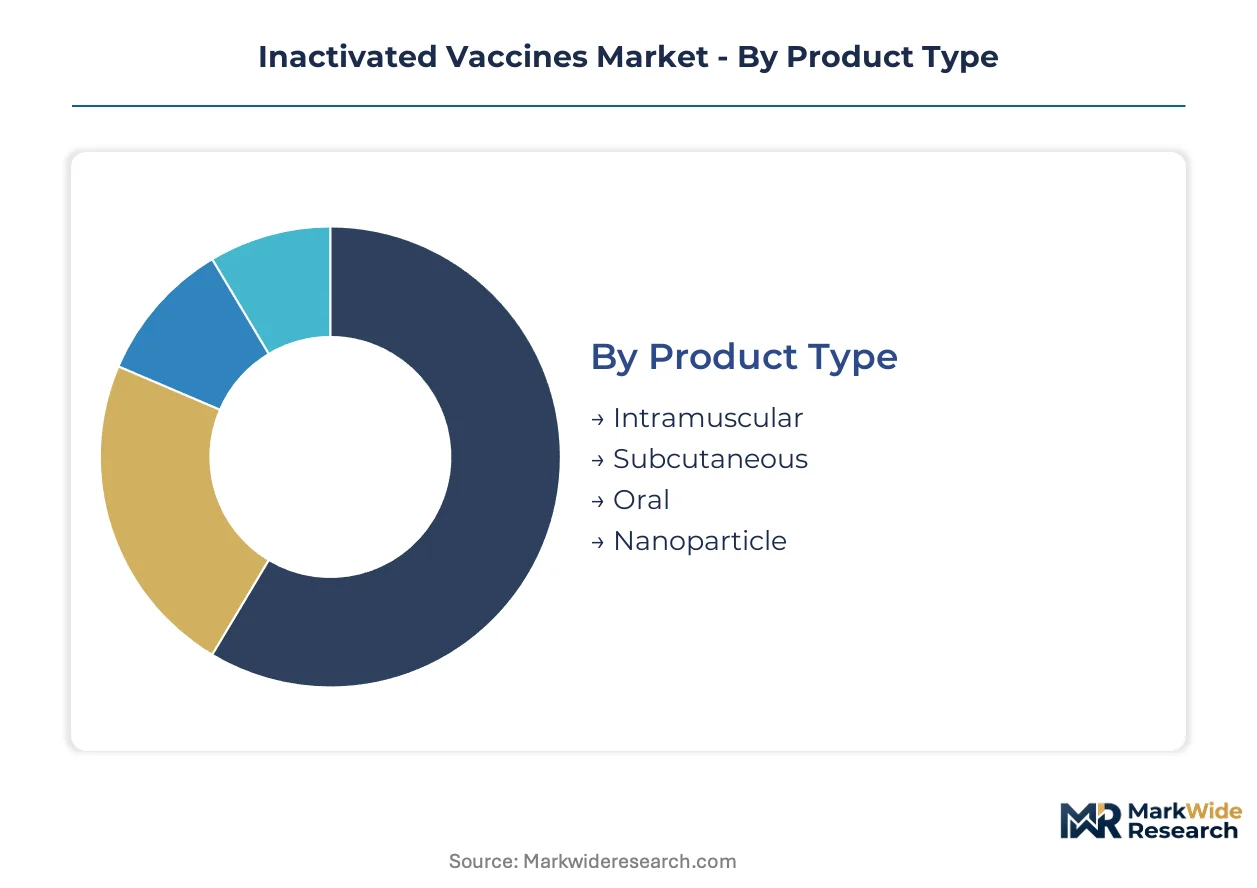
Inactivated vaccines fragment across administration routes, delivery technologies, and procurement channels. Each segment carries distinct cold-chain requirements, pricing power, and regulatory validation burdens that reshape manufacturer portfolio priorities.
Product Type:
Standalone administration dominates routine immunization schedules, while embedded nanoparticle systems integrate adjuvant and carrier functions into unified delivery platforms.
- Intramuscular:The deltoid and vastus lateralis injection sites accommodate larger antigen loads with established healthcare worker proficiency. Demand concentrates in India's universal immunization program and Nigeria's Gavi-supported campaigns, where muscle deposition ensures reliable immune response in populations with variable nutritional status.
- Nanoparticle:Lipid and polymeric carriers encapsulate antigens to enhance dendritic cell uptake and enable dose sparing. Pediatric formulations in Ethiopia and the Democratic Republic of Congo are piloting these systems to stretch limited supply budgets.
- Subcutaneous:Fat-layer deposition suits heat-labile antigens requiring slower release kinetics.
- Oral:Enteric-coated capsules bypass cold-chain dependencies for polio boosters in remote distribution settings.
Volume placements concentrate in intramuscular formats; the faster expansion belongs to nanoparticle carriers.
Delivery Mode:
Cost tiers separate premium pre-filled systems from standard vial presentations, with auto-injectors occupying a mid-tier position defined by safety-engineered features.
- Pre-filled Syringe:Single-unit packaging eliminates multi-dose vial contamination risk and reduces reconstitution errors. UNICEF procurement in Kenya and Bangladesh has shifted toward these formats for outreach campaigns where field conditions compromise aseptic technique.
- Vial:Multi-dose glass containers retain dominance in institutional settings with trained staff and controlled environments. Brazil's Ministry of Health maintains strategic reserves in 10-dose vials for yellow fever emergency response.
- Syringe:Conventional needle-and-barrel combinations persist in cost-sensitive public health systems.
- Auto-Injector:Spring-loaded devices with needle shields protect community health workers in India's village-level distribution networks.
Cost efficiency keeps vial presentations at highest volume; pre-filled syringes are climbing the fastest.
End User:
Customer type determines batch size, documentation requirements, and service intensity, with public systems prioritizing throughput over customization.
- Public Health Units:Government-operated cold-chain networks handle bulk procurement for national immunization days. India's state-level vaccine stores distribute to over 25,000 peripheral centers, with wastage monitoring mandated under the Universal Immunization Programme.
- Hospitals:Tertiary centers manage complex cases requiring serological testing before administration. Saudi Arabia's SFDA-regulated facilities maintain surge capacity for Hajj-associated meningococcal vaccination.
- Clinics:Private practice settings serve travel medicine and occupational health segments.
- Research Laboratories:Phase III trial sites generate demand for investigational lots with customized potency specifications.
Procurement scale peaks at public health units; hospitals show the steepest expansion trajectory.
Application:
Maturity levels separate established preventive programs from emergency response mechanisms, with outbreak control commanding premium pricing during stockpile activation.
- Preventive Care:Scheduled administration through national immunization programs generates predictable, recurring demand. India's pentavalent and rotavirus coverage targets drive annual procurement cycles with 3-5 year supply agreements.
- Outbreak Control:Emergency procurement for yellow fever and meningococcal response bypasses standard tender timelines. Brazil's direct-to-government contracting for Amazon basin reserves illustrates this pattern.
- Travel Vaccination:Pre-departure requirements for Hajj, Umrah, and tropical deployment create seasonal demand spikes.
- Pediatric Use:Birth-cohort targeting shapes hexavalent and pentavalent combination demand curves.
Programmatic stability anchors preventive care volumes; outbreak control shows the most volatile expansion pattern.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune anchors global inactivated vaccine production through Serum Institute of India's integrated campus, supplying UNICEF and Gavi-eligible markets with pentavalent and polio formulations manufactured at industrial scale.
United States
FDA lot-release testing requirements for influenza and polio vaccines compress working capital cycles for domestic manufacturers. The Biomedical Advanced Research and Development Authority maintains strategic stockpiles through direct contracting mechanisms. Maryland's I-270 biotech corridor hosts adjuvant research facilities optimizing toll-like receptor agonist combinations for enhanced immunogenicity.
India
Universal Immunization Programme procurement drives volume demand for domestically manufactured pentavalent and rotavirus vaccines across 25,000 peripheral distribution centers. CDSCO streamlined registration pathways accelerate WHO prequalification timelines for export-oriented producers. Hyderabad's Genome Valley clusters bulk antigen manufacturing with fill-finish operations serving African and Southeast Asian markets.
Germany
EMA carbon footprint thresholds embedded in EU Green Deal procurement specifications reshape cold-chain logistics requirements for influenza vaccine tenders. The Paul-Ehrlich-Institut enforces stringent potency consistency standards for inactivated viral formulations. Marburg's vaccine production hub integrates single-use bioreactor platforms with downstream purification trains originally designed for stainless-steel vessels.
Brazil
Direct-to-government contracting for yellow fever emergency stockpiles bypasses traditional UNICEF allocation frameworks. ANVISA's national regulatory authority status enables bilateral purchase agreements with manufacturers seeking supply security. São Paulo's Butantan Institute anchors regional production capacity for meningococcal and pentavalent combination vaccines distributed across Amazon basin states.
Saudi Arabia
Hajj and Umrah pilgrimage requirements generate seasonal demand spikes for meningococcal vaccination administered through SFDA-regulated facilities. National immunization schedule expansion targets underimmunized birth cohorts with hexavalent formulations. Riyadh's King Faisal Specialist Hospital maintains surge capacity for outbreak response stockpiles serving the Gulf Cooperation Council region.
Inactivated Vaccines Market Competitive Landscape
Premium-margin players sit above commodity-margin players across adjuvant technology and manufacturing scale dimensions. The vendor base concentrates among integrated multinationals with cell-culture platforms and emerging market specialists with egg-based legacy capacity. Three archetypes dominate: R&D-intensive innovators with proprietary adjuvant pipelines, scale-driven bulk suppliers serving UN procurement channels, and regional fill-finish operators capturing government tenders. Competitive moves center on nanoparticle delivery system licensing and backward integration into squalene raw material sourcing.
Within the scale-driven tier, Serum Institute of India Pvt. Ltd and Sinovac Biotech Ltd occupy positions exemplifying volume-oriented manufacturing archetypes, while Sanofi and GSK plc represent R&D-intensive innovators with integrated adjuvant capabilities. Sanofi, a French société anonyme, anchors premium positioning through multi-continental manufacturing networks. GSK plc, a UK public limited company, exemplifies sustained investment in immunogenicity enhancement technologies. Serum Institute of India Pvt. Ltd, a Pune-based private limited entity, represents the emerging market specialist archetype through its status as the world's largest vaccine manufacturing facility by volume.
| Leading Market Players |
|---|
| Sanofi |
| GSK plc |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Bharat Biotech |
| Serum Institute of India Pvt. Ltd |
| Sinovac Biotech Ltd. |
| Sinopharm |
| Valneva SE |
| Others |
Supply & Pricing Matrix
Adjuvant formulation specialists in Maryland's I-270 biotech corridor command premium compensation that widens spreads between R&D-intensive premium tiers and commodity bulk supply. Labor-cost differentials between US-based toll-like receptor agonist developers and Indian fill-finish operators translate into three-tier pricing stratification across WHO-prequalified, EMA-authorized, and domestic-only product grades.
Pricing Analysis
Throughput-based contract structures anchor government procurement for national immunization programs, with price differentiation driven by WHO prequalification status and cold-chain certification grade. UNICEF tender awards for pentavalent and polio formulations compress margins in the economy tier, while outbreak stockpile premiums sustain higher pricing for yellow fever and meningococcal reserves. Cost compression in the standard tier intensifies as Serum Institute of India and Sinovac Biotech expand cell-culture capacity. Public health units exhibit highest price sensitivity; private hospital systems in Saudi Arabia and Brazil show lowest sensitivity due to direct-to-government contracting mandates.
Supply Chain Analysis
Freight costs for 2-8°C controlled logistics consume disproportionate share of landed cost in tropical last-mile distribution, particularly across sub-Saharan Africa and Southeast Asian archipelagos. Bulk antigen manufacturing concentrates in India, China, and Germany, with fill-finish operations drawing from Pune, Hyderabad, and Marburg production hubs. Squalene and aluminum salt adjuvants hinge on three specialty chemical suppliers, creating single-source vulnerability for immunogenicity-enhanced formulations. Distribution runs through UNICEF's Copenhagen supply division and bilateral government tenders, with emergency stockpiles bypassing standard allocation frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inactivated vaccine manufacturing is becoming a vertical-integration race as players pursue captive supply of squalene raw materials and nanoparticle carrier technologies to defend margin structure against adjuvant cost volatility.
For Market Incumbents: Lock in backward integration into squalene sourcing and aluminum salt processing to neutralize input cost volatility from specialty chemical suppliers. Expand cell-culture capacity in India and Germany to displace egg-based legacy methods before viral vector platforms capture influenza indication share. Secure ISO 14001 certification for carbon-neutral cold-chain logistics to capture EU Green Deal procurement preference. For New Entrants and Emerging Players: The mid-tier price-point gap between GSK plc's premium adjuvant formulations and Indian bulk suppliers presents white-space opportunity for nanoparticle carrier licensing plays. Target Ethiopia and Democratic Republic of Congo for pentavalent volume penetration through Gavi co-financing mechanisms. Pursue WHO prequalification acceleration via CDSCO streamlined pathways to unlock UNICEF supply contracts. For Investors and Strategic Acquirers: Re-rating potential sits with adjuvant platform specialists given EMA's evolving guidance on toll-like receptor agonist combinations. Long-term viability favors manufacturers with integrated cell-culture and single-use bioreactor capabilities over egg-based legacy operators. Watch FDA lot-release testing timeline extensions as inflection indicator for working capital compression across US-focused portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Adjuvant Platform Licensing | Proprietary toll-like receptor agonist combinations command premium positioning in EMA-authorized tenders. |
| Cell-Culture Manufacturing Scale-Up | Serum-free platforms displace egg-based methods, reducing batch variability for influenza supply contracts. |
| WHO Prequalification Acceleration | Streamlined CDSCO pathways compress registration timelines for UNICEF and Gavi-eligible market access. |
| Sustainable Cold-Chain Certification | ISO 14001 credentials unlock EU Green Deal procurement preference for carbon-neutral distribution networks. |
| Direct-to-Government Contracting | Bilateral agreements with Brazil's ANVISA and Saudi Arabia's SFDA bypass UNICEF allocation frameworks. |
Research Methodology
Multi-period observation of WHO prequalification timelines, Gavi disbursement cycles, and national immunization program procurement volumes anchored the trend analysis, supplemented by interviews with vaccine development executives, regulatory affairs leads at CDSCO and ANVISA, UNICEF supply division procurement managers, and cold-chain logistics operators. Secondary validation drew from FDA lot-release databases, EMA assessment reports, WHO prequalification listings, and national universal immunization program coverage statistics. Bottom-up manufacturer capacity data triangulated against top-down procurement flow analysis.
Input-output matrix modeling connected antigen production capacity, adjuvant raw material supply, and distribution network throughput across the projection horizon. Segmentation dimensions included administration route, delivery technology, end-user archetype, and regional regulatory cluster. CAGRs were derived from weighted regression of historical procurement volumes against immunization schedule expansion targets and outbreak stockpile activation patterns. Forecast inputs incorporated cell-culture platform adoption curves and nanoparticle formulation pipeline maturity.
Inputs from WHO prequalification records and national regulatory authority filings were available through the study window; gaps in real-time cold-chain wastage monitoring across sub-Saharan Africa introduce uncertainty bands around last-mile distribution cost assumptions. Forecasts reflect documented assumptions about Gavi co-financing continuity and EMA carbon footprint threshold implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Peptide Antibiotics Market
Biopharmaceuticals
Protein Kinase B Inhibitors Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Global Myelodysplastic Syndrome (MDS) Drugs Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Global CIS Insulin Market