
 North Africa Generic Drug Market | 2026-2036
North Africa Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Generic Drug Market Intelligence
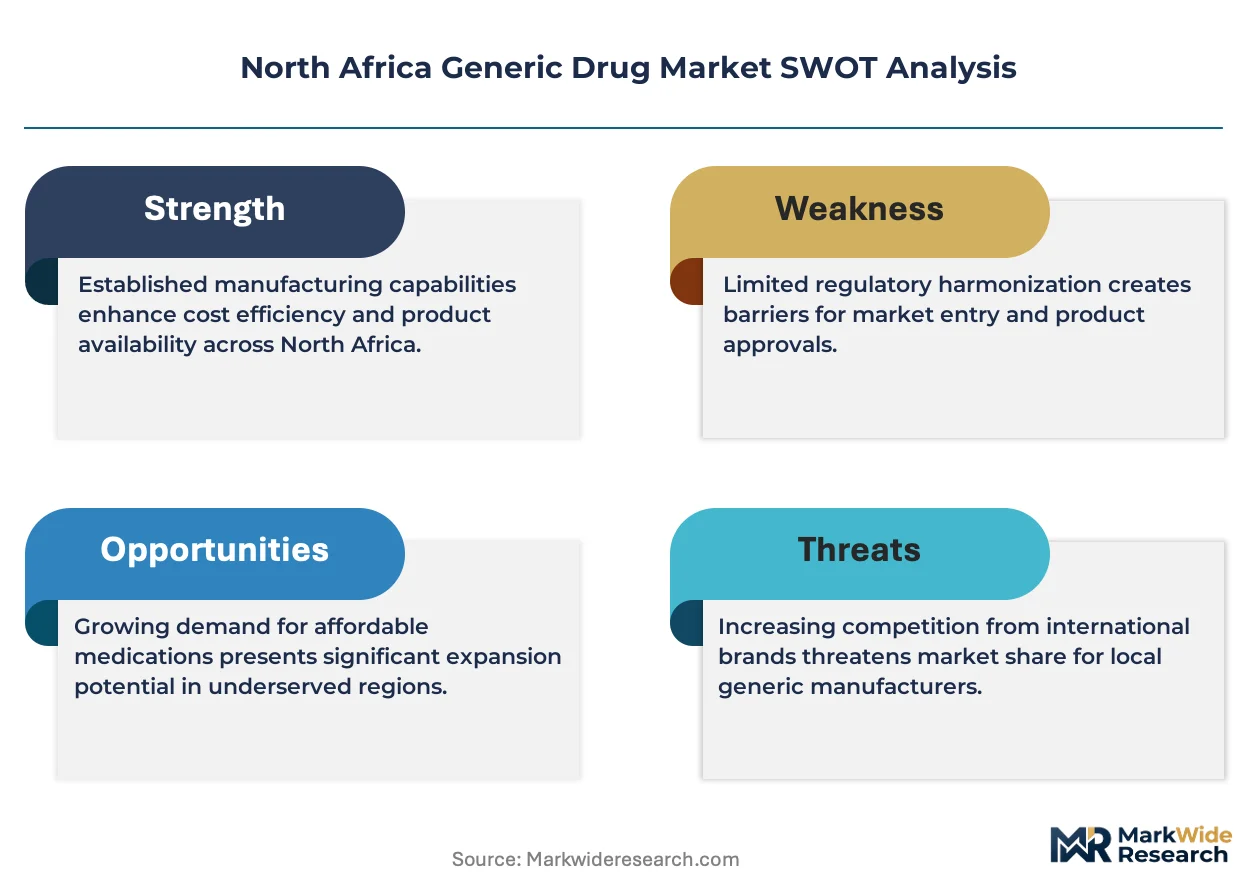
Hospital procurement is expanding as the dominant demand channel across North Africa, with public health systems prioritizing affordable therapeutic access. Teva Pharmaceutical Industries leverages its broad portfolio to anchor tenders in multiple North African markets. Sandoz International sustains manufacturing scale advantages through its established regional supply infrastructure. Ciplamed competes on localized production capabilities that reduce import dependency for Egyptian health authorities.
Generic drugs are chemically equivalent copies of originator pharmaceuticals, manufactured after patent expiry and required to demonstrate bioequivalence through pharmacokinetic studies before regulatory approval. Their primary purpose is to deliver identical therapeutic outcomes at substantially lower cost, enabling health system sustainability across emerging economies. Prescription generics occupy the largest volume share, while biosimilars represent the fastest-expanding margin pool as biologic patents expire. Oral delivery dominates unit volumes, though injectable formats command premium positioning in hospital settings.
Egypt's Ministry of Health and Population enforces local pricing ceilings that shape product registration decisions, while Morocco's Ministry of Health applies WHO-prequalification standards as a market access filter. Algeria's national pharmaceutical regulator mandates local partnership requirements for import authorization, redirecting foreign company strategies toward joint manufacturing arrangements. Stakeholders must monitor how evolving local-content rules and tender centralization reshape competitive positioning across the Maghreb.
Market Dynamics
Public hospital procurement centralization across Egypt, Morocco, and Algeria is compressing supplier margins while amplifying volume concentration among manufacturers with localized production capabilities. Governments are consolidating tender mechanisms to extract cost efficiencies from pharmaceutical spending.
Growth Catalysts
- Egyptian local production incentives:Ministry of Health and Population policies mandating domestic manufacturing for import authorization are redirecting foreign investment toward joint ventures with Egyptian pharmaceutical firms.
- Biologic patent expiry waves:The expanding pipeline of off-patent biologics is creating regulatory and commercial pathways for biosimilar registration across North African health authorities.
- Hospital formulary expansion:Public health systems in Morocco and Algeria are widening generic substitution mandates for chronic disease management, pulling volume from originator brands.
Market Restraints
- Active pharmaceutical ingredient import dependency:Regional manufacturers rely on Chinese and Indian API suppliers, exposing production schedules to shipping volatility and currency fluctuation.
- WHO-prequalification barriers:Morocco's Ministry of Health applies this standard as a market access filter, disqualifying products that lack international certification and limiting supplier pools.
- Originator brand loyalty in private channels:Physician prescribing habits and patient brand recognition sustain premium pricing for patented alternatives outside public procurement.
Strategic Opportunities
- Algerian joint manufacturing requirements:National pharmaceutical regulator mandates for local partnership create entry pathways for foreign firms through technology transfer arrangements.
- Injectable format premiumization:Hospital demand for sterile parenteral generics in oncology and anesthesia offers margin expansion beyond oral commoditized segments.
- Regional tender platform consolidation:Emerging cross-border procurement cooperation between Maghreb health ministries could reward manufacturers with multi-country supply infrastructure.
Industry Challenges
- Bioequivalence study capacity constraints:Limited regional clinical pharmacology units delay generic registration timelines and extend time-to-market for new filings.
- Cold chain distribution infrastructure gaps:Temperature-sensitive biologics and injectables require capital investment in refrigerated logistics networks that many distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Generic Drug Market |
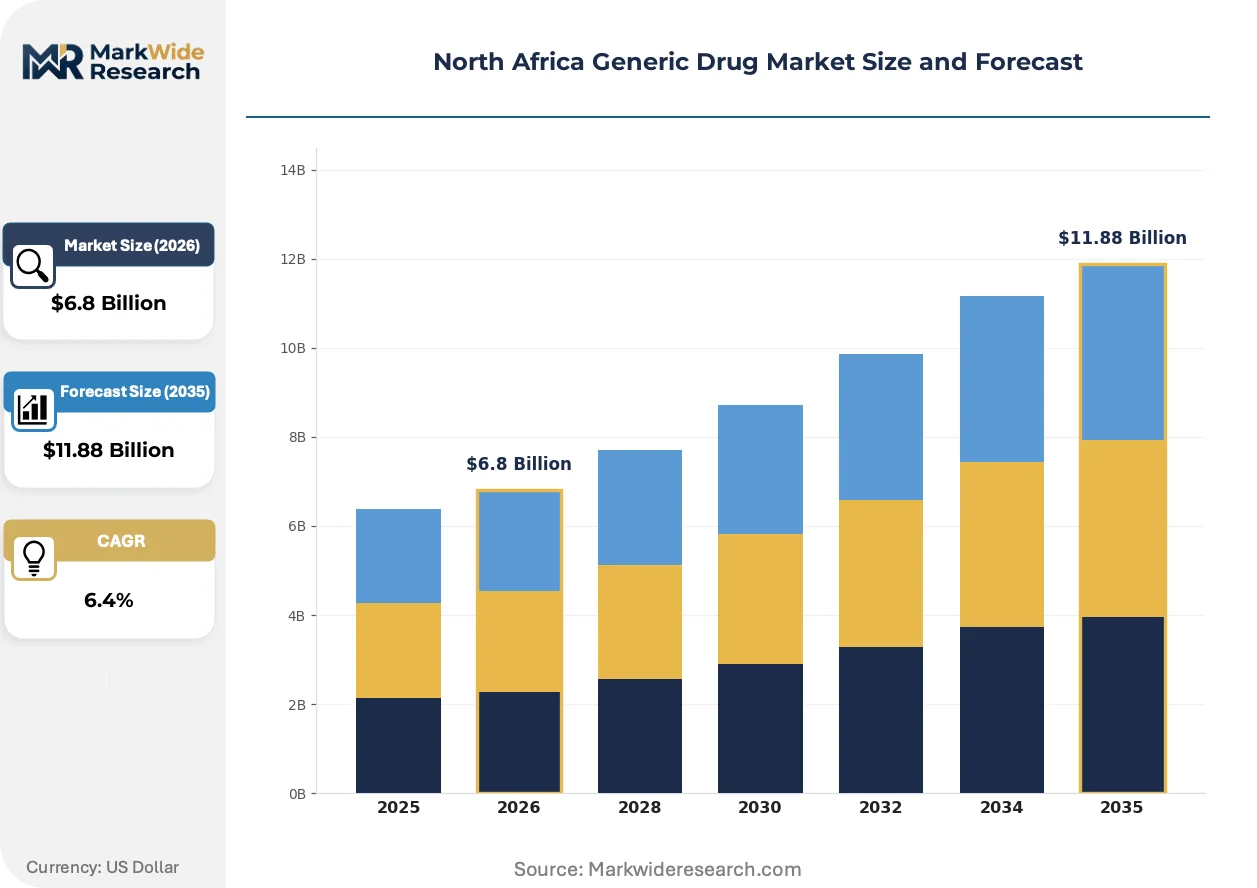
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription, Over-the-Counter, Biosimilars, Injectables Therapy Area: Cardiovascular, Oncology, Hormonal, Infectious Diseases Delivery Mode: Oral, Topical, Injectable, Transdermal End User: Hospitals, Pharmacies, Clinics, Home Care |
| Companies Covered | Teva Pharmaceutical Industries, Sandoz International, Mylan (Viatris), Sun Pharmaceutical Industries, Ciplamed, Dr. Reddy's Laboratories, Aurobindo Pharma, Alkaloid, Unimed, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing technologies and digital quality systems are compressing production batch cycles while tightening pharmacovigilance standards across North African regulatory environments. These shifts favor capitalized manufacturers over trading-dependent importers.
Continuous processing equipment is rewriting batch economics for oral solid dose production. Egyptian manufacturers with GMP-certified facilities are adopting these systems to reduce unit costs and meet tender volume requirements. The technology is compressing lead times from API to finished dose, enabling just-in-time inventory for hospital procurement cycles.
Morocco's Ministry of Health is tightening WHO-prequalification alignment for all imported generics, effectively harmonizing local standards with international procurement benchmarks. This policy is elevating documentation and inspection burdens for suppliers. Foreign manufacturers without existing WHO certification are redirecting resources toward prequalification audits or exiting tender participation.
Centralized hospital purchasing is consolidating supplier relationships around single-source contracts for therapeutic categories. Moroccan and Algerian public health authorities are replacing fragmented hospital-level buying with regional tender boards. Egypt's Ministry of Health and Population piloted this model in Cairo and Alexandria before national expansion, concentrating volume among three to five approved suppliers per molecule.
North Africa Generic Drug Market Segmentation
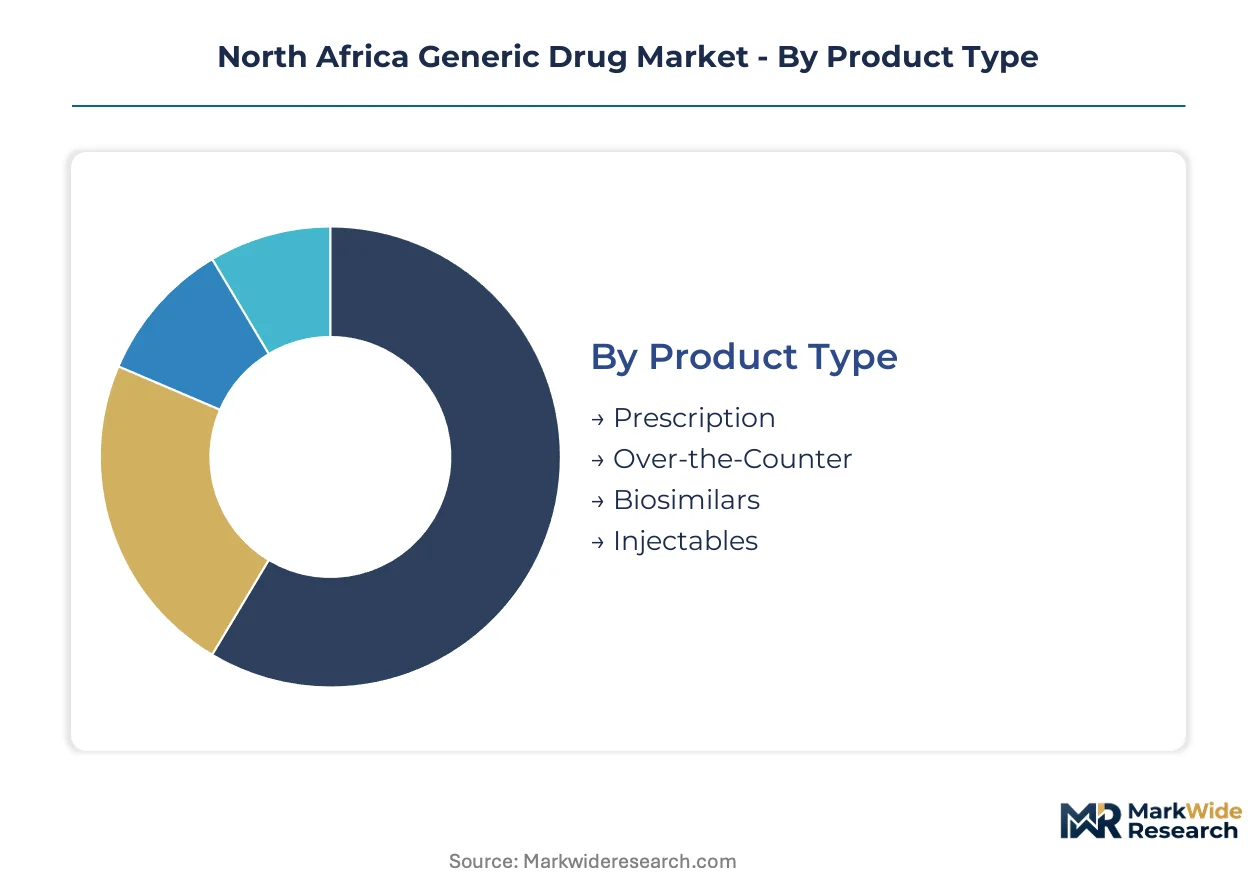
Segmentation reveals how procurement centralization and regulatory requirements reshape competitive positioning across North Africa's generic drug landscape. Each dimension carries distinct certification burdens and margin structures that determine manufacturer viability.
Product Type:
Prescription generics and biosimilars demand WHO-prequalification or Egyptian Ministry of Health and Population registration, while over-the-counter products face lighter documentation requirements.
- Prescription:Chemically equivalent copies of originator drugs requiring bioequivalence demonstration through pharmacokinetic studies. Egyptian public hospital procurement concentrates volume here as formulary expansion mandates generic substitution for chronic disease management.
- Biosimilars:Large-molecule therapeutics manufactured after biologic patent expiry with immunogenicity and analytical comparability requirements. Moroccan health authorities apply stringent WHO-prequalification alignment, compressing supplier pools to certified manufacturers.
- Over-the-Counter:Self-medication products with abbreviated registration pathways.
- Injectables:Sterile parenteral formulations requiring aseptic manufacturing capabilities.
Prescription sits at the top of the volume ranking, with Biosimilars climbing the fastest.
Therapy Area:
Cost tier differentiation separates chronic disease maintenance therapies from acute intervention categories across tender mechanisms.
- Cardiovascular:Antihypertensive and lipid-lowering agents dominating chronic prescription volumes. Algerian regional tender boards consolidate procurement for these high-frequency maintenance therapies, rewarding manufacturers with localized production.
- Oncology:Cytotoxic and targeted therapies with cold chain and handling complexity. Egyptian hospital procurement pulls volume as cancer incidence rises and biosimilar alternatives to monoclonal antibodies enter registration pipelines.
- Hormonal:Endocrine therapies including insulin and thyroid replacements.
- Infectious Diseases:Antibiotic and antiviral agents with resistance surveillance requirements.
Cardiovascular captures the largest tender allocation, while Oncology gains share fastest on biologic substitution.
Delivery Mode:
Supply concentration patterns diverge sharply between commoditized oral formats and capital-intensive sterile manufacturing.
- Oral:Tablet and capsule formulations with established regional manufacturing capacity. Egyptian continuous processing adoption compresses unit costs for tender volume requirements.
- Injectable:Parenteral products commanding premium positioning in hospital settings. Cold chain infrastructure gaps constrain distribution reach to major urban centers.
- Topical:Dermal and mucosal preparations with localized manufacturing feasibility.
- Transdermal:Patch-based delivery with specialized adhesive and permeation technology requirements.
Oral dominates unit volumes, with Injectable expanding most quickly on hospital formulary premiumization.
End User:
Customer type determines pricing flexibility and brand loyalty exposure across public and private channels.
- Hospitals:Public health system procurement with centralized tender mechanisms and generic substitution mandates. Moroccan and Algerian regional boards concentrate volume among approved suppliers per therapeutic category.
- Pharmacies:Retail dispensing with originator brand persistence in private payment segments.
- Clinics:Outpatient facilities with mixed procurement autonomy.
- Home Care:Patient-administered therapies with reimbursement pathway dependencies.
Hospitals anchor procurement volume, with Home Care showing steepest expansion on chronic disease management decentralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined bioequivalence pathways and localized production incentives. Egypt's cost-of-compliance gap relative to European standards attracts joint-venture formation, while Morocco's WHO-prequalification alignment elevates entry barriers that certified manufacturers exploit.
Egypt
Public hospital procurement centralization and chronic disease formulary expansion drive volume concentration. The Ministry of Health and Population enforces domestic manufacturing mandates for import authorization, redirecting foreign capital toward Egyptian joint ventures. Cairo and Alexandria anchor production clusters where continuous processing adoption compresses unit costs for tender participation.
Morocco
WHO-prequalification alignment and regional tender board consolidation reshape competitive access. The Ministry of Health applies international certification as a market filter, compressing supplier pools to audited manufacturers. Casablanca-Rabat corridor concentrates distribution infrastructure serving Maghreb procurement cooperation pilots.
Algeria
Joint manufacturing requirements and technology transfer mandates redirect foreign entry strategies. The national pharmaceutical regulator conditions import authorization on local partnership structures, favoring manufacturers with captive production capabilities. Oran and Constantine host emerging sterile manufacturing clusters serving hospital injectable demand.
Tunisia
Smaller-scale procurement centralization and chronic disease management programs pull generic substitution volumes. The national health authority maintains lighter registration burdens than Maghreb neighbors, attracting trading-oriented distributors. Tunis-Sfax axis concentrates pharmaceutical logistics serving public hospital networks.
Libya
Import-dependent supply reconstruction and fragmented procurement create volatile demand patterns. The national pharmaceutical oversight body operates with limited regulatory capacity, exposing channels to quality variation risks. Tripoli and Benghazi distribution hubs rebuild cold chain infrastructure for temperature-sensitive therapies.
North Africa Generic Drug Market Key Industry Players
Capacity expansion dominates the current landscape as manufacturers localize production to satisfy Egyptian and Algerian domestic-content requirements. The market structures around three tiers: multinational subsidiaries with regional GMP-certified facilities, mid-scale regional producers with tender specialization, and import-dependent traders facing margin compression. Strategic archetypes include joint-venture operators leveraging technology transfer, continuous-processing adopters competing on unit economics, and WHO-prequalified specialists accessing Moroccan premium segments. M&A activity and sterile manufacturing capacity expansion constitute the dominant competitive moves.
Among multinational generic manufacturers, Teva Pharmaceutical Industries and Sandoz International exemplify the joint-venture archetype through established regional supply infrastructure. Ciplamed occupies a position representing localized production capabilities that reduce Egyptian import dependency. These three anchors demonstrate how certification depth and manufacturing proximity determine tender access across North African procurement centralization.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Sandoz International |
| Mylan (Viatris) |
| Sun Pharmaceutical Industries |
| Ciplamed |
| Dr. Reddy's Laboratories |
| Aurobindo Pharma |
| Alkaloid |
| Unimed |
| Others |
Cost & Logistics Intelligence
Pharmaceutical formulation chemists concentrated in Cairo and Alexandria anchor North Africa's cost-competitive manufacturing base, with labor-cost differentials against European standards enabling three-tier pricing stratification across WHO-prequalified, locally certified, and import-dependent supply tiers.
Pricing Analysis
Distributor margin compression in Egyptian public tender channels is intensifying as the Ministry of Health and Population consolidates procurement around single-source contracts per therapeutic category. Price differentiation hinges on WHO-prequalification status and local manufacturing certification, with hospital buyers exhibiting highest sensitivity in oral commoditized segments and lowest sensitivity in cold-chain injectables where sterile capabilities are scarce.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian active pharmaceutical ingredient suppliers, exposing Egyptian and Moroccan finished-dose manufacturers to shipping volatility and currency fluctuation. Regional production draws from imported APIs, excipients, and packaging materials, with tariff exposure on API imports compounding margin pressure. Distribution runs through state-appointed hospital procurement boards and fragmented retail pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North Africa's generic drug sector functions as a regulatory compounder, with Egyptian domestic manufacturing mandates and Moroccan WHO-prequalification alignment driving demand concentration toward certified local producers.
For Market Incumbents: Deepen backward integration into API sourcing through Egyptian joint-venture structures to offset import dependency risks. Expand sterile manufacturing capacity in Algerian Oran and Constantine clusters to capture injectable premiumization. Sandoz International and Teva Pharmaceutical Industries must defend tender positions against Indian biosimilar entrants by accelerating technology transfer partnerships. For New Entrants and Emerging Players: Algerian joint manufacturing requirements open a window for technology-transfer arrangements with established regional producers. Target Egyptian chronic disease segments where formulary expansion mandates generic substitution, and pursue WHO-prequalification to access Moroccan regional tender boards. A go-to-market angle through hospital formulary committees in Casablanca-Rabat corridor offers fastest volume accumulation. For Investors and Strategic Acquirers: Mid-cap pharmaceutical manufacturers with captive Egyptian production assets are the most active acquirer targets in this space. Long-term viability centers on regulatory certification depth rather than trading margins, favoring GMP-certified facilities over import-dependent distributors. Watch for biosimilar registration pipeline acceleration at Egyptian Ministry of Health and Population as inflection indicator for oncology segment premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| WHO-Prequalification Investment | Egyptian and Moroccan regulators elevate documentation burdens, filtering supplier pools to audited manufacturers. |
| Joint Manufacturing Partnership | Algerian import authorization rules redirect foreign capital toward technology transfer with local firms. |
| Sterile Injectable Capacity Expansion | Hospital demand for oncology and anesthesia parenterals commands margin premiums beyond oral commoditization. |
| Continuous Processing Adoption | Cairo-based manufacturers compress batch economics to meet centralized tender volume requirements. |
| Regional Tender Platform Integration | Cross-border procurement cooperation between Maghreb health ministries rewards multi-country supply infrastructure. |
Research Approach
Multiple input streams — primary interviews with hospital procurement managers, regulatory affairs leads, and pharmaceutical manufacturing executives; secondary validation through EMA submissions, Egyptian Ministry of Health and Population registration databases, and WHO-prequalification listings; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from formulary directors and tender board administrators across the projection horizon. Segmentation modeling incorporated therapy area, delivery mode, and regulatory certification tier dimensions. CAGRs were derived from therapeutic-category growth rates weighted by tender allocation shifts, with biologic patent expiry waves and local production incentive policies serving as key forecast inputs.
Revisions become necessary when Egyptian pricing ceiling adjustments, Algerian partnership rule changes, or API supply disruptions materialize. Forecasts reflect documented assumptions around regulatory continuity and hospital procurement centralization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
East Africa Generic Drug Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Insulin Aspart Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
Global Infertility Drugs Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market