
 Gypsum-Free Lactic Acid Market | 2026-2036
Gypsum-Free Lactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Gypsum-Free Lactic Acid Market Foresight
Project finance for fermentation-capacity expansion is tilting competitive dynamics toward firms with balance-sheet depth and offtake partnerships. Henan Jindan Lactic Acid Technology leverages captive starch supply to anchor cost positions in food-grade output. Corbion sustains technology leadership through continuous fermentation optimization. NatureWorks competes by integrating downstream into Ingeo biopolymer production, locking polymer-grade demand.
Gypsum-free lactic acid denotes fermentation-derived lactic acid purified without calcium sulfate precipitation, typically achieving optical purity above 99.5 percent through membrane filtration and electrodialysis, serving as a platform chemical for biodegradable polymers, pH regulation, and active pharmaceutical intermediates. Food-grade material dominates volume flows given preservative and flavoring demand across processed food supply chains, while pharmaceutical-grade commands premium pricing due to USP and EP compliance burdens. Bioplastics application represents the fastest-expanding consumption pool as polylactic acid resin capacity scales in Europe and Asia.
FDA purity standards for pharmaceutical-grade lactic acid and EU REACH registration requirements for industrial chemical placement constrain market entry and elevate compliance spending for new fermentation operators. The EPA's renewable fuel standard framework and USDA bio-preferred procurement guidelines indirectly channel capital toward gypsum-free processing routes that reduce waste salt generation. Stakeholders must monitor fermentation yield advances and carbon-source diversification to assess which purification technology platforms will achieve cost parity with conventional gypsum-based recovery.
Market Dynamics
Fermentation-capacity expansion is concentrating competitive advantage among firms with captive starch supply and membrane filtration expertise. The shift from calcium sulfate precipitation to electrodialysis purification is redrawing cost curves and compliance thresholds across pharmaceutical and bioplastic feedstock tiers.
Growth Catalysts
- EU Green Deal implementation:REACH compliance frameworks are tightening purity requirements for fermentation-derived acids, accelerating demand for gypsum-free processing routes that eliminate waste salt generation.
- Polylactic acid resin scaling:Bioplastic producers in Germany and the Netherlands are expanding offtake agreements for polymer-grade feedstock to supply packaging converters.
- Membrane filtration maturation:Electrodialysis and nanofiltration systems are achieving optical purity above 99.5 percent at commercial scale, enabling pharmaceutical-grade certification.
Market Restraints
- Feedstock cost volatility:Corn and cassava starch prices fluctuate with agricultural commodity cycles, compressing margins for fermentation operators without backward integration into crop processing.
- Purification capex intensity:Electrodialysis stack replacement and membrane cleaning protocols require sustained capital deployment that disadvantages smaller fermentation entrants.
- USP/EP certification timelines:FDA and EMA pharmaceutical-grade validation processes extend 18-24 months, creating regulatory friction for new market participants.
Strategic Opportunities
- Carbon-source diversification:Lignocellulosic feedstock conversion and agricultural waste streams offer defensible cost positions for operators investing in C5/C6 sugar fermentation.
- Active pharmaceutical intermediate expansion:Chiral synthesis applications for gypsum-free lactic acid derivatives are penetrating oncology and immunology drug pipelines.
- USDA BioPreferred procurement:Federal purchasing guidelines channel institutional demand toward certified biobased materials, creating preferential access for compliant suppliers.
Industry Challenges
- Specialized fermentation engineering scarcity:Continuous culture optimization and contamination control expertise concentrates among legacy industrial biotechnology hubs, constraining talent mobility.
- Optical purity standardization gaps:D-lactic acid and L-lactic acid specification mismatches between ISO methods and customer protocols create batch rejection risk and contract disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gypsum-Free Lactic Acid Market |
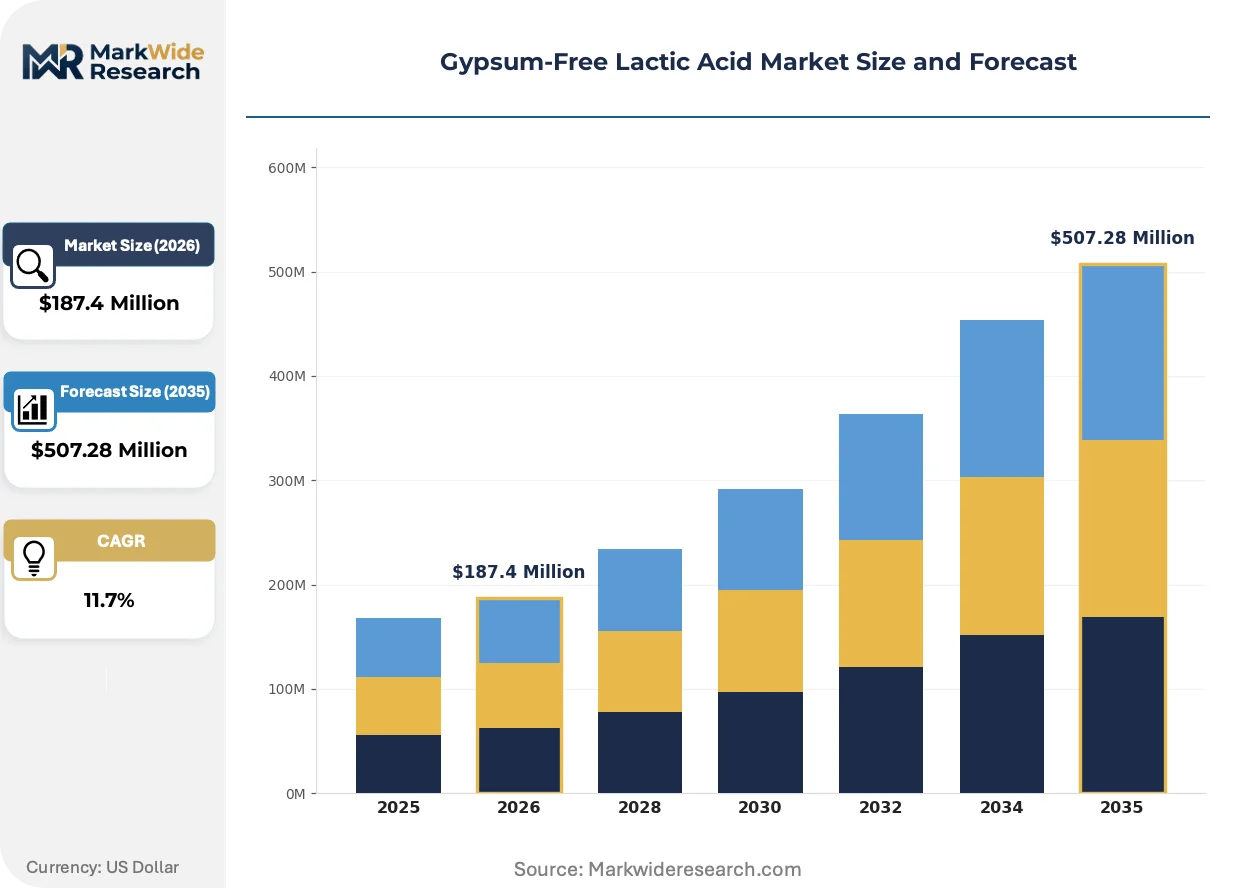
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Cosmetic Grade Application: Food & Beverage, Pharmaceuticals, Personal Care, Bioplastics End User: Food Manufacturers, Cosmetic Brands, Pharmaceutical Companies, Bioplastic Producers Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | Henan Jindan Lactic Acid Technology, Musashino Chemical Laboratory, Corbion, Galactic, Cargill, NatureWorks, BASF, ADM, Jungbunzlauer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gypsum-Free Lactic Acid Market Shifts & Advancements
Purification technology trajectories and regulatory chemistry mandates are converging to favor electrodialysis-based recovery systems. These shifts compress the viability window for conventional gypsum precipitation while elevating optical purity as the decisive competitive variable.
Membrane-based lactic acid recovery is migrating from batch electrodialysis to integrated continuous fermentation-separation systems. Pharmaceutical-grade buyers in Switzerland and Germany are specifying electrodialysis certificates in supply contracts. This migration from conventional precipitation is compressing capital recovery periods for early adopters while stranding gypsum-based capacity.
REACH registration requirements for industrial chemical placement are tightening impurity thresholds for fermentation-derived acids. ECHA's updated guidance on salt waste classification is elevating disposal costs for calcium sulfate byproduct streams. Bioplastic converters in the Netherlands and Belgium are now mandating gypsum-free process documentation to secure polymer-grade certification.
Long-term offtake contracting is displacing spot market purchasing among polylactic acid resin producers. Tier-one packaging-grade buyers in Germany are locking five-year supply agreements with fixed optical purity bands. This behavioral shift is most visible in the Rhine-Ruhr chemical cluster, where specialty converters are consolidating supplier panels to three qualified fermentation operators.
Gypsum-Free Lactic Acid Market Segmentation
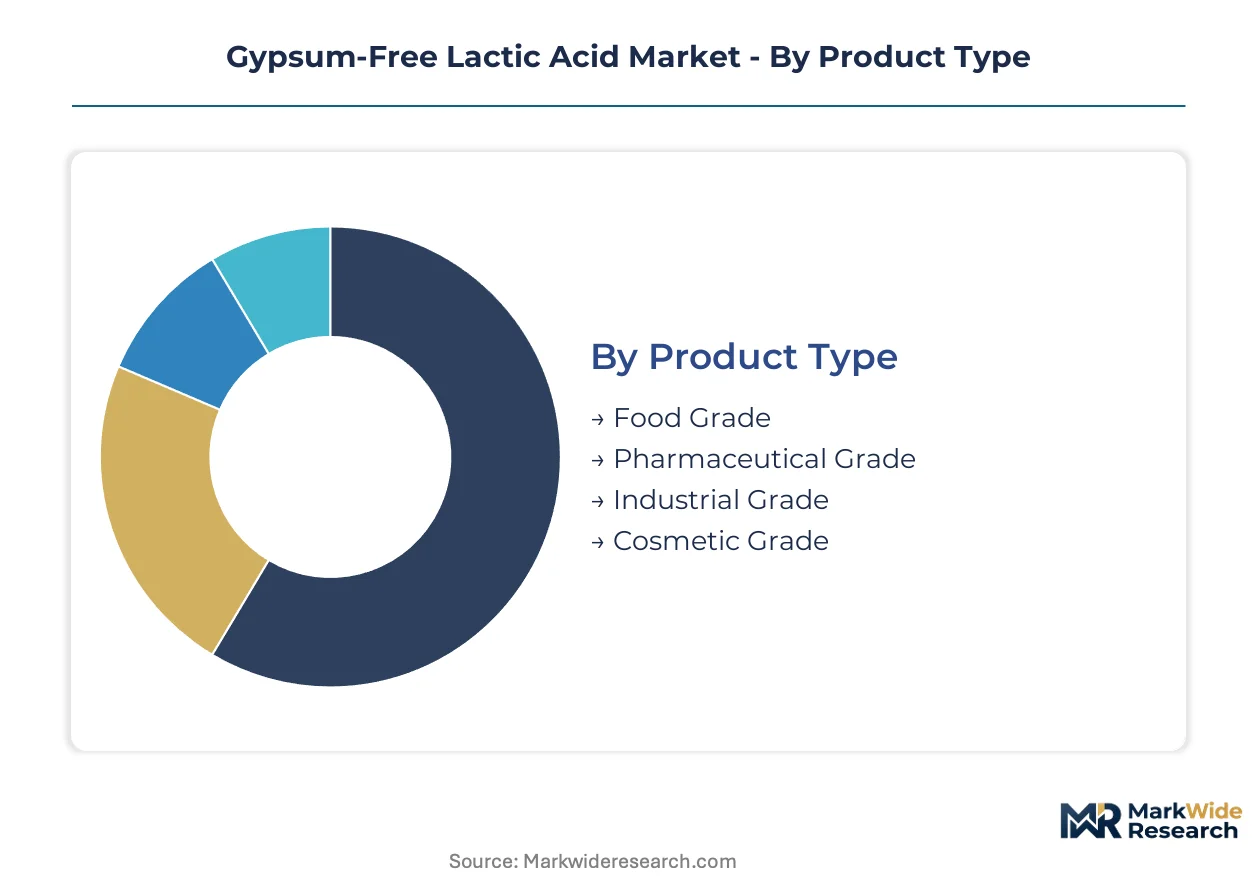
Segmentation in the gypsum-free lactic acid market reflects divergent purity requirements and certification burdens across end-use industries. Each tier demands distinct fermentation optimization and membrane filtration protocols, creating specialized supply relationships that resist commoditization.
Product Type:
Mature grades dominate volume flows while emerging specifications capture margin expansion through pharmaceutical and bioplastic certification.
- Food Grade:Fermentation-derived lactic acid meeting FCC and JECFA standards for pH regulation and preservation in processed foods. Demand concentrates among European dairy processors and Asian noodle manufacturers seeking clean-label acidulants without gypsum residue concerns.
- Pharmaceutical Grade:Material achieving USP and EP monograph compliance with optical purity above 99.5 percent through electrodialysis purification. Swiss and German injectable drug manufacturers are locking multi-year supply agreements to secure chiral intermediate feedstock.
- Industrial Grade:Standard fermentation output for leather tanning and textile processing applications.
- Cosmetic Grade:Purified material meeting ISO 16128 natural origin criteria for pH adjustment in skincare formulations.
Food grade handles the majority of throughput; pharmaceutical grade is the fastest mover on share.
Application:
Cost tier differentiation separates commodity preservation uses from premium biopolymer and active pharmaceutical ingredient feedstock.
- Food & Beverage:Preservation and flavoring across processed meat, bakery, and dairy supply chains. German sauerkraut and Asian fermented beverage producers are the largest volume offtakers, though margin compression is accelerating consolidation toward membrane-purified supply.
- Bioplastics:Polylactic acid resin feedstock requiring polymer-grade optical purity and metal ion specifications. Dutch and Belgian packaging converters are mandating gypsum-free process documentation to meet EU Green Deal circular economy targets.
- Pharmaceuticals:Chiral synthesis and parenteral formulation applications.
- Personal Care:Exfoliant and pH buffering agent in premium skincare.
Food and beverage absorbs the largest volume base; bioplastics is climbing the fastest as polylactic acid capacity scales.
End User:
Customer type determines contracting structure, with institutional procurement favoring long-term offtake over spot purchasing.
- Food Manufacturers:Processed meat, dairy, and bakery operators purchasing bulk fermentation acids for shelf-life extension. Major European dairy cooperatives are consolidating supplier panels to three qualified membrane-purification operators to reduce qualification overhead.
- Bioplastic Producers:Polylactic acid resin manufacturers requiring polymer-grade lactic acid with controlled D-isomer ratios. NatureWorks and TotalEnergies Corbion are locking five-year supply agreements with fixed purity bands to secure feedstock for Ingeo and Luminy resin production.
- Pharmaceutical Companies:Injectable and oncology drug manufacturers demanding USP-certified material.
- Cosmetic Brands:Clean-label skincare formulators seeking natural origin certification.
Food manufacturers command the greatest volume throughput; bioplastic producers are gaining share fastest through capacity expansion.
Distribution Channel:
Supply concentration shapes channel selection, with direct relationships dominating high-certification tiers and intermediaries serving fragmented buyers.
- Direct Sales:Long-term supply agreements between fermentation operators and tier-one bioplastic and pharmaceutical manufacturers. Henan Jindan and Corbion negotiate directly with NatureWorks and European drug makers to secure volume commitments and co-development protocols.
- Distributors:Regional chemical distributors serving mid-size food and cosmetic manufacturers without direct procurement scale. German specialty chemical distributors in the Rhine-Ruhr cluster maintain inventory positions for qualified fermentation acids.
- Wholesale:Bulk volume transactions for industrial-grade material.
- Online Retail:Small-package sales to research laboratories and artisan formulators.
Direct sales captures the highest value throughput; distributor relationships are expanding fastest as mid-market buyers seek qualified supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Switzerland where pharmaceutical-grade certification commands substantial premiums, while Chinese producers compete on food-grade volume with thinner margins. This asymmetry shapes investment flows toward membrane filtration capacity in Western Europe and captive starch integration in Asia.
Germany
Bioplastic converters in the Rhine-Ruhr cluster are locking five-year supply agreements for polymer-grade feedstock. EU Green Deal circular economy targets mandate gypsum-free process documentation for packaging-grade certification. Specialty chemical distributors in Cologne and Düsseldorf are consolidating supplier panels to three qualified fermentation operators.
China
Henan Province starch processors are expanding fermentation capacity to serve Asian noodle and dairy preservative demand. The country's national food safety regulator is tightening impurity thresholds for fermentation-derived acidulants. Zhengzhou-based producers are integrating backward into corn processing to buffer agricultural commodity volatility.
Switzerland
Swissmedic-certified injectable drug manufacturers are securing multi-year chiral intermediate supply contracts. REACH registration requirements for industrial chemical placement constrain new market entry through extended validation timelines. Basel pharmaceutical clusters are specifying electrodialysis purification certificates in procurement protocols.
United States
FDA purity standards for pharmaceutical-grade material are elevating compliance spending for fermentation entrants. USDA BioPreferred procurement guidelines channel federal purchasing toward certified biobased lactic acid. NatureWorks in Minnesota is integrating downstream into Ingeo biopolymer production to lock polymer-grade demand.
Netherlands
Polylactic acid resin producers in Rotterdam and Geleen are mandating gypsum-free documentation for EU Green Deal compliance. ECHA salt waste classification updates are elevating disposal costs for calcium sulfate byproduct streams. TotalEnergies Corbion operations are anchoring polymer-grade supply agreements with fixed optical purity bands.
Gypsum-Free Lactic Acid Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation and purification technology. The vendor base separates into three tiers: starch-integrated fermentation operators, membrane technology licensors, and downstream biopolymer producers. Two strategic archetypes dominate—captive feedstock players defending cost positions and certification-focused specialists capturing pharmaceutical premiums. Capacity expansion and long-term offtake contracting represent the primary competitive moves reshaping supply relationships.
Within the captive feedstock tier, Henan Jindan Lactic Acid Technology exemplifies backward integration into starch supply. Corbion and NatureWorks occupy positions spanning fermentation optimization and downstream polymer integration. These three anchors illustrate the strategic divergence between cost-driven volume players and premium-tier certification specialists.
| Leading Market Players |
|---|
| Henan Jindan Lactic Acid Technology |
| Musashino Chemical Laboratory |
| Corbion |
| Galactic |
| Cargill |
| NatureWorks |
| BASF |
| ADM |
| Jungbunzlauer |
| Others |
Supply & Pricing Matrix
Undercapacity in membrane filtration capacity across Western Europe is forcing bioplastic converters into multi-year offtake commitments at fixed purity bands. This utilization squeeze simultaneously elevates pharmaceutical-grade premiums and compresses food-grade margins as fermentation operators prioritize higher-certification output.
Pricing Analysis
The customization-premium spread separates configured-to-order electrodialysis-certified batches from standard food-grade spot deliveries. Contract-based long-term offtake dominates polymer-grade transactions, while commodity spot purchasing persists in industrial applications. Price differentiation rests on USP/EP certification burden and optical purity thresholds above 99.5 percent. Cost compression in food-grade tiers is intensifying because Chinese starch-integrated producers are expanding export volumes. Mid-size dairy processors exhibit highest price sensitivity; Swiss injectable drug manufacturers show least.
Supply Chain Analysis
Contract-manufacturing concentration sits with Henan Jindan, Corbion, and NatureWorks as the three qualified fermentation operators serving European bioplastic demand. Geographic supply concentration centers on China, the Netherlands, and Germany for purification capacity and downstream polymer integration. Raw material dependencies draw from corn starch, cassava feedstock, and electrodialysis membrane stacks. Single-source vulnerability in pharmaceutical-grade membrane supply creates bottleneck risk. Distribution runs through direct sales for tier-one bioplastic and pharmaceutical buyers, with regional chemical distributors serving fragmented food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where polylactic acid resin specifications are becoming the interoperability standard for biodegradable packaging certification across EU member states.
For Market Incumbents: Pre-empt lignocellulosic feedstock conversion by acquiring C5/C6 sugar fermentation expertise before agricultural waste streams achieve cost parity. Lock five-year supply agreements with Rotterdam and Geleen polylactic acid producers to defend volume positions against emerging Chinese membrane-purification capacity. Certification investment in Swissmedic and FDA pharmaceutical-grade validation represents the priority defensive lever against specialty chemical entrants. For New Entrants and Emerging Players: Pursue cosmetic-grade white-space in clean-label skincare formulations where ISO 16128 natural origin criteria create certification barriers for incumbent industrial producers. European mid-size food manufacturers without direct procurement scale offer the most penetrable buyer segment. A distributor-partnership go-to-market angle through Rhine-Ruhr specialty chemical channels reduces customer acquisition costs versus direct sales buildout. For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-security play because bioplastic resin capacity expansion is outpacing qualified fermentation supply. Acquisition targets should display captive starch integration or membrane filtration technology licensing positions. The signal to watch is polylactic acid producer capital expenditure announcements for greenfield resin plants without backward lactic acid integration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Supply | Henan Jindan's captive corn processing buffers agricultural commodity volatility for fermentation feedstock security. |
| Electrodialysis Capacity Expansion | Corbion's continuous fermentation optimization sustains technology leadership in pharmaceutical-grade optical purity. |
| Long-term Supply Agreement | NatureWorks locks polymer-grade demand through Ingeo biopolymer production integration with fixed purity bands. |
| Green Manufacturing Transition | EU Green Deal REACH compliance frameworks mandate gypsum-free process documentation for packaging-grade certification. |
| Joint Venture | TotalEnergies Corbion anchors Rotterdam polymer-grade supply through shared electrodialysis purification infrastructure. |
Research Methodology
Cross-validation between primary interviews with fermentation plant managers, bioplastic procurement leads, pharmaceutical regulatory affairs directors, and specialty chemical distributors anchors the qualitative findings against secondary validation from ECHA REACH registration databases, EU customs trade flows, SEC 10-K filings of listed fermentation operators, and Cefic chemical industry reports. Bottom-up capacity buildout estimates from named fermentation facilities triangulate against top-down demand projections from polylactic acid resin producers.
Calibration against historical optical purity certification timelines and membrane replacement cycles shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs derive from volume-weighted average of facility-level capacity utilization trajectories and offtake contract pricing bands. Industry-specific forecast inputs incorporate corn starch price volatility indices and electrodialysis membrane technology maturation curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity cycles, EU carbon border adjustment implementation, or bioplastic substitution rates would shift the trajectory. Forecasts reflect documented assumptions on fermentation yield advances and carbon-source diversification timelines. Quarterly review of polylactic acid resin capacity announcements, ECHA salt waste classification updates, and pharmaceutical-grade validation backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Nahcolite Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Ethylene and Propylene Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market