
 Industrial Air Purifiers Market | 2026-2036
Industrial Air Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Air Purifiers Market Foresight
Multi-source procurement for filter media and fan assemblies is pivoting toward vertically integrated supply chains as OEMs seek cost predictability. Mann+Hummel leverages captive membrane production to control lead times for automotive and industrial clients. Donaldson Company anchors its position through dense distribution networks across North American manufacturing corridors. Camfil AB differentiates via cleanroom-grade certification depth that pharmaceutical buyers require for aseptic processing.
Industrial air purifiers are engineered systems that remove airborne contaminants through mechanical filtration, electrostatic attraction, or photocatalytic oxidation, typically achieving MERV 13–17 efficiency ratings or HEPA-class performance at 99.97% particle retention for 0.3-micron aerosols; these units serve manufacturing and process industries where ambient particulate, volatile organic compound, or microbial loads threaten product integrity, equipment longevity, or worker respiratory safety. HEPA Filters occupy the dominant product position due to universal regulatory acceptance and proven performance in critical environments, while UV Light Purifiers represent the fastest-expanding technology segment as food processing and pharmaceutical facilities adopt non-chemical disinfection protocols to complement mechanical stages. Dust Removal commands the largest application share because mining, metalworking, and cement operations generate continuous heavy particulate loads that demand sustained extraction capacity.
OSHA permissible exposure limits for respirable crystalline silica and hexavalent chromium directly shape industrial air purifier specification thresholds in United States metalworking and construction material plants. EPA National Emission Standards for Hazardous Air Pollutants extend compliance obligations to chemical facilities and coating operations, reinforcing demand for integrated VOC reduction and particulate control systems. ISO 16890 test standards for filter performance are displacing older EN 779 protocols in cross-border procurement, creating certification complexity that buyers must navigate when qualifying suppliers for multinational facility rollouts.
Market Dynamics
OSHA's tightening permissible exposure limits for respirable crystalline silica and hexavalent chromium are forcing metalworking and construction material plants to upgrade filtration infrastructure ahead of compliance deadlines, compressing replacement cycles and elevating specification thresholds across the installed base.
Growth Catalysts
- OSHA Indoor Air Quality Mandates:Tightening permissible exposure limits for industrial particulates in United States manufacturing facilities are accelerating replacement demand for legacy systems that cannot meet new thresholds.
- Pharmaceutical Sterile Manufacturing:Aseptic processing requirements for biologics and injectables are expanding HEPA filtration capacity in fill-finish operations and active pharmaceutical ingredient suites.
- German Automotive Clusters:High-volume paint booths and battery cell manufacturing lines in Baden-Württemberg and Bavaria are driving concentrated deployments of activated carbon and HEPA-integrated systems.
Market Restraints
- Filter Media Supply Concentration:Microglass and synthetic membrane production concentrates among a limited set of European and Asian suppliers, exposing OEMs to lead time volatility and input cost spikes.
- Technical Limitation in High-Humidity Environments:HEPA filter efficiency degrades in saturated air streams common to food processing and coastal chemical plants, requiring costly pre-conditioning stages.
- Capital Intensity of Cleanroom-Grade Systems:ISO 14644-compliant installations demand specialized ductwork, sealed enclosures, and continuous monitoring infrastructure that stretches facility budgets.
Strategic Opportunities
- UV-Photocatalytic Convergence:Food processing facilities are combining UV-C stages with titanium dioxide catalysts to achieve non-chemical microbial reduction without residual ozone generation.
- Underpenetrated Indian Pharmaceutical Manufacturing:CDSCO's tightening GMP enforcement for domestic drug production is creating first-time demand for certified cleanroom air handling in Hyderabad and Ahmedabad clusters.
- Service Contract Unbundling:Filter replacement and performance monitoring are separating from equipment sales, creating recurring revenue streams for technical service providers.
Industry Challenges
- ISO 16890 Certification Timeline:The displacement of EN 779 protocols is forcing multinational buyers to requalify supplier test data, delaying procurement decisions for cross-border facility rollouts.
- Integration Complexity with Legacy HVAC:Retrofitting HEPA-class performance into existing ducted systems requires pressure-drop recalculation and fan capacity upgrades that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Air Purifiers Market |
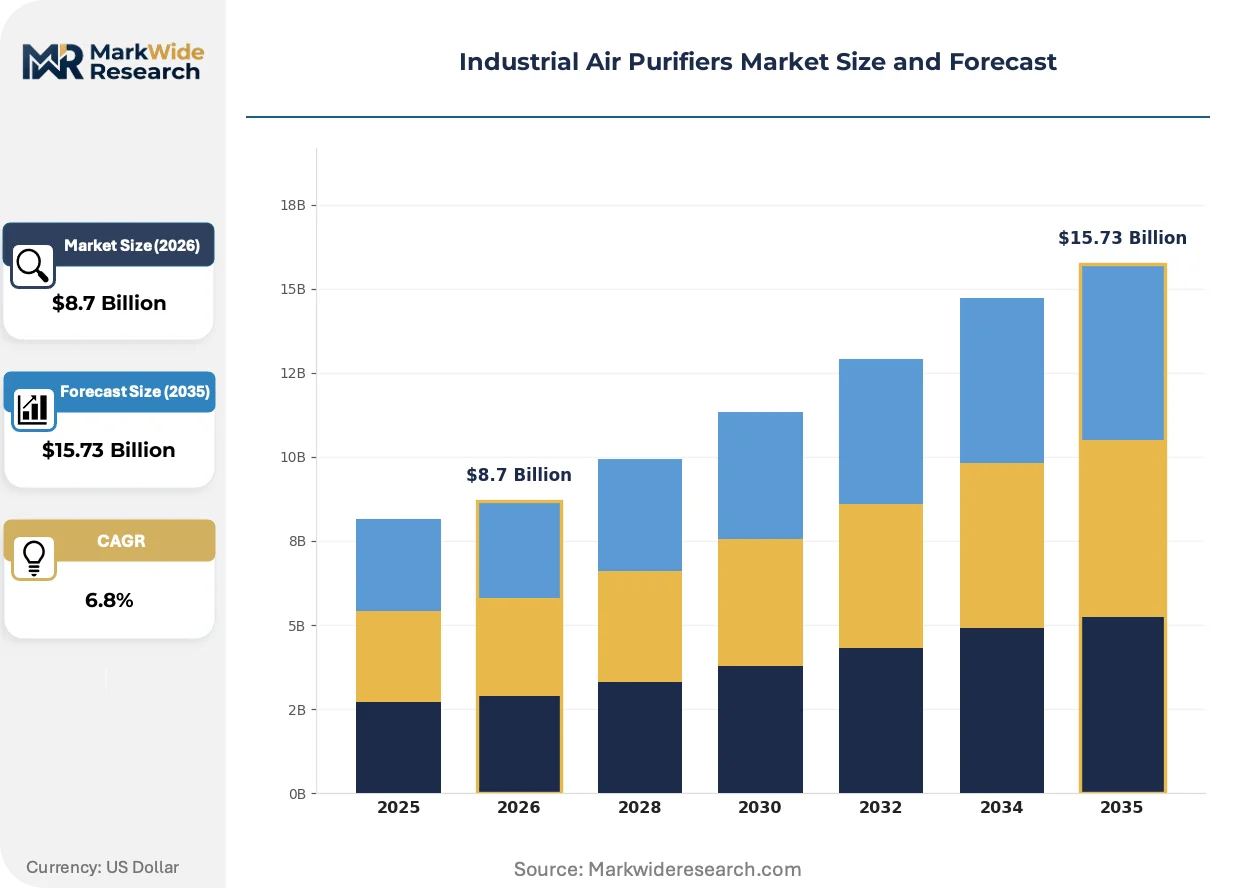
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Activated Carbon Filters, Electrostatic Precipitators, UV Light Purifiers End User: Manufacturing Plants, Chemical Facilities, Food Processing, Pharmaceutical Labs Technology: Filtration, Adsorption, Ionization, Photocatalytic Oxidation Application: Dust Removal, Odor Control, VOC Reduction, Bacteria Elimination |
| Companies Covered | Mann+Hummel, AAF International, Donaldson Company, Daikin Industries, Honeywell International, Camfil AB, Freudenberg Filtration Technology, Parker Hannifin Corporation, Nederman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Air Purifiers Market Shifts & Advancements
Electrostatic precipitation is re-emerging as a complement to mechanical filtration in heavy particulate environments, while smart monitoring systems are embedding sensor networks that shift maintenance from calendar-based to condition-based protocols.
Photocatalytic oxidation using titanium dioxide-coated substrates is integrating with UV-C irradiation stages to decompose volatile organic compounds without generating harmful ozone byproducts. Automotive painting operations in Germany and aerospace coating facilities in France are adopting these hybrid systems to meet solvent emission limits. The technology is integrating VOC destruction with particulate capture in single-unit footprints that reduce floor space requirements by eliminating separate abatement trains.
EPA National Emission Standards for Hazardous Air Pollutants are extending compliance obligations to chemical facilities and coating operations beyond traditional stationary sources. The rules mandate integrated control systems that address both particulate matter and toxic air contaminants simultaneously. Chemical manufacturers in Texas and Louisiana are responding by specifying multi-stage purifiers with activated carbon depth beds preceding HEPA final filters.
Buyer concentration among contract manufacturing organizations is compressing equipment specification cycles as pharmaceutical packagers centralize procurement across global facility networks. Large CMOs are deploying standardized air handling units that simplify validation documentation and reduce spare parts complexity. This pattern is most visible in Ireland and Singapore, where clustering of sterile fill-finish operations has created concentrated demand for harmonized cleanroom infrastructure.
Industrial Air Purifiers Market Segmentation
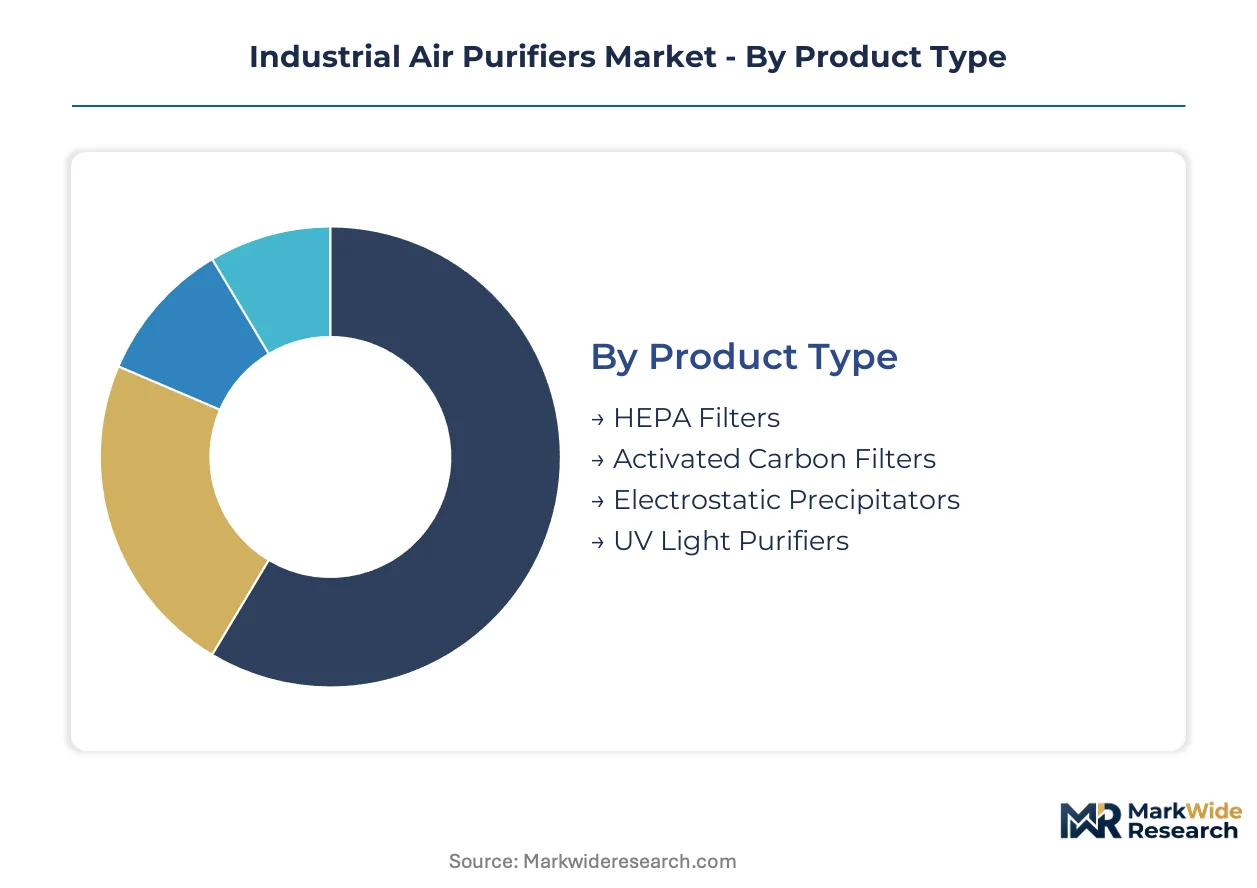
Industrial air purifier procurement divides sharply between facilities requiring certified cleanroom performance and those managing heavy particulate loads. Specification thresholds vary by contaminant type, regulatory jurisdiction, and process criticality, creating distinct technology-product pairings across end-use verticals.
Product Type:
Filter media supply concentrates among European and Asian membrane producers, forcing OEMs to secure long-term contracts for microglass and synthetic substrates.
- HEPA Filters:These mechanical filtration units achieve 99.97% retention of 0.3-micron particles through dense microglass fiber matrices. Pharmaceutical fill-finish operations in Germany and sterile API suites in India drive specification intensity as CDSCO and EMA tighten aseptic processing mandates.
- UV Light Purifiers:UV-C irradiation systems decompose microbial DNA and VOC chains without chemical residuals. Food processing facilities in the United States are integrating these stages ahead of mechanical filtration to meet USDA sanitation requirements while reducing water-intensive clean-in-place cycles.
- Activated Carbon Filters:Porous carbon substrates adsorb solvent vapors and odorous compounds through physisorption. Automotive paint booths in Baden-Württemberg specify deep-bed configurations to capture toluene and xylene emissions.
- Electrostatic Precipitators:Charged plate arrays capture sub-micron particulate without pressure drop penalties. Cement and mining operations deploy these for pre-filtration of high-dust streams.
HEPA filters absorb the bulk of installed capacity; UV light purifiers are expanding most quickly.
End User:
Capital deployment intensity separates facilities with continuous extraction demands from those with episodic or localized contamination control needs.
- Manufacturing Plants:Metalworking and cement operations generate sustained heavy particulate loads requiring high-capacity dust collection infrastructure. OSHA silica limits are compressing replacement cycles for legacy baghouse and cartridge systems.
- Pharmaceutical Labs:Aseptic processing suites demand ISO 14644-compliant air handling with continuous particle monitoring. Fill-finish operations in Ireland and Singapore cluster drive harmonized procurement of validated cleanroom units.
- Chemical Facilities:Texas and Louisiana petrochemical complexes specify multi-stage systems combining activated carbon with HEPA final filtration to address EPA NESHAP requirements for hazardous air pollutants.
- Food Processing:High-humidity environments challenge HEPA efficiency, forcing pre-conditioning stages or hybrid UV-mechanical configurations to prevent filter degradation.
Manufacturing plants absorb the bulk of installed capacity; pharmaceutical labs are climbing the fastest.
Technology:
Process integration complexity favors technologies that combine multiple contaminant removal mechanisms within single-unit footprints.
- Filtration:Mechanical particle capture through fibrous media remains the baseline specification for all regulated environments. MERV 13-17 ratings satisfy most industrial particulate limits.
- Photocatalytic Oxidation:Titanium dioxide-coated substrates activated by UV-C irradiation decompose VOCs without ozone generation. French aerospace coating facilities adopt these hybrid systems to meet solvent emission limits.
- Adsorption:Activated carbon and zeolite substrates trap molecular contaminants through surface bonding. Chemical facilities specify carbon depth beds for toxic vapor control.
- Ionization:Corona discharge systems charge airborne particles for collection on grounded surfaces. These complement mechanical stages in high-dust mining environments.
Filtration absorbs the bulk of installed capacity; photocatalytic oxidation is gaining share fastest.
Application:
Contaminant physics dictate technology selection, with particulate removal commanding baseline capacity and molecular control requiring specialized substrate investments.
- Dust Removal:Continuous extraction of respirable particulate dominates mining, cement, and metalworking operations. Heavy loading rates demand automated pulse-cleaning or continuous-duty fan assemblies.
- VOC Reduction:Solvent vapor capture through activated carbon addresses EPA and ECHA emission limits. Coating and chemical operations specify carbon change-out protocols based on breakthrough monitoring.
- Odor Control:Adsorption and oxidation stages address nuisance complaints and regulatory thresholds for hydrogen sulfide and ammonia. Food rendering and wastewater treatment facilities deploy these systems.
- Bacteria Elimination:UV-C and filtration combinations achieve microbial reduction without residual chemicals. Aseptic packaging lines specify these for surface and air sterilization.
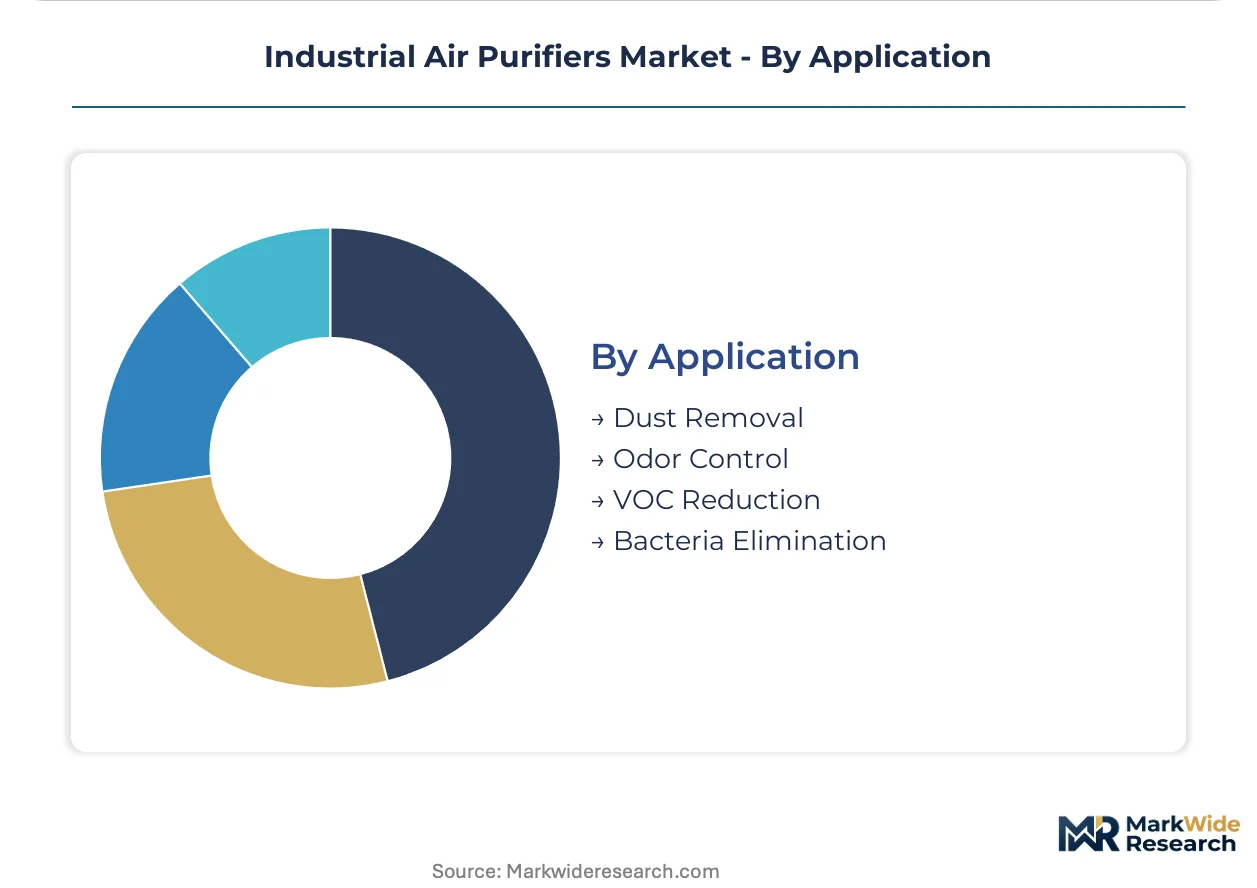
Dust removal absorbs the bulk of installed capacity; VOC reduction is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial air purifier procurement concentrates in manufacturing corridors where regulatory enforcement intersects with high-volume production. Germany, the United States, China, India, and Japan absorb the bulk of capital deployment as each jurisdiction tightens occupational exposure frameworks.
Germany
Automotive paint booths and battery cell manufacturing in Baden-Württemberg and Bavaria drive activated carbon and HEPA-integrated system demand. The German Social Accident Insurance (DGUV) enforces strict workplace exposure limits for solvents and particulates. Stuttgart and Munich manufacturing clusters specify deep-bed carbon configurations to capture toluene and xylene emissions from coating operations.
United States
OSHA's crystalline silica and hexavalent chromium limits are compressing replacement cycles for legacy filtration in metalworking plants. EPA National Emission Standards for Hazardous Air Pollutants extend compliance to chemical facilities in Texas and Louisiana. Houston petrochemical complexes deploy multi-stage systems combining activated carbon with HEPA final filters to meet NESHAP requirements.
China
Semiconductor fabrication and pharmaceutical manufacturing in the Yangtze River Delta and Pearl River Delta expand cleanroom-grade air handling capacity. The Ministry of Ecology and Environment enforces GB standards for industrial emissions and workplace air quality. Shanghai and Suzhou electronics clusters specify ISO 14644-compliant systems for wafer processing environments.
India
CDSCO's tightening GMP enforcement for domestic drug production creates first-time demand for certified cleanroom infrastructure. The Hyderabad and Ahmedabad pharmaceutical clusters upgrade active pharmaceutical ingredient suites and fill-finish operations. Telangana and Gujarat manufacturing corridors specify validated HEPA filtration for aseptic processing compliance.
Japan
Precision electronics and pharmaceutical manufacturing in the Kanto and Kansai regions sustain demand for ultra-high-efficiency filtration. METI industrial standards and JIS certification protocols govern equipment specification. Tokyo and Osaka production facilities specify MERV 16-17 rated systems for contamination-sensitive assembly operations.
Industrial Air Purifiers Market Competitive Landscape
Backward integration into filter media production dominates the current landscape as OEMs seek supply security. The vendor base spans diversified industrial conglomerates and specialized filtration engineering houses, creating a tiered structure where scale advantages coexist with certification depth. Three archetypes define positioning: vertically integrated membrane producers, distribution-anchored system integrators, and cleanroom-grade certification specialists. Capacity expansion in Asian manufacturing hubs and strategic technology licensing partnerships represent the primary competitive vectors reshaping market share.
Among European filtration engineering houses, Mann+Hummel and Camfil AB exemplify divergent strategic positions. Mann+Hummel leverages captive membrane production to compress lead times for automotive and industrial clients. Camfil AB occupies a certification-specialist position emphasizing cleanroom-grade depth that pharmaceutical buyers require for aseptic processing validation. Donaldson Company anchors North American presence through dense distribution networks across manufacturing corridors.
| Leading Market Players |
|---|
| Mann+Hummel |
| AAF International |
| Donaldson Company |
| Daikin Industries |
| Honeywell International |
| Camfil AB |
| Freudenberg Filtration Technology |
| Parker Hannifin Corporation |
| Nederman |
| Others |
Supply & Pricing Matrix
Membrane engineering talent concentration in Baden-Württemberg and the Yangtze River Delta widens labor-cost differentials between premium cleanroom-grade systems and standard industrial units, compressing mid-tier pricing spreads as buyers arbitrage certification tiers.
Pricing Analysis
Warranty and service-bundling unbundling reshapes transaction structures as OEMs separate filter replacement contracts from equipment sales. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 14644 certification depth and captive membrane production. Cost compression in economy tiers intensifies because Asian microglass suppliers expand synthetic substrate capacity. Pharmaceutical labs exhibit lowest price sensitivity given validation documentation requirements; metalworking plants show highest sensitivity amid compressed replacement cycles.
Supply Chain Analysis
ISO 16890 certification gating delays supplier qualification as multinational buyers revalidate test data previously accepted under EN 779 protocols. Microglass and synthetic membrane production centers on Germany, Japan, and China, drawing from specialized glass fiber and polymer resin feedstocks. Single-source vulnerability concentrates in European membrane producers serving pharmaceutical OEMs. Distribution runs through dense technical service networks anchored by regional system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filter media supply concentration props pricing power for backward-integrated OEMs, with microglass capacity expansion lagging pharmaceutical demand growth across the analysis window.
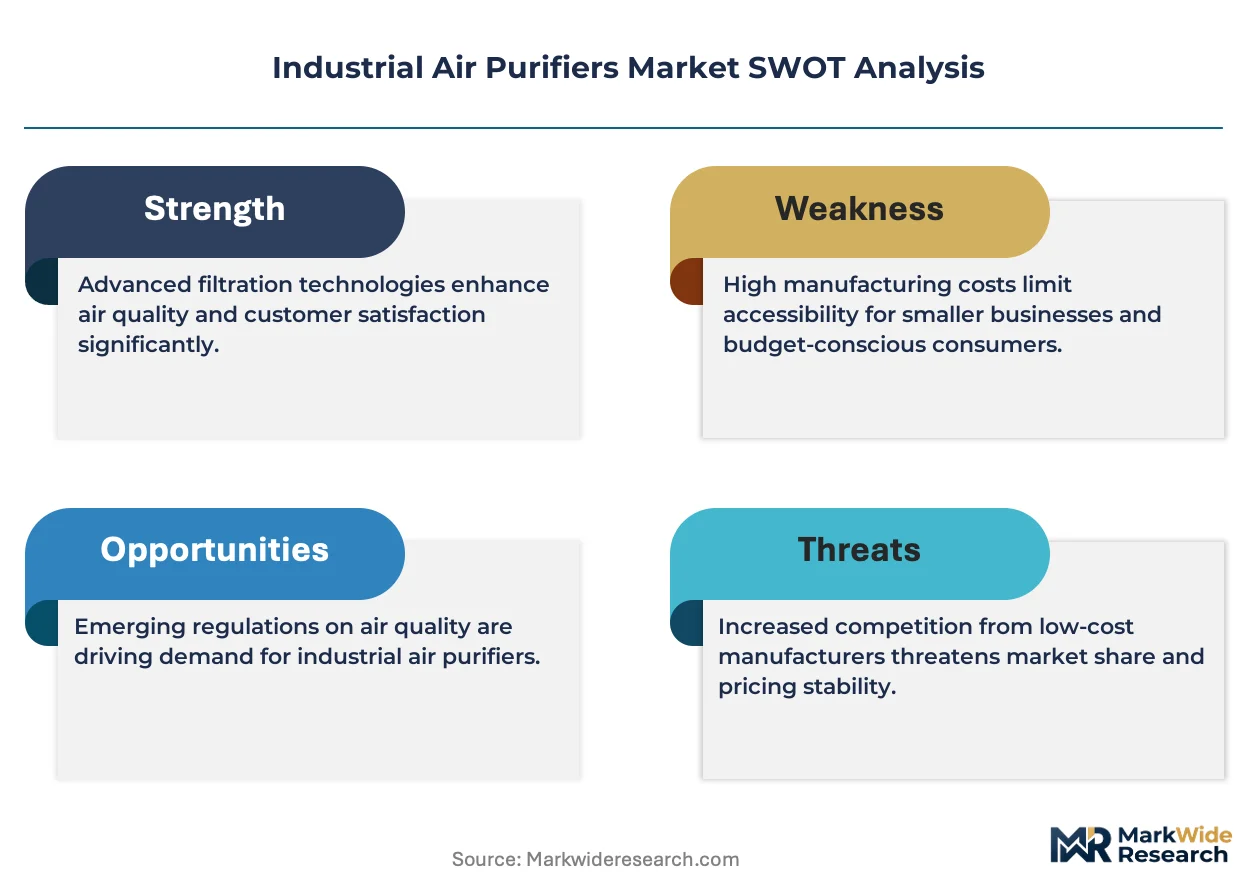
For Market Incumbents: Lock in long-term membrane supply contracts with Japanese and German substrate producers before CDSCO and EMA enforcement waves accelerate. Defend margin position by embedding sensor networks that shift maintenance revenue from calendar-based to condition-based protocols, countering emerging UV-photocatalytic hybrid entrants. For New Entrants and Emerging Players: UV-photocatalytic convergence offers technology-first entry into food processing facilities seeking non-chemical microbial reduction. Target underpenetrated Indian pharmaceutical manufacturing in Hyderabad and Ahmedabad clusters where CDSCO GMP enforcement creates first-time cleanroom demand. Pursue validation partnerships with contract manufacturing organizations centralizing procurement across global networks. For Investors and Strategic Acquirers: Re-rating potential sits with cleanroom-grade certification specialists given EMA and CDSCO tightening aseptic processing mandates. Long-term viability favors membrane producers with captive pharmaceutical validation depth. Watch ISO 16890 requalification timelines as inflection indicators for procurement decision velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Production | Mann+Hummel's captive microglass supply compresses lead times for automotive clients in Baden-Württemberg. |
| UV-Photocatalytic Technology Licensing | French aerospace coating facilities adopt titanium dioxide-UV hybrid systems to meet solvent emission limits. |
| Service Contract Unbundling | Filter replacement and performance monitoring separate from equipment sales, creating recurring revenue for technical providers. |
| Cleanroom Certification Depth Investment | Camfil AB's ISO 14644 validation documentation satisfies pharmaceutical buyers for aseptic processing compliance. |
| Indian Pharmaceutical Cluster Expansion | Hyderabad and Ahmedabad API suites drive first-time HEPA filtration demand under CDSCO enforcement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this industrial air purifiers analysis. Primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers combined with OSHA enforcement databases, EPA NESHAP guidance documents, ISO certification registries, and EMA aseptic processing guidelines. Bottom-up facility-level demand modeling triangulated against top-down sector expenditure patterns.
Granularity-level modeling addressed product type, end-user vertical, technology mechanism, application contaminant, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level volume and value build-ups incorporating filter replacement cycle compression under tightening exposure limits. Industry-specific inputs included pharmaceutical fill-finish capacity expansion timelines and automotive paint booth specification trends.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation on microglass substrates or accelerated ISO 16890 displacement timelines. Forecasts reflect assumptions about regulatory enforcement velocity and membrane supply expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Rotary Union Market
Others
Aerospace Tester Market
Others
Embedded Computer Market
Others
Storm Surge Barriers Market
Others
Asia-Pacific Legal Services Market
Others
Buchner Funnels Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Aerospace Software Testing Market
Others
Shisha Tobacco Market
Others
Binoculars and Mounting Solutions Market
Others
Rotary Dial Machine Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Toy Packaging Market
Others
Mexico 3D Printing Construction Market
Others
Infant Fever Stickers Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market