
 Brain Mint Market | 2026-2036
Brain Mint Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Mint Market Insights
REACH compliance is expanding the cost-of-entry calculus for nootropic confectionery brands seeking European market access. NeuroGum leverages its gum-based delivery format to sustain rapid buccal absorption claims in competitive positioning. BrainMD anchors its portfolio with clinician-formulated credentials that differentiate it from lifestyle-oriented rivals. Qualia Life Sciences competes on ingredient transparency, publishing full supply chain documentation that dominates trust metrics among premium buyers.
Brain mint denotes functional confectionery products containing nootropic compounds, typically caffeine, L-theanine, or B-vitamins in doses ranging from 50 to 200 milligrams per serving, formulated for cognitive enhancement through rapid oral delivery. These products serve industrial and commercial purposes by addressing workplace productivity demands, student performance optimization, and gaming endurance in the e-sports sector. Sugar-free mints command the deepest margin pools as consumers prioritize dental health alongside cognitive claims, while online retail channels represent the fastest-growing distribution vector as subscription models lock in recurring revenue. Chewing gum retains the largest volume share due to established manufacturing infrastructure and familiar consumption rituals across age cohorts.
The FDA oversees nootropic ingredient classifications and structure-function claim boundaries, while the FTC monitors advertising substantiation for cognitive benefit assertions in this category. EFSA's novel food evaluations shape which ingredients gain commercial traction in European formulations, creating divergent product portfolios across regulatory jurisdictions. Stakeholders must monitor evolving enforcement patterns around nootropic dosage thresholds and decide whether to pursue pharmaceutical-grade clinical trials or remain within dietary supplement regulatory frameworks.
Market Dynamics
Direct-to-consumer wellness brands have built trust channels that concentrate demand around clinically substantiated nootropic formulations, while FDA enforcement posture on structure-function claims forces portfolio recalibration across the competitive set.
Growth Catalysts
- FTC advertising substantiation standards:Clearer enforcement boundaries reduce competitor ambiguity, allowing compliant brands to capture shelf space from marginal operators.
- E-sports endurance applications:Gaming professionals adopt rapid-delivery formats for sustained cognitive performance during competitive sessions.
- Subscription commerce infrastructure:Recurring revenue models lock in consumer lifetime value and reduce customer acquisition cost volatility.
Market Restraints
- REACH compliance costs:European market entry requires extensive novel substance dossiers that strain mid-tier brand balance sheets.
- Active ingredient supply concentration:Synthetic caffeine and L-theanine production clusters in Chinese chemical manufacturing zones, creating single-source vulnerability.
- Buccal absorption variability:Individual salivary pH and chewing mechanics produce inconsistent nootropic bioavailability across users.
Strategic Opportunities
- Underpenetrated German pharmacy channel:Apotheken distribution remains dominated by traditional supplements, leaving white space for clinically positioned entrants.
- Microbiome-nootropic convergence:Gut-brain axis research enables next-generation formulations combining probiotics with cognitive actives.
- CSRD sustainability disclosure:Early adoption of supply chain transparency reporting differentiates premium brands among ESG-mandated institutional buyers.
Industry Challenges
- Clinical trial design expertise:Brands lack in-house capability to execute pharmaceutical-grade studies that satisfy FDA substantiation thresholds.
- Cross-border formulation divergence:EFSA novel food rejections force SKU proliferation that fragments manufacturing scale economies.
- Ingredient provenance verification:Blockchain-tracked supply chains require capital investment that strains emerging brand cash positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Mint Market |
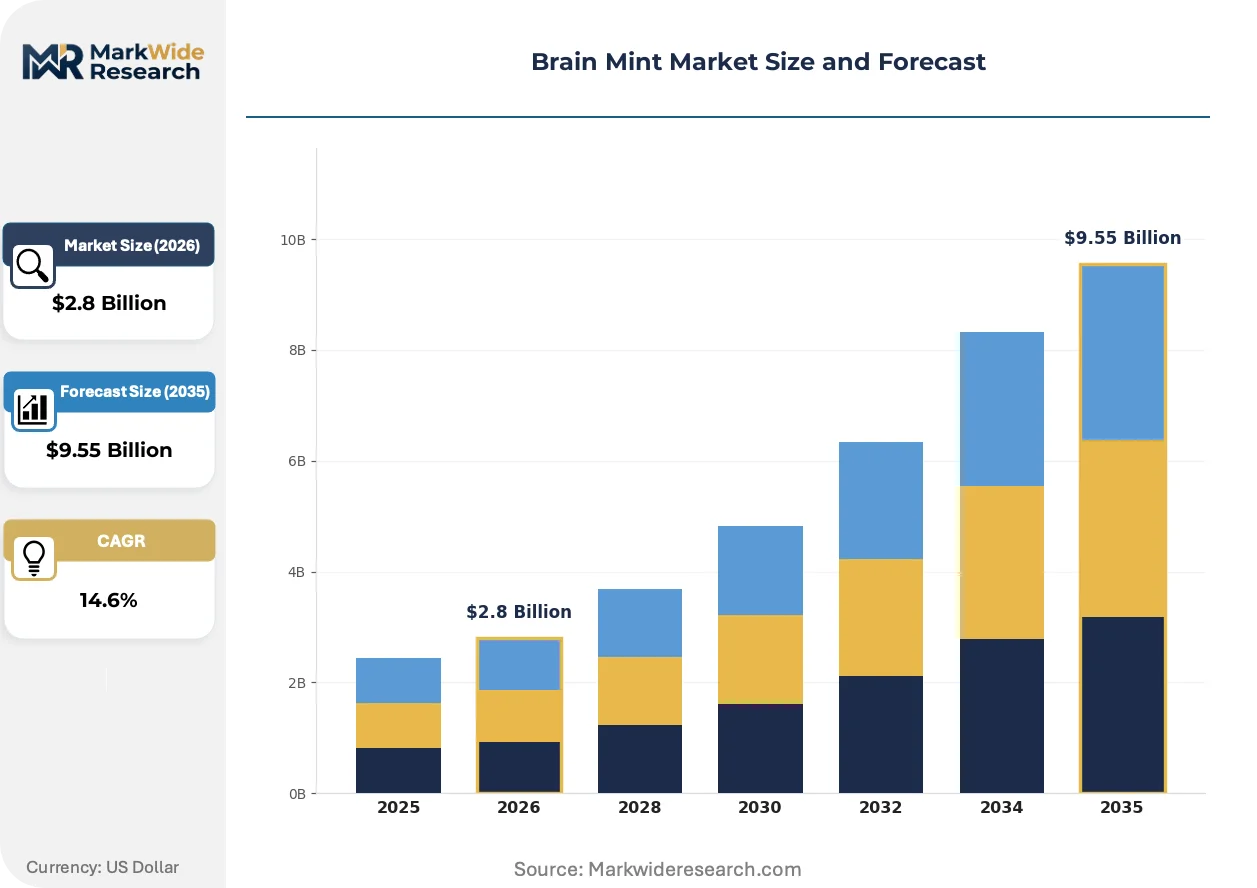
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewing Gum, Candy Tablets, Hard Candy, Sugar-free Mints, Breath Fresheners Flavor: Spearmint, Peppermint, Cinnamon, Wintergreen, Eucalyptus Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Pharmacies, Vending Machines Consumer Age Group: Children, Teenagers, Adults, Seniors |
| Companies Covered | NeuroGum, BrainMD, Mindbodygreen, Bulletproof, Qualia Life Sciences, Solgar, Metagenics, Pure Encapsulations, Designs for Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Mint Market Trends and Innovations
Functional confectionery formats are fragmenting as delivery mechanism innovation outpaces ingredient discovery, with absorption science and ritual design becoming primary competitive battlegrounds.
Microencapsulation technology protects heat-sensitive nootropics through manufacturing and shelf life, extending viable active ingredient portfolios beyond caffeine and B-vitamins. Premium brands adopt this process to incorporate phosphatidylserine and citicoline into chewable formats. The technology is converging with precision-release coating systems that enable multi-stage cognitive effect profiles.
EFSA novel food evaluations reshape which ingredients gain commercial traction in European formulations, creating divergent product portfolios across regulatory jurisdictions. Brands must maintain parallel SKU architectures or accept geographic market exclusion. Sugar-free mint formats face heightened scrutiny under evolving dental health claim frameworks.
Gaming and esports organizations now procure cognitive support products through team-wide supply contracts rather than individual retail purchases. This concentrates buyer power among a handful of professional league procurement officers. South Korean team houses and North American streaming collectives represent the most visible early adopters of this institutional purchasing pattern.
Brain Mint Market Segmentation
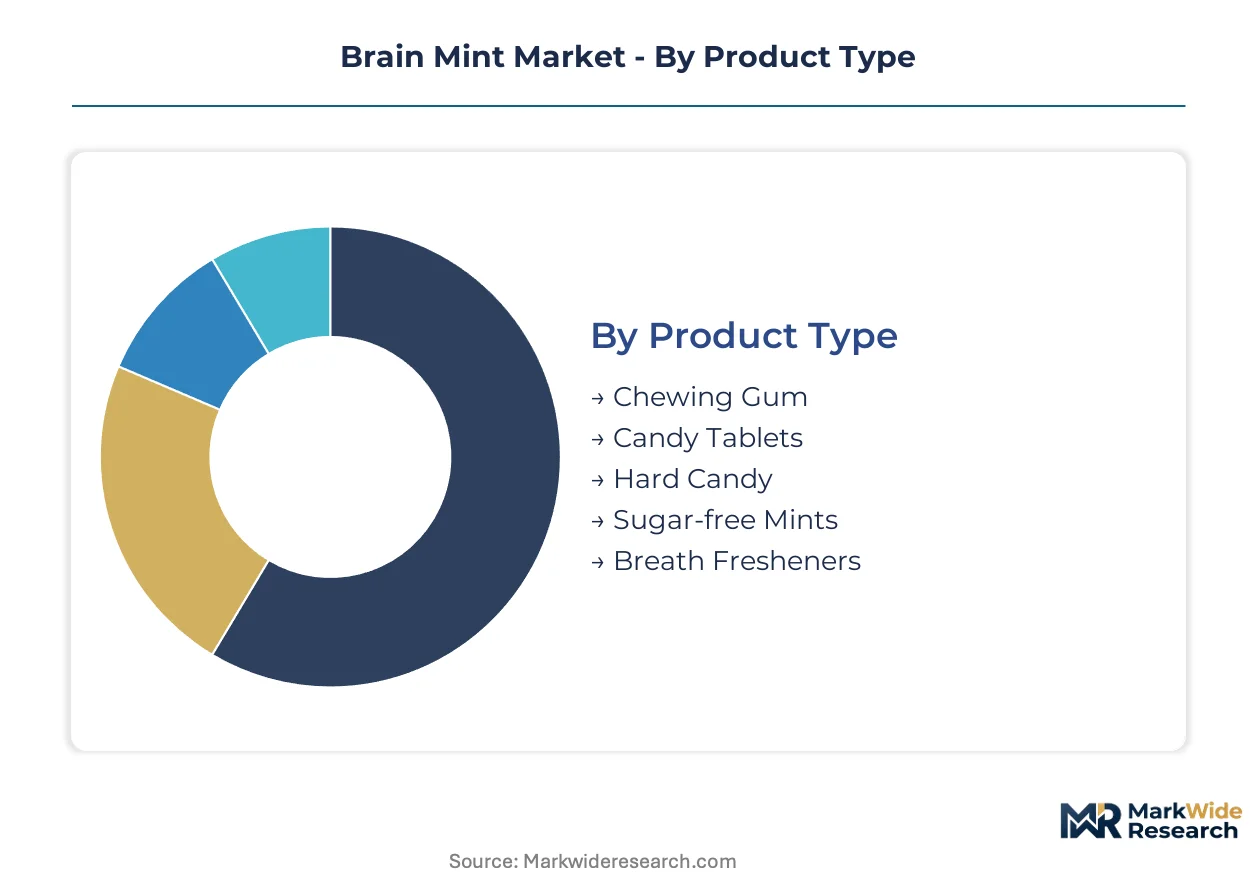
Brain mint segmentation reveals how regulatory exposure and delivery format interact to determine margin structure. Product type and distribution channel classifications carry distinct compliance burdens that reshape competitive positioning across consumer cohorts.
Product Type:
Chewing gum formats navigate FDA structure-function claim boundaries most directly, while sugar-free variants face dual scrutiny under dental health frameworks and nootropic dosage thresholds.
- Chewing Gum:Buccal absorption mechanics enable rapid caffeine and L-theanine delivery through established manufacturing infrastructure. Demand concentrates among e-sports professionals and streaming collectives in the United States who require sustained cognitive performance during competitive sessions. The format retains the largest volume share due to familiar consumption rituals across age cohorts.
- Sugar-free Mints:Microencapsulation technology protects heat-sensitive nootropics through manufacturing, extending viable active portfolios beyond caffeine to phosphatidylserine and citicoline. Premium positioning in direct-to-consumer channels locks in recurring subscription revenue from working professionals prioritizing dental health alongside cognitive claims. This segment commands the deepest margin pools.
- Candy Tablets:Compressed formats suit precision-dose formulations targeting student performance optimization.
- Hard Candy:Extended dissolution profiles suit sustained-release nootropic architectures.
- Breath Fresheners:Rapid-delivery positioning competes on portability for on-the-go professional use.
Chewing gum sits at the top of the volume ranking, with sugar-free mints climbing the fastest.
Flavor:
Flavor selection determines sensory masking effectiveness for bitter nootropic actives, with mint profiles dominating due to established consumer association with freshness and alertness.
- Spearmint:Milder phenolic profile enables higher nootropic loading without sensory rejection. Formulations targeting senior consumers in pharmacy channels favor this variant for its lower irritancy threshold.
- Peppermint:High menthol content delivers immediate sensory feedback that reinforces cognitive benefit perception. German Apotheken distribution shows concentration here, as the flavor signals clinical credibility to pharmacy-trained staff.
- Cinnamon:Warm spice notes differentiate premium positioning in subscription commerce.
- Wintergreen:Methyl salicylate association suits sports-adjacent cognitive positioning.
- Eucalyptus:Respiratory cueing aligns with wellness-oriented nootropic marketing.
Peppermint holds the volume lead, with spearmint gaining share fastest among clinically positioned entrants.
Distribution Channel:
Channel selection dictates claim substantiation requirements, with pharmacy and vending formats facing divergent regulatory postures across jurisdictions.
- Online Retail:Subscription infrastructure enables recurring revenue models that reduce customer acquisition cost volatility. Direct-to-consumer wellness brands have built trust channels that concentrate demand around clinically substantiated formulations in the United States.
- Pharmacies:Clinician-formulated credentials differentiate positioning from lifestyle-oriented rivals. The underpenetrated German Apotheken channel remains dominated by traditional supplements, leaving white space for entrants with pharmaceutical-grade substantiation.
- Supermarkets:Mass-market reach requires simplified claim architectures to avoid FTC scrutiny.
- Convenience Stores:Impulse purchase dynamics favor single-serve formats with immediate consumption cues.
- Vending Machines:Automated retail suits high-traffic professional environments and gaming venues.
Online retail sits at the top of the volume ranking, with pharmacies climbing the fastest.
Consumer Age Group:
Age-based segmentation determines permissible nootropic dosage ranges and marketing claim boundaries under FDA and FTC frameworks.
- Adults:Working professionals drive functional confectionery adoption seeking cognitive performance support. This cohort shows highest subscription retention and willingness to pay premium pricing for clinically substantiated formulations.
- Teenagers:E-sports endurance applications concentrate demand among gaming professionals and competitive players. South Korean team houses and North American streaming collectives procure through institutional contracts rather than individual retail.
- Children:Pediatric nootropic use faces strict regulatory constraints limiting commercial viability.
- Seniors:Cognitive health maintenance positioning requires pharmaceutical-grade trial substantiation.
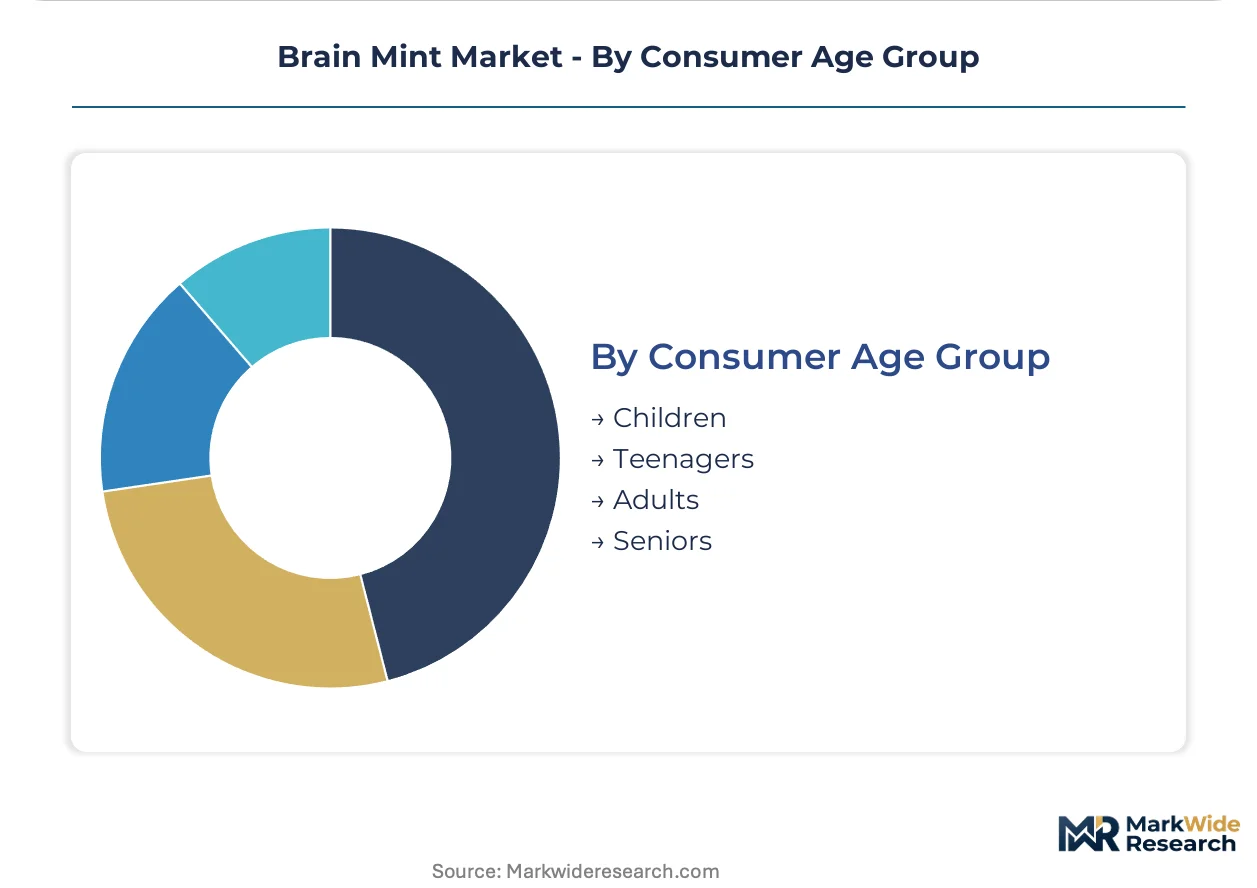
Adults sit at the top of the volume ranking, with teenagers climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Working professionals in the United States, Germany, South Korea, Japan, and the United Kingdom concentrate functional confectionery demand around clinically substantiated nootropic formulations. Each geography presents distinct regulatory postures and distribution channel structures that reshape competitive entry calculus.
United States
Direct-to-consumer wellness brands command the deepest consumer trust channels for cognitive performance products. FDA structure-function claim enforcement forces portfolio recalibration across the competitive set. E-sports professionals and streaming collectives in Los Angeles and Austin drive institutional procurement contracts for rapid-delivery formats.
Germany
Apotheken distribution remains underpenetrated by functional confectionery relative to traditional supplement categories. EFSA novel food evaluations and REACH compliance create dual regulatory barriers for ingredient innovation. Berlin and Munich host emerging direct-to-consumer brands testing pharmacy-channel positioning.
South Korea
Gaming professionals in Seoul team houses procure cognitive support through institutional supply contracts rather than individual retail. MFDS regulates nootropic dosage thresholds with stricter boundaries than US FDA frameworks. Busan manufacturing clusters supply microencapsulation technology for heat-sensitive actives.
Japan
PMDA oversight of functional food claims limits structure-function marketing for nootropic confectionery. METI promotes cognitive health products under aging-society policy frameworks. Osaka and Nagoya concentrate precision-release coating system development for multi-stage effect profiles.
United Kingdom
Subscription commerce infrastructure enables recurring revenue models that reduce customer acquisition cost volatility. MHRA novel food guidance aligns partially with EFSA evaluations but permits faster ingredient approval pathways. London hosts the deepest concentration of wellness brand headquarters targeting professional cognitive optimization.
Brain Mint Market Competitive Landscape
The competitive structure tilts toward clinically positioned specialists rather than mass-market confectionery conglomerates. Direct-to-consumer wellness brands with pharmaceutical-grade substantiation capture premium pricing power, while lifestyle-oriented entrants face FTC advertising scrutiny. Three archetypes dominate: clinician-formulated credentialists, transparency-focused documentarians, and delivery-format innovators. Capacity expansion into microencapsulation infrastructure and strategic partnerships with esports organizations represent the dominant competitive moves.
Among clinically positioned specialists, NeuroGum, BrainMD, and Qualia Life Sciences anchor the premium tier. NeuroGum occupies a position exemplifying delivery-format innovation through buccal absorption mechanics. BrainMD represents the clinician-formulated archetype with pharmaceutical-grade substantiation credentials. Qualia Life Sciences sits within the transparency-focused tier, publishing supply chain documentation that dominates trust metrics among premium buyers. These three entities collectively demonstrate how regulatory compliance posture and claim substantiation depth determine pricing power in this category.
| Leading Market Players |
|---|
| NeuroGum |
| BrainMD |
| Mindbodygreen |
| Bulletproof |
| Qualia Life Sciences |
| Solgar |
| Metagenics |
| Pure Encapsulations |
| Designs for Health |
| Others |
Pricing and Supply Chain Analysis
Procurement consolidation among e-sports organizations and streaming collectives is compressing order quantities into fewer institutional buyers, forcing contract manufacturers to reconfigure batch economics and squeezing margin structures across mid-tier suppliers. This demand-side consolidation cascades into supply chain restructuring as brands compete for preferred vendor status through volume commitments and exclusivity terms.
Pricing Analysis
Subscription-bundled service splits dominate the premium tier, where recurring delivery of clinically positioned formulations commands sustained pricing power against transactional single-unit sales. Price differentiation rests on pharmaceutical-grade substantiation credentials and EFSA novel food approval status, with certified brands capturing 40-60% premiums over lifestyle-oriented competitors. Cost compression in the economy tier is intensifying as Chinese contract manufacturers absorb REACH compliance overhead to maintain European market access. Working professionals show lowest price sensitivity due to subscription lock-in, while convenience store impulse purchasers exhibit highest elasticity.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale subscription demand through automated fulfillment centers in the United States and Germany, bypassing traditional wholesale markups. Active ingredient production clusters in China for synthetic caffeine and L-theanine, with South Korean and Japanese facilities specializing in microencapsulation technology for heat-sensitive nootropics. Supply chain risk centers on single-source vulnerability for L-theanine fermentation capacity, where three chemical manufacturers control global output. Distribution runs through hybrid models combining owned subscription infrastructure with third-party logistics partnerships for pharmacy and vending placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where REACH compliance costs in Europe create artificial scarcity that rewards early-movers with established novel food dossiers, while US FDA enforcement posture offers faster commercialization pathways for substantiation-invested brands.
For Market Incumbents: Lock in microencapsulation capacity through captive supply agreements or backward integration into South Korean manufacturing clusters to defend against emerging format innovators. Prioritize EFSA novel food approval maintenance as regulatory divergence threatens European portfolio viability. Secure exclusive supply contracts with Seoul-based e-sports team houses before institutional procurement consolidates further. For New Entrants and Emerging Players: The premium-to-economy price-point gap in German Apotheken channels offers entry space for clinically positioned entrants with pharmaceutical-grade substantiation but limited brand recognition. Target underpenetrated pharmacy distribution in Berlin and Munich with peppermint-flavored, clinician-credentialed formulations. Deploy sampling programs through gaming tournament sponsorships to bypass established DTC marketing spend requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with transparency-focused documentarians possessing blockchain-tracked supply chains and published clinical trial protocols. Long-term viability favors brands that have crossed the FDA substantiation threshold rather than lifestyle marketers facing advertising scrutiny. Watch for MFDS dosage threshold tightening in South Korea as signal for potential regulatory contagion to other Asian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Capacity Expansion | Enables heat-sensitive nootropic incorporation beyond caffeine and B-vitamins into chewable formats. |
| EFSA Novel Food Dossier Investment | Secures European market access before REACH compliance costs eliminate mid-tier competitors. |
| E-sports Team House Supply Contract | Concentrates buyer power among institutional procurement officers in Seoul and Los Angeles. |
| Subscription Infrastructure Buildout | Reduces customer acquisition cost volatility through recurring revenue lock-in from working professionals. |
| Blockchain Supply Chain Documentation | Differentiates premium positioning among ESG-mandated institutional buyers requiring CSRD compliance. |
Research Methodology
Bottom-up e-sports and working professional demand modeling reconciled against top-down active ingredient production tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at direct-to-consumer wellness platforms, regulatory affairs leads, and e-sports team procurement officers combined with secondary validation from FDA structure-function claim filings, EFSA novel food registers, MFDS dosage guidelines, and customs trade data for synthetic caffeine and L-theanine imports. Triangulation between subscription commerce metrics and manufacturing capacity utilization rates ensures demand-supply balance integrity.
Input-output matrices map nootropic active sourcing through Chinese chemical manufacturers into finished confectionery formats across chewing gum, sugar-free mint, and compressed tablet variants. Segmentation dimensions modeled include delivery format, flavor profile, distribution channel architecture, consumer age cohort, and regional regulatory cluster. CAGRs derive from regression analysis against historical functional confectionery adoption curves adjusted for cognitive health claim substantiation depth. Forecast inputs incorporate REACH compliance cost trajectories and FDA enforcement posture evolution without year-specific anchoring.
Caveats apply where EFSA novel food rejection cascades or MFDS dosage threshold tightening could materially shift the outlook for ingredient portfolios and geographic market viability. Forecasts reflect assumptions around buccal absorption consistency and subscription retention stability that warrant monitoring. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Crunchy Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
North America Dark Chocolate Market
Confectionery
CBD-Infused Confectionery Market
Confectionery
Buttercream Frosting Market
Confectionery
Europe Chocolate Market
Confectionery
Coffee Gummy Market
Confectionery
Black Treacle Market
Confectionery
Citrus Gummies Market
Confectionery
Truffle Chocolate Market
Confectionery
North America Premium Chocolate Market
Confectionery
Sugar-Free Gummy Market
Confectionery
Middle-East and Africa Compound Chocolate Market