
 Gulf Cooperation Council Fragrance and Perfumes Market | 2026-2036
Gulf Cooperation Council Fragrance and Perfumes Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf Cooperation Council Fragrance and Perfumes Market Foresight
Duty-free retail corridors across GCC airports are reshaping how prestige fragrance brands reach international travelers. Rasasi Perfumes Industry leverages its captive manufacturing base in Dubai to sustain price competitiveness across Middle Eastern routes. Abdul Samad Al Qurashi Company anchors its position through heritage oud formulations that dominate heritage retail segments. Ajmal Perfumes competes by extending its distribution footprint into Southeast Asian diaspora markets.
Gulf Cooperation Council fragrance and perfumes encompass alcohol-based and oil-based scent formulations with concentrations ranging from Eau de Toilette to pure perfume oil, designed for personal adornment and cultural gifting customs. These products serve both daily wear occasions and ceremonial hospitality traditions across Arabian Peninsula societies. Eau de Parfum commands the dominant value share due to higher oil concentration and extended longevity in arid climates. Perfume Oil segments register accelerated expansion as consumers shift toward alcohol-free alternatives aligned with regional preferences. Natural ingredient categories face margin pressure from oud scarcity and sustainable harvesting constraints.
SFDA in Saudi Arabia and SASO enforce evolving fragrance safety protocols that mandate allergen labeling and restrict specific synthetic compounds. The EU REACH framework indirectly shapes GCC import standards as European houses supply regional distributors. Stakeholders must monitor regulatory divergence between national Gulf standards and evolving EU cosmetic regulations to anticipate reformulation costs and compliance timelines.
Market Dynamics
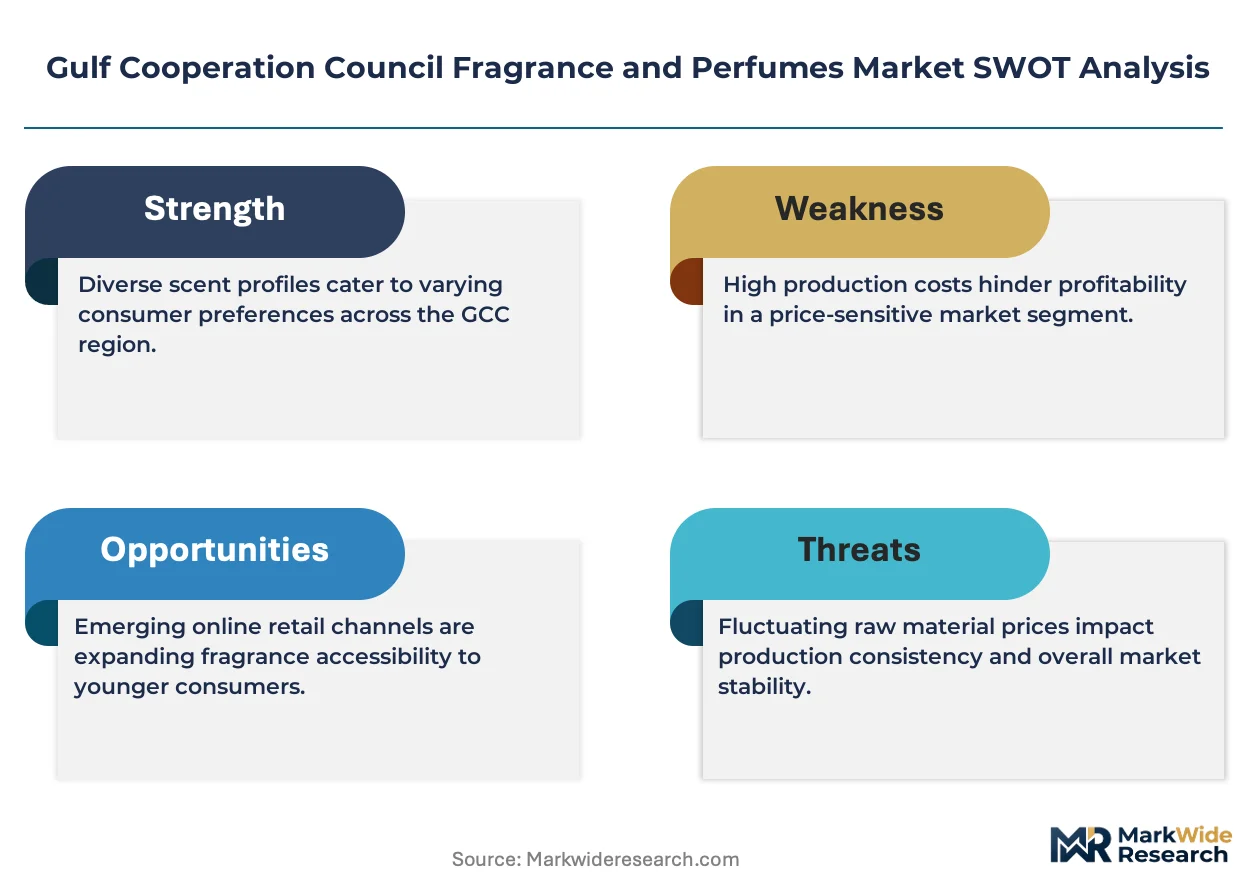
Concentrated perfume oil demand across Saudi Arabia and the UAE is compressing traditional alcohol-based fragrance volumes while forcing reformulation investments and retail space reallocation.
Growth Catalysts
- SFDA allergen disclosure mandates:Saudi Arabia's tightening ingredient transparency rules are accelerating premium brand differentiation through clean-label positioning.
- Heritage gifting customs:Ceremonial hospitality traditions across Arabian Peninsula societies sustain high-velocity purchase cycles for oud-based formulations.
- Dubai airport duty-free corridors:Prestige brand exposure to international transit passengers generates trial-to-loyalty conversion at unmatched scale.
Market Restraints
- Oud raw material scarcity:Sustainable harvesting constraints in Southeast Asian supply zones are elevating input costs for natural ingredient categories.
- EU REACH indirect compliance burden:European cosmetic export standards force Gulf distributors into costly dual-track formulation testing.
- Synthetic compound restrictions:SASO prohibitions on specific fragrance molecules limit palette options for mass-market product development.
Strategic Opportunities
- Riyadh luxury zone emergence:Saudi retail infrastructure expansion creates first-mover positioning for experiential flagship formats.
- Southeast Asian diaspora channels:Extended distribution into Muslim-majority export markets unlocks volume beyond domestic saturation.
- Alcohol-free formulation innovation:Converging biotech extraction methods with traditional maceration processes enables next-generation oil-based delivery systems.
Industry Challenges
- Master perfumer talent scarcity:Deep expertise in oud compounding concentrates among aging practitioner networks with limited knowledge transfer mechanisms.
- Dual regulatory certification timelines:Parallel SFDA and SASO approval pathways extend product launch windows by 8-14 months.
- Legacy retail fixture integration:Premium mall operators resist space reconfiguration for experiential oil-sampling formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf Cooperation Council Fragrance and Perfumes Market |
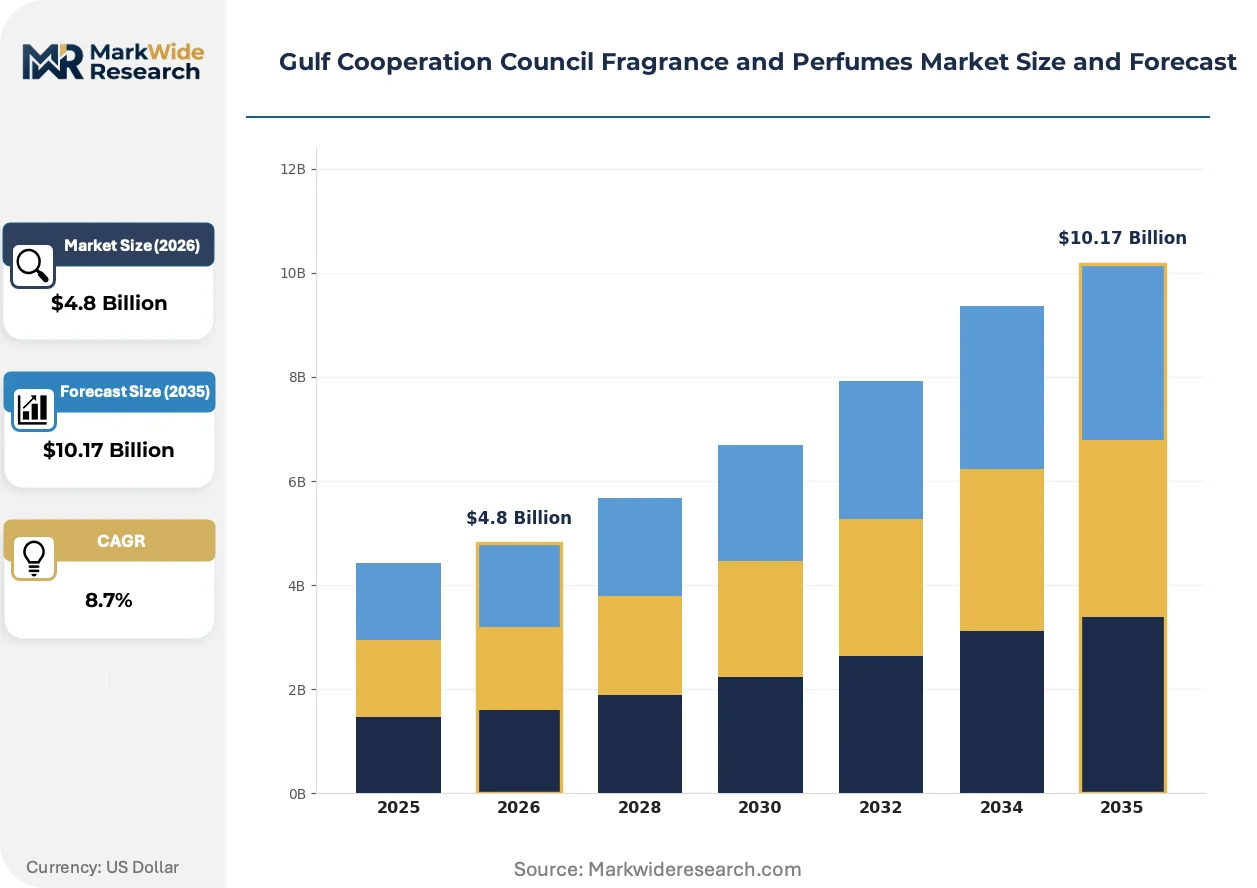
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eau de Parfum, Eau de Toilette, Perfume Oil, Body Spray Ingredient Type: Natural, Synthetic, Essential Oils, Floral End User: Women, Men, Unisex, Children Distribution Channel: Online, Specialty Stores, Supermarkets, Department Stores |
| Companies Covered | Rasasi Perfumes Industry, Abdul Samad Al Qurashi Company, Procter & Gamble, Coty Inc., Estee Lauder, L'Oreal, Ajmal Perfumes, Fragrance World Perfumes, Arabian Oud Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf Cooperation Council Fragrance and Perfumes Market Shifts & Advancements
Digital scent profiling and AI-driven personalization are compressing traditional counter-based consultation models while elevating precision in fragrance matching.
Molecular distillation technology is digitizing how concentrated perfume oils achieve batch consistency. Heritage houses in Dubai and Jeddah are adopting automated compound analysis to preserve signature oud profiles at commercial scale. This precision layer is compressing artisan-to-industrial quality variance windows.
SFDA and SASO are converging toward unified GCC fragrance safety protocols with mandatory allergen labeling expansions. The regulatory alignment is forcing multinational houses into consolidated Gulf-specific formulation lines. Smaller regional blenders face disproportionate compliance cost absorption.
Direct-to-consumer sampling via subscription micro-vials is displacing traditional department store discovery rituals. Younger buyers across Saudi Arabia and Kuwait are prioritizing home-based trial before flagship commitment. This behavioral pivot is compressing foot traffic dependency for prestige retail locations.
Gulf Cooperation Council Fragrance and Perfumes Market Segmentation
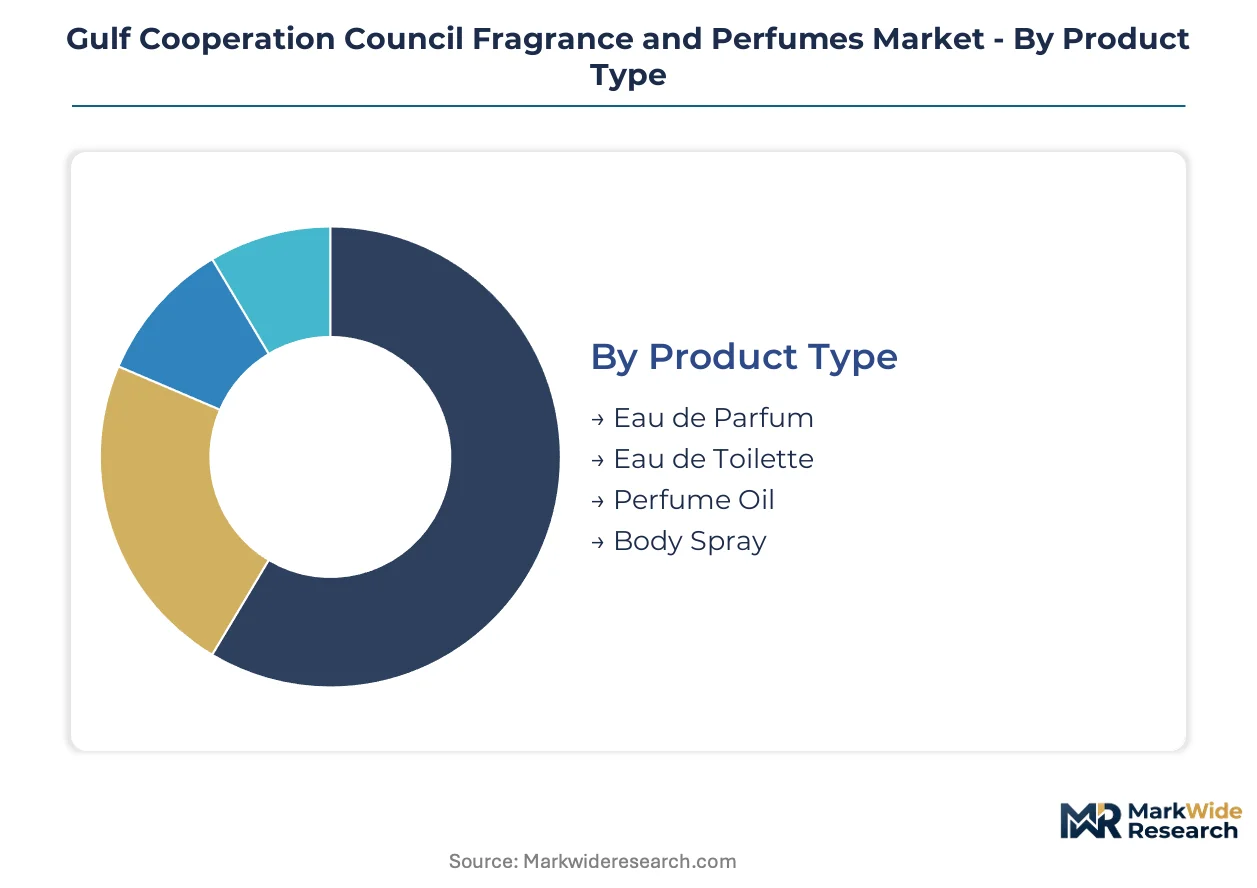
Segmentation in the Gulf Cooperation Council fragrance and perfumes market reveals distinct consumption patterns tied to cultural preferences, climate adaptation, and retail infrastructure maturity across Saudi Arabia and the UAE. Understanding these divisions enables precise resource allocation for formulation development, channel investment, and geographic targeting.
Product Type:
After-sales service intensity varies dramatically across product formats, with oil-based formulations demanding specialized application guidance and longevity consulting that alcohol-based alternatives rarely require.
- Eau de Parfum:Higher oil concentration formulations deliver extended longevity in arid Gulf climates. Demand concentrates among working professionals in Dubai and Riyadh seeking all-day projection without reapplication.
- Perfume Oil:Alcohol-free compositions align with regional preferences for skin-friendly, long-lasting scents. Accelerated uptake across Saudi Arabia's conservative consumer base is compressing traditional spray fragrance volumes.
- Eau de Toilette:Lighter concentration suited for daily office environments and high-temperature outdoor exposure.
- Body Spray:Mass-market positioning targets younger demographics and price-sensitive volume purchasing.
Eau de Parfum holds the largest share; momentum sits with Perfume Oil.
Ingredient Type:
Cost tier stratification separates heritage natural formulations from scalable synthetic alternatives, with premium positioning commanding fivefold price multiples at retail.
- Natural:Oud, ambergris, and resin-based compositions derived from sustainable harvesting protocols. Supply constraints in Southeast Asian source regions are elevating input costs and extending lead times for Gulf blenders.
- Synthetic:Laboratory-engineered molecules replicating rare natural notes at commercial scale. Dominates mass-market production across Dubai manufacturing zones due to batch consistency and regulatory predictability.
- Essential Oils:Plant-derived concentrates requiring cold-chain handling and shorter shelf life management.
- Floral:Rose, jasmine, and orange blossom distillations favored for ceremonial gifting occasions.
Natural ingredients anchor premium positioning; synthetic compounds drive volume scalability.
End User:
Application context determines formulation intensity, with professional environments demanding subtle projection and ceremonial settings permitting opulent sillage.
- Women:Floral-oud fusion compositions dominate purchasing across UAE luxury retail corridors. Seasonal collection cycles align with Ramadan and Eid gifting peaks.
- Men:Woody-spicy profiles concentrated in Saudi Arabia's heritage retail segments. Unisex crossover acceptance is expanding category boundaries.
- Unisex:Gender-neutral positioning gaining traction among younger demographics in Kuwait and Bahrain.
- Children:Alcohol-free, hypoallergenic formulations for ceremonial family occasions.
Women's fragrances generate the highest absolute revenue; unisex positioning is expanding most quickly.
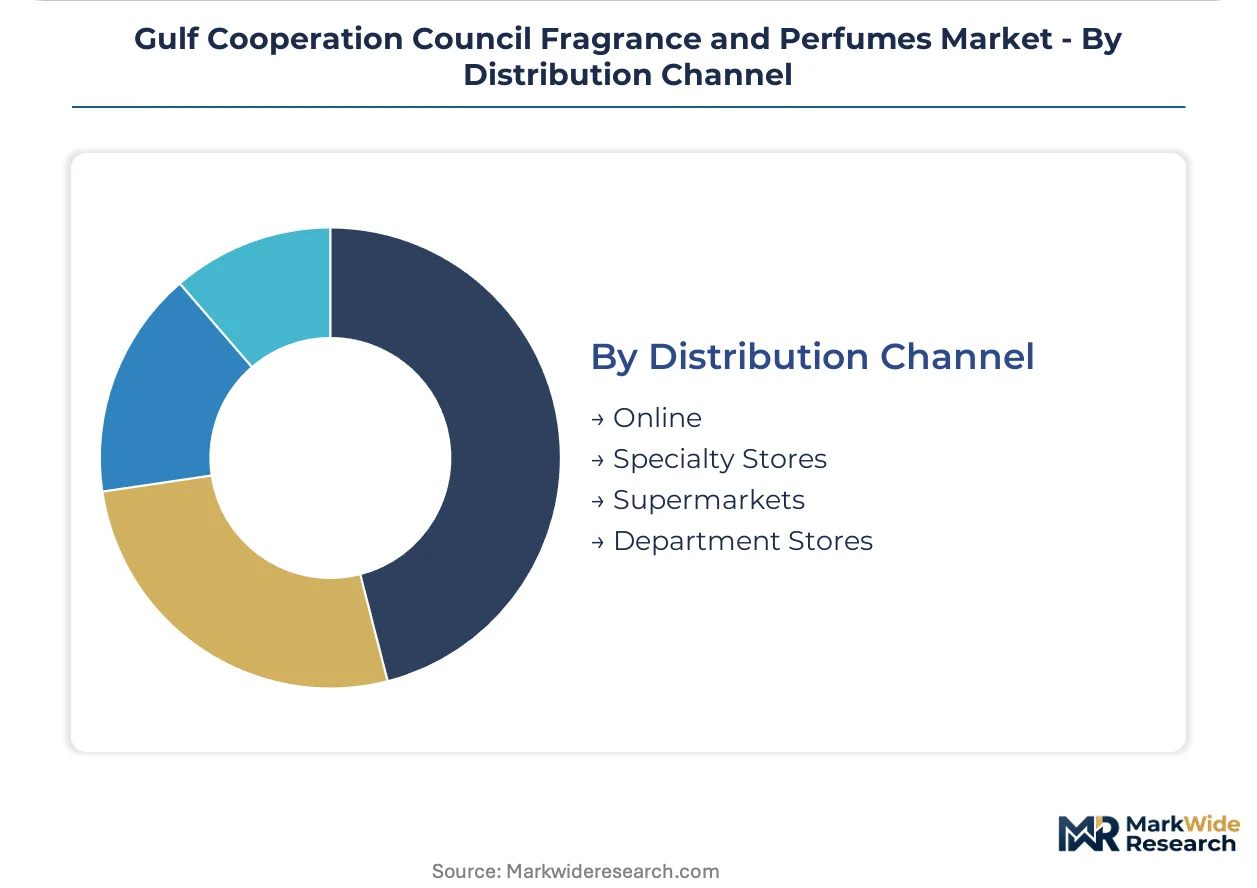
Distribution Channel:
Customer type stratification separates experiential buyers seeking consultation from transactional purchasers prioritizing convenience and price transparency.
- Specialty Stores:Staff-trained environments offering personalized scent profiling and layering guidance. Concentrate in Dubai Mall and Riyadh's emerging luxury zones where conversion rates exceed general retail benchmarks.
- Online:Subscription micro-vial sampling and AI-driven recommendation engines. Younger Saudi consumers are prioritizing home-based trial before flagship commitment, compressing foot traffic dependency.
- Department Stores:Legacy prestige brand presence with counter-based consultation models.
- Supermarkets:Mass-market accessibility for body sprays and entry-priced formats.
Specialty stores retain the highest margin contribution; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands pricing premiums on heritage oud formulations while UAE retail density compresses margin capture for comparable products. This asymmetry shapes cross-border sourcing patterns and distributor location decisions across the Gulf Cooperation Council.
Saudi Arabia
Riyadh's luxury zone expansion and Jeddah's heritage retail corridors drive concentrated perfume oil demand. SFDA allergen disclosure mandates are accelerating reformulation investments among domestic blenders. The Eastern Province manufacturing cluster near Dammam is absorbing new extraction technology to secure oud supply chain control.
United Arab Emirates
Dubai Mall and Abu Dhabi's Yas Mall anchor experiential flagship formats for prestige fragrance houses. MOHAP cosmetic safety protocols align with emerging GCC-wide standards on ingredient transparency. Jebel Ali manufacturing zones host captive production facilities serving duty-free corridor volumes.
Kuwait
High per-capita fragrance expenditure sustains premium positioning for heritage oud houses. The national standards body enforces parallel compliance pathways with Saudi and Emirati regulatory frameworks. Kuwait City's Salhiya retail district concentrates specialty store formats with trained scent consultation staff.
Qatar
Luxury hospitality procurement drives institutional volume for concentrated perfume oil categories. The national quality infrastructure authority monitors fragrance safety alignment with Gulf standardization initiatives. Doha's Pearl-Qatar retail cluster is attracting experiential flagship investments from regional heritage brands.
Bahrain
Cross-border shopping flows from eastern Saudi Arabia sustain Manama's fragrance retail density. The national regulatory authority maintains equivalence with SASO and SFDA cosmetic safety requirements. Bahrain's duty-free zone at the airport serves as a trial-to-loyalty conversion point for transit passengers.
Gulf Cooperation Council Fragrance and Perfumes Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in raw material and extraction technology. The vendor base separates between multinational houses with Gulf-specific formulation lines and regional heritage blenders with captive oud sourcing. Three archetypes dominate: European luxury houses with regional adaptation capabilities, Arabian heritage brands with vertical oud control, and mass-market distributors with private label portfolios. Competitive moves concentrate on regulatory certification parallelism and experiential retail format deployment.
Among heritage fabricators with generational oud expertise, Rasasi Perfumes Industry, Abdul Samad Al Qurashi Company, and Ajmal Perfumes occupy positions representing distinct geographic anchoring within the Gulf Cooperation Council. These entities exemplify the specialist tier where deep compounding knowledge and sustained raw material relationships create defensive positioning against multinational expansion. Their archetype sits upstream from the platform integrators, supplying both direct retail presence and ingredient foundations for broader market coverage.
| Leading Market Players |
|---|
| Rasasi Perfumes Industry |
| Abdul Samad Al Qurashi Company |
| Procter & Gamble |
| Coty Inc. |
| Estee Lauder |
| L'Oreal |
| Ajmal Perfumes |
| Fragrance World Perfumes |
| Arabian Oud Company |
| Others |
Supply & Pricing Matrix
Jebel Ali's captive manufacturing cluster in Dubai anchors regional fragrance production capacity, concentrating formulation expertise and bulk compounding infrastructure that downstream distributors leverage for margin control across GCC retail corridors.
Pricing Analysis
Configured-to-order heritage oud formulations command fivefold premiums over standard synthetic alternatives across Saudi Arabia's heritage retail segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient concentration and certification tier, with SFDA allergen disclosure mandates accelerating clean-label price premiums. Cost compression in mass-market Eau de Toilette segments intensifies as synthetic compound restrictions limit formulation flexibility. Younger demographics in Kuwait and Bahrain exhibit highest price sensitivity, while ceremonial gift purchasers in Riyadh's luxury zones demonstrate lowest elasticity.
Supply Chain Analysis
Extended payment terms from Southeast Asian oud harvesters to Dubai-based compounders compress working capital cycles for regional blenders. Supply concentrates in Thailand, Cambodia, and Vietnam for agarwood resin, while synthetic molecule production centers on China and India. Jebel Ali and Dammam manufacturing zones feed from these inputs, with single-source vulnerability in mature agarwood groves elevating cost unpredictability. Distribution runs through duty-free corridors at Dubai International Airport and Riyadh's King Khalid International Airport, bypassing traditional wholesale layers for transit passenger conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC fragrance demand cycles track pilgrimage travel volumes and hospitality sector expansion, with Umrah and Hajj recovery patterns signaling near-term volume inflection across Saudi Arabia's retail corridors.
For Market Incumbents: Entrench heritage oud sourcing relationships through backward integration into sustainable Southeast Asian harvesting partnerships, insulating against raw material scarcity that Rasasi and Abdul Samad Al Qurashi already exploit. Expand experiential flagship footprints in Riyadh's emerging luxury zones before retail space saturation tightens. Dual regulatory certification timelines represent the critical threat compressing product launch velocity. For New Entrants and Emerging Players: Alcohol-free perfume oil formulations for Saudi Arabia's conservative consumer base represent the most penetrable entry point, with demand acceleration outpacing incumbent capacity allocation. Southeast Asian diaspora channels in Malaysia and Indonesia offer volume extension beyond domestic GCC saturation. Direct-to-consumer subscription sampling models bypass legacy department store gatekeeping that entrenched players dominate. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional heritage blenders with captive oud supply relationships and automated compound analysis capabilities, as molecular distillation standardization separates scalable artisan operations from craft-limited competitors. Acquisition targets should demonstrate vertical integration into sustainable harvesting protocols and SFDA pre-certification status. Inflection signals to monitor include unified GCC fragrance safety protocol ratification and Dubai airport duty-free passenger traffic recovery trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Experiential Flagship Expansion | Riyadh's emerging luxury zones enable first-mover positioning before retail space constraints tighten. |
| Backward Integration into Oud Sourcing | Sustainable harvesting partnerships in Southeast Asia secure supply chain control against scarcity-driven cost spikes. |
| Alcohol-Free Formulation Innovation | Biotech extraction methods converging with traditional maceration unlock next-generation oil-based delivery systems. |
| Dual Regulatory Certification Investment | Parallel SFDA and SASO approval pathways compress launch windows for compliant product lines. |
| Diaspora Channel Extension | Southeast Asian Muslim-majority markets extend volume beyond domestic GCC saturation points. |
Research Methodology
A spread of perspectives from master perfumers, heritage house supply chain directors, SFDA regulatory affairs specialists, and Dubai Mall category buyers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SFDA cosmetic safety filings, and duty-free retail audit records from Dubai International Airport and King Khalid International Airport. Bottom-up volume triangulation across product type, ingredient category, and distribution channel intersected with top-down macroeconomic sizing across the analysis window.
Demand-supply balance modeling tracked pilgrimage travel recovery patterns, hospitality sector procurement cycles, and retail infrastructure expansion timelines across Saudi Arabia and the UAE. Segmentation dimensions included product concentration tier, natural versus synthetic ingredient classification, end-user demographic, and channel format. CAGRs derived from iterative regression against historical volume trajectories and elasticity-adjusted forward projections, with oud raw material cost curves and regulatory compliance cost absorption as industry-specific forecast inputs.
Practitioners should monitor unified GCC fragrance safety protocol negotiations, sustainable agarwood harvesting certification expansion, and Dubai airport passenger traffic indices for early signals of assumption drift. Macroeconomic deviation in oil-dependent government spending, regulatory divergence between national Gulf standards and EU REACH alignment timelines, or technological disruption in molecular replication of rare natural notes would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
UAE Perfume Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
Saudi Arabia Perfume Market
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
GCC Perfume and Fragrance Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Digital Fragrance Market
Fragrances & Perfumes
Wax Melts Market