
 UAE Perfume Market | 2026-2036
UAE Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Perfume Market Intelligence
Dubai's luxury retail infrastructure expansion is reshaping how fragrance houses allocate regional capacity. Ajmal Perfumes leverages its vertically integrated oud sourcing and distillation network to control raw material quality from harvest to bottling. Swiss Arabian anchors its position through mass-market accessibility across GCC duty-free channels. Amouage competes at the ultra-premium tier with limited-batch attars and international boutique distribution.
Perfumes are formulated compositions of aromatic compounds, fixatives, and solvents designed to emit a persistent scent profile on skin or fabric, typically classified by concentration levels from eau fraîche to pure parfum based on oil-to-alcohol ratios. The UAE market serves both personal adornment and cultural gifting functions, with oud-based and musk-heavy formulations holding particular ceremonial significance. Oil-based and non-alcoholic variants command structural preference among local consumers seeking longer-lasting sillage aligned with regional climate conditions and religious observance. Luxury buyers and unisex segments represent the fastest-expanding customer pools, while glass bottle packaging dominates premium positioning due to perceived preservation quality and gifting aesthetics.
MOHAP and the Emirates Authority for Standardization and Metrology enforce fragrance safety standards, ingredient labeling protocols, and halal certification requirements that determine market access for both domestic manufacturers and imports. Compliance with these frameworks shapes formulation decisions, particularly around alcohol content thresholds and allergen disclosure. Stakeholders must monitor evolving halal certification criteria and sustainability disclosure expectations as Dubai advances its consumer protection agenda.
Market Dynamics
The UAE perfume market is being fundamentally restructured by MOHAP's escalating halal certification mandates, which are forcing reformulation across alcohol content thresholds and accelerating investment in non-alcoholic extraction technologies.
Growth Catalysts
- Luxury tourism infrastructure:Dubai International Airport's duty-free expansion and Mall of the Emirates flagship clustering are creating captive high-spend audiences for oud and attar specialists.
- MOHAP ingredient transparency mandates:The Emirates Authority for Standardization and Metrology's disclosure protocols are rewarding early-compliant houses with preferential retail placement.
- Climate-adapted formulations:Oil-based perfume technologies with extended sillage profiles are capturing share from alcohol-dominant European imports during summer months.
Market Restraints
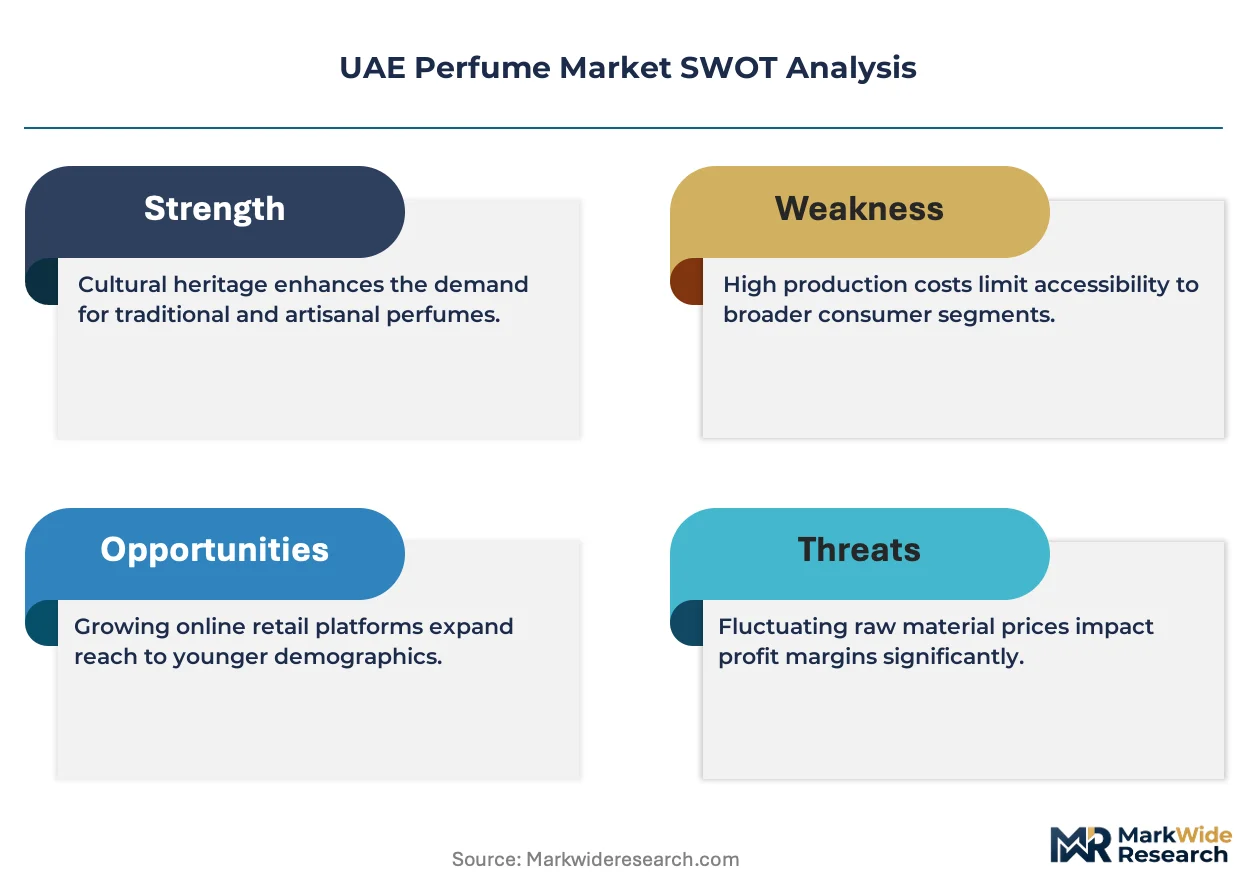
- Agarwood supply concentration:Over 70% of wild oud feedstock originates from Southeast Asian forests facing export restrictions and harvest quotas.
- Halal certification fragmentation:Divergent standards between UAE, Saudi Arabia, and Malaysia create compliance duplication costs for multi-market brands.
- Synthetic musk substitution pressure:Biotech-derived ambrettolide and galaxolide are displacing natural deer musk in price-sensitive gifting segments.
Strategic Opportunities
- Sharjah manufacturing zones:Hamriyah Free Zone's fragrance-specific incentives and proximity to Jebel Ali port offer integrated production-export positioning.
- Biotechnology convergence:Precision fermentation for rare botanicals is enabling sustainable replication of depleted sandalwood and oud notes.
- Direct-to-consumer channels:Instagram and TikTok commerce are bypassing traditional mall dependency for niche Emirati attar houses.
Industry Challenges
- Master perfumer scarcity:The Gulf region lacks training institutions producing nose specialists capable of balancing traditional oud craftsmanship with modern regulatory compliance.
- Glass packaging lead times:European bottle suppliers are extending delivery windows to 16-20 weeks, compressing new product launch calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Perfume Market |
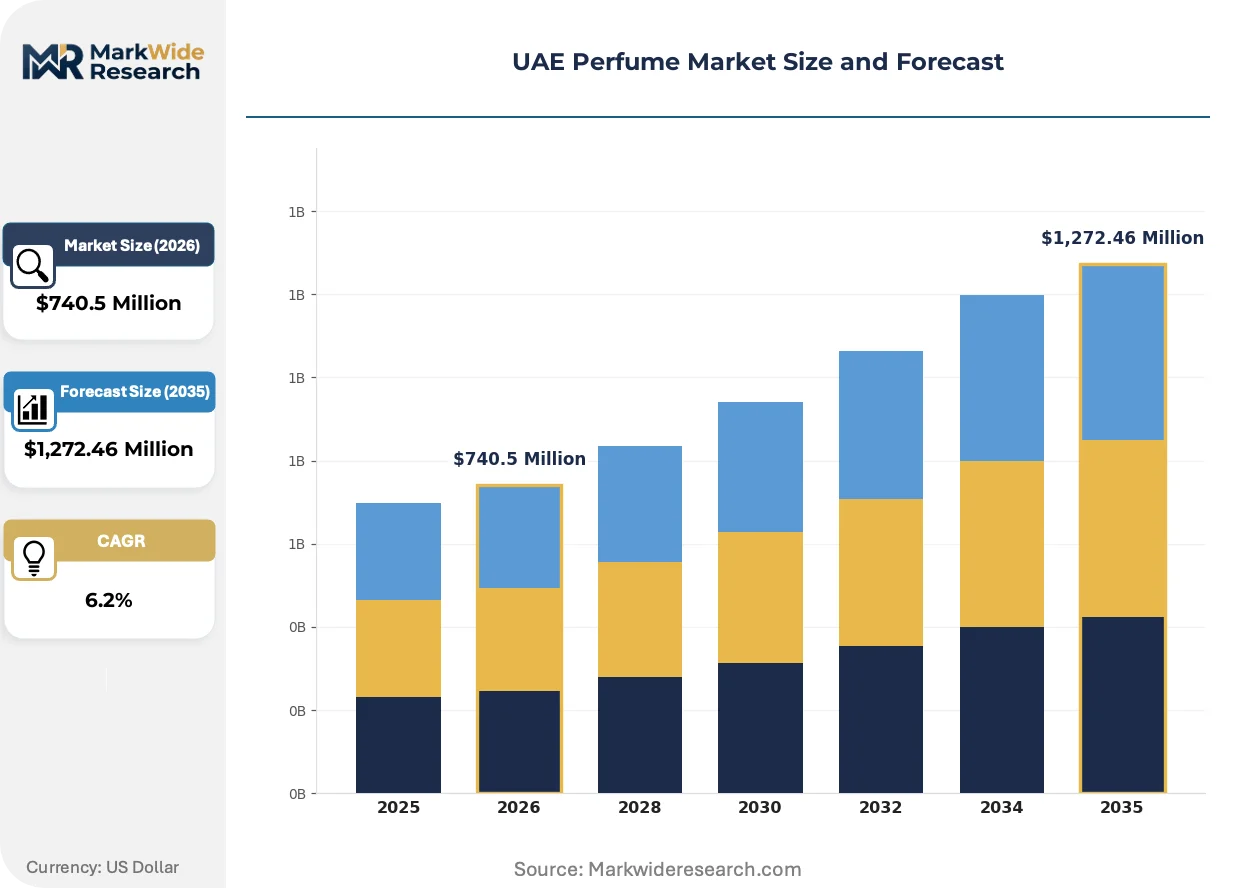
| Market Size in 2026 | $740.5 Million |
| Market Size in 2035 | $1,272.46 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcoholic, Non-Alcoholic, Solid, Oil-Based Packaging Type: Glass Bottles, Plastic Bottles, Roll-On, Gift Sets Customer Type: Men, Women, Unisex, Luxury Buyers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Marketplaces |
| Companies Covered | Ajmal Perfumes, Arabian Oud Company, Swiss Arabian, Rasasi Perfumes, Abdul Samad Al Qurashi Company, Al Haramain Perfumes, Chanel, Dior, Amouage, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Perfume Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reshape how fragrance houses compete across the Emirates, with digitization and regulatory alignment emerging as the primary axes of differentiation.
Headspace capture technology is digitizing the scent replication process by extracting volatile compounds from living flowers without harvest destruction. Amouage and Ajmal are deploying this for endangered rose varieties in their limited attar lines. The technology is compressing R&D cycles from 18 months to under six while preserving biodiversity narratives critical to ultra-premium positioning.
MOHAP's 2024 fragrance safety standard updates are mandating expanded allergen disclosure panels and traceable supply chain documentation for all retail-facing products. Domestic manufacturers are restructuring procurement to comply, while import houses are establishing Dubai-based testing partnerships to accelerate clearance. The attar segment faces the steepest adaptation costs due to complex multi-ingredient traditional recipes.
Gifting occasions are fragmenting purchase patterns as corporate bulk orders decline and individual occasion-based buying rises. Department store counters are losing traffic to specialized oud boutiques in Deira and perfumery districts, where staff expertise justifies premium pricing. Abu Dhabi's Yas Mall and Dubai's City Walk are witnessing the fastest boutique expansion as developers prioritize experiential retail over anchor tenants.
UAE Perfume Market Segmentation
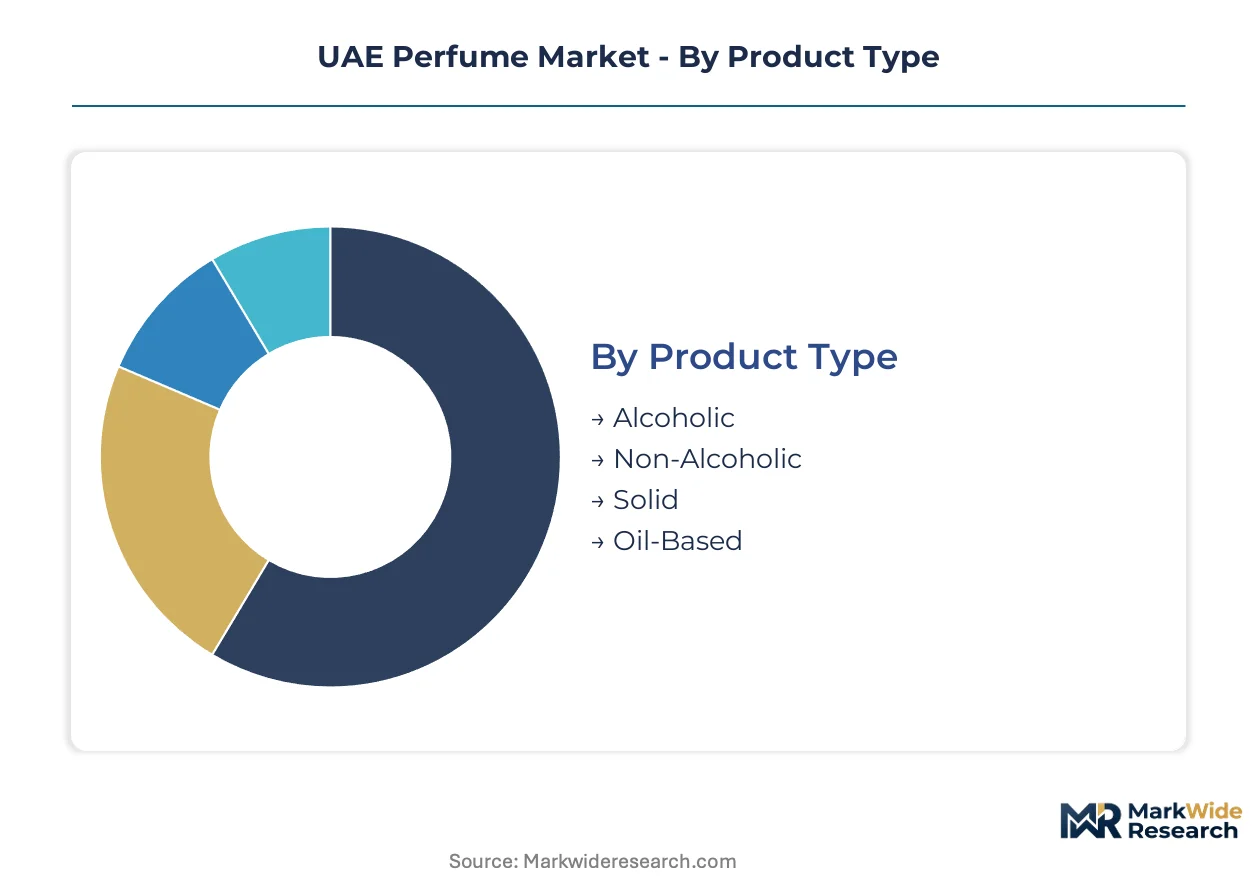
UAE fragrance segmentation reflects the market's dual function as personal adornment and cultural gifting. Religious observance, climate adaptation, and luxury tourism create distinct demand profiles across product formats and customer pools.
Product Type:
Formulation chemistry spans alcohol-dominant European heritage formats to oil-based regional traditions serving religious and climatic requirements.
- Alcoholic:Ethanol-based compositions with 70-90% alcohol content deliver volatile top-note projection favored by expatriate professionals and Western tourists. Dubai Duty Free anchors volume for international prestige houses, though MOHAP labeling mandates now require expanded allergen panels.
- Non-Alcoholic:Water and glycol-based carriers with zero ethanol content serve observant Muslim consumers and Gulf climate conditions where alcohol evaporation accelerates. Ajmal and Swiss Arabian dominate shelf space in Deira souks and Sharjah retail corridors.
- Solid:Wax or balm matrices with 15-25% fragrance load offer portability and discrete application for travel and workplace environments.
- Oil-Based:Pure parfum oils in fractionated coconut or jojoba carriers deliver 8-12 hour sillage profiles prized for ceremonial gifting and summer heat endurance.
Established volume favors Alcoholic; emerging adoption favors Oil-Based.
Packaging Type:
Container economics and gifting ritual shape procurement decisions across mass-market and ultra-premium tiers.
- Glass Bottles:Borosilicate and crystal constructions with UV-protective coatings preserve volatile compounds in premium attar and oud collections. European suppliers extend lead times to 16-20 weeks, compressing launch calendars for Dubai-based houses.
- Plastic Bottles:PET and HDPE formats reduce unit costs for mass-market rollouts across UAE hypermarket chains and GCC export markets.
- Roll-On:10-15ml glass or aluminum rollerball applicators concentrate volume in travel retail and prayer-friendly portable formats.
- Gift Sets:Multi-SKU configurations combining perfume with lotion or incense capture Eid and Ramadan corporate gifting demand.
Glass Bottles command margin concentration; Gift Sets gain share fastest during seasonal peaks.
Customer Type:
Demographic targeting fragments across gender lines, religious practice, and wealth stratification.
- Men:Oud-forward and woody-amber profiles dominate, with oud-musk hybrids serving daily prayer rituals and workplace presence.
- Women:Floral-oriental and gourmand compositions concentrate in Mall of the Emirates and Dubai Mall flagship counters.
- Unisex:Rose-oud and saffron-citrus formulations are climbing the fastest as younger consumers reject gendered marketing.
- Luxury Buyers:Limited-batch attars with certified wild oud sourcing and bespoke blending services command four-figure dirham price points.
Men anchor established volume; Unisex represents the steepest expansion trajectory.
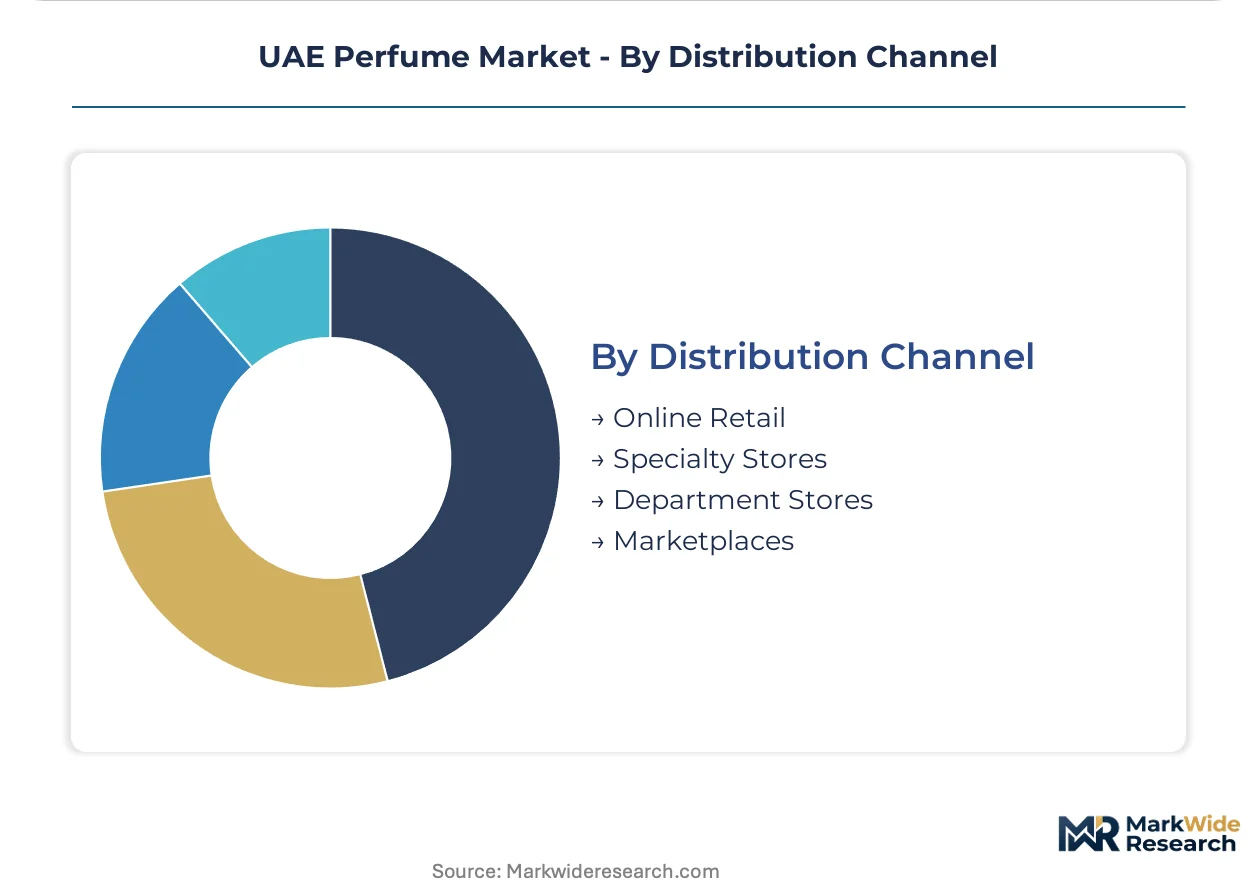
Distribution Channel:
Route-to-market architecture is restructuring as mall dependency weakens and digital capture accelerates.
- Online Retail:Instagram and TikTok commerce enable direct-to-consumer bypass of traditional retail markup for niche Emirati attar houses.
- Specialty Stores:Oud boutiques in Deira and perfumery districts justify premium pricing through staff expertise and ingredient provenance storytelling.
- Department Stores:Harvey Nichols and Bloomingdale's Dubai anchor prestige house visibility, though traffic is fragmenting to experiential formats.
- Marketplaces:Noon and Amazon.ae concentrate price-sensitive volume with fulfillment infrastructure reaching secondary Emirates.
Department Stores defend legacy position; Online Retail is accelerating most rapidly among under-35 demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wild agarwood harvesting concentrates in Southeast Asian forests, with export quotas from Cambodia, Vietnam, and Thailand tightening feedstock access for UAE distillers. This supply bottleneck is redirecting procurement toward plantation-grown alternatives and biotechnology replication methods.
Dubai
Dubai Duty Free's fragrance category expansion and Mall of the Emirates flagship clustering attract high-spend tourists seeking oud and attar exclusives. MOHAP's halal certification mandates require reformulation of alcohol content thresholds for all retail-facing products. Deira's perfumery district and City Walk boutiques concentrate experiential retail growth as developers prioritize specialized over anchor tenants.
Abu Dhabi
Yas Mall's luxury retail expansion and resident wealth concentration sustain demand for limited-batch attars and bespoke blending services. The emirate's consumer protection agenda is advancing sustainability disclosure requirements alongside existing safety standards. Saadiyat Island cultural district retail is emerging as a secondary fragrance destination for museum-going tourists.
Sharjah
Hamriyah Free Zone's fragrance-specific incentives and Jebel Ali port proximity attract manufacturing investment from GCC-exporting houses. The emirate's industrial regulator enforces alignment with federal halal certification protocols for production facilities. Sharjah retail corridors concentrate mass-market accessibility for price-sensitive consumers and prayer-friendly oil-based formats.
Northern Emirates
Ras Al Khaimah and Fujairah's lower operational costs are capturing secondary packaging and fulfillment operations from Dubai-based houses. Federal standards apply uniformly across these emirates, though enforcement capacity varies by municipality. Ajman manufacturing zones are developing as cost-competitive alternatives for mid-tier fragrance bottling and gift set assembly.
UAE Perfume Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in raw material and packaging supply. The UAE fragrance market structures around vertically integrated oud houses, multinational prestige brands, and mass-market GCC exporters. Three archetypes dominate: heritage Emirati distillers with captive agarwood sourcing, European luxury houses leveraging duty-free distribution, and regional scale players optimizing price-accessibility. Competitive moves concentrate on halal certification compliance acceleration and direct-to-consumer channel bypass of traditional retail markup.
Among heritage Emirati houses, Ajmal Perfumes and Arabian Oud Company occupy positions defined by upstream agarwood control and traditional distillation expertise. Rasasi Perfumes exemplifies the mass-market accessibility archetype through GCC duty-free penetration and price-tiered portfolio breadth. Amouage anchors the ultra-premium vector with limited-batch positioning and international boutique distribution. Swiss Arabian sits within the regional scale tier, optimizing manufacturing efficiency for export markets. These players collectively represent the competitive spectrum from raw material sovereignty to brand prestige construction.
| Leading Market Players |
|---|
| Ajmal Perfumes |
| Arabian Oud Company |
| Swiss Arabian |
| Rasasi Perfumes |
| Abdul Samad Al Qurashi Company |
| Al Haramain Perfumes |
| Chanel |
| Dior |
| Amouage |
| Others |
Cost & Logistics Intelligence
Southeast Asian agarwood forests anchor raw material access for UAE distillers, with harvest quotas and export restrictions from Cambodia, Vietnam, and Thailand translating directly into feedstock cost volatility that concentrates pricing power among vertically integrated houses with captive plantation supply.
Pricing Analysis
MOHAP halal certification mandates dictate the pricing tier structure across the UAE fragrance market. Three-tier pricing stratifies across premium attar houses with certified wild oud sourcing, mid-tier regional brands meeting baseline compliance, and mass-market players competing on volume accessibility. Price differentiation centers on certification grade and ingredient provenance documentation. Cost compression in the mass-market tier is intensifying because synthetic musk substitution erodes natural ingredient premiums. Corporate gifting segments show highest price sensitivity, while ultra-premium collectors demonstrate inelastic demand for limited-batch releases with traceable agarwood lineage.
Supply Chain Analysis
CITES export controls limiting wild agarwood flows reshape procurement geography for UAE-based houses. Feedstock draws from Cambodian plantation operations, Vietnamese state-managed harvest quotas, and Thai sustainable forestry initiatives. Raw material dependencies center on agarwood resin grade, sandalwood oil purity, and deer musk alternatives. Single-source vulnerability concentrates around Southeast Asian wild oud supplies facing depletion timelines. Distribution runs through Jebel Ali port consolidation for GCC re-export, with Sharjah free zone manufacturing enabling integrated production-to-retail positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE fragrance market sits at a platform-economics inflection where Instagram and TikTok commerce disintermediate traditional mall-based distribution, creating new interoperability standards between content creation and direct fulfillment.
For Market Incumbents: Harden halal certification compliance infrastructure against MOHAP's escalating disclosure requirements to defend shelf space in Dubai Duty Free and Mall of the Emirates flagship locations. Deepen captive agarwood plantation investment in Southeast Asia to secure feedstock continuity against CITES tightening. Channel control through Deira boutique expansion preserves margin against direct-to-consumer erosion.
For New Entrants and Emerging Players: Pursue underpenetrated Northern Emirates retail corridors in Ras Al Khaimah and Fujairah where operational costs run below Dubai benchmarks and federal standards apply with lighter enforcement capacity. Target price-sensitive prayer-friendly oil-based formats in Sharjah residential districts. Go-to-market leverage through TikTok commerce bypasses traditional retail markup and mall dependency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated oud houses with captive distillation capacity and established GCC export channels. Long-term viability over the coming decade rests on biotechnology replication capabilities for depleted botanicals and direct-to-consumer platform infrastructure. Acquisition targets should demonstrate headspace capture technology deployment or precision fermentation partnerships. Watch for MOHAP sustainability disclosure mandates as the signal forcing balance sheet restructuring toward traceable supply chain documentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | MOHAP compliance timelines determine retail access and duty-free placement priority. |
| Direct-to-Consumer Platform Launch | Instagram and TikTok commerce bypass traditional mall markup for niche attar houses. |
| Biotechnology Partnership | Precision fermentation for sandalwood and oud replication addresses CITES supply risk. |
| Vertical Integration into Plantation Supply | Captive agarwood sourcing in Cambodia and Vietnam secures feedstock against export quotas. |
| Experiential Retail Expansion | Deira and City Walk boutiques justify premium pricing through staff expertise and provenance storytelling. |
Research Approach
A standing panel of fragrance house procurement directors, MOHAP regulatory affairs specialists, Dubai Duty Free category managers, and Southeast Asian agarwood plantation operators provided ongoing calibration. Primary interviews with brand managers at heritage Emirati distillers and European prestige houses active in GCC markets combined with secondary validation from customs trade records, Emirates Authority for Standardization and Metrology filings, and CITES export permit databases. Bottom-up volume modeling across product formats triangulated against top-down tourism spend and resident consumption estimates.
Scenario-bracketing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include formulation chemistry, packaging tier, customer demographic, and distribution channel architecture. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Industry-specific forecast inputs incorporated agarwood harvest quota schedules and halal certification penetration timelines.
Sensitivities concentrate around CITES quota revisions, MOHAP disclosure mandate expansion, and biotechnology replication cost curves. Forecasts reflect documented assumptions on tourism recovery velocity and resident wealth concentration. Material shifts in Southeast Asian export policy or synthetic musk substitution economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Global Perfume Market
Fragrances & Perfumes
Fragrance Emulsion Market
Fragrances & Perfumes
Kuwait Perfume Market
Fragrances & Perfumes
Digital Perfume Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market
Fragrances & Perfumes
Reed Diffusers Market
Fragrances & Perfumes
Fragrance Oil Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Digital Scent Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Fragrance Diffuser Market