
 GCC Perfume and Fragrance Market | 2026-2036
GCC Perfume and Fragrance Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Perfume and Fragrance Market Insights
Aftermarket attar blending and personalized fragrance concierge services is rewriting margin capture across the GCC value chain. Abdul Samad Al Qurashi leverages its vertical control over aged oud resin sourcing to command premium positioning in Riyadh and Jeddah. LVMH Moët Hennessy Louis Vuitton anchors luxury Western fragrance distribution through dedicated boutique networks in Dubai and Abu Dhabi. Arabian Oud Company dominates the traditional oud oil segment with specialized retail footprints across Saudi Arabia, Kuwait, and Bahrain.
Perfume and fragrance encompasses formulated scent compositions using essential oils, aroma compounds, fixatives, and solvents designed for topical application or ambient diffusion, with alcohol concentration typically ranging from 15% to 30% in eau de parfum grades and serving personal grooming, identity expression, and hospitality scenting purposes. The fragrance type dimension shows Oriental and woody profiles commanding dominant shelf space in Gulf retail due to cultural affinity for oud, amber, and musk bases, while fresh and floral categories compete through younger demographic targeting in UAE and Qatari urban centers. Distribution channel dynamics reveal specialty stores and department stores sustaining the highest margin pools through experiential sampling and gift-wrapping services, whereas online retail is accelerating fastest among repeat purchasers seeking subscription-based attar replenishment.
SFDA in Saudi Arabia and MOHAP in the UAE enforce ingredient labeling and allergen disclosure standards that elevate compliance costs for imported European and Asian fragrance houses while creating regulatory preference for domestically blended oud products with established supply chain documentation. The EU REACH framework indirectly shapes GCC import channels by requiring full chemical safety dossiers from European suppliers, which Gulf distributors must verify before customs clearance. Stakeholders should monitor evolving halal certification requirements for alcohol-free formulations and the potential harmonization of Gulf standards through the GCC Standardization Organization, as these developments will determine which product architectures secure sustained shelf access across the six member states.
Market Dynamics
SFDA and MOHAP ingredient disclosure mandates are compressing formulation lead times for imported fragrance houses while elevating compliance costs, forcing a strategic pivot toward documented oud supply chains and alcohol-free halal architectures across Saudi Arabia and the UAE.
Growth Catalysts
- Regulatory harmonization via GCC Standardization Organization:Converging disclosure standards across member states reduces multi-jurisdiction compliance overhead for regional oud blenders.
- Duty-free corridor concentration in Dubai:Emirates' airport retail infrastructure captures transit passenger volume with experiential sampling environments that sustain premium price realization.
- Attar subscription replenishment models:Digital platforms serving repeat purchasers in Riyadh and Jeddah reduce customer acquisition costs while locking in lifetime value through automated reorder cycles.
Market Restraints
- Aged oud resin supply concentration:Southeast Asian sourcing corridors face harvest variability and export quota restrictions that compress raw material availability for Gulf perfumers.
- EU REACH dossier verification burden:European fragrance houses must submit complete chemical safety documentation before UAE customs clearance, extending import timelines.
- Alcohol-based formulation substitution threat:Rising consumer preference for oil-based attars in conservative Saudi demographics limits eau de parfum category expansion.
Strategic Opportunities
- Halal certification tailwind:MOHAP's evolving standards for alcohol-free formulations create first-mover advantage for domestic blenders with established sharia-compliant production.
- Personalized fragrance concierge services:Bespoke blending studios in Abu Dhabi and Doha capture margin pools that mass-market distribution cannot access.
- Kuwait and Bahrain retail underpenetration:Specialized oud boutiques remain sparse relative to per-capita fragrance expenditure, offering expansion runway for proven Saudi and UAE formats.
Industry Challenges
- Master perfumer talent scarcity:Traditional attar blending expertise concentrates in generational family operations, limiting scalable workforce development for commercial expansion.
- Documentation-intensive compliance timelines:SFDA's ingredient registry requirements demand 12-18 month validation cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Perfume and Fragrance Market |
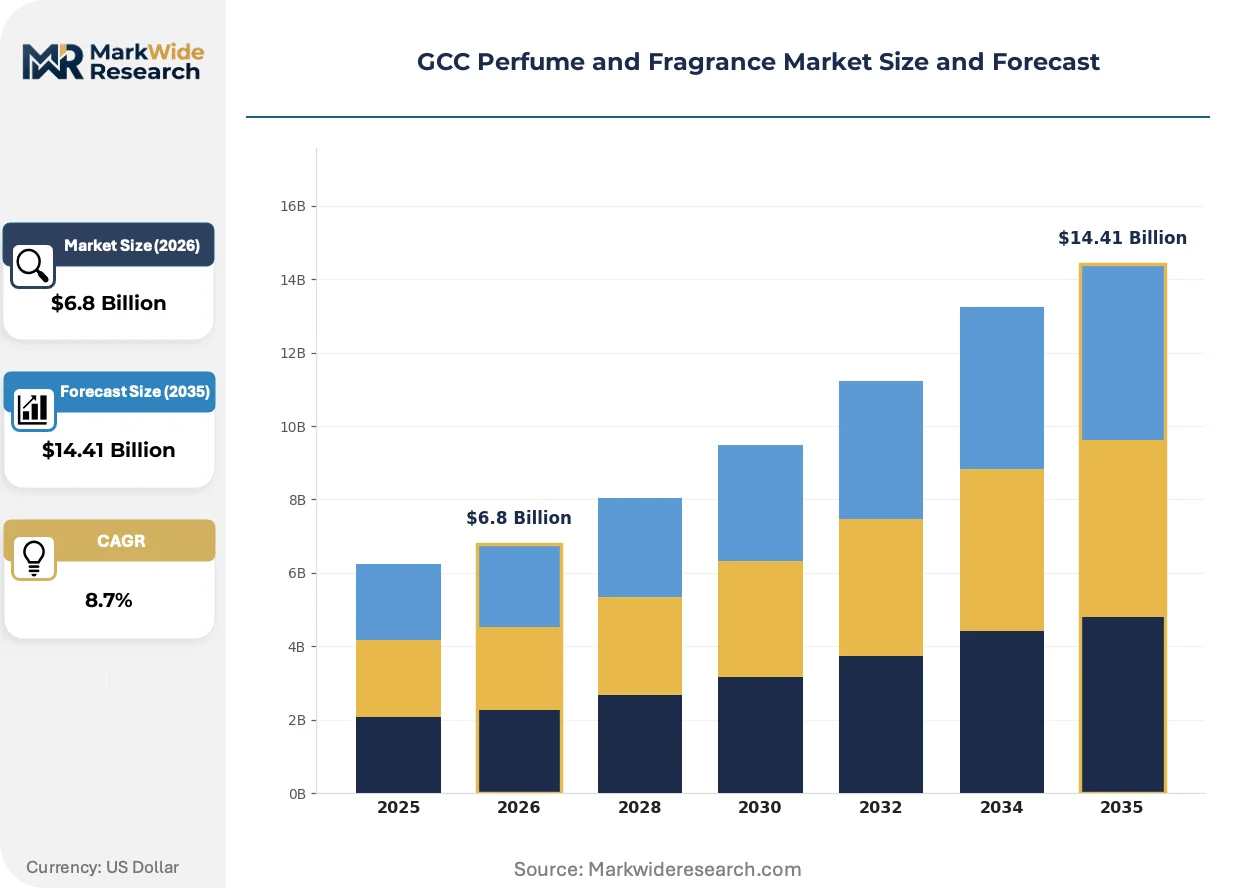
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Oils, Roll-ons, Solid Perfumes Fragrance Type: Floral, Woody, Oriental, Fresh End User: Women, Men, Unisex, Children Distribution Channel: Online Retail, Department Stores, Specialty Stores, Supermarkets |
| Companies Covered | Abdul Samad Al Qurashi, LVMH Moët Hennessy Louis Vuitton, Arabian Oud Company, Gulf Flavours & Fragrances, Yas Perfumes, Ajmal Perfumes, Al-Haramain, Zohoor AL Reef Co., Rasasi, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Perfume and Fragrance Market Trends and Innovations
Digital scent profiling and molecular replication technologies are compressing traditional formulation cycles while regulatory disclosure mandates reshape competitive advantage toward supply chain transparency rather than proprietary secrecy.
Molecular distillation and gas chromatography-mass spectrometry (GC-MS) analysis is digitizing the traditional art of oud authentication. Premium retailers in Dubai and Riyadh deploy portable spectrometers to verify resin age and geographic origin in real-time. This capability collapses information asymmetry between sellers and buyers, shifting margin capture toward documented provenance rather than brand narrative alone.
SFDA's phased ingredient labeling mandates are forcing fragrance houses to disclose allergen compounds and synthetic fixatives previously protected as trade secrets. Domestic Saudi blenders with vertically controlled oud supply chains respond faster than European importers burdened by REACH documentation gaps. The regulatory friction elevates regional players with established halal certification and transparent sourcing.
Experiential retail formats are displacing conventional counter-based distribution in Gulf urban centers. Dedicated fragrance boutiques in Riyadh's upscale mall networks now offer personalized blending consultations and gift-wrapping services that command price premiums. This behavioral shift concentrates volume in specialty channels rather than department store concessions, rewarding operators with trained olfactory consultants and immersive sampling environments.
GCC Perfume and Fragrance Market Segmentation
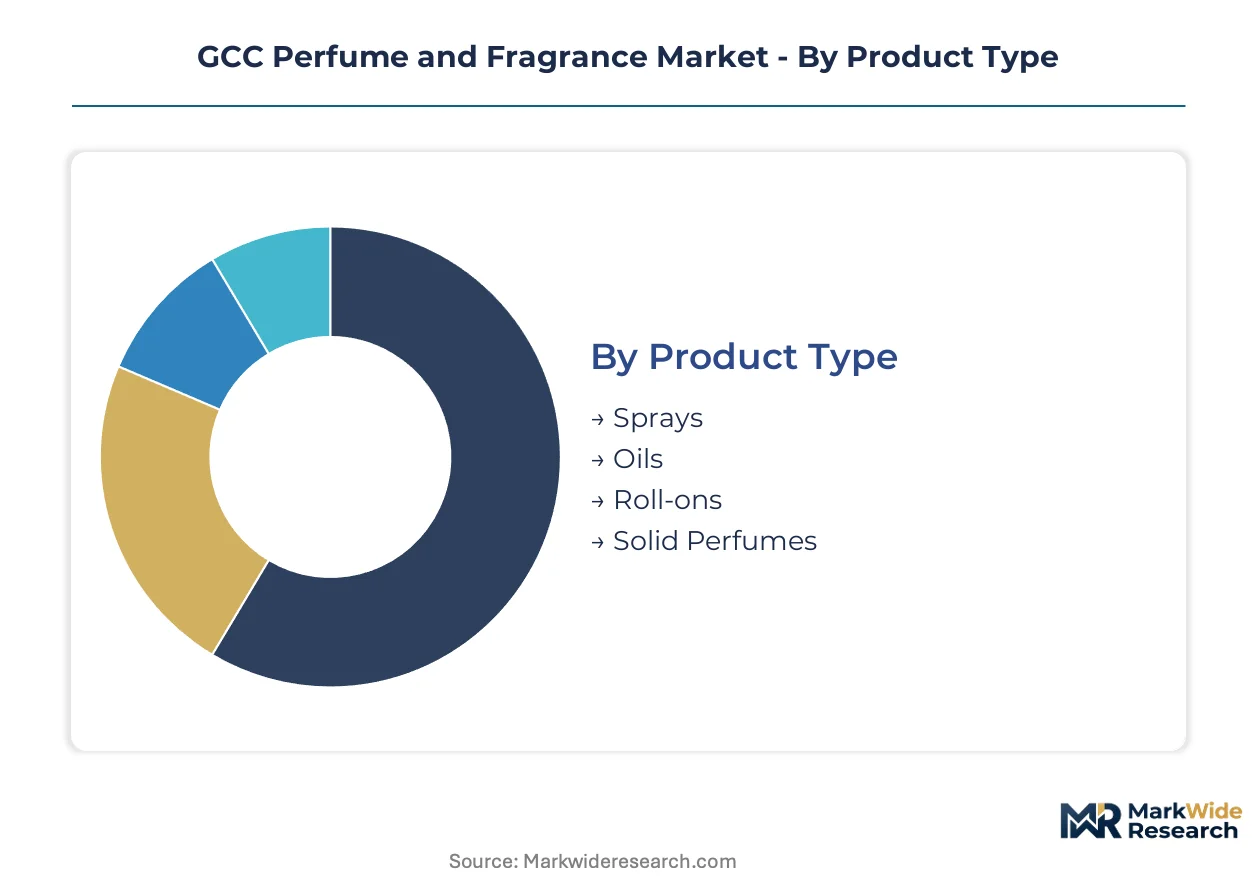
Segmentation in the GCC perfume and fragrance market reveals how formulation formats, scent profiles, and channel strategies align with divergent consumer rituals across Saudi Arabia and the UAE. Understanding these divides exposes where margin pools concentrate and which architectures face substitution pressure from regulatory and cultural shifts.
Product Type:
Mature spray formats dominate mass-market turnover, while emerging oil-based delivery systems capture premium positioning through halal compliance and cultural authenticity.
- Sprays:Alcohol-based aerosol formulations with 15-30% fragrance concentration serve daily wear occasions across UAE malls and Saudi urban centers. Department store counters in Dubai and Riyadh move the highest spray volumes during seasonal gifting windows, though SFDA disclosure mandates now extend import timelines for European houses.
- Oils:Alcohol-free attar concentrates using pure oud or amber bases command price multiples in specialty retail. Saudi consumers in Jeddah and Riyadh drive concentrated demand for documented provenance oils, with domestic blenders leveraging vertical supply chain control to outpace imported competitors on compliance speed.
- Roll-ons:Portable oil applicators target travel and workplace contexts where discreet reapplication matters, finding traction among younger professionals in Doha and Abu Dhabi.
- Solid Perfumes:Wax-based carriers with lower fragrance load appeal to niche segments seeking alcohol-free alternatives with extended wear time, particularly in conservative Saudi demographics.
Sprays handle the majority of throughput; oils are the fastest mover on share.
Fragrance Type:
Cost tier differentiation separates heritage oud compositions from mass-market fresh formulations, with pricing power concentrating in resin-intensive categories.
- Oriental:Complex amber-musk-oud compositions with heavy fixative bases anchor Gulf perfumery tradition. Saudi Arabia and Kuwait sustain the densest consumption of pure oud oils, where generational blending houses command sustained loyalty through authenticated resin sourcing.
- Woody:Sandalwood and cedar-forward profiles bridge traditional and contemporary preferences, gaining traction in UAE cosmopolitan centers where Western and Eastern scent conventions merge.
- Floral:Rose, jasmine, and white flower concentrations target female demographics in Qatar and Bahrain urban markets, competing through gift-oriented packaging and seasonal launches.
- Fresh:Citrus and aquatic notes appeal to younger male consumers and outdoor wear contexts, expanding fastest in Dubai's expatriate-heavy retail corridors where Western fragrance habits predominate.
Oriental formulations command the highest margin tier; fresh profiles are expanding most quickly among demographic segments new to attar traditions.
End User:
Application context varies sharply across gendered and age-based segments, with unisex formulations disrupting traditional category boundaries.
- Women:Floral-oriental hybrids and concentrated oud oils for evening wear dominate purchasing patterns, with Saudi female consumers driving premium attar replenishment through subscription platforms.
- Men:Woody and leather-accented compositions sustain the core of male fragrance wardrobes, with oud-based signatures retaining dominance across all GCC states.
- Unisex:Gender-neutral marketing and shared household purchasing are gaining share in UAE and Qatari markets where younger consumers reject traditional segmentation.
- Children:Alcohol-free, hypoallergenic formulations with mild floral or powder bases serve a niche but growing segment in Kuwait and Bahrain.
Women's formulations generate the largest absolute revenue base; unisex positioning is climbing the fastest on share gains.
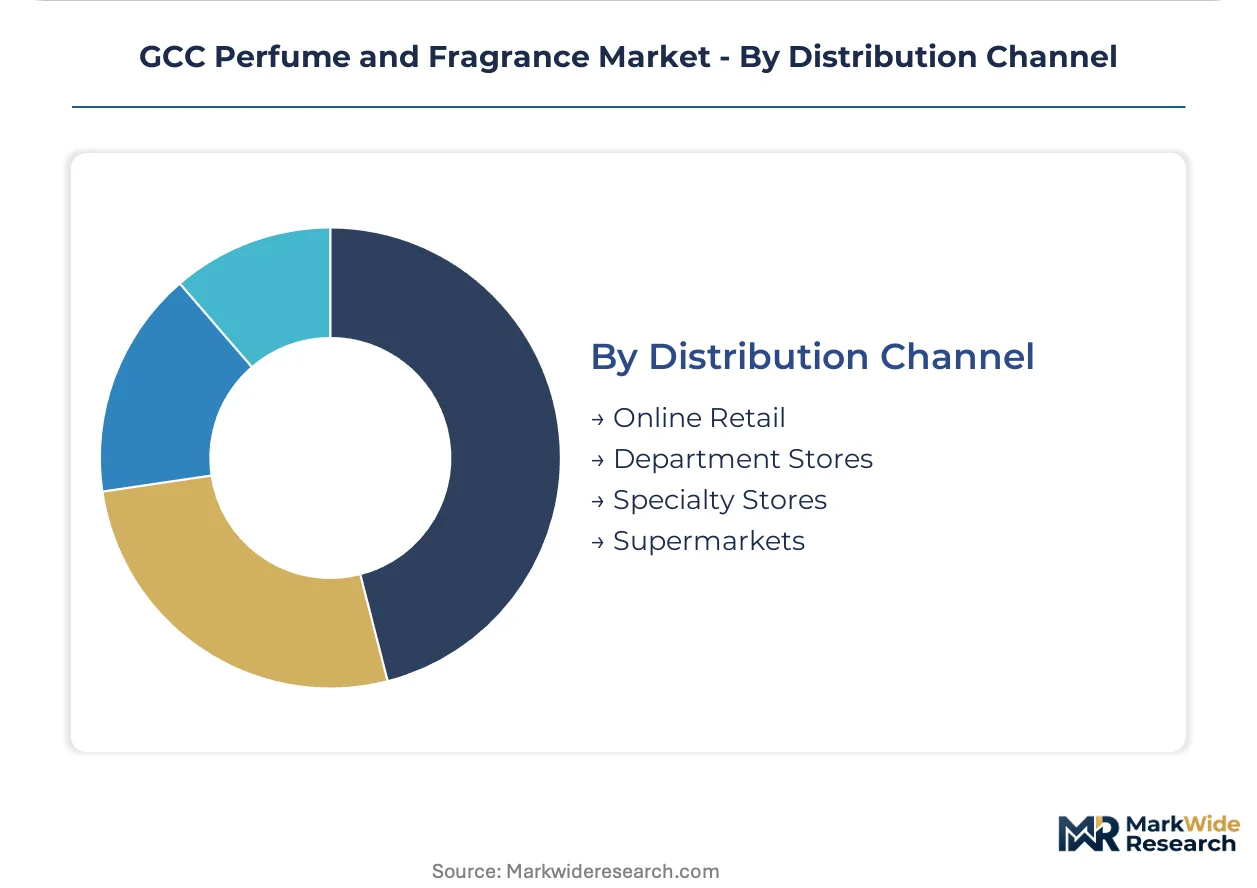
Distribution Channel:
Margin structure inverts between experiential high-touch formats and automated replenishment systems, with geography determining channel viability.
- Specialty Stores:Dedicated fragrance boutiques with trained olfactory consultants and bespoke blending services capture the highest price realization. Dubai's Mall of the Emirates and Riyadh's Kingdom Centre host flagship formats where personalized consultation justifies significant premiums.
- Department Stores:Counter-based distribution with gift-wrapping and sampling infrastructure sustains volume in transitional markets, though foot traffic is compressing in favor of experiential specialty formats.
- Online Retail:Digital platforms with subscription-based attar replenishment reduce customer acquisition costs and lock in lifetime value, accelerating fastest among repeat purchasers in Saudi Arabia's major cities.
- Supermarkets:Mass-market spray formats and value-oriented gift sets serve convenience purchasing, with limited penetration outside UAE and Qatar urban centers.
Specialty stores command the dominant margin pool; online retail is gaining share fastest through automated replenishment mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
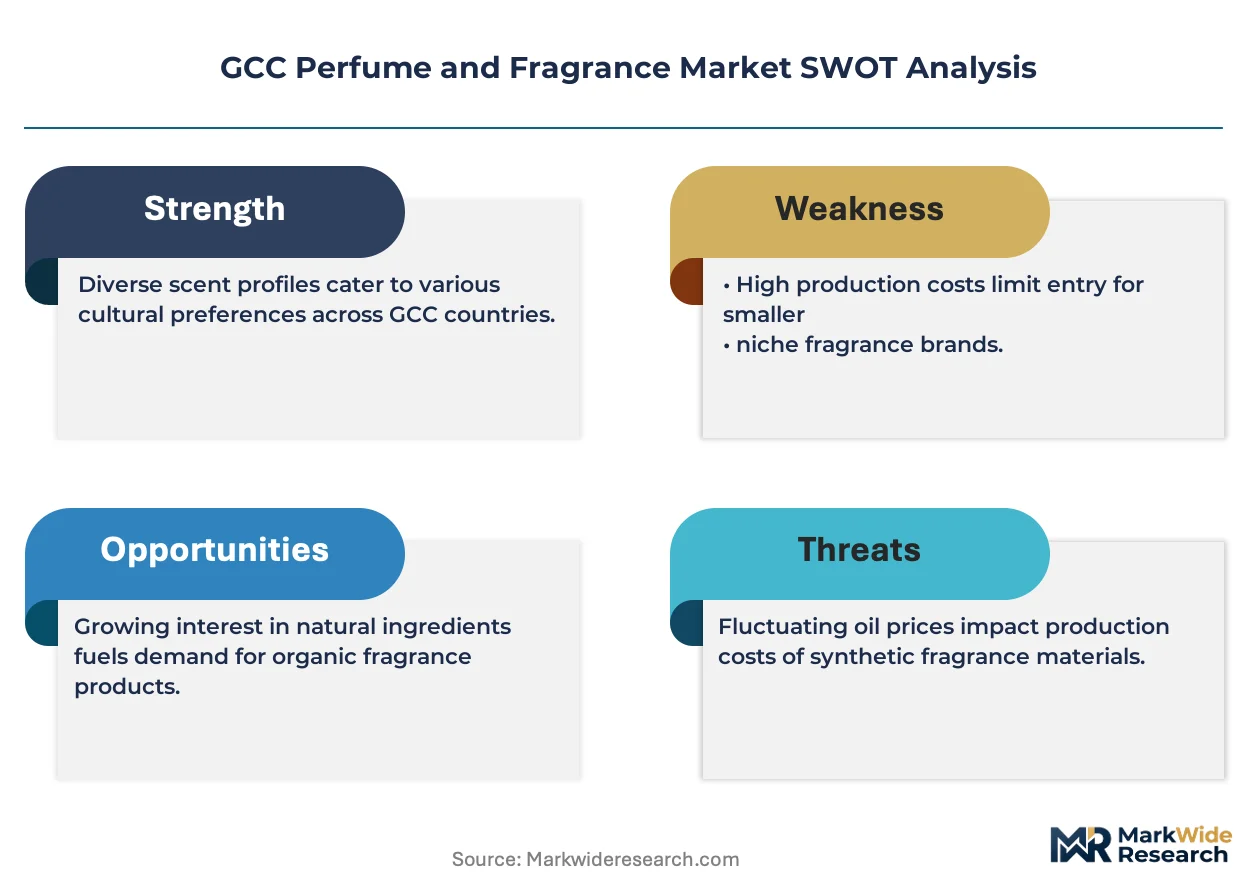
Fragrance buyers in Kuwait and Bahrain demonstrate the highest price elasticity, while Saudi Arabia and UAE consumers sustain premium tier resilience through documented provenance preferences and gifting rituals.
Saudi Arabia
Riyadh and Jeddah drive concentrated attar replenishment through subscription platforms, with domestic blenders capturing margin from documented oud supply chains. SFDA ingredient disclosure mandates compress import timelines for European houses while elevating compliance costs. The Kingdom Centre mall network hosts flagship experiential boutiques where personalized consultation justifies significant premiums over standard retail formats.
United Arab Emirates
Dubai's duty-free corridors capture transit passenger volume with immersive sampling environments that sustain price realization unattainable in conventional retail. MOHAP standards for alcohol-free formulations create regulatory preference for halal-certified domestic production. Mall of the Emirates and Abu Dhabi's Yas Mall anchor specialized fragrance boutiques with trained olfactory consultants displacing traditional department store concessions.
Kuwait
Per-capita fragrance expenditure exceeds regional averages yet specialized oud boutiques remain underpenetrated relative to demand density. The country's national consumer protection regulator enforces labeling standards that parallel GCC harmonization efforts. Salmiya and Kuwait City retail corridors present expansion runway for proven Saudi and UAE boutique formats seeking new addressable markets.
Qatar
Doha's younger demographics reject traditional gender segmentation, accelerating unisex formulation adoption faster than neighboring markets. The national standardization body aligns with GCC Standardization Organization disclosure frameworks to reduce multi-jurisdiction compliance overhead. Pearl-Qatar and West Bay districts concentrate experiential retail investment where bespoke blending studios capture margin pools inaccessible to mass distribution.
Bahrain
Conservative demographics sustain demand for alcohol-free solid perfumes and oil-based delivery systems with extended wear characteristics. Regulatory frameworks mirror UAE and Saudi disclosure mandates through GCC coordination mechanisms. Manama's Seef Mall and City Centre host limited specialized fragrance retail relative to population density, indicating white-space opportunity for documented provenance operators.
GCC Perfume and Fragrance Market Competitive Landscape
Heritage oud houses and global luxury conglomerates split the market along authenticity-versus-scale lines. Concentration remains moderate with generational family operations commanding premium positioning through vertical resin control while European houses compete on brand recognition and distribution breadth. Three archetypes dominate: vertically integrated Saudi blenders with captive agarwood sourcing, UAE-based specialty retailers with experiential service models, and global luxury houses with airport retail dominance. Competitive moves center on halal certification acceleration and boutique network expansion into underpenetrated secondary cities.
Within the heritage blender tier, Abdul Samad Al Qurashi and Arabian Oud Company exemplify vertically controlled supply chain architectures that compress compliance timelines under SFDA and MOHAP mandates. Among global luxury houses, LVMH Moët Hennessy Louis Vuitton anchors Western fragrance distribution through dedicated boutique networks in Dubai and Abu Dhabi. These three named entities represent the structural poles around which mid-cap specialists and regional distributors position for share.
| Leading Market Players |
|---|
| Abdul Samad Al Qurashi |
| LVMH Moët Hennessy Louis Vuitton |
| Arabian Oud Company |
| Gulf Flavours & Fragrances |
| Yas Perfumes |
| Ajmal Perfumes |
| Al-Haramain |
| Zohoor AL Reef Co. |
| Rasasi |
| Others |
Pricing and Supply Chain Analysis
Southeast Asian agarwood harvesting clusters in Thailand and Cambodia constrain aged resin availability, concentrating upstream pricing power among Gulf blenders with multi-year sourcing contracts and documented provenance chains.
Pricing Analysis
After-sales attar replenishment subscriptions drive lifetime value capture across Saudi and UAE digital platforms. Three-tier pricing structure across premium, standard, and economy levels separates documented vintage oud from blended compositions and mass-market sprays. Cost compression in European import tiers intensifies because SFDA disclosure mandates extend validation timelines. Price-sensitive mass-market spray buyers in Dubai's expatriate corridors contrast with least-sensitive heritage attar collectors in Riyadh seeking authenticated resin provenance.
Supply Chain Analysis
Export quota restrictions on wild-harvested agarwood under CITES Appendix II controls limit raw material flows into Gulf processing facilities. Supply concentrates in Thailand, Cambodia, and Vietnam for aged resin, while synthetic fixative production centers on China and India. Raw material dependencies include agarwood chips, sandalwood oil, and ambergris substitutes. Single-source vulnerability runs through generational family harvesters in Southeast Asian forests. Distribution runs through Dubai's Jebel Ali free zone for re-export across GCC member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment around halal certification and documented oud sourcing creates durable barriers against European luxury houses lacking compliant supply chains.
For Market Incumbents: Pre-empt European fragrance house recovery by accelerating boutique network expansion into Kuwait City and Manama before import compliance timelines normalize. Deepen backward integration into captive agarwood aging facilities in Southeast Asia to secure resin allocation against harvest quota tightening. Channel control through dedicated mall footprints in Riyadh's Kingdom Centre and Dubai's Mall of the Emirates anchors customer lock-in against digital-native entrants. For New Entrants and Emerging Players: Pursue white-space opportunity in Bahrain's solid perfume segment where conservative demographics reject alcohol-based formulations and incumbent presence remains thin. Target Doha's unisex fragrance studios where younger Qatari consumers reject traditional gender segmentation faster than neighboring markets. A direct-to-consumer subscription model with automated attar replenishment cycles reduces customer acquisition costs against established retail networks. For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored play because halal compliance and documented oud provenance create irreplicable intangible assets that compound across regulatory tightening windows. Acquisition targets should profile domestic Saudi blenders with vertically controlled Southeast Asian sourcing and established SFDA registration histories. The signal to watch is GCC Standardization Organization harmonization progress, which would elevate multi-jurisdiction compliance costs for fragmented regional distributors and accelerate consolidation toward integrated operators.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | MOHAP's evolving alcohol-free standards in UAE reward first-mover domestic blenders with compliant production architectures. |
| Experiential Boutique Expansion | Flagship formats in Riyadh's Kingdom Centre and Dubai's Mall of the Emirates displace department store concessions through trained olfactory consultants. |
| Documented Provenance Investment | Portable GC-MS spectrometers in premium Dubai and Riyadh retailers collapse information asymmetry and shift margin toward authenticated sourcing. |
| Subscription Platform Development | Automated attar replenishment cycles in Saudi Arabia's major cities reduce customer acquisition costs and lock in lifetime value. |
| Secondary City Penetration | Kuwait's Salmiya corridor and Bahrain's Seef Mall present expansion runway where specialized oud boutiques remain underpenetrated relative to demand density. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fragrance house master perfumers, GCC retail category managers, regulatory affairs specialists at SFDA and MOHAP, and duty-free procurement directors; alongside secondary validation through customs import records, GCC Standardization Organization disclosure frameworks, and airport retail operator filings. Bottom-up triangulation across product-format volumes and top-down reconciliation against aggregate market value estimates anchored forecast reliability.
Forecast inputs considered formulation format shifts, fragrance type preference evolution, channel migration patterns, and regulatory compliance cost trajectories across the projection horizon. Segmentation modeling captured product type, fragrance profile, end-user demographics, and distribution channel dynamics alongside halal certification status as an industry-specific dimension. CAGRs derived from historical volume progression adjusted for disclosed regulatory phase-in schedules and documented supply constraints.
Sensitivities concentrate around harvest quota volatility in Southeast Asian sourcing corridors and GCC regulatory harmonization pace. Forecasts reflect assumptions on sustained premium tier resilience in Saudi Arabia and UAE gifting rituals. Material shifts in CITES agarwood trade restrictions or accelerated alcohol-free formulation mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Scented Oil Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Evaporative Diffusers Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Smart Fragrance Box Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
Organic Perfumes Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
Fragrance Product Market
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Floral Water Spray Market