
 Guardrail Protection System Market | 2026-2036
Guardrail Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Guardrail Protection System Market Insights
The gap between passive safety design and active monitoring technology is narrowing as sensor-integrated guardrail systems enter field trials. BrandSafway leverages its scaffolding heritage to extend into temporary roadside protection for construction zones. Honeywell anchors its position through advanced materials R&D aimed at impact-absorbing composites. Altrad Group competes across European infrastructure maintenance contracts with modular barrier platforms.
Guardrail protection systems are roadside safety barriers engineered to contain or redirect errant vehicles through controlled deformation of metal, plastic, concrete, or wire rope elements, typically tested to TL-3 or TL-4 impact severity levels per MASH criteria. Their primary purpose is to reduce fatalities and serious injuries by managing crash energy dissipation along highways, bridges, and work zones. Metal guardrails sustain the largest installed base across North American interstate corridors, though wire rope barriers gain share in medians where deflection space is constrained. Highway application dominates procurement volumes, while construction site deployment shows the fastest expansion tied to temporary work-zone mandates.
The Federal Highway Administration enforces MASH compliance timelines that shape manufacturer product development cycles and state DOT replacement schedules. NHTSA coordinates vehicle-to-infrastructure safety research that increasingly references barrier interaction kinematics. ASTM International maintains material specification standards that govern steel grade acceptance and corrosion protection protocols. Stakeholders must track how evolving crash-test criteria and infrastructure funding authorization cycles interact to reshape competitive qualification requirements.
Market Dynamics
The Federal Highway Administration's MASH compliance deadlines are compressing state DOT replacement cycles and forcing manufacturers to requalify entire product lines simultaneously.
Growth Catalysts
- FHWA MASH 2016 Implementation:State transportation departments face mandated crash-test upgrades for roadside barriers, creating synchronized replacement demand across interstate corridors.
- Steel Recycling Infrastructure:Domestic mills now supply higher-grade galvanized W-beam sections with improved corrosion resistance, extending service life in coastal and de-icing salt environments.
- Work Zone Safety Mandates:OSHA temporary traffic control requirements for highway construction projects are expanding deployment of portable barrier systems beyond permanent installations.
Market Restraints
- Zinc Price Volatility:Hot-dip galvanizing costs fluctuate with London Metal Exchange zinc futures, squeezing margin stability for steel barrier fabricators.
- Regional Fabrication Concentration:Midwestern US steel processors dominate W-beam roll-forming capacity, creating geographic supply vulnerability for coastal infrastructure projects.
- Concrete Barrier Substitution:Precast Jersey barriers compete for median applications where deflection space permits, capturing share from flexible metal systems.
Strategic Opportunities
- Sensor-Integrated Barriers:Accelerometer and strain-gauge embedded guardrails enable real-time impact detection and predictive maintenance scheduling for state DOT asset managers.
- Rural Bridge Retrofit Programs:Federal bridge formula funding targets secondary road structures with obsolete railings, opening procurement channels outside interstate highways.
- Composite Material Qualification:Glass-reinforced polymer barriers offer corrosion immunity and reduced mass for seismic zones, pending MASH test validation.
Industry Challenges
- MASH Test Facility Bottlenecks:Only three US proving grounds operate full-scale vehicle-to-barrier crash corridors, creating 18-month queues for new product certification.
- Welding Technician Scarcity:Certified structural welders for terminal assembly operations command premium wages in tight labor markets, constraining production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guardrail Protection System Market |
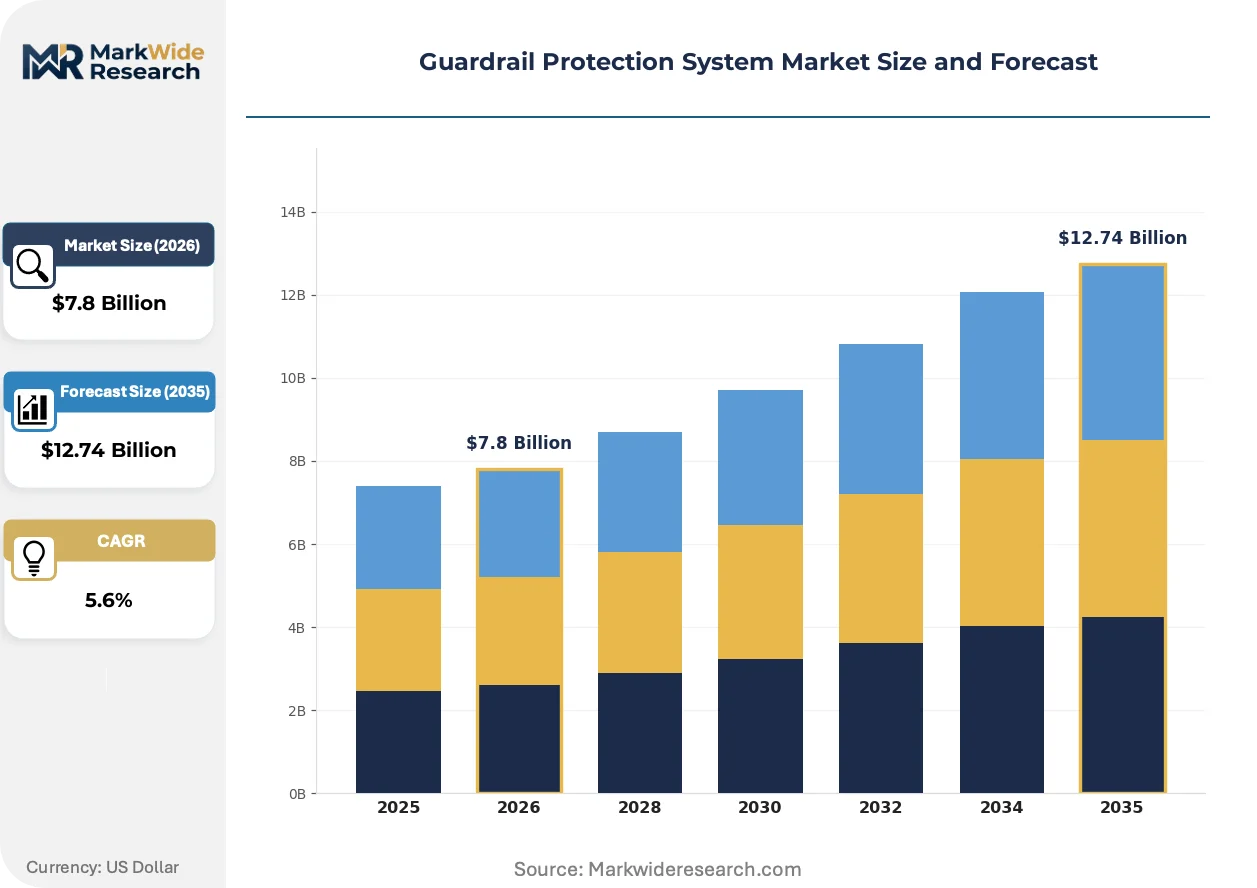
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.74 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Guardrails, Plastic Guardrails, Concrete Barriers, Wire Rope Barriers Application: Highway, Bridge, Parking Lot, Construction Site Installation Type: Permanent, Removable, Temporary, Modular End User: Government Agencies, Construction Companies, Infrastructure Developers, Private Sector |
| Companies Covered | BrandSafway, Honeywell, Altrad Group, PERI, Doka, KGUARD International, ULMA, Billington, TLC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guardrail Protection System Market Trends and Innovations
Digital twin modeling and connected infrastructure protocols are converging with physical barrier engineering, transforming guardrails from passive steel installations into data-generating roadside assets.
Embedded fiber-optic sensing technology is virtualizing traditional inspection workflows. State DOT maintenance crews now receive automated structural integrity alerts rather than conducting manual visual surveys. California and Texas transportation departments pilot these systems on high-collision corridors, compressing response times from weeks to hours.
NHTSA coordinates with the FHWA on vehicle-to-barrier interaction research that directly shapes MASH update priorities. The agency's crash reconstruction database identifies specific impact kinematics where current barrier designs underperform, channeling manufacturer R&D toward geometric profile modifications. European regulators through the EN 1317 standardization committee observe these US developments for potential harmonization.
Asset management software platforms are consolidating procurement decisions for state infrastructure agencies. Michigan and Ohio DOTs now bundle guardrail replacement contracts with pavement resurfacing schedules, forcing manufacturers to align production cadences with broader highway maintenance windows. This synchronization favors suppliers with flexible fabrication capacity and multi-state distribution networks.
Guardrail Protection System Market Segmentation
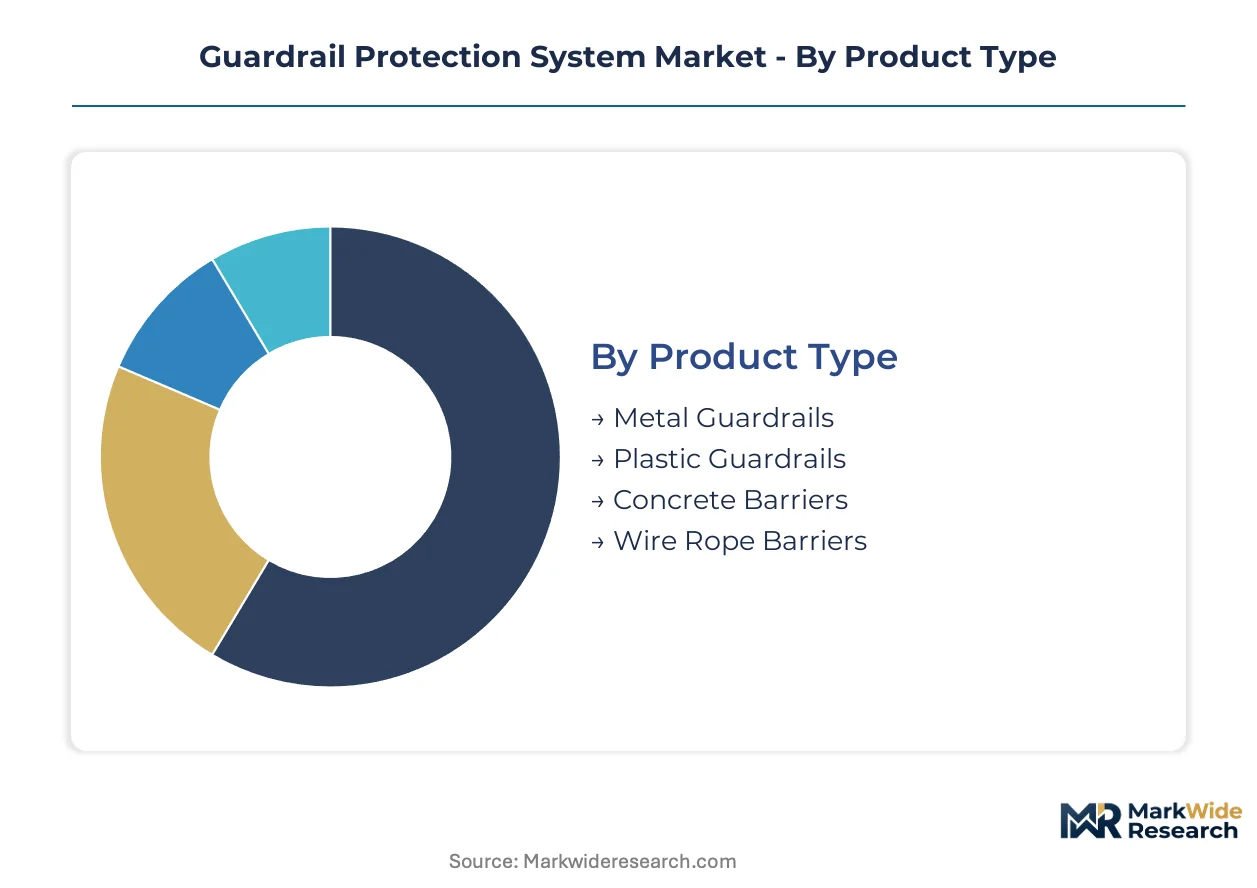
Guardrail procurement cycles vary dramatically across product categories, with permanent highway installations requiring decades-long replacement windows while temporary construction systems turn over within months. Understanding these velocity differentials helps manufacturers align production capacity with predictable revenue streams versus project-based spikes.
Product Type:
Replacement cycles stretch from 30-50 years for permanent steel barriers down to 5-10 years for wire rope systems in high-deflection medians, creating distinct inventory and service revenue profiles.
- Metal Guardrails:W-beam and thrie-beam steel sections dominate interstate corridors with hot-dip galvanized coatings resisting corrosion in salt-heavy environments. State DOTs in Michigan and Ohio concentrate replacement demand where aging TL-2 systems must upgrade to MASH-compliant TL-3 configurations.
- Wire Rope Barriers:Tensioned cable systems mount on weak posts that collapse on impact, capturing narrow medians where rigid barriers lack deflection space. Texas and California transportation departments favor these for high-speed divided highways with constrained right-of-way.
- Concrete Barriers:Precast Jersey profiles serve permanent median and work-zone applications where vehicle penetration cannot occur.
- Plastic Guardrails:Polymer composites target low-speed parking facilities and pedestrian zones requiring aesthetic flexibility.
Metal guardrails dominate installed base. Wire rope barriers are where expansion concentrates.
Application:
Budget authority flows differently across application types, with federal-aid highway programs funding 80-90% of interstate barrier costs while bridge and parking projects rely on mixed funding streams.
- Highway:Interstate and primary arterial corridors consume the largest procurement volumes under Federal Highway Administration oversight. MASH compliance deadlines synchronize replacement waves across multiple state DOTs simultaneously.
- Construction Site:OSHA temporary traffic control mandates drive portable barrier deployment for highway work zones, with rental models gaining traction over purchase for project-specific durations.
- Bridge:Bridge formula funding targets obsolete railings on secondary road structures, opening procurement channels outside major interstate corridors.
- Parking Lot:Municipal and commercial developers specify lower-speed protection for pedestrian-vehicle separation in structured and surface facilities.
Highway applications anchor manufacturer revenue stability. Construction site deployment is climbing the fastest as infrastructure spending accelerates work-zone protection mandates.
Installation Type:
Capital intensity separates permanent foundations requiring soil bearing analysis from surface-mounted temporary systems deployable within hours.
- Permanent:Driven-post steel systems embed 6-8 feet below grade with engineered soil-structure interaction for high-energy impacts. These installations generate decades of minimal maintenance revenue after initial capital outlay.
- Temporary:Water-filled or surface-anchored barriers relocate between project phases, with rental fleet operators capturing recurring revenue from construction contractors.
- Removable:Bolted-base systems allow seasonal or event-based reconfiguration for reversible lanes and special access routes.
- Modular:Interlocking components enable rapid assembly without specialized equipment, serving emergency response and military mobilization scenarios.
Permanent installations lock in long-term market position. Temporary systems are gaining share fastest as project-based procurement expands.
End User:
Contracting sophistication varies sharply, with government agencies running multi-year blanket purchase agreements while private developers negotiate project-specific terms.
- Government Agencies:State departments of transportation administer federal-aid contracts through competitive bidding processes, with MASH qualification requirements filtering supplier pools. California DOT and Texas DOT set specification trends adopted by smaller agencies.
- Construction Companies:General contractors and subcontractors procure temporary barriers under OSHA work-zone mandates, prioritizing rental availability and rapid deployment over long-term durability.
- Infrastructure Developers:Public-private partnership concessionaires bundle barrier systems into design-build-finance-operate contracts spanning 30-50 year terms.
- Private Sector:Commercial property owners and industrial facility operators specify parking lot and perimeter protection with lower crash-test requirements than public roadways.
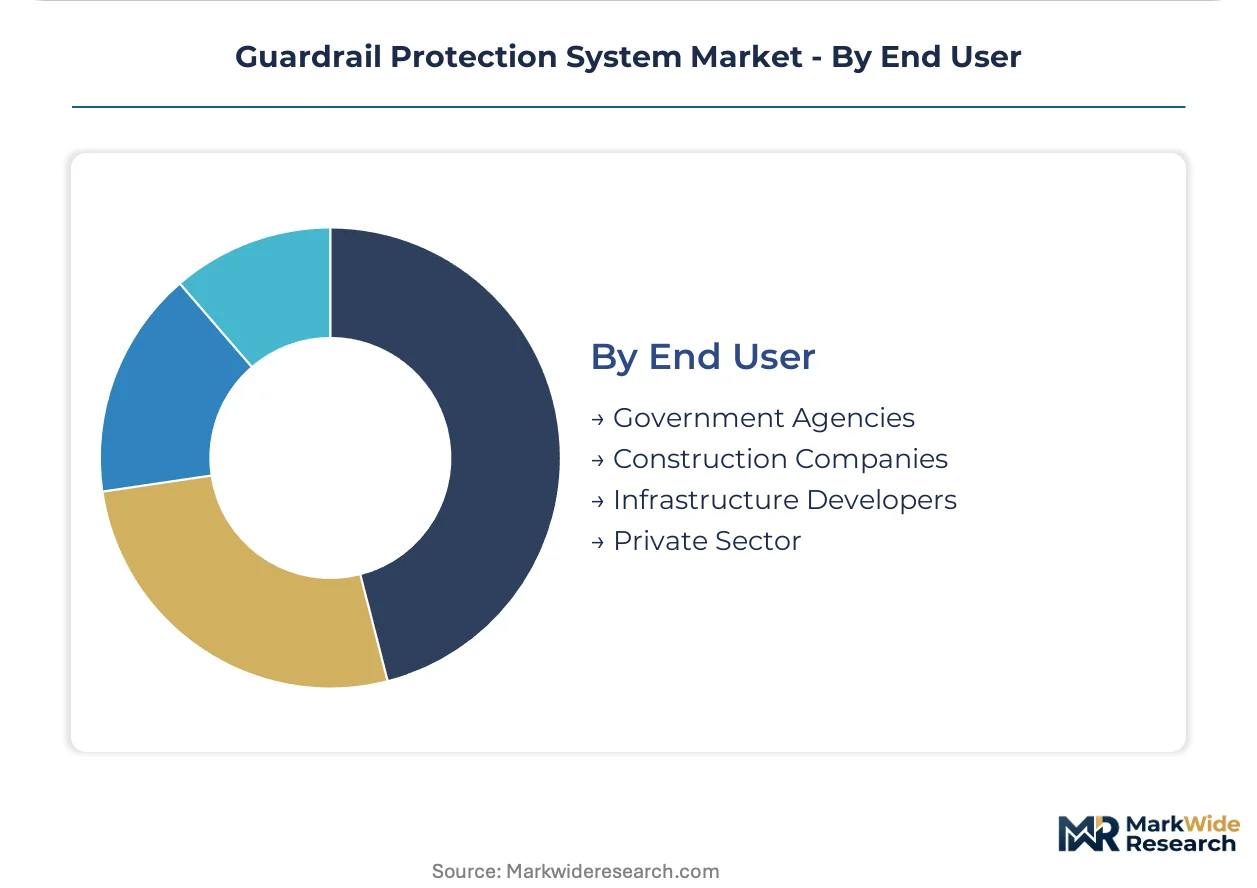
Government agencies dominate procurement volume. Construction companies are where supplier margins face greatest pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State transportation departments in the United States concentrate the largest procurement volumes for guardrail protection systems, with federal-aid highway programs funneling infrastructure dollars through DOT purchasing channels. Construction contractors in coastal and inland regions generate secondary demand through temporary work-zone mandates.
United States
The Federal Highway Administration's MASH 2016 compliance deadlines are compressing replacement cycles across state DOTs simultaneously. California DOT and Texas DOT set specification trends that smaller agencies adopt, with both states piloting sensor-embedded barriers on high-collision corridors. Midwestern steel processors dominate W-beam roll-forming capacity, creating geographic supply concentration for coastal projects.
Canada
Transport Canada coordinates with provincial ministries of transportation on barrier standards harmonization with US MASH protocols. Ontario's Ministry of Transportation administers the largest replacement programs targeting aging TL-2 systems on the 400-series highways. Quebec fabricators supply galvanized steel sections to Atlantic provinces where coastal corrosion accelerates service-life concerns.
Germany
The Federal Highway Research Institute (BASt) maintains EN 1317 certification protocols that govern roadside barrier acceptance across federal trunk roads. KBA vehicle safety standards intersect with infrastructure protection requirements in ways that shape manufacturer product development priorities. Bavarian steel fabricators cluster around Munich and Nuremberg, supplying guardrail systems for Autobahn expansion projects in southern states.
China
MIIT infrastructure investment targets expressway expansion in western provinces where terrain challenges demand specialized barrier geometries. GB standards for highway safety facilities are converging with international crash-test protocols, opening procurement to qualified foreign suppliers. Yangtze River Delta fabricators concentrate production of wire rope barriers for median applications on high-speed divided highways.
Australia
Austroads national specifications govern state-level procurement for barrier systems on the National Highway network. Transport for New South Wales and VicRoads administer the largest replacement programs targeting aging installations on Pacific Highway and Hume Highway corridors. Queensland fabricators supply modular barrier systems for remote road projects where rapid deployment outweighs permanent foundation requirements.
Guardrail Protection System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct procurement pathways. State DOT blanket purchase agreements favor suppliers with multi-state distribution networks and MASH qualification breadth. Three archetypes define competitive positioning: integrated infrastructure conglomerates with scaffolding heritage extending into temporary protection, diversified industrial technology groups anchoring through materials R&D, and specialized barrier fabricators focused on regional DOT relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves, with rental fleet operators acquiring regional players to consolidate temporary barrier markets.
Within the integrated infrastructure tier, BrandSafway occupies a position exemplifying scaffolding-to-roadside extension strategies, while Altrad Group anchors European maintenance contract competition through modular platform specialization. Honeywell sits within the diversified technology archetype, representing advanced materials research positioning. These three companies illustrate how heritage capabilities shape guardrail market entry vectors without determining specific product outcomes.
| Leading Market Players |
|---|
| BrandSafway |
| Honeywell |
| Altrad Group |
| PERI |
| Doka |
| KGUARD International |
| ULMA |
| Billington |
| TLC Group |
| Others |
Pricing and Supply Chain Analysis
Midwestern US steel processors in Ohio and Indiana concentrate W-beam roll-forming capacity, granting these fabricators pricing leverage over coastal state DOTs facing freight-adjusted delivered costs. Hot-dip galvanizing expenses track London Metal Exchange zinc futures, transmitting commodity volatility directly into state procurement budgets.
Pricing Analysis
Cost-plus contracts with London Metal Exchange zinc indexation dominate state DOT procurement, insulating fabricators from raw material swings while exposing buyers to pass-through volatility. Price differentiation hinges on MASH certification tier and geographic delivery distance from Midwestern mills. Cost compression in standard W-beam segments is intensifying because concrete barrier substitutes capture median applications. Municipal parking lot developers exhibit highest price sensitivity; infrastructure concessionaires with 30-year O&M contracts show lowest.
Supply Chain Analysis
Contract manufacturing concentrates among Midwestern US roll-forming specialists, Chinese wire rope assembly plants, and German precision terminal fabricators. Galvanized steel coil, zinc ingot, and engineered soil anchors constitute critical input dependencies. Single-source vulnerability runs through Midwestern W-beam capacity for Atlantic and Pacific coast projects. Distribution runs through state DOT blanket purchase agreements, construction contractor rental fleets, and infrastructure concessionaire design-build contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
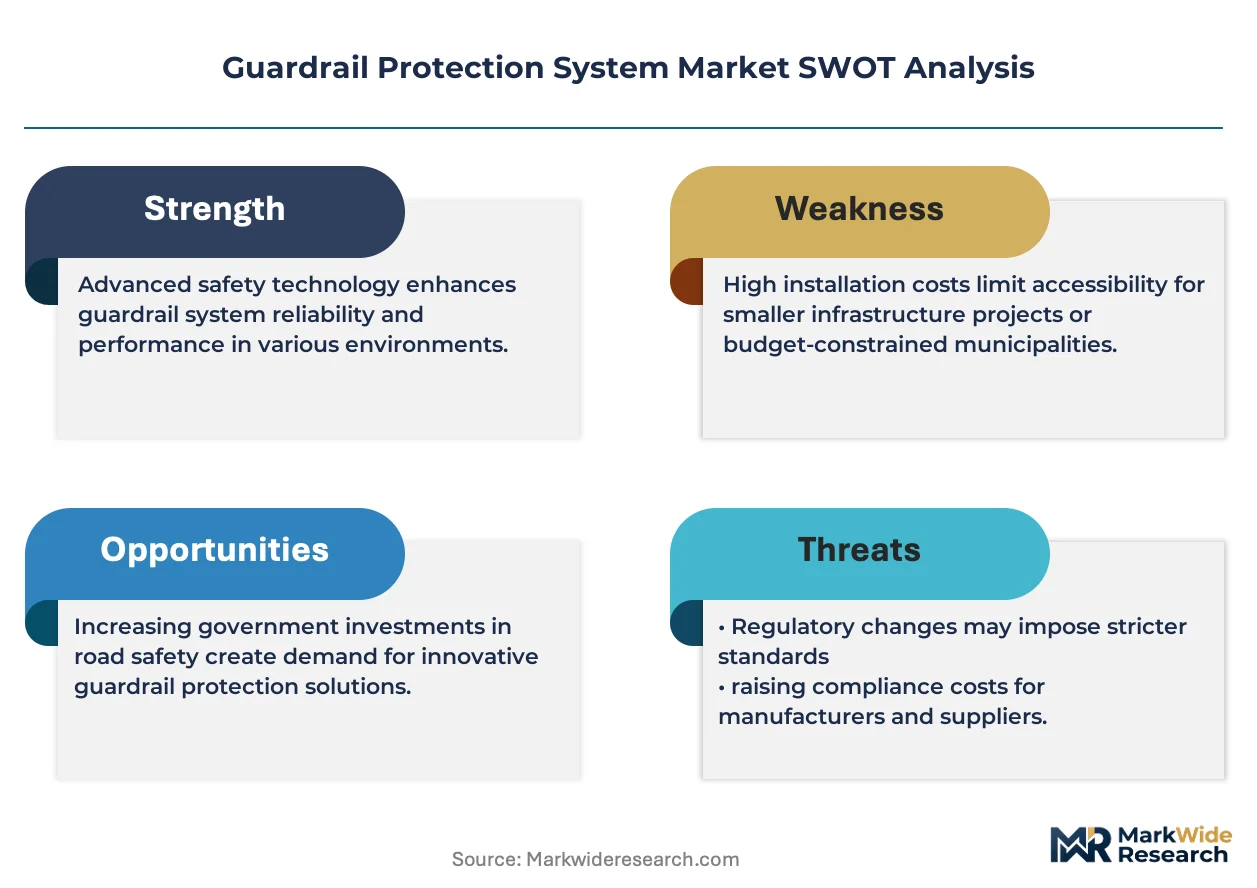
Fragmentation opportunity emerges as MASH compliance deadlines fragment procurement across fifty state DOTs with divergent replacement schedules, creating niche entry points for specialized fabricators.
For Market Incumbents: Insulate market position by securing captive zinc supply through backward integration into galvanizing operations, and accelerate MASH 2016 requalification timelines to lock out competitors facing 18-month test facility queues. Threat substitution from precast concrete barriers in median applications demands defensive R&D into hybrid steel-concrete systems. For New Entrants and Emerging Players: Atlantic Canada and Queensland Australia present geographic underpenetration where provincial transport ministries lack established supplier relationships. Target rural bridge retrofit programs outside interstate corridors where incumbent presence thins. Go-to-market angle: bundle sensor-embedded barrier pilots with predictive maintenance software subscriptions. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified scaffolding conglomerates seeking to monetize roadside protection divisions non-core to access equipment heritage. Long-term viability centers on MASH qualification breadth and multi-state DOT contract tenure. Signal to watch: FHWA announcement of MASH 2026 update timeline compressing next replacement wave.| Strategic Initiative | Industry Significance |
|---|---|
| MASH Certification Investment | Test facility queue positions determine market access timing for state DOT contracts. |
| Sensor Integration Partnership | California DOT and Texas DOT pilot programs validate embedded fiber-optic technology. |
| Rental Fleet Consolidation | Construction work-zone mandates expand addressable market for temporary barrier operators. |
| Galvanizing Capacity Expansion | Coastal mill proximity reduces freight-adjusted pricing disadvantage versus Midwestern suppliers. |
| Rural Bridge Retrofit Targeting | Federal bridge formula funding opens procurement channels outside interstate highway networks. |
Research Methodology
The analysis maps metal guardrail, wire rope barrier, concrete barrier, and plastic guardrail sub-sectors, each validated through state DOT procurement officers, barrier system engineers, construction contractor fleet managers, and galvanizing plant operations directors. Primary interview intelligence triangulates against FHWA MASH compliance databases, state transportation department bid tabulations, ASTM material specification records, and American Iron and Steel Institute production statistics. Bottom-up segment sizing reconciles with top-down federal infrastructure spending allocation models.
Assumptions hold FHWA MASH implementation timelines and federal-aid highway funding authorization levels fixed across the projection horizon, while zinc price volatility and steel tariff regimes vary within historical bands. Segmentation dimensions include product type, application category, installation permanence, and end-user contracting sophistication. CAGRs derive from replacement cycle velocity differentials and infrastructure spending elasticity models, with MASH compliance deadline clustering and work-zone safety mandate expansion as primary demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese wire rope exporters or accelerated MASH 2026 timeline announcements would shift outcomes. Quarterly review of state DOT bid award patterns and zinc futures curve inversion indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Middle East Commercial Security Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market