
 Middle East Commercial Security Market | 2026-2036
Middle East Commercial Security Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Commercial Security Market Foresight
Market Context
The Middle East commercial security landscape is restructuring around a sharp split between premium AI-driven analytics platforms and commodity hardware installations. Hikvision Digital Technology dominates volume supply across the Gulf Cooperation Council, leveraging its manufacturing scale to control pricing in standardized video surveillance. Axis Communications anchors the premium tier, specializing in edge-computing cameras with embedded machine learning for corporate offices and financial institutions. Johnson Controls International competes through integrated building management systems that merge physical security with HVAC and fire safety infrastructure.
Technical and Segment Dynamics
Middle East commercial security encompasses electronic systems designed to protect non-residential assets through detection, deterrence, and response functions, typically incorporating IP-based cameras with minimum 4K resolution, biometric readers with liveness detection, and centralized command platforms. Video surveillance leads product type demand due to government mandates for public space monitoring in Saudi Arabia and the UAE, while access control systems command higher margins through integration with national ID databases. Cloud-based technology represents the fastest-expanding segment as regional data sovereignty laws evolve, though on-premise deployments still dominate financial institutions requiring air-gapped networks. AI analytics is displacing rule-based monitoring in transportation hubs, where real-time crowd behavior analysis reduces staffing costs.
Regulatory Environment
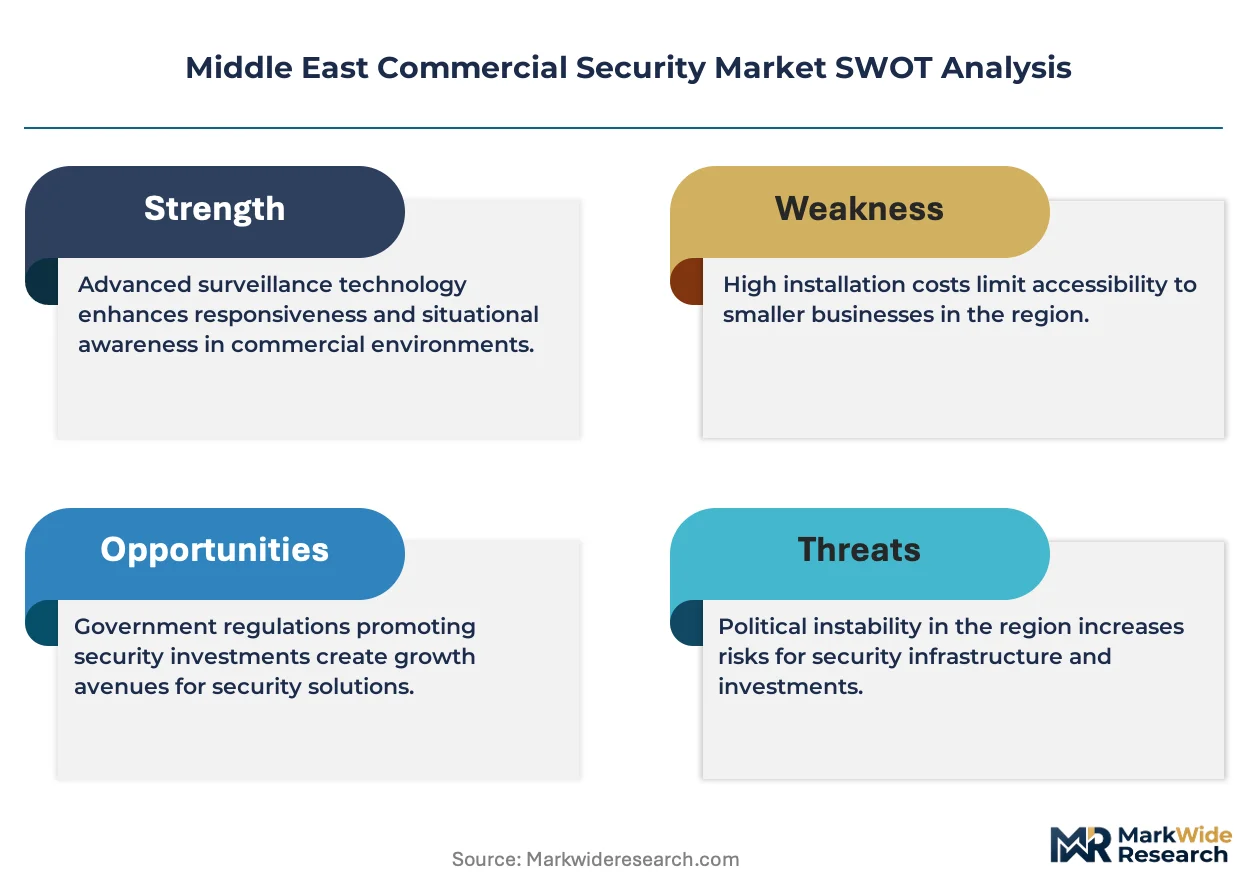
SFDA cybersecurity frameworks and UAE NESA compliance standards are tightening product certification requirements, forcing vendors to localize data storage and submit to government security audits. Saudi Arabia's Critical Systems Protection Regulation and Dubai's Electronic Security Center mandates shape procurement specifications for intrusion detection in energy and aviation facilities. Stakeholders must monitor evolving data localization laws across Kuwait, Qatar, and Oman, where divergent approaches to cloud governance will fragment deployment architectures and elevate compliance costs for multi-country operators.
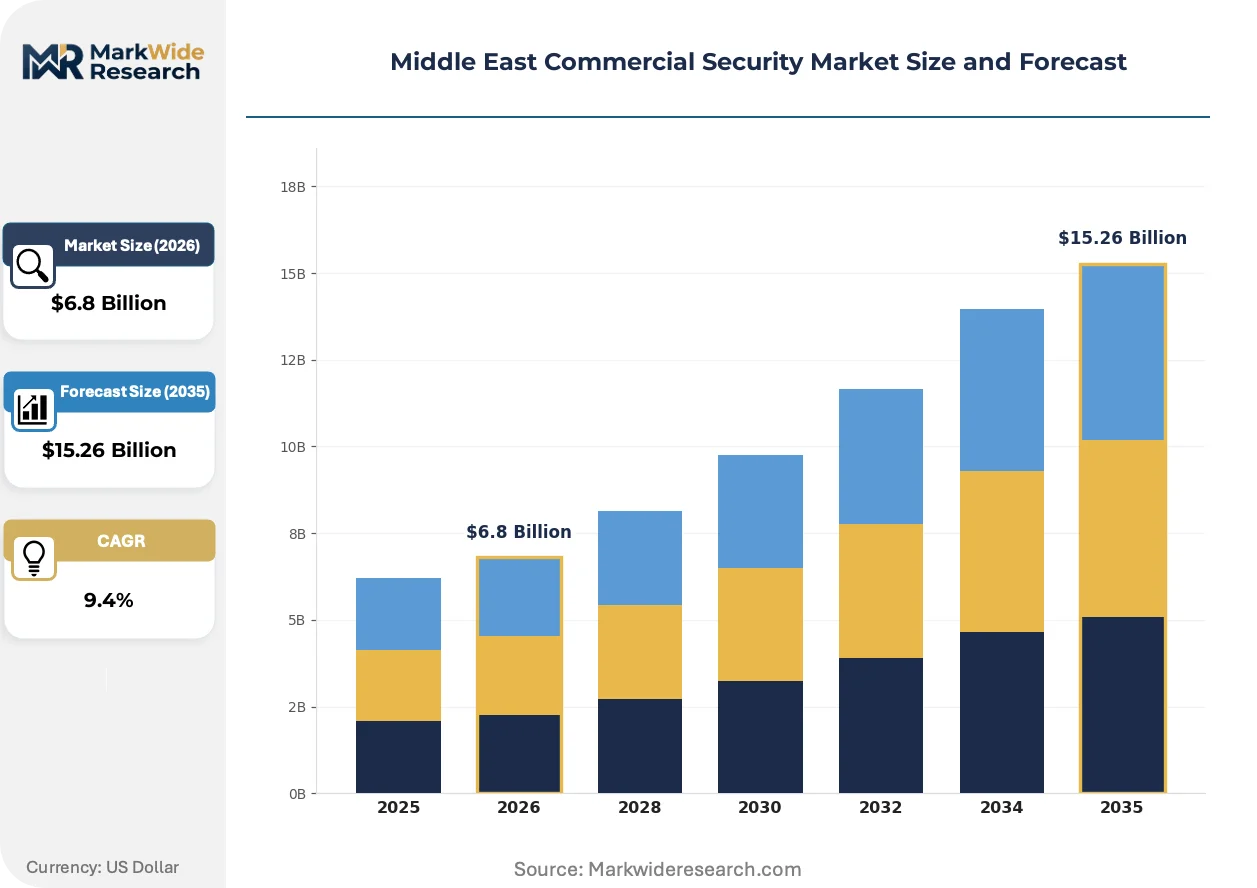
Market Dynamics
Smart city mandates across the Gulf Cooperation Council are compressing procurement cycles for integrated security systems, forcing vendors to bundle AI analytics with legacy infrastructure upgrades rather than sell standalone hardware.
Growth Catalysts
- SFDA Cybersecurity Mandates:Saudi Arabia's pharmaceutical and healthcare security standards are mandating encrypted surveillance networks, creating replacement demand across hospital campuses and medical supply chains.
- Biometric Liveness Detection:Airport operators in the UAE and Qatar are deploying 3D facial recognition with anti-spoofing algorithms to automate passenger processing and reduce manual screening stations.
- Critical Infrastructure Protection:Energy facilities across Kuwait and Oman face hardened perimeter requirements under national security directives, accelerating thermal imaging and radar-based intrusion detection procurement.
Market Restraints
- Semiconductor Component Volatility:Edge AI chipsets and high-resolution image sensors face supply allocation constraints, extending lead times for camera manufacturers serving mega-project timelines.
- Data Localization Requirements:Divergent cloud governance frameworks across Saudi Arabia, UAE, and Qatar fragment architecture standards, elevating compliance engineering costs for regional operators.
- Skilled Integration Labor Scarcity:Shortages of certified systems engineers capable of merging physical security with IT networks constrain deployment velocity for complex multi-site installations.
Strategic Opportunities
- Oman and Bahrain Expansion:Underpenetrated commercial real estate sectors in these markets present first-mover advantages for vendors establishing localized support infrastructure ahead of competitor entry.
- AI-Video Convergence:Behavioral analytics platforms that fuse computer vision with predictive algorithms are opening subscription revenue streams beyond one-time hardware sales.
- MOHAP Healthcare Standards:Dubai's medical facility security protocols are creating template specifications that vendors can replicate across private hospital networks throughout the emirates.
Industry Challenges
- Legacy Analog System Integration:Financial institutions in Saudi Arabia maintain extensive coaxial cable infrastructure, complicating IP migration projects and requiring hybrid architecture expertise.
- Multi-Jurisdiction Certification Lag:Vendors must navigate separate approval processes from UAE NESA, Saudi CITC, and Qatar's national cyber authority, delaying product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Commercial Security Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Access Control Systems, Video Surveillance, Alarms, Intrusion Detection End User: Retail Stores, Financial Institutions, Transportation, Corporate Offices Technology: Cloud-Based, IoT Security Solutions, AI Analytics, Biometric Identification Service Type: Installation Services, Monitoring, Maintenance, Consulting |
| Companies Covered | Hikvision Digital Technology, Axis Communications, Johnson Controls International, Avigilon Corporation, Hanwha Techwin, Honeywell International, Dahua Technology, ADT, Bosch Security Systems, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Commercial Security Market Shifts & Advancements
Edge computing architectures are redistributing processing power from centralized servers to camera hardware, collapsing bandwidth requirements while enabling real-time threat response without cloud dependency.
Multispectral imaging sensors combining visible light with thermal detection are electrifying perimeter security deployments at oil terminals and desalination plants across the Arabian Peninsula. Saudi Aramco facilities and UAE port operators are adopting these systems at accelerated procurement cycles. This convergence of optical and thermal analytics is electrifying the shift from human patrol verification to automated anomaly flagging, compressing security staffing models.
UAE NESA compliance frameworks now mandate government security audits for all critical infrastructure vendors, forcing manufacturers to establish sovereign data centers within federation borders. Industrial consequences include mandatory encryption key escrow and source code disclosure for foreign suppliers. Banking and aviation facilities face the steepest certification burdens, with several international vendors withdrawing from tender processes rather than accept audit conditions.
Consolidated procurement through sovereign wealth fund-backed project developers is displacing fragmented buying by individual facility operators. NEOM, Red Sea Global, and Qiddiya Investment Company now specify security architectures at master planning stages, locking vendors into decade-long service agreements. Saudi Arabia's giga-project pipeline exhibits this concentration most acutely, with single-source awards replacing competitive bidding for integrated city-scale systems.
Middle East Commercial Security Market Segmentation
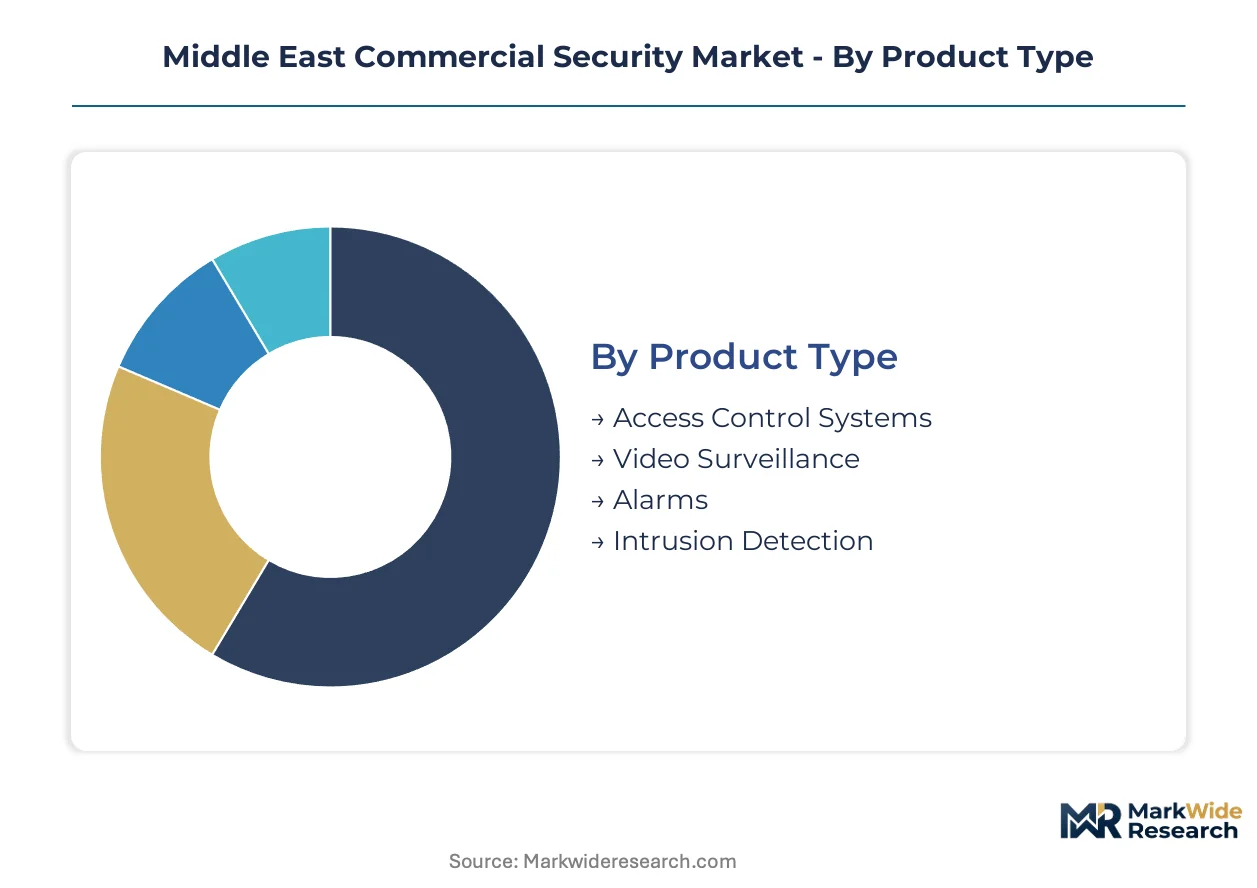
Commercial security procurement across the Middle East diverges sharply by deployment scale and integration complexity. Mega-project developers in Saudi Arabia and the UAE favor bundled systems requiring substantial upfront capital, while smaller commercial operators prioritize modular upgrades.
Product Type:
Capital intensity varies dramatically across hardware categories, with integrated command platforms demanding infrastructure investments that dwarf standalone sensor deployments.
- Access Control Systems:Biometric readers with liveness detection and encrypted credential databases form the core of high-security perimeter protection. Financial institutions in Dubai and Riyadh concentrate procurement here, driven by UAE NESA and Saudi CITC mandates for multi-factor authentication in critical facilities.
- Video Surveillance:IP-based camera networks with edge-computing capabilities now specify minimum 4K resolution and AI-enabled analytics. Transportation hubs across the Gulf Cooperation Council absorb the largest deployment volumes, with automated crowd behavior analysis reducing manual monitoring staffing.
- Alarms:Sensor networks for environmental and perimeter breach notification serve smaller commercial facilities with limited integration requirements.
- Intrusion Detection:Thermal imaging and radar-based systems protect energy infrastructure under hardened national security directives in Kuwait and Oman.
Video surveillance absorbs the bulk of installed capacity; access control systems are expanding most quickly.
End User:
Security spending per square meter diverges by facility criticality, with aviation and financial infrastructure commanding premiums over retail and general office space.
- Financial Institutions:Air-gapped networks and encrypted surveillance archives satisfy Saudi Arabian Monetary Authority and UAE Central Bank cybersecurity protocols. Branch modernization programs across Riyadh and Jeddah concentrate replacement demand as legacy analog systems face mandatory retirement.
- Transportation:Airports in Doha, Dubai, and Jeddah deploy 3D facial recognition with anti-spoofing algorithms for automated passenger processing. Qatar Airways and Emirates hub operations drive specification standards that cascade to regional secondary airports.
- Retail Stores:Loss prevention systems with cloud-based video analytics serve shopping mall operators in Bahrain and Oman with lighter compliance burdens.
- Corporate Offices:Integrated building management systems merge physical security with HVAC and fire safety infrastructure in premium commercial developments.
Transportation commands the highest per-site investment; financial institutions show the steepest replacement cycle acceleration.
Technology:
Architecture decisions between cloud and on-premise deployments determine ongoing operational expenditure profiles and data sovereignty compliance exposure.
- AI Analytics:Computer vision platforms with predictive behavioral algorithms enable subscription revenue models beyond hardware sales. Saudi Aramco facilities and UAE port operators deploy these systems for automated anomaly flagging at perimeter boundaries.
- Biometric Identification:3D facial recognition and fingerprint liveness detection integrate with national ID databases for high-throughput identity verification. Dubai International Airport and Hamad International Airport concentrate demand for touchless passenger processing.
- Cloud-Based:Regional data sovereignty law evolution in Saudi Arabia and Qatar fragments deployment standards for multi-country operators.
- IoT Security Solutions:Sensor convergence platforms merge physical access with environmental monitoring in smart city deployments.
AI analytics is gaining share fastest; biometric identification anchors the highest-margin deployment tier.
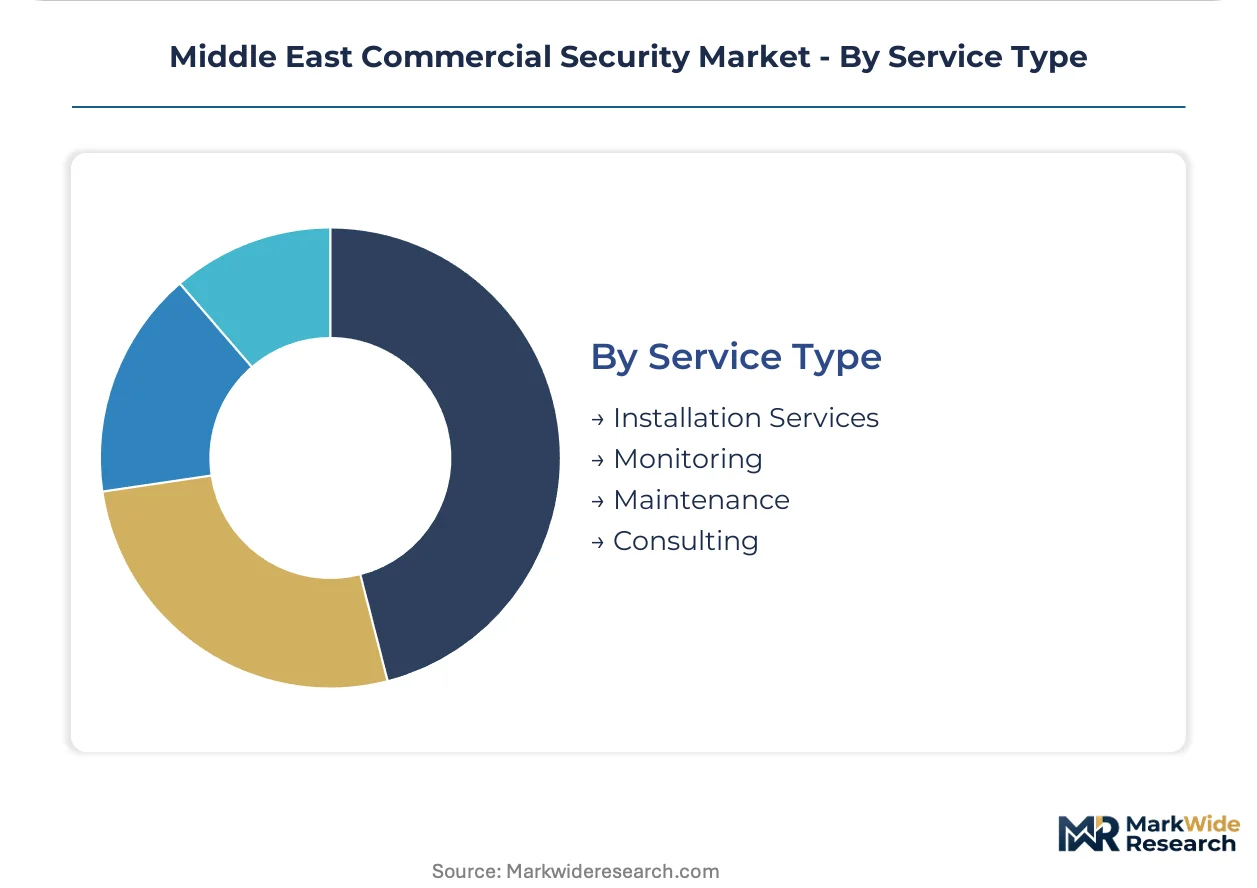
Service Type:
Contract structure preferences separate mega-project developers seeking decade-long integrated service agreements from facility operators buying discrete installation and maintenance packages.
- Monitoring:24/7 command center operations with AI-assisted threat triage command recurring revenue premiums. NEOM, Red Sea Global, and Qiddiya Investment Company specify these services at master planning stages, locking vendors into long-term performance contracts.
- Installation Services:Complex multi-site deployments require certified systems engineers capable of merging physical security with IT networks, a capability scarce across the region.
- Maintenance:Firmware update and hardware replacement schedules ensure compliance with evolving SFDA and NESA certification requirements.
- Consulting:Security architecture design and compliance pathway navigation support foreign vendors facing multi-jurisdiction approval processes.
Monitoring services capture the longest contract durations; installation services face the tightest skilled labor constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai anchors commercial security procurement across the Gulf Cooperation Council, with mega-project developments in the emirate compressing vendor selection timelines and mandating integrated city-scale system architectures.
United Arab Emirates
NEOM and Red Sea Global specifications cascade procurement standards to secondary developers across the federation. MOHAP healthcare security protocols and Dubai Electronic Security Center mandates tighten certification requirements for hospital and aviation facilities. Abu Dhabi National Oil Company facilities drive thermal imaging adoption at energy infrastructure perimeters.
Saudi Arabia
Qiddiya Investment Company and Riyadh mega-developments concentrate decade-long service agreements with single-source vendors. SFDA cybersecurity frameworks mandate encrypted surveillance networks across pharmaceutical supply chains and hospital campuses. Jeddah financial district branch modernization accelerates analog-to-IP migration timelines for banking infrastructure.
Qatar
Hamad International Airport and Qatar Airways hub operations deploy 3D facial recognition with anti-spoofing algorithms for automated passenger processing. National cyber authority certification requirements fragment cloud deployment architectures for multi-country operators. Doha port terminals adopt multispectral imaging sensors for perimeter anomaly detection.
Kuwait
Energy facilities face hardened perimeter requirements under national security directives, accelerating thermal imaging and radar-based intrusion detection procurement. Divergent data localization approaches elevate compliance engineering costs for regional operators maintaining multi-country networks. Kuwait City commercial real estate shows underpenetrated demand for modular access control upgrades.
Oman
Underpenetrated commercial real estate sectors present first-mover positioning for vendors establishing localized support infrastructure. Desalination plants and oil terminals along the Arabian Peninsula coastline adopt automated perimeter monitoring to compress security staffing models. Muscat International Airport expansion drives biometric passenger processing specifications.
Middle East Commercial Security Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated vendor landscape where manufacturing scale and software specialization define opposing strategic poles. Hikvision Digital Technology and Dahua Technology anchor volume supply through integrated production capabilities, while Axis Communications and Avigilon Corporation occupy premium positioning through edge-computing specialization. Three archetypes dominate: integrated building management conglomerates, dedicated video surveillance manufacturers, and AI-native analytics platforms. Competitive intensity concentrates on bundled service agreements for mega-project developers and certification pathway navigation for multi-jurisdiction compliance.
Within the manufacturing-scale tier, Hikvision Digital Technology and Dahua Technology exemplify vertically integrated production models that control component costs and compress delivery timelines for standardized deployments. Axis Communications occupies a differentiated position through edge-computing camera architectures that embed machine learning for corporate and financial institution applications. Johnson Controls International represents the building systems convergence archetype, merging physical security with HVAC and fire safety infrastructure in premium commercial developments.
| Leading Market Players |
|---|
| Hikvision Digital Technology |
| Axis Communications |
| Johnson Controls International |
| Avigilon Corporation |
| Hanwha Techwin |
| Honeywell International |
| Dahua Technology |
| ADT |
| Bosch Security Systems |
| Others |
Supply & Pricing Matrix
A sharp certification-grade bifurcation between UAE NESA-compliant systems and commodity hardware shapes both procurement premiums and supplier sourcing strategies across the Gulf Cooperation Council. Premium tier vendors absorb sovereign data center localization costs and government security audit fees, while volume manufacturers leverage component scale from East Asian production bases to compress unit economics for standardized deployments.
Pricing Analysis
Value-based pricing anchored to system uptime guarantees and compliance certification levels dominates integrated command platform contracts. Three-tier pricing structure across premium, standard, and economy levels separates edge-AI analytics bundles from basic IP camera installations. Cost compression in the commodity tier intensifies because Hikvision and Dahua manufacturing scale feeds aggressive Gulf distributor pricing. Financial institutions in Dubai and Riyadh show least price sensitivity, prioritizing air-gapped network architectures over per-unit hardware costs.
Supply Chain Analysis
Freight cost volatility from East Asian component hubs to Jebel Ali and Dammam ports elevates landed costs for edge-AI chipsets and thermal imaging sensors. Manufacturing concentrates in China, South Korea, and Taiwan for image sensors, system-on-chip processors, and encrypted storage modules. Supply chain risk centers on single-source vulnerability for liveness detection algorithms and biometric reader firmware. Distribution runs through sovereign wealth fund-backed project developers who consolidate decade-long service agreements at master planning stages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where SFDA cybersecurity mandates and UAE NESA certification requirements erect substantial barrier-to-entry moats for vendors bearing localization and audit burdens.
For Market Incumbents: Anchor market position through captive supply of sovereign data center infrastructure and pre-certified hardware platforms. Deepen backward integration into edge-AI chipset sourcing to insulate against semiconductor allocation constraints. Defend against emerging AI-native analytics platforms by locking mega-project developers into bundled service agreements before competitive tendering opens. For New Entrants and Emerging Players: Behavioral analytics platforms with predictive crowd algorithms offer technology-first wedge opportunity against legacy rule-based monitoring incumbents. Target Oman's underpenetrated commercial real estate sector and Bahrain's modular access control upgrade cycles. Pursue channel partnerships with established systems integrators to bypass multi-jurisdiction certification lag. For Investors and Strategic Acquirers: Re-rating potential sits with AI-video convergence specialists given subscription revenue model displacement of one-time hardware sales. Long-term viability favors vendors with established sovereign data center footprints across Saudi Arabia, UAE, and Qatar. Monitor NEOM and Red Sea Global procurement announcements as inflection signal for consolidated buying concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Data Center Localization | UAE NESA compliance mandates force foreign suppliers to establish federation-border data centers with encryption key escrow. |
| AI-Video Analytics Platform Launch | Computer vision with predictive behavioral algorithms opens recurring subscription revenue beyond hardware transaction cycles. |
| Multi-Jurisdiction Certification Investment | Parallel approval processes with Saudi CITC, UAE NESA, and Qatar's national cyber authority compress product launch timelines. |
| Systems Integrator Partnership | Channel alliances with certified engineers capable of merging physical security with IT networks address skilled labor scarcity. |
| Biometric Liveness Detection Acquisition | 3D facial recognition with anti-spoofing algorithms captures high-margin airport passenger processing specifications. |
Research Methodology
Document review covered regulatory filings with Saudi CITC and UAE NESA, customs trade data for security hardware imports, and project developer procurement disclosures, complemented by interviews with systems integration specialists, hospital procurement managers, airport security directors, and financial institution compliance officers. Secondary validation drew from Gulf Cooperation Council smart city investment databases, SFDA cybersecurity framework documentation, and Dubai Electronic Security Center mandate records. Bottom-up demand modeling triangulated against top-down mega-project capital allocation estimates.
Market sizing outputs reflect segment-level projections across product type, end user, technology, and service type dimensions, with additional granularity for deployment scale and integration complexity tiers. CAGRs were derived from historical procurement cycle analysis and forward-looking smart city investment commitments across the projection horizon. Industry-specific forecast inputs incorporated semiconductor lead time volatility and evolving data sovereignty law trajectories in Saudi Arabia and Qatar.
Several conditions sit outside the modeled scope, including unforeseen regulatory harmonization across Gulf Cooperation Council jurisdictions and abrupt shifts in cloud governance frameworks. Forecasts reflect assumptions about continued sovereign wealth fund project development velocity and stable semiconductor supply allocation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Asia-Pacific Public Infrastructure Safety Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Guardrail Protection System Market