
 Perimeter Defense System Market | 2026-2036
Perimeter Defense System Market Size, Share, and Industry Trends Forecast 2026-2036
Perimeter Defense System Market Insights
Consolidation among critical infrastructure operators is repositioning procurement toward integrated platform contracts rather than standalone sensor purchases. Honeywell International Inc. leverages its building-automation heritage to bundle access control with perimeter detection. Dahua Technology Co., Ltd. competes on manufacturing scale across video surveillance and thermal imaging lines. Bosch Security Systems anchors European demand through factory-calibrated sensor arrays that comply with CE marking and data protection protocols.
Perimeter defense systems encompass multi-sensor arrays—typically combining radar, infrared, acoustic, and video analytics—that detect, classify, and alert operators to unauthorized boundary incursions with specified detection ranges and false-alarm thresholds. These systems serve commercial and governmental facilities requiring continuous physical security against intrusion, sabotage, or espionage. Video surveillance dominates current installed base value owing to mature IP-camera ecosystems and analytics software attach rates. Radar-based detection represents the fastest-expanding system type as millimeter-wave hardware drops in cost and integrates with drone-countermeasure networks. Microwave and acoustic sensor categories occupy narrower niche positions where terrain or foliage interference degrades optical performance.
The U.S. Department of Homeland Security and the European Union Agency for Cybersecurity (ENISA) shape demand through critical infrastructure protection mandates that require certified detection reliability and encrypted data transmission. The EU AI Act imposes additional conformity obligations on autonomous threat-classification algorithms, forcing vendors to revalidate software modules. Stakeholders must monitor evolving procurement specifications that increasingly bundle cybersecurity compliance with physical sensor performance.
Market Dynamics
Layered sensor fusion is compressing procurement cycles as defense ministries abandon siloed sensor purchases for unified command platforms. This architectural shift forces vendors to certify integrated stacks under tightening AI governance frameworks.
Growth Catalysts
- EU AI Act:Mandated conformity assessment for autonomous threat-classification algorithms creates certified vendor pools that accelerate procurement timelines for critical infrastructure operators.
- Drone countermeasure networks:Millimeter-wave radar integration with kinetic and electronic defeat systems is driving replacement demand at airports, power plants, and data centers.
- India:The PLI scheme for electronics manufacturing is localizing sensor assembly and reducing import dependency for border security modernization programs.
Market Restraints
- Semiconductor supply concentration:Millimeter-wave chip fabrication clusters in Taiwan and South Korea expose radar system vendors to geopolitical disruption risks and allocation bottlenecks.
- GDPR data localization:Cross-border video analytics deployment faces operational friction from EU member state implementations of data residency requirements for biometric processing.
- LiDAR cost structures:Solid-state ranging sensors remain 3-4x the unit cost of camera arrays, limiting adoption in commercial perimeter applications outside high-security facilities.
Strategic Opportunities
- Saudi Arabia:Giga-project construction at NEOM and Red Sea tourism zones is creating greenfield demand for AI-native perimeter architectures without legacy integration burdens.
- Convergence of thermal imaging and edge AI:On-chip neural processing units are enabling classification at the sensor node, reducing bandwidth costs and cloud dependency for remote installations.
- Brazil ANVISA:Pharmaceutical manufacturing security mandates are extending perimeter certification requirements to API production facilities previously exempt from critical infrastructure classification.
Industry Challenges
- Systems integration talent scarcity:Vendors struggle to recruit engineers proficient in both RF sensor calibration and cybersecurity hardening for converged physical-digital platforms.
- EU AI Act recertification timelines:Software update cycles for threat-detection algorithms trigger re-validation protocols that extend deployment schedules by 6-12 months.
- Interoperability with legacy PIDS:Fiber-optic disturbance sensors and older magnetic detection loops require protocol bridging that degrades real-time performance in mixed-generation installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perimeter Defense System Market |
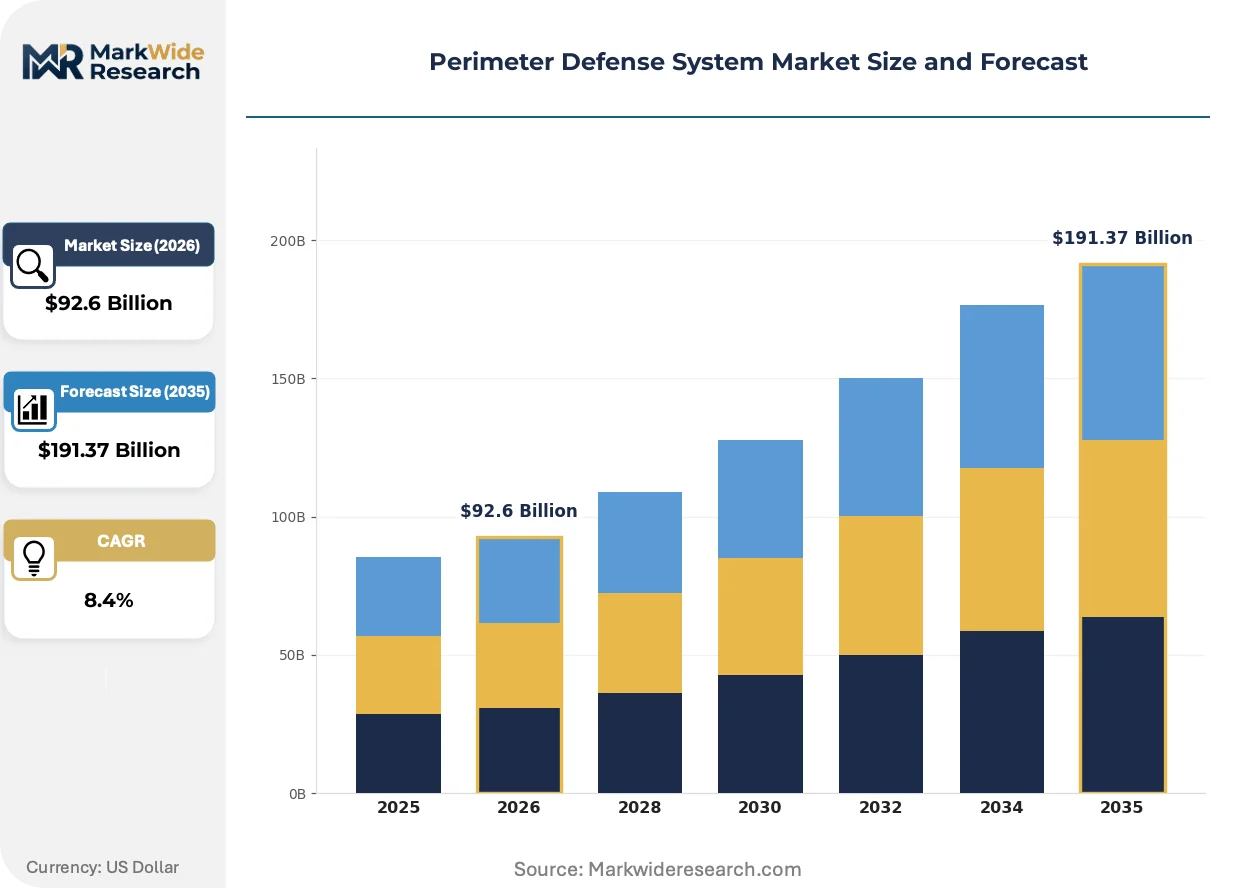
| Market Size in 2026 | $92.6 Billion |
| Market Size in 2035 | $191.37 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Radar-Based, Infrared Sensors, Video Surveillance, Microwave, Acoustic Sensors Deployment Mode: Fixed, Mobile, Networked, Hybrid Application: Critical Infrastructure, Military Bases, Transportation Security, Correctional Facilities, Data Centers End User: Government Agencies, Private Security Firms, Utility Operators, Event Organizers |
| Companies Covered | Honeywell International Inc., Axis Communications AB, Dahua Technology Co., Ltd., Bosch Security Systems, Johnson Controls Inc., Hikvision Digital Technology Co., Ltd., Teledyne FLIR LLC, Hanwha Vision, Senstar Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perimeter Defense System Market Trends and Innovations
Software-defined detection architectures are decoupling hardware refresh cycles from capability upgrades, enabling subscription-based feature delivery that alters vendor revenue models and buyer capital planning.
Millimeter-wave radar-on-chip is rewriting competitive economics in perimeter detection. Foundry-scale production of 60-81 GHz transceiver arrays is cutting unit costs below thermal camera parity. Energy utilities and logistics hubs are deploying these sensors at density levels previously reserved for video analytics. The technology is compressing the total addressable market for pure-play thermal vendors by enabling all-weather detection without illuminator infrastructure.
The EU AI Act's risk-based classification system is restructuring product development roadmaps. High-risk autonomous threat-detection systems now require notified body involvement in training data governance and model validation. German and French critical infrastructure operators are prioritizing vendors with established EU AI Act conformity infrastructure. This regulatory segmentation is creating tiered market access where certified suppliers command procurement preference in public sector tenders.
Consolidated platform contracting is displacing component-level procurement at large facility operators. Honeywell and Johnson Controls are bundling access control, video management, and perimeter detection under single master service agreements. This model shift concentrates vendor selection authority with corporate security directors rather than site-level engineering teams. The United States and Germany exhibit the fastest transition, with integrated platform contracts now representing the majority of new critical infrastructure awards above ten million dollars.
Perimeter Defense System Market Segmentation
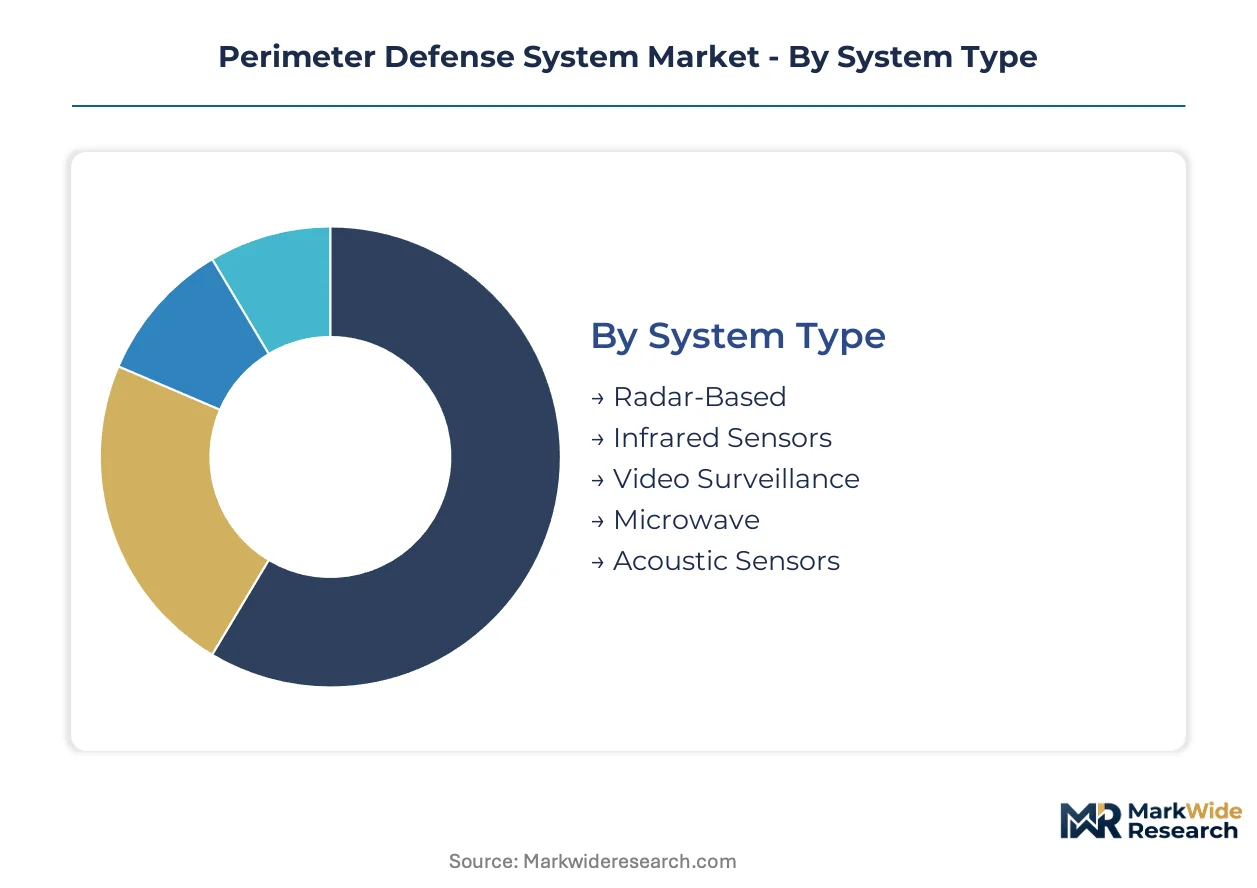
Perimeter defense procurement splits sharply between volume-driven video surveillance and premium radar platforms. Understanding where each technology commands price premiums versus scale economics shapes vendor positioning and R&D allocation across defense ministries and commercial operators.
System Type:
Volume concentration favors mature optical platforms, while premium deployment shifts toward all-weather detection arrays.
- Video Surveillance:IP-camera ecosystems with embedded analytics dominate installed base value through mature supply chains and software attach rates. Data centers and logistics hubs in Germany and the United States drive replacement cycles as cybersecurity hardening requirements tighten under ENISA and DHS mandates.
- Radar-Based:Millimeter-wave arrays detect movement through obscurants without illuminator infrastructure. Airports and power plants across India and Saudi Arabia are deploying these sensors at density levels previously reserved for thermal imaging, enabled by foundry-scale cost reductions in 60-81 GHz transceiver production.
- Infrared Sensors:Thermal imaging lines serve high-security facilities requiring passive detection without RF emissions.
- Microwave:Beam-interruption systems occupy niches where terrain interference degrades optical performance.
- Acoustic Sensors:Vibration and sound detection arrays complement layered architectures in foliage-heavy border zones.
Mature deployment sits with video surveillance. Newer deployment is concentrated in radar-based systems.
Deployment Mode:
Fixed infrastructure absorbs capital budgets, while mobility premiums expand in expeditionary and temporary protection scenarios.
- Fixed:Permanent sensor emplacements with buried cable infrastructure and hardened command centers. Critical infrastructure operators in the United States and Germany favor these installations for 20-year asset lifecycles under master service agreements with building-automation vendors.
- Mobile:Rapidly deployable trailer-mounted arrays with self-contained power and satellite backhaul. Border security agencies in India deploy these units along disputed frontiers where permanent construction faces terrain or diplomatic constraints.
- Networked:Distributed sensor nodes feeding centralized analytics platforms via encrypted mesh protocols.
- Hybrid:Configurations combining fixed backbone with mobile augmentation for surge capacity.
Fixed installations anchor procurement value. Hybrid architectures are gaining share fastest among operators managing variable threat levels.
Application:
Critical infrastructure commands compliance premiums, while military specifications drive performance certification thresholds.
- Critical Infrastructure:Energy, water, and telecommunications facilities requiring continuous protection under national security directives. EU member states enforce CE marking and EU AI Act conformity for autonomous threat classification at nuclear and substation perimeters.
- Military Bases:Layered detection with kinetic defeat integration and electronic warfare hardening. Procurement concentrates in the United States and India as defense ministries modernize forward operating bases and strategic asset protection.
- Transportation Security:Airports, seaports, and rail yards combining passenger screening with perimeter intrusion detection.
- Correctional Facilities:Anti-climb and tunnel-detection systems for prison perimeters.
- Data Centers:Hyperscale computing campuses requiring drone countermeasures and thermal detection for cooling infrastructure protection.
Critical infrastructure absorbs the largest procurement volumes. Data centers are expanding most quickly as cloud operators harden physical security against espionage and sabotage.
End User:
Government tenders set technical specifications that cascade into private sector procurement standards.
- Government Agencies:Defense ministries and border forces issuing performance-based specifications with cybersecurity annexes. DHS and EU Agency for Cybersecurity mandates require encrypted transmission and AI algorithm validation, creating certified vendor pools that accelerate procurement for compliant suppliers.
- Private Security Firms:Contracted facility protection operators purchasing integrated platforms rather than component sensors. Consolidation among European and North American operators is concentrating buying power with corporate security directors.
- Utility Operators:Electricity, water, and pipeline companies subject to critical infrastructure protection regulations.
- Event Organizers:Temporary perimeter protection for sporting venues and political summits requiring rapid deployment and strike capabilities.
Government agencies anchor specification development. Private security firms are driving fastest adoption of subscription-based software-defined detection models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries in the United States, Germany, and India concentrate procurement volumes for layered detection platforms. Border security agencies across these markets modernize physical protection at energy nodes and transportation infrastructure under tightening certification mandates.
United States
The Department of Homeland Security drives procurement through critical infrastructure protection mandates requiring encrypted data transmission and certified detection reliability. DHS specifications cascade into private sector standards for data centers and logistics hubs. Texas and Virginia hyperscale computing campuses deploy drone countermeasures and thermal detection for cooling infrastructure protection.
Germany
Industrial operators in Baden-Württemberg and Bavaria anchor European demand for factory-calibrated sensor arrays. The EU AI Act imposes conformity obligations on autonomous threat-classification algorithms, forcing vendors to revalidate software modules. Frankfurt and Munich data centers prioritize suppliers with established EU AI Act conformity infrastructure for public sector tenders.
India
The PLI scheme for electronics manufacturing localizes sensor assembly and reduces import dependency for border security modernization. Defense ministries deploy mobile trailer-mounted arrays along disputed frontiers where permanent construction faces terrain constraints. Gujarat and Karnataka manufacturing clusters scale millimeter-wave radar component production for domestic and export markets.
Saudi Arabia
Giga-project construction at NEOM and Red Sea tourism zones creates greenfield demand for AI-native perimeter architectures without legacy integration burdens. The kingdom's national security directives require continuous protection at energy and water facilities. Riyadh and the Eastern Province concentrate procurement for strategic asset protection and critical infrastructure hardening.
United Kingdom
ENISA mandates shape procurement specifications for encrypted transmission and AI algorithm validation across nuclear and telecommunications facilities. London and Southeast England data centers expand physical security against espionage and sabotage. The country's border force deploys layered detection at ports and airports under performance-based specifications with cybersecurity annexes.
Perimeter Defense System Market Competitive Landscape
United States producers anchor the integrated platform tier; European specialists hold the factory-calibrated sensor segment. The vendor base separates between building-automation conglomerates bundling access control with perimeter detection and pure-play security manufacturers competing on sensor density. Three archetypes dominate: automation-heritage conglomerates, video surveillance scale players, and thermal imaging specialists. Competitive moves concentrate on unified command platform certification and AI governance framework compliance.
Within the automation-heritage tier, Honeywell International Inc. and Johnson Controls Inc. represent consolidated platform contracting models that displace component-level procurement. Among video surveillance manufacturers, Dahua Technology Co., Ltd. and Hikvision Digital Technology Co., Ltd. occupy positions defined by manufacturing scale across camera ecosystems. Bosch Security Systems anchors European demand through CE marking compliance and data protection protocol adherence. These named entities exemplify how regulatory certification and integration capability determine procurement preference in public sector tenders.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Axis Communications AB |
| Dahua Technology Co., Ltd. |
| Bosch Security Systems |
| Johnson Controls Inc. |
| Hikvision Digital Technology Co., Ltd. |
| Teledyne FLIR LLC |
| Hanwha Vision |
| Senstar Corporation |
| Others |
Pricing and Supply Chain Analysis
Defense ministry procurement programs in the United States, Germany, and India anchor demand for integrated perimeter platforms, compressing vendor margins through consolidated master service agreements that bundle hardware, software, and maintenance under long-term contractual frameworks.
Pricing Analysis
Volume concentration in video surveillance segments runs on per-unit transactional pricing with thin software attach margins, while radar-based platforms command project-based premiums driven by millimeter-wave certification tiers and kinetic defeat integration complexity. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-validated autonomous threat classification from legacy sensor arrays and unbundled component sales. Pricing pressure stems from foundry-scale cost compression in 60-81 GHz transceiver production eroding thermal camera parity. Government agencies exhibit lowest price sensitivity due to cybersecurity compliance mandates; commercial logistics operators in emerging markets show highest elasticity.
Supply Chain Analysis
Millimeter-wave chip fabrication rests on Taiwan and South Korea for foundry capacity, with Germany and the United States contributing RF design and calibration equipment. Critical inputs span GaAs/GaN semiconductor substrates, precision antenna arrays, and edge AI neural processing units. Single-source vulnerability concentrates in Taiwan Strait geopolitical exposure threatening radar system allocation. Distribution runs through building-automation conglomerates with direct defense ministry contracting and certified systems integrators serving critical infrastructure operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millimeter-wave foundry capacity bottlenecks in Taiwan and South Korea prop pricing premiums for radar-integrated platforms, constraining supply elasticity even as demand accelerates for drone countermeasure networks.
For Market Incumbents: Hedge against pure-play thermal vendor displacement by accelerating backward integration into edge AI chip design and securing EU AI Act notified body partnerships before recertification timelines extend. Prioritize capacity addition in India under PLI scheme incentives to reduce Taiwan exposure. Channel control through master service agreements with Honeywell and Johnson Controls anchors procurement preference. For New Entrants and Emerging Players: Capture greenfield demand at Saudi giga-projects and Brazilian pharmaceutical facilities newly subject to ANVISA perimeter mandates, where legacy integration burdens are absent. Target mobile trailer-mounted arrays for Indian border security programs facing terrain constraints. Go-to-market through satellite backhaul partnerships enables rapid deployment without fixed infrastructure investment. For Investors and Strategic Acquirers: The window for entry favors EU AI Act-certified software-defined detection specialists with established notified body relationships and recurring revenue architectures. Long-term viability hinges on convergence of thermal imaging and edge AI classification at the sensor node. Watch millimeter-wave radar-on-chip cost curves as inflection indicator for thermal camera market compression.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Conformity Investment | Notified body partnerships accelerate procurement timelines for German and French critical infrastructure tenders. |
| Millimeter-Wave Radar Integration | Drone countermeasure network certification opens airport and power plant replacement cycles in India and Saudi Arabia. |
| Software-Defined Detection Architecture | Subscription-based feature delivery alters vendor revenue models and buyer capital planning for data center operators. |
| India PLI Localization | Domestic sensor assembly reduces import dependency for border security modernization programs under defense ministry specifications. |
| Edge AI Neural Processing Unit Development | On-chip classification reduces bandwidth costs and cloud dependency for remote installations in foliage-heavy border zones. |
Research Methodology
Independent corroboration across defense ministry procurement officers, critical infrastructure security directors, and building-automation systems integrators underwrites the qualitative findings, validated against ENISA critical infrastructure protection mandates, DHS cybersecurity specifications, and EU AI Act conformity assessment protocols. Secondary sources include customs filings for millimeter-wave component trade, SEC disclosures from automation-heritage conglomerates, and project development databases for giga-project security spending. Bottom-up sensor deployment tallies triangulate with top-down addressable market sizing across the analysis window.
Comparable-period anchoring to historical defense modernization cycles and critical infrastructure protection directive implementation timelines shapes the projection horizon. Segmentation dimensions span system type, deployment mode, application vertical, and end-user procurement authority, with regional regulatory cluster effects modeled separately. CAGRs derive from installed base replacement assumptions, technology substitution elasticities, and compliance-driven upgrade mandates. Forecast inputs incorporate foundry capacity expansion schedules for 60-81 GHz transceiver production and EU AI Act recertification timeline distributions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan Strait supply disruption, EU AI Act enforcement variance across member states, and drone threat evolution accelerating technology obsolescence. Assumptions reflect current regulatory trajectories and procurement specification trends. Semiconductor allocation bottlenecks, GDPR biometric data localization rulings, and kinetic defeat integration standards warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Infrastructure Protection Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Europe Pipeline Security Market