
 Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market | 2026-2036
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market Outlook
Multi-source procurement for safety instrumented systems is broadening across Asia-Pacific energy projects. Emerson Electric Co. leverages its integrated automation portfolio to anchor large-scale LNG contracts in Australia. Yokogawa Electric Corp. specializes in distributed control architectures that compete for offshore platform retrofits. HIMA Paul Hildebrandt GmbH sustains its position through certified safety logic solvers that dominate high-integrity applications.
A High-Integrity Pressure Protection System comprises independent sensor arrays, logic solvers, and final control elements designed to achieve Safety Integrity Level 3 ratings per IEC 61511, shutting down process flow within milliseconds when pressure exceeds preset thresholds. Electronic HIPPS variants command the dominant share due to faster response times and diagnostic visibility, while Hybrid HIPPS configurations are gaining traction in subsea tiebacks where mechanical redundancy supplements electronic precision. Oil and Gas applications absorb the largest procurement volumes, though Chemical Processing represents the fastest-growing segment as China's petrochemical expansion drives new safety investments.
Japan's METI enforces stringent certification under JIS standards for pressure safety equipment, while Australia's state-level regulators mandate compliance with AS 61511 for offshore installations. China's SAMR aligns domestic HIPPS testing with GB standards that increasingly reference IEC frameworks. Procurement teams must weigh certification reciprocity against project-specific regulator demands when qualifying suppliers across this fragmented compliance terrain.
Market Dynamics
Offshore field developments in Southeast Asia are pushing procurement toward subsea-rated HIPPS architectures as operators confront deeper-water pressure envelopes and stricter AS 61511 compliance mandates across Australian LNG corridors.
Growth Catalysts
- Subsea tieback proliferation:Indonesia's Natuna gas development and Malaysia's Sarawak deepwater blocks are mandating SIL 3-rated final control elements for subsea wellhead isolation.
- Australia's Work Health and Safety Act amendments:Tighter pressure equipment standards are forcing brownfield retrofit cycles across Queensland and Western Australia LNG trains.
- Electronic HIPPS diagnostic visibility:Millisecond response times and predictive maintenance capabilities are displacing legacy mechanical trip systems in high-integrity applications.
Market Restraints
- Specialized alloy input costs:Inconel 625 and duplex stainless steel price volatility constrains final element manufacturing margins for subsea valve suppliers.
- Safety logic solver supply concentration:Certified TÜV Rheinland-approved platforms remain concentrated among German and Swiss automation houses, creating procurement bottlenecks.
- JIS certification reciprocity gaps:Japan's METI standards lack mutual recognition with Australia's state-level regulators, forcing redundant testing for regional projects.
Strategic Opportunities
- Vietnam offshore licensing rounds:Block B and Ca Voi Xanh developments are opening first-mover positioning for integrated HIPPS-EPC contractors.
- China's petrochemical expansion:Ethylene crackers and aromatics complexes along the Yangtze River Delta are driving Chemical Processing segment demand for compact HIPPS skids.
- Digital twin integration:Convergence of SIL-rated logic solvers with real-time process simulation is enabling predictive safety verification before physical commissioning.
Industry Challenges
- Functional safety engineering talent scarcity:IEC 61511 certified practitioners remain concentrated in Australia and Japan, creating project staffing gaps for Indonesian and Vietnamese developments.
- Legacy DCS integration complexity:Brownfield platforms running Yokogawa CENTUM or Honeywell TDC 3000 require custom gateway engineering to achieve seamless HIPPS integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market |
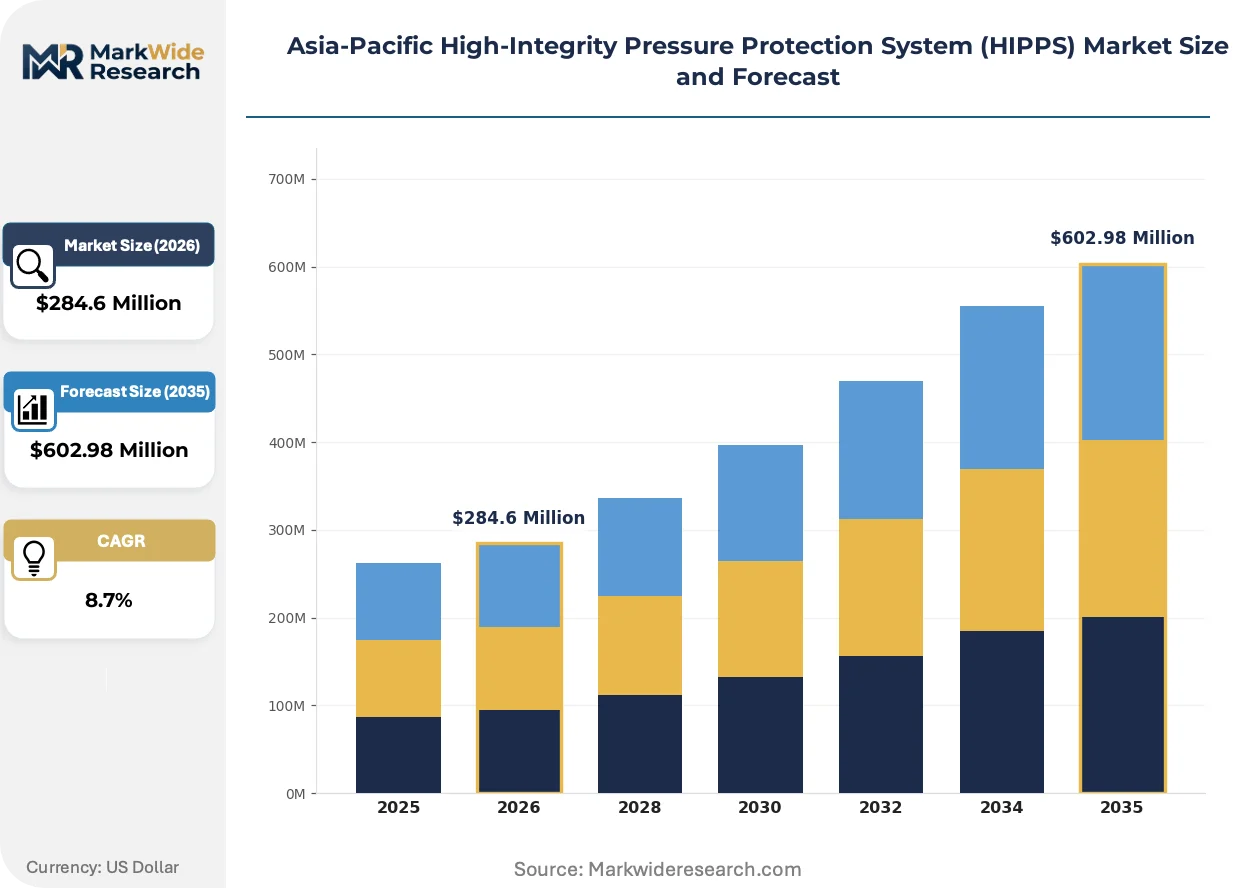
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $602.98 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic HIPPS, Mechanical HIPPS, Hybrid HIPPS, Software-based HIPPS Application: Oil & Gas, Chemical Processing, Power Generation, Marine Industry End User: Utilities, Industrial Manufacturers, Oil Refineries, Engineering Firms Technology: Smart Sensors, Control Systems, Safety Instrumented Systems, Remote Monitoring |
| Companies Covered | Emerson Electric Co., Yokogawa Electric Corp., HIMA Paul Hildebrandt GmbH, ABB, Rockwell Automation Inc., L&T Valves Limited, SLB, IMI Critical Engineering, KROHNE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market Strategic Shifts
Hybrid HIPPS configurations are gaining procurement traction as subsea projects demand mechanical redundancy layered beneath electronic precision, while regulatory divergence across Asia-Pacific jurisdictions is fragmentating supplier qualification protocols.
Hybrid HIPPS architectures combine spring-actuated mechanical trip systems with electronic monitoring loops to achieve fault tolerance in subsea umbilical failures. Offshore operators in Australia's Ichthys and Prelude developments are specifying these configurations for Christmas tree protection. This dual-layer approach is expanding into shallower-water tiebacks as insurers demand demonstrable redundancy beyond single-technology solutions.
Japan's METI has tightened JIS B 8265 enforcement for pressure safety equipment, requiring third-party witnessing of HIPPS valve seat leakage tests. Australian state regulators are reciprocally demanding AS 61511 compliance documentation for all imported safety instrumented systems. Chemical Processing facilities in China's Zhejiang and Jiangsu provinces face the steepest adaptation curve as they reconcile GB standards with IEC framework alignment.
Integrated service contracting is compressing traditional EPC-SSI procurement separations as operators bundle HIPPS specification with long-term maintenance liability. Australia's LNG exporters are leading this consolidation, requiring vendors to assume 15-year availability guarantees. This restructuring is most visible in Queensland's Curtis Island developments, where single-source accountability is displacing fragmented multi-vendor arrangements.
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market Segmentation
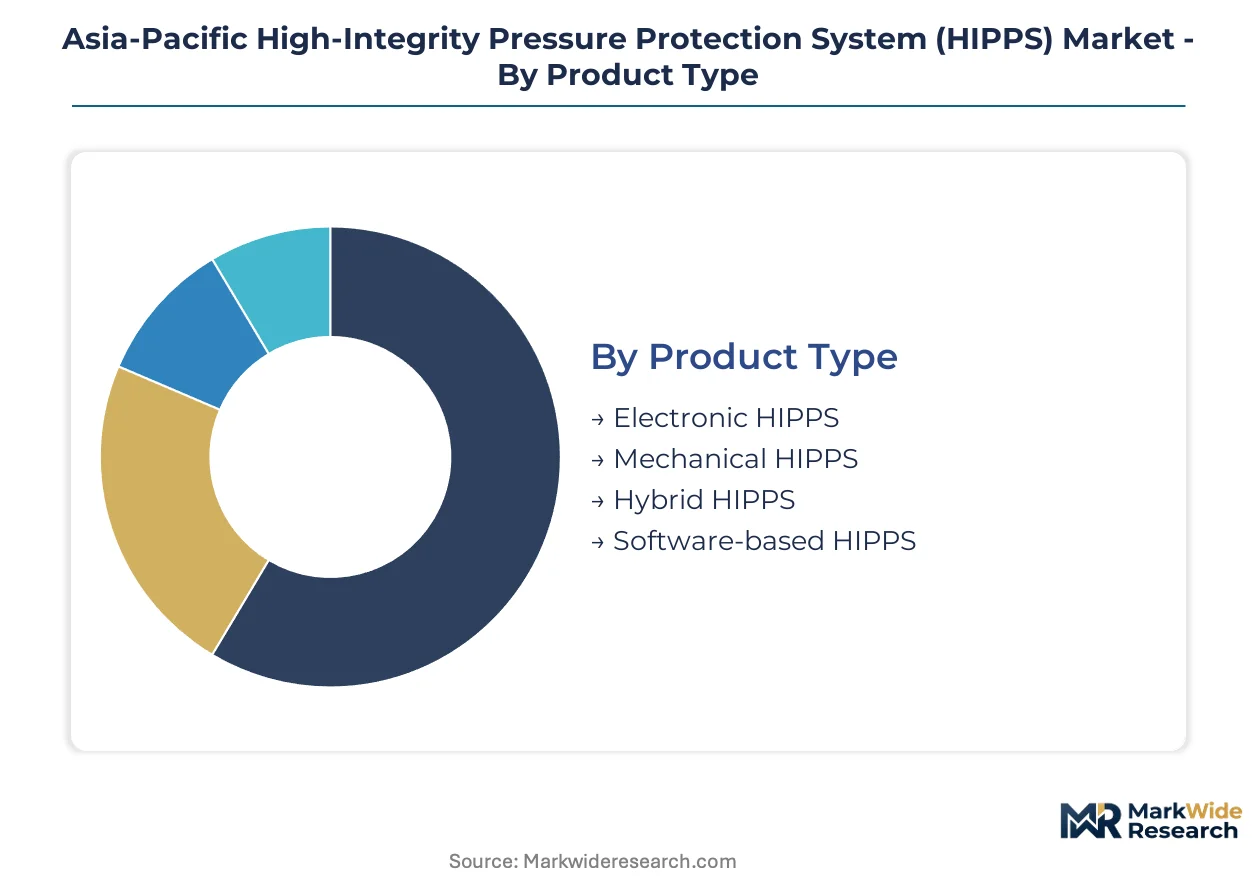
HIPPS procurement across Asia-Pacific fragments sharply by operational environment and safety architecture requirements. Electronic systems dominate offshore specifications while hybrid configurations penetrate deeper-water tiebacks. Each segment carries distinct certification burdens under IEC 61511, JIS B 8265, and AS 61511 frameworks.
Product Type:
Customization intensity spans from fully configurable electronic platforms to rigid mechanical trip systems with fixed setpoints.
- Electronic HIPPS:Microprocessor-based logic solvers achieve SIL 3 ratings through redundant CPU architectures with diagnostic coverage exceeding 99%. Australian LNG corridors and Indonesia's Natuna developments specify these for millisecond response requirements. Predictive maintenance capabilities displace legacy mechanical systems in brownfield retrofits.
- Hybrid HIPPS:Spring-actuated mechanical trips layered beneath electronic monitoring loops provide fault tolerance during subsea umbilical failures. Australia's Ichthys and Prelude fields mandate these for Christmas tree protection at depths exceeding 1,500 meters. Insurers increasingly require demonstrable redundancy beyond single-technology solutions.
- Mechanical HIPPS:Pneumatic or hydraulic trip systems without electronic dependencies serve isolated wellhead applications in remote Papua New Guinea fields.
- Software-based HIPPS:Virtualized safety logic running on certified industrial servers gains traction in onshore chemical processing facilities.
Leading the category by volume: Electronic HIPPS. Growing fastest: Hybrid HIPPS.
Application:
Application mix tracks regional energy infrastructure investment cycles with offshore oil and gas commanding procurement priority.
- Oil & Gas:Offshore field developments in Southeast Asia drive SIL 3-rated final element specifications for subsea wellhead isolation. Malaysia's Sarawak deepwater blocks and Vietnam's Block B licensing rounds anchor demand concentration. Brownfield retrofit cycles across Queensland and Western Australia LNG trains accelerate replacement of legacy mechanical trip systems.
- Chemical Processing:Ethylene crackers and aromatics complexes along China's Yangtze River Delta require compact HIPPS skids for high-pressure reactor protection. Zhejiang and Jiangsu provinces face steepest adaptation curves reconciling GB standards with IEC framework alignment. Petrochemical expansion outpaces other application segments in procurement velocity.
- Power Generation:Combined-cycle gas turbine plants in South Korea and Taiwan specify HIPPS for steam drum overpressure protection.
- Marine Industry:LNG carrier cargo containment systems utilize pressure protection for membrane tank integrity.
Dominant by procurement value: Oil & Gas. Expanding most quickly: Chemical Processing.
End User:
End user categories reflect divergent technical capabilities and long-term maintenance liability preferences.
- Oil Refineries:Integrated refining-petrochemical complexes in Singapore and Thailand require continuous HIPPS availability for hydrocracker and resid upgrading units. These operators favor 15-year service contracts bundling specification with maintenance liability. Single-source accountability displaces fragmented multi-vendor arrangements.
- Engineering Firms:EPC contractors executing Vietnam's Ca Voi Xanh and Indonesia's Abadi developments specify HIPPS during front-end engineering design. These firms concentrate functional safety engineering talent for IEC 61511 compliance documentation. Procurement teams weigh certification reciprocity against project-specific regulator demands.
- Industrial Manufacturers:Fertilizer and specialty chemical producers in eastern China adopt standardized skid-mounted configurations.
- Utilities:Power grid operators in Australia and Japan specify HIPPS for gas-insulated switchgear pressure containment.
Highest specification complexity: Oil Refineries. Fastest contract velocity: Engineering Firms.
Technology:
Technology stack composition determines diagnostic visibility and integration complexity with existing distributed control architectures.
- Safety Instrumented Systems:Certified TÜV Rheinland-approved logic solver platforms remain concentrated among German and Swiss automation houses. These systems achieve fault tolerance through redundant architectures with automatic self-testing. Procurement bottlenecks persist due to limited certified supplier base.
- Smart Sensors:Piezoelectric and strain-gauge pressure transmitters with HART protocol integration enable predictive diagnostics for valve seat leakage detection. Japan's METI mandates third-party witnessing of seat leakage tests under tightened JIS B 8265 enforcement.
- Control Systems:Custom gateway engineering bridges SIL-rated solvers with legacy Yokogawa CENTUM or Honeywell TDC 3000 installations.
- Remote Monitoring:Subsea umbilical fiber-optic links transmit diagnostic data to platform control rooms for unmanned wellhead protection.
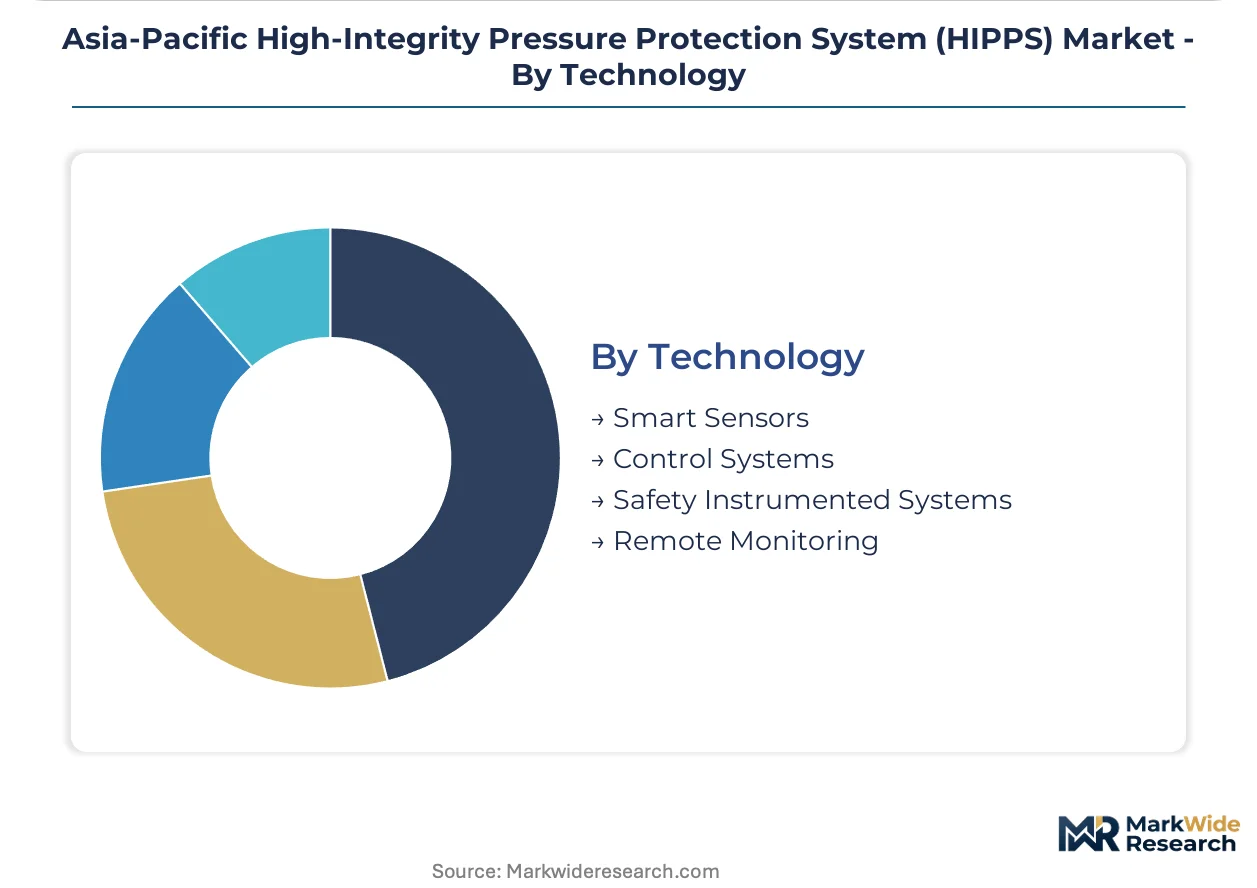
Core technology by procurement spend: Safety Instrumented Systems. Steepest capability investment: Smart Sensors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement for High-Integrity Pressure Protection Systems concentrates along Australia's LNG export corridor and Indonesia's deepwater gas developments, with emerging demand clusters forming in Vietnam's offshore licensing rounds and China's petrochemical expansion zones.
Australia
Queensland's Curtis Island LNG trains and Western Australia's offshore platforms drive brownfield retrofit demand as the Work Health and Safety Act tightens pressure equipment standards. State-level regulators mandate AS 61511 compliance documentation for all imported safety instrumented systems. The Ichthys and Prelude fields specify hybrid HIPPS configurations for Christmas tree protection at depths exceeding 1,500 meters.
Indonesia
The Natuna gas development and Abadi deepwater project mandate SIL 3-rated final control elements for subsea wellhead isolation. The country's national energy regulator enforces certification alignment with IEC 61511 frameworks for offshore installations. Engineering procurement centers in Jakarta coordinate front-end engineering design for integrated HIPPS-EPC contracts.
China
Ethylene crackers and aromatics complexes along the Yangtze River Delta require compact HIPPS skids for high-pressure reactor protection. SAMR aligns domestic HIPPS testing with GB standards that increasingly reference IEC frameworks. Zhejiang and Jiangsu provinces face the steepest adaptation curves reconciling local standards with international safety protocols.
Vietnam
Block B and Ca Voi Xanh offshore developments are opening first-mover positioning for integrated HIPPS-EPC contractors. The country's national industrial safety authority is developing pressure equipment regulations modeled on regional precedents. Ho Chi Minh City-based engineering firms concentrate functional safety talent for IEC 61511 compliance documentation.
Japan
Combined-cycle gas turbine plants and power generation infrastructure specify HIPPS for steam drum overpressure protection. METI enforces stringent certification under JIS B 8265, requiring third-party witnessing of valve seat leakage tests. The Kanto and Kansai industrial corridors maintain concentrated engineering expertise for high-integrity safety system design.
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market Competitive Environment
Integrated service contracting dominates the current landscape as operators bundle HIPPS specification with long-term maintenance liability. The vendor base separates into three distinct tiers: multinational automation houses with certified safety logic platforms, regional valve specialists with subsea manufacturing capabilities, and integrated EPC contractors assuming single-source accountability. Two strategic archetypes define competitive positioning: technology licensors leveraging diagnostic visibility advantages, and project developers capturing lifecycle revenue through availability guarantees. Geographic expansion and portfolio diversification represent the dominant competitive moves as suppliers chase Vietnam's offshore licensing rounds and China's petrochemical buildout.
Among Germany-based safety specialists, HIMA Paul Hildebrandt GmbH exemplifies the certified logic solver archetype, while Japan's Yokogawa Electric Corp. occupies a position within the distributed control integration tier. Emerson Electric Co. represents the integrated automation house model with anchoring presence across Australian LNG contracts. These three entities illustrate the competitive spectrum spanning specialized safety engineering through full-scope automation portfolios.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Yokogawa Electric Corp. |
| HIMA Paul Hildebrandt GmbH |
| ABB |
| Rockwell Automation Inc. |
| L&T Valves Limited |
| SLB |
| IMI Critical Engineering |
| KROHNE |
| Others |
Value Chain & Pricing Dynamics
Captive integration of safety logic solver manufacturing anchors both supply security and pricing power for certified HIPPS suppliers serving Australia's LNG corridors and Indonesia's deepwater gas developments. German and Swiss automation houses control TÜV Rheinland-approved platforms, enabling premium positioning against regional valve specialists who must source these critical components externally.
Pricing Analysis
Availability-guarantee bundling separates premium-tier suppliers from unbundled competitors across Asia-Pacific energy projects. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under IEC 61511, JIS B 8265, and AS 61511 frameworks. Cost compression in electronic logic solver tiers is intensifying because alloy input volatility for Inconel 625 final elements constrains manufacturing margins. Engineering firms executing Vietnam's Block B developments exhibit highest price sensitivity, while Australia's Curtis Island LNG operators prioritize 15-year service contracts over unit economics.
Supply Chain Analysis
Freight cost escalation for subsea-rated valve assemblies shapes procurement geography across Asia-Pacific HIPPS deployments. Manufacturing concentrates in Germany, Switzerland, and Japan for certified safety logic solvers, while final element fabrication centers on Singapore and South Korea for subsea alloy machining. The supply chain draws from specialized Inconel 625 and duplex stainless steel feedstocks, plus fiber-optic umbilical components for deepwater diagnostics. Single-source vulnerability in TÜV-certified logic solver platforms creates procurement bottlenecks for Indonesian and Vietnamese developments. Distribution runs through integrated EPC contractors assuming single-source accountability for long-term maintenance liability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where Australia's AS 61511 mandates and Japan's JIS B 8265 enforcement erect barrier-to-entry moats favoring incumbent suppliers with established certification portfolios.
For Market Incumbents: Extend certification coverage across multiple Asia-Pacific regulatory frameworks to preempt reciprocity gaps between Australia's state-level regulators and Japan's METI. Backward integration into subsea valve alloy sourcing mitigates Inconel 625 price volatility threatening manufacturing margins. Capacity addition in Singapore or South Korea final element fabrication strengthens position against regional valve specialists. For New Entrants and Emerging Players: Begin with compact HIPPS skid configurations for China's Yangtze River Delta petrochemical expansion, where GB standard alignment with IEC frameworks creates accessible entry conditions. Vietnam's Ca Voi Xanh and Block B developments offer white-space positioning before integrated EPC contracting consolidates. Partner with Ho Chi Minh City engineering firms for IEC 61511 compliance documentation capability. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated automation houses seeking safety logic solver capabilities. Long-term viability hinges on certification portfolio breadth across Australian, Japanese, and Chinese regulatory frameworks. Target specialists with TÜV Rheinland-approved platforms and established subsea final element supply relationships. Watch for JIS-AS reciprocity agreements as inflection signal for qualification cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | Multi-jurisdiction AS 61511 and JIS B 8265 coverage unlocks Australian LNG and Japanese power generation contracts. |
| Subsea Alloy Supply Integration | Captive Inconel 625 sourcing insulates margins against nickel price volatility affecting final element manufacturing. |
| Integrated EPC Contracting | Single-source 15-year availability guarantees displace fragmented multi-vendor arrangements across Queensland developments. |
| Digital Twin Integration | SIL-rated logic solver convergence with real-time simulation enables predictive safety verification before physical commissioning. |
| Vietnam Market Entry | First-mover positioning in Block B and Ca Voi Xanh licensing rounds precedes regulatory consolidation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific HIPPS market assessment. Primary interviews with safety system engineering directors, EPC procurement leads, offshore platform maintenance managers, and national regulator compliance officers combined with secondary validation from IEC standards documentation, METI certification databases, and Australian state-level WHS enforcement records. Bottom-up project pipeline analysis across Indonesia's Natuna development, Australia's Curtis Island LNG trains, and Vietnam's offshore licensing rounds triangulated against top-down energy infrastructure investment forecasts.
Reconciliation of shipment data, contract award announcements, and certification registry updates informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture tier, application environment, end-user liability preference, and technology stack composition. CAGRs derived from installed base expansion rates, brownfield retrofit cycles, and greenfield project commissioning schedules. Subsea tieback proliferation intensity and petrochemical capacity buildout velocity served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; electronic HIPPS and established LNG corridor deployments carry tighter precision than emerging hybrid configurations and Vietnam licensing round timing. Forecasts reflect assumptions regarding regulatory enforcement continuity, alloy input price stability, and certification reciprocity negotiation progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Threat Lifecycle Services Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
UK Critical Infrastructure Protection Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market