
 Asia-Pacific Public Infrastructure Safety Market | 2026-2036
Asia-Pacific Public Infrastructure Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Public Infrastructure Safety Market Insights
Buyer concentration across Asia-Pacific transportation authorities is rebalancing as fragmented municipal contracts consolidate into multi-city framework agreements. Motorola Solutions Inc leverages its command-center software footprint to anchor large-scale transit deployments across Australian states. Cisco Systems Inc competes on edge-networking integration for urban surveillance backbones. Hexagon AB specializes in geospatial incident-response platforms that dominate emergency-service dispatch protocols.
Public infrastructure safety encompasses engineered systems and operational protocols that protect critical physical assets from operational failure, deliberate harm, and environmental hazards, incorporating sensor networks with sub-second latency thresholds and redundant communication pathways for continuous monitoring. Surveillance Systems command the largest installed base among product types, though AI-Driven Analytics within the technology dimension captures the fastest expansion as municipalities replace rule-based alerts with predictive threat models. Installation Services generate recurring revenue streams that outlast initial hardware margins, particularly across government institutions with decade-long maintenance obligations.
Japan's METI enforces industrial-security standards for critical infrastructure operators, while Australia's Essential Services Commission mandates resilience reporting for utility providers. India's CEA issues grid-protection directives that compel utility providers to upgrade substation monitoring. Stakeholders must weigh interoperability requirements against proprietary platform lock-in as procurement shifts toward integrated multi-technology stacks.
Market Dynamics
Multi-city framework agreements are consolidating fragmented municipal procurement across Southeast Asian transportation authorities, compressing vendor sales cycles and favoring integrated platform providers over point-solution specialists.
Growth Catalysts
- India's National Infrastructure Pipeline:Urban resilience mandates under this framework are compelling metropolitan transit authorities to upgrade sensor networks and command-center capabilities.
- CEA Grid-Protection Directives:India's Central Electricity Authority mandates compel utility providers to deploy substation monitoring systems with redundant communication pathways.
- AI-Driven Predictive Analytics:Municipalities across the region are replacing rule-based alert systems with machine-learning threat models that reduce false-positive rates in urban surveillance.
Market Restraints
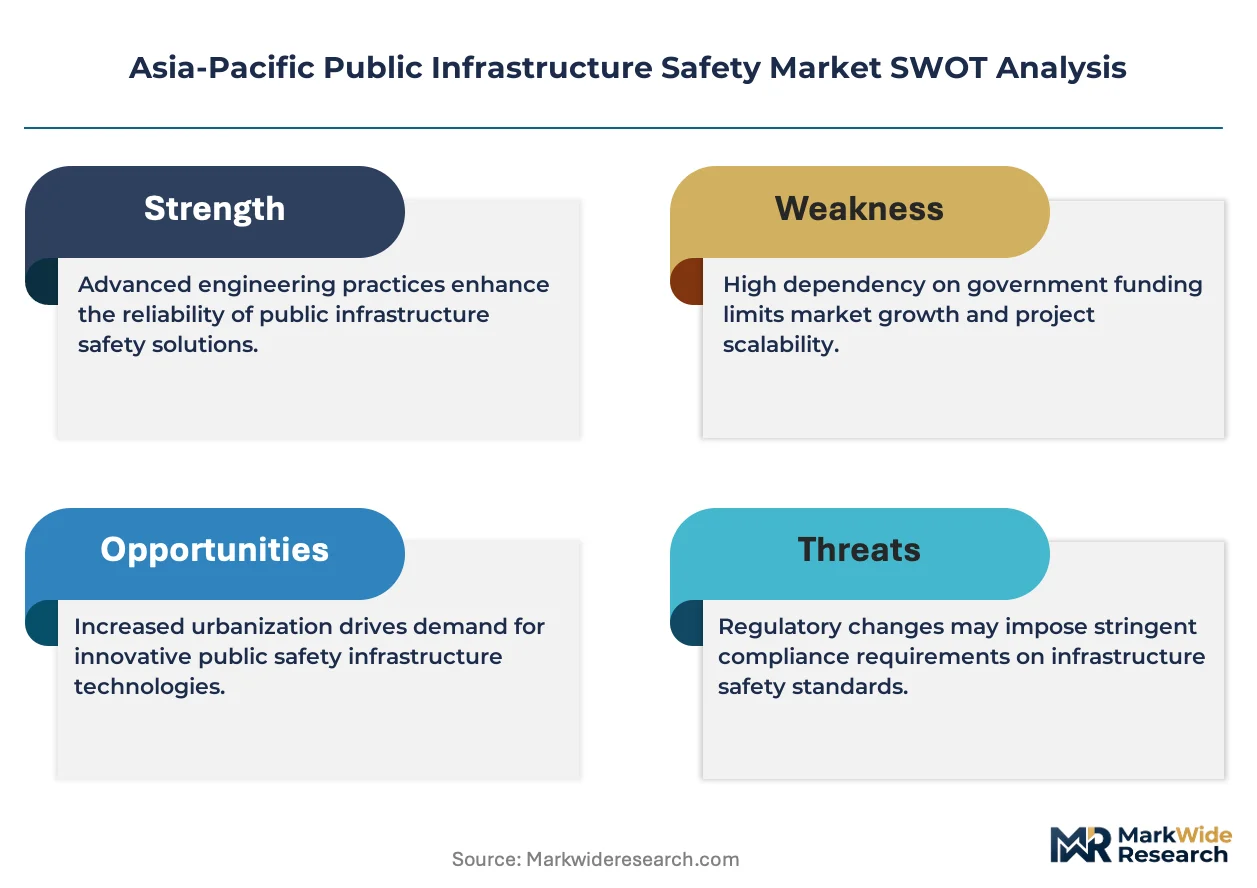
- Proprietary Platform Lock-In:Interoperability requirements clash with vendor-specific protocols, forcing buyers to accept captive maintenance ecosystems or absorb integration costs.
- Semiconductor Supply Concentration:Sensor network deployments face lead-time volatility from concentrated East Asian chip fabrication capacity.
- Essential Services Commission Reporting Burden:Australia's resilience disclosure mandates impose compliance overhead that stretches procurement timelines for mid-tier utilities.
Strategic Opportunities
- Vietnam's Smart City Corridors:Underpenetrated municipal safety infrastructure in secondary Vietnamese cities offers first-mover positioning for integrated platform vendors.
- Edge-Networking Convergence:Fusion of 5G private networks with AI inference at the sensor layer creates new product categories for low-latency incident response.
- Philippines Disaster Resilience Act:Regulatory tailwind mandates integrated early-warning systems across archipelago-critical infrastructure, opening framework-scale contracts.
Industry Challenges
- Cyber-Physical Systems Expertise Gap:Shortage of engineers capable of bridging operational technology and information security domains delays deployment timelines.
- Legacy SCADA Integration Friction:Brownfield utility environments require costly protocol translation layers to connect decades-old control systems with modern analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Public Infrastructure Safety Market |
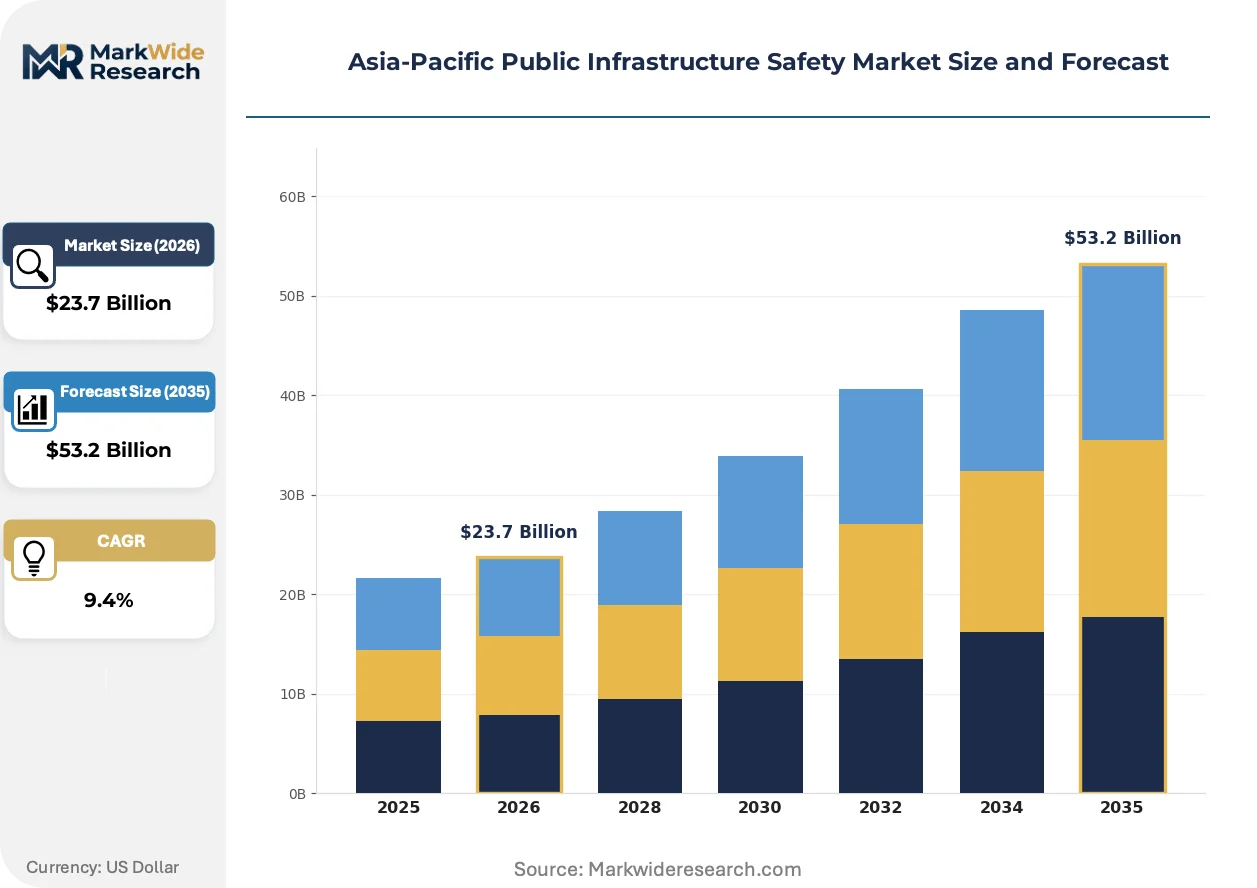
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Fire Safety Equipment, Intrusion Detection Systems, Emergency Communication Systems Service Type: Training Services, Consulting Services, Maintenance Services, Installation Services End User: Government Institutions, Transportation Authorities, Construction Firms, Utility Providers Technology: IoT Solutions, AI-Driven Analytics, Cloud-Based Systems, Mobile Applications |
| Companies Covered | Telefonaktiebolaget LM Ericsson, Motorola Solutions Inc, Cisco Systems Inc, L3Harris Technologies Inc, General Dynamics Corporation, Atos SE, Hexagon AB, Kaspersky Lab Inc, NEC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Public Infrastructure Safety Market Trends and Innovations
Digital twin architectures and edge-native AI are compressing incident-response latency from minutes to seconds across critical infrastructure networks. These shifts are redefining competitive advantage around real-time data orchestration rather than hardware durability.
Digital twin platforms are rewriting operational protocols for energy and transit operators by creating persistent virtual replicas of physical assets. Australian critical network operators are deploying these systems at scale to simulate failure cascades before they propagate. This capability is rewriting vendor selection criteria toward software-defined lifecycle management.
METI's industrial-security standards for critical infrastructure operators in Japan are mandating continuous monitoring architectures with sub-second anomaly detection. The regulation forces operators to retire periodic manual inspection regimes in favor of automated sensor grids. Energy distribution networks bear the heaviest compliance burden, accelerating procurement of integrated safety stacks.
Consolidated framework agreements are displacing single-city tenders across Southeast Asian procurement offices. Transportation authorities in Thailand and Indonesia now issue multi-jurisdiction contracts that bundle installation, decade-long maintenance, and technology refresh cycles. This pattern is most visible in metropolitan rail expansions where capital efficiency demands standardized platforms across provincial boundaries.
Asia-Pacific Public Infrastructure Safety Market Segmentation
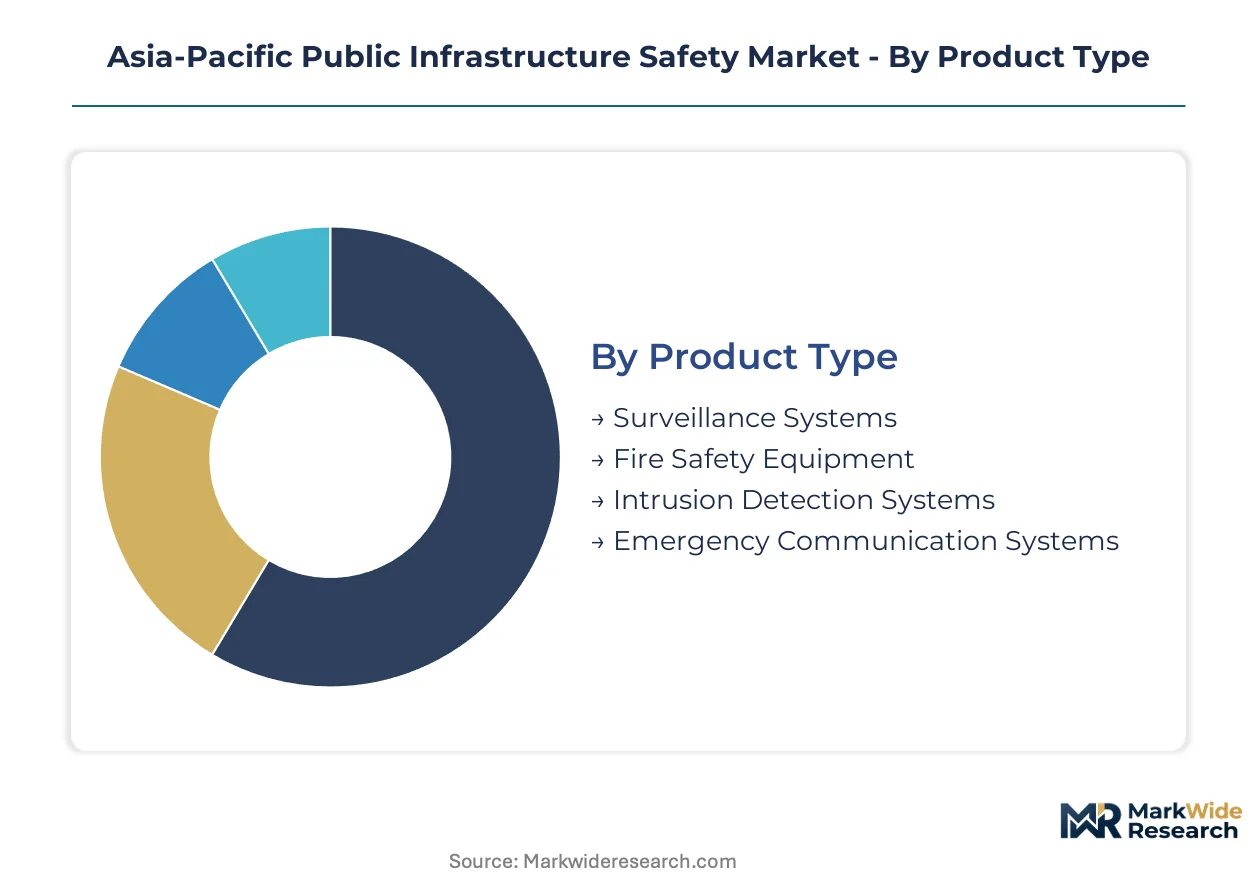
Segmentation in Asia-Pacific public infrastructure safety reveals distinct procurement patterns across hardware-intensive and service-recurring revenue streams. Capital allocation decisions diverge sharply between government institutions favoring integrated platforms and utility providers prioritizing point-solutions for legacy compatibility.
Product Type:
Capital intensity varies dramatically across physical infrastructure categories, with sensor networks and redundant communication pathways demanding the heaviest upfront investment.
- Surveillance Systems:Camera arrays with edge-computing nodes and sub-second latency transmission infrastructure form the backbone of urban monitoring networks. Indian metropolitan transit hubs and Australian energy networks concentrate procurement for these systems under multi-city framework agreements.
- Fire Safety Equipment:Suppression systems, detection sensors, and evacuation signaling hardware require specialized installation protocols across high-occupancy infrastructure. Demand clusters in Vietnam's emerging smart city corridors and Philippine commercial developments driven by disaster resilience mandates.
- Intrusion Detection Systems:Perimeter sensors and access control hardware secure critical substations and command centers.
- Emergency Communication Systems:Redundant radio networks and public address infrastructure enable coordinated incident response across distributed assets.
Surveillance Systems absorb the bulk of installed capacity; AI-Driven Analytics integration is expanding most quickly within this product category.
Service Type:
Revenue stability correlates directly with contract duration, creating divergent margin profiles across one-time implementation and decade-long maintenance obligations.
- Installation Services:System deployment, integration with legacy SCADA architectures, and commissioning protocols generate substantial upfront project revenue. Transportation authorities across Thailand and Indonesia bundle these services with technology refresh cycles under consolidated framework agreements.
- Maintenance Services:Preventive inspection, sensor calibration, and firmware updates sustain operational readiness across government institutions with extended procurement timelines. Australia's Essential Services Commission resilience reporting mandates compel utility providers to maintain rigorous service contracts.
- Training Services:Operator certification and emergency response protocol instruction ensure effective system utilization.
- Consulting Services:Risk assessment and compliance advisory support regulatory alignment for critical infrastructure operators.
Installation Services command the largest project-based revenue pools; Maintenance Services deliver the most predictable recurring income streams.
End User:
Procurement sophistication separates centralized government frameworks from fragmented private-sector purchasing, reshaping vendor go-to-market strategies.
- Government Institutions:National and municipal agencies issue multi-jurisdiction contracts standardizing safety platforms across provincial boundaries. India's National Infrastructure Pipeline urban resilience mandates are reshaping vendor priorities toward integrated command-center capabilities.
- Transportation Authorities:Rail, airport, and port operators require synchronized surveillance and emergency communication across distributed physical assets. Southeast Asian procurement consolidation is compressing sales cycles for vendors capable of anchoring large-scale transit deployments.
- Utility Providers:Electricity, water, and telecommunications operators face distinct regulatory compliance burdens for critical asset protection.
- Construction Firms:Project-phase safety system integration during infrastructure build-out creates episodic demand tied to development cycles.
Government Institutions dominate absolute procurement volume; Transportation Authorities are driving the steepest expansion trajectory through consolidated regional frameworks.
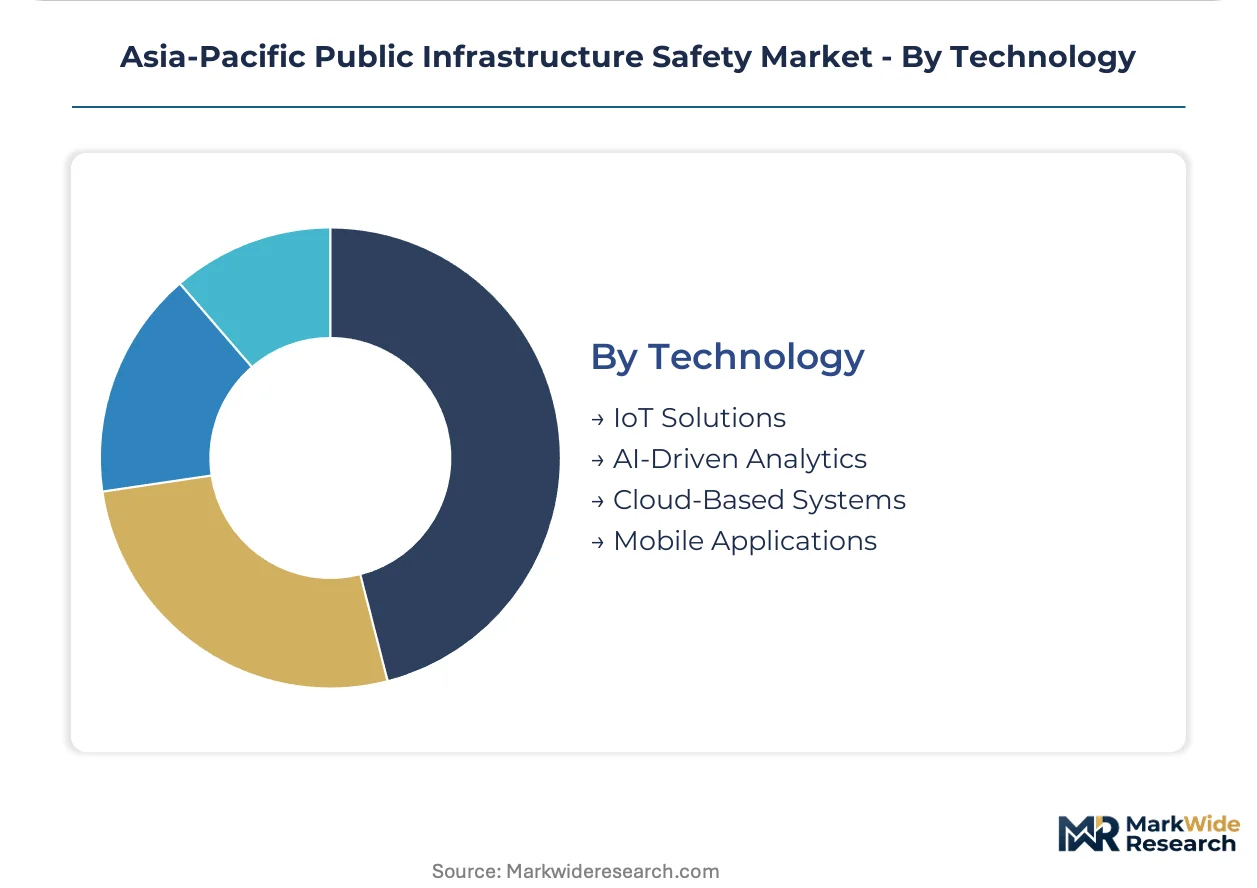
Technology:
Architecture choices between cloud-centric and edge-native deployments determine latency performance and cybersecurity exposure for critical infrastructure operators.
- AI-Driven Analytics:Machine-learning threat models replacing rule-based alert systems reduce false-positive rates in urban surveillance networks. Japanese energy distribution operators deploy these platforms to satisfy METI-mandated sub-second anomaly detection requirements.
- IoT Solutions:Distributed sensor grids with redundant communication pathways enable continuous monitoring of physical asset condition. India's CEA grid-protection directives compel substation monitoring upgrades incorporating these architectures.
- Cloud-Based Systems:Centralized data aggregation and remote management capabilities support multi-site operational visibility.
- Mobile Applications:Field operator interfaces and public alerting channels extend system accessibility beyond fixed command centers.
IoT Solutions anchor the majority of deployed sensor infrastructure; AI-Driven Analytics is climbing the fastest as municipalities modernize threat detection capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate shipments from Indonesian smelters feed sensor fabrication lines across East Asian electronics clusters. Rare earth processing nodes in southern China supply magnet components for motor drives in surveillance gimbals. Australian lithium spodumene underpins battery backup systems for redundant communication pathways.
India
Metropolitan transit hubs in Mumbai and Delhi are deploying integrated command-center platforms under the National Infrastructure Pipeline urban resilience mandates. The Central Electricity Authority compels utility providers to upgrade substation monitoring with redundant communication pathways. Gujarat and Maharashtra energy distribution networks are accelerating procurement of sensor grids to satisfy grid-protection directives.
Japan
Energy distribution operators in Tokyo and Osaka are retiring manual inspection regimes for automated sensor grids. METI enforces industrial-security standards mandating sub-second anomaly detection across critical infrastructure. Kansai region utilities are consolidating procurement of integrated safety stacks to meet continuous monitoring requirements.
Australia
Critical energy network operators are deploying digital twin architectures to simulate failure cascades before propagation. The Essential Services Commission mandates resilience reporting that stretches procurement timelines for mid-tier utilities. Queensland and New South Wales transmission operators are standardizing platforms across state boundaries under multi-jurisdiction contracts.
Vietnam
Secondary cities including Da Nang and Can Tho present underpenetrated municipal safety infrastructure for first-mover platform vendors. The country's national infrastructure regulator is aligning smart city corridor specifications with regional ASEAN standards. Ho Chi Minh City metro expansion is bundling installation services with decade-long maintenance obligations.
Thailand
Transportation authorities are consolidating fragmented municipal contracts into multi-city framework agreements covering Bangkok and provincial rail extensions. The national transport ministry compresses vendor sales cycles by standardizing procurement across provincial boundaries. Eastern Economic Corridor industrial zones are integrating surveillance backbones with 5G private network deployments.
Asia-Pacific Public Infrastructure Safety Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge-native AI inference and 5G private network convergence. The vendor base stratifies across three tiers: integrated platform providers anchoring multi-city framework agreements, point-solution specialists defending legacy SCADA compatibility positions, and telecom-centric players leveraging licensed spectrum assets. Dominant competitive moves include strategic partnerships between hardware fabricators and software orchestration layers, plus geographic expansion through local system integrator alliances.
Within the integrated platform tier, Motorola Solutions Inc and Cisco Systems Inc exemplify contrasting architectural philosophies. Motorola anchors large-scale transit deployments through command-center software footprints across Australian states. Cisco competes on edge-networking integration for urban surveillance backbones. Hexagon AB occupies a specialist position in geospatial incident-response platforms that dominate emergency-service dispatch protocols. These three represent the competitive archetypes shaping procurement outcomes: hardware-software bundling, network-centric infrastructure, and domain-specific analytics.
| Leading Market Players |
|---|
| Telefonaktiebolaget LM Ericsson |
| Motorola Solutions Inc |
| Cisco Systems Inc |
| L3Harris Technologies Inc |
| General Dynamics Corporation |
| Atos SE |
| Hexagon AB |
| Kaspersky Lab Inc |
| NEC Corporation |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed system integrators across Southeast Asia are consolidating procurement channels for command-center platforms, compressing vendor margins while elevating pricing power for those with decade-long maintenance lock-in. This ownership pattern tethers hardware pricing to bundled service obligations and creates captive revenue streams that outlast initial deployment cycles.
Pricing Analysis
Volume concentrates in standardized sensor networks while margins accrue to AI-driven analytics tiers. Three-tier pricing structure across premium command-center bundles, standard surveillance backbones, and economy-grade detection hardware separates multinational integrators from regional specialists. Cost compression in camera arrays and edge nodes is intensifying because semiconductor supply bottlenecks from concentrated East Asian fabrication capacity force buyers toward longer-term offtake contracts. Government institutions with consolidated framework agreements exhibit lowest price sensitivity; mid-tier utilities facing Essential Services Commission compliance overhead show highest sensitivity to upfront capital outlays.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale substation monitoring deployments across Indian states and Australian transmission networks. Geographic supply concentration centers on Taiwan and South Korea for sensor fabrication, Japan for precision optics in surveillance gimbals, and China for rare earth magnet components in motorized positioning systems. Raw material dependencies include copper concentrate from Indonesian smelters, Australian lithium spodumene for battery backup systems, and processed rare earth elements from southern China. Single-source vulnerability in advanced semiconductor nodes creates procurement risk for sub-second latency architectures. Distribution runs through national system integrators with sovereign certification for critical infrastructure access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor fabrication capacity constraints for edge-AI inference chips are propping pricing discipline across integrated platform tiers, making supply security the dominant commercial variable.
For Market Incumbents: Extend maintenance contract durations to capture recurring revenue streams that offset hardware margin compression from multi-city framework agreements. Anchor large-scale transit deployments through command-center software footprints that create switching costs for Australian state transportation authorities. Vertical integration into sensor calibration services defends against point-solution specialists competing on legacy SCADA compatibility. For New Entrants and Emerging Players: The Philippines Disaster Resilience Act opens a window for framework-scale early-warning system contracts across archipelago-critical infrastructure. Target Vietnam's secondary smart city corridors in Da Nang and Can Tho where municipal safety infrastructure remains underpenetrated and first-mover positioning is achievable. Lead with 5G private network convergence offerings that fuse edge-native AI with licensed spectrum assets, differentiating from established hardware-software bundlers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier system integrators with sovereign certification relationships in India and Southeast Asia. Long-term viability hinges on recurring maintenance revenue visibility rather than project-based installation exposure. The signal to watch is consolidation velocity among municipal procurement offices as fragmented single-city tenders compress into multi-jurisdiction framework agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Fusing command-center software with edge-AI inference layers reduces latency for METI-compliant anomaly detection. |
| Strategic Partnership | Alliances between hardware fabricators and 5G spectrum holders unlock private-network deployments in Thailand's Eastern Economic Corridor. |
| Acquisition of Specialist Firm | Geospatial analytics capabilities from regional players anchor emergency-service dispatch protocols against Hexagon AB dominance. |
| Geographic Expansion | Local integrator relationships in Vietnam and the Philippines secure framework-scale contracts under disaster resilience mandates. |
| Technology Licensing | Digital twin architectures licensed to Australian critical network operators simulate failure cascades before propagation. |
Research Methodology
Document review covered CEA grid-protection directives, METI industrial-security standards, Essential Services Commission resilience mandates, and ASEAN smart city corridor specifications, complemented by interviews with transportation authority procurement officers, utility planning directors, critical infrastructure security leads, and system integrator program managers. Secondary validation drew from customs data on sensor network imports, national infrastructure pipeline disclosures, and regulatory filing databases. Bottom-up deployment forecasts triangulated against top-down government capital allocation commitments.
Market sizing outputs reflect segment-level modeling across product type, service type, end user, and technology dimensions, with additional stratification by procurement mechanism and regulatory compliance tier. CAGRs were derived from elasticity-adjusted demand curves incorporating infrastructure investment cycles and technology refresh timelines. Forecast inputs included substation monitoring upgrade schedules under CEA mandates, metropolitan transit hub deployment pipelines under India's National Infrastructure Pipeline, and digital twin adoption curves across Australian critical energy networks.
Caveats apply where semiconductor supply disruptions, regulatory deadline extensions, or interoperability standard revisions could materially shift the outlook. Practitioners should monitor framework agreement award velocity, sovereign certification requirement changes, and edge-AI chip availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Critical Infrastructure Protection Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Global Perimeter Protection Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Hazardous Area Equipment Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market