
 Global High Integrity Pressure Protection System (HIPPS) Market | 2026-2036
Global High Integrity Pressure Protection System (HIPPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Integrity Pressure Protection System (HIPPS) Market Intelligence
Specialized component manufacturing for HIPPS in Germany is expanding to meet stringent safety integrity level (SIL) requirements. Emerson Electric leverages its extensive portfolio in final control elements and digital twins to serve complex oil and gas projects. Siemens differentiates through integrated logic solvers and automation systems, providing certified safety solutions for petrochemical facilities in Europe and Asia.
A High Integrity Pressure Protection System is an engineered, autonomous safety instrumented system designed to prevent catastrophic over-pressurization of pipelines and vessels. These systems achieve a high Safety Integrity Level, typically SIL 3, using redundant sensors, logic solvers, and final elements. While Oil & Gas Upstream projects command the highest specification requirements, demand is rising in Petrochemical Plant Protection. Valve-Based Technology forms the core of most installations, with sensor advancements improving diagnostic coverage.
Global functional safety standards, primarily IEC 61508 and IEC 61511, provide the foundational framework for HIPPS design and implementation. In the United States, EPA regulations indirectly mandate such protective systems in high-risk facilities, while Europe's Seveso III Directive serves a similar function. The critical decision for operators is how to verify system integrity throughout the asset lifecycle without prohibitive operational costs.
Market Dynamics
The market's central dynamic is the mandatory adherence to functional safety standards, primarily IEC 61511. This non-negotiable requirement for SIL 3 certification in high-pressure applications dictates component design, system architecture, and lifecycle management, making HIPPS a critical, non-discretionary expenditure.
Growth Catalysts
- Regulatory Mandates:Europe's Seveso III Directive and similar EPA regulations in the United States compel high-risk chemical and petrochemical facilities to implement verifiable protective systems, directly stimulating demand for certified HIPPS installations.
- Upstream Oil & Gas Expansion:The development of deepwater and ultra-deepwater hydrocarbon assets, particularly in the Gulf of Mexico and offshore Brazil, necessitates HIPPS to manage extreme pressures and protect subsea infrastructure.
- Infrastructure Investment:Major capital projects in the Middle East, including Saudi Arabia's expansion of its hydrocarbon processing and export facilities, create large-scale, specification-driven demand for high-integrity protection systems.
Market Restraints
- High Capital Cost:The significant upfront investment required for SIL 3 certified components and engineering services acts as a barrier, particularly for retrofitting aging facilities or for operators with constrained capital budgets.
- Proof Testing Complexity:Verifying the integrity of a HIPPS installation through its lifecycle without causing costly production shutdowns is a major operational constraint, increasing the total cost of ownership.
- Component Specialization:The market for critical HIPPS components, such as fast-acting valves and certified logic solvers, is highly concentrated among a few specialized manufacturers, creating potential supply chain vulnerabilities.
Strategic Opportunities
- Hydrogen Economy Infrastructure:The build-out of high-pressure hydrogen production, storage, and transportation networks presents a new, high-specification application vertical requiring advanced pressure protection systems from the ground up.
- Digitalization of Safety:Integrating HIPPS with digital twin technology offers the opportunity to conduct virtual proof testing and implement predictive maintenance, significantly reducing operational downtime and lifecycle costs for asset owners.
- Petrochemical Sector Growth in Asia:Rapid expansion of the petrochemical and LNG industries in Southeast Asian nations like Indonesia and Vietnam provides a significant opportunity as these countries upgrade their industrial safety standards.
Industry Challenges
- Functional Safety Skills Gap:A persistent shortage of certified functional safety engineers and technicians qualified to design, validate, and maintain systems according to IEC 61511 standards constrains project execution capacity.
- Legacy System Integration:Integrating modern, certified HIPPS with older, non-certified plant control and automation systems presents significant technical challenges, increasing project complexity and risk.
- Certification and Validation Delays:The lengthy and rigorous process of achieving SIL 3 certification for new system designs or components can slow the pace of innovation and deployment for vendors and operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Integrity Pressure Protection System (HIPPS) Market |
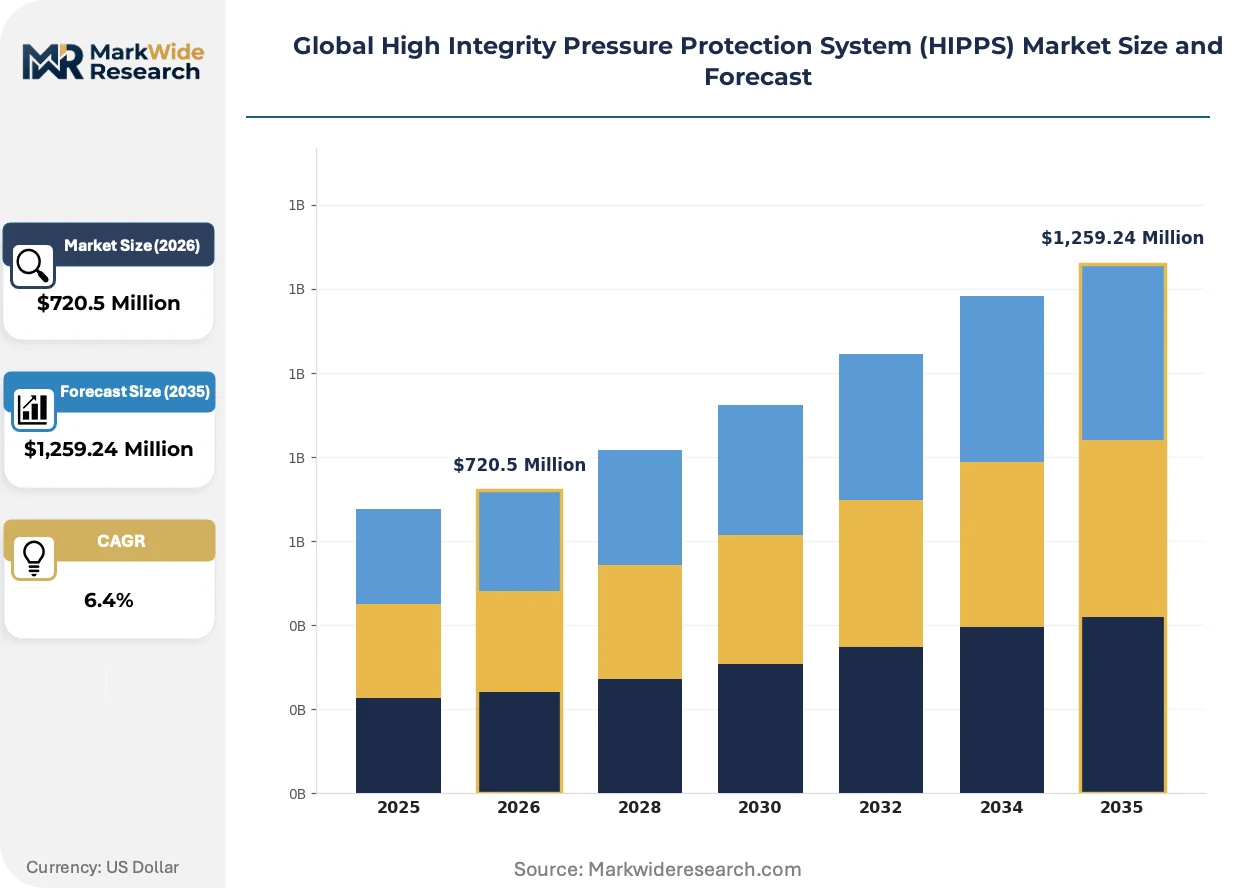
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,259.24 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical HIPPS, Electro-Mechanical HIPPS, Solid-State HIPPS, Hybrid System HIPPS Technology: Valve-Based Technology, Sensor-Based Technology, Logic Solver-Based Technology, Pressure Switch Technology Application: Oil & Gas Upstream, Oilfield Safety Controls, Refinery Pressure Safety, Petrochemical Plant Protection, Subsea Systems End User: Exploration Companies, E&P Operators, Petrochemical Manufacturers, Refining Companies, Offshore Operators |
| Companies Covered | Emerson Electric, Yokogawa Electric, Schneider Electric, Rockwell Automation, Siemens, Honeywell International, ABB, General Electric, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Integrity Pressure Protection System (HIPPS) Market Strategic Shifts & Innovations
The evolution of HIPPS is marked by a decisive shift from standalone hardware to intelligent, data-centric systems. This transition is aimed at enhancing not only catastrophic event prevention but also operational efficiency and predictive asset management throughout the system's lifecycle.
Advanced diagnostic capabilities are being integrated directly into smart sensors, actuators, and valve positioners. These components provide real-time health monitoring and partial stroke testing data without requiring a full system trip. Oil & Gas Upstream and large-scale chemical operators are the primary adopters for their most critical assets. This embedded intelligence is absorbing the function of separate, bolt-on diagnostic equipment and manual inspection routines, shifting value towards software-driven analytics.
Global standards like IEC 61508 and IEC 61511 are driving a greater focus on the entire safety lifecycle beyond initial commissioning. This evolution requires asset owners to provide verifiable proof of system integrity and personnel competency over decades. The European Union's Seveso III Directive most clearly affects operators in the chemical sector, mandating comprehensive safety management systems and documentation that force investment in lifecycle tools and training.
A distinct shift in purchasing models is evident, moving from the procurement of discrete components to sourcing fully engineered, skid-mounted HIPPS packages. This trend favors large automation vendors capable of guaranteeing end-to-end SIL performance and providing a single point of responsibility. The preference for these turnkey solutions is most pronounced in complex, schedule-driven LNG projects in geographies like Qatar and Australia.
Global High Integrity Pressure Protection System (HIPPS) Market Segmentation
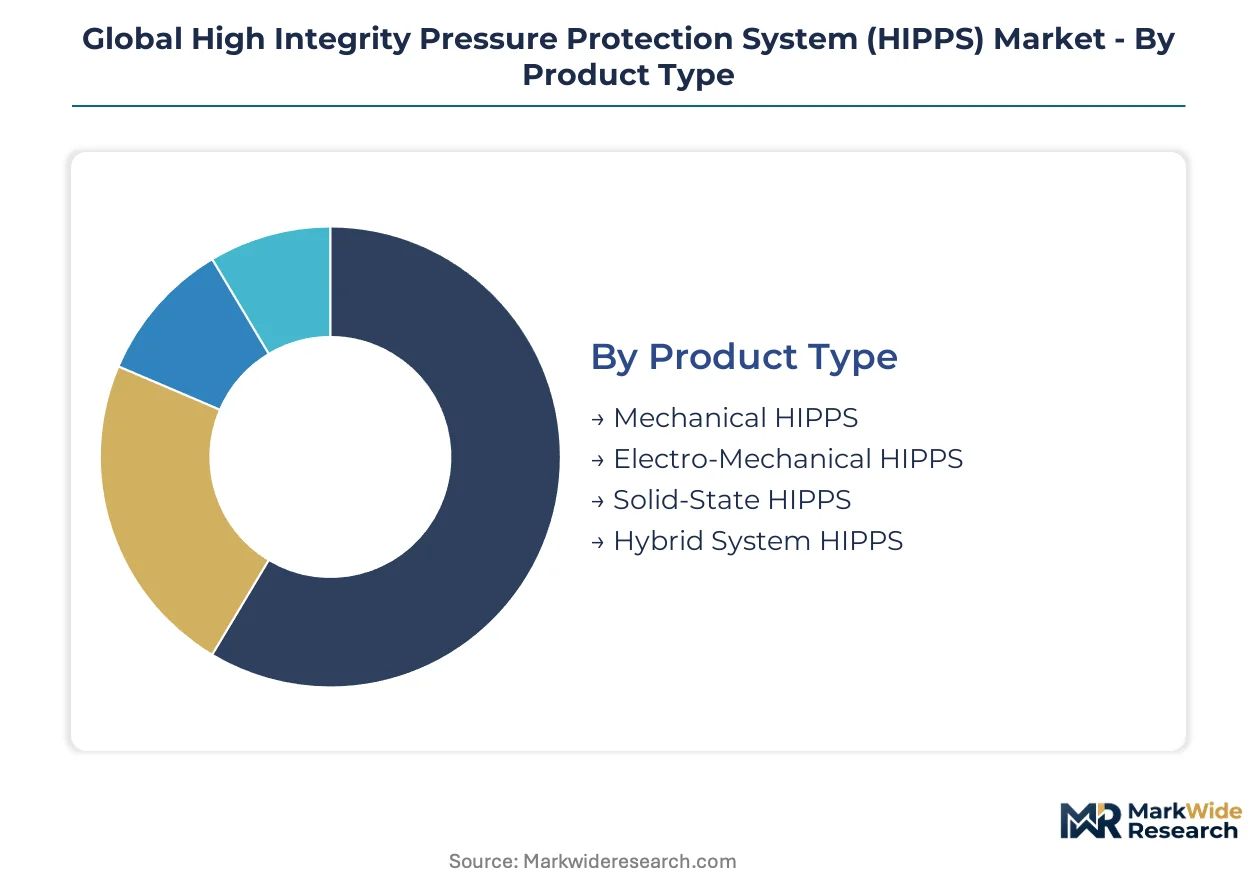
The Global High Integrity Pressure Protection System (HIPPS) Market is segmented to provide a granular view of demand drivers and technological preferences across various industrial applications. This detailed breakdown helps in understanding the specific needs and compliance requirements that shape purchasing decisions for these critical safety systems.
Product Type:
Supply concentration in the HIPPS product type segment reflects specialized manufacturing capabilities required for safety-critical components.
- Electro-Mechanical HIPPS:These systems integrate electrical control logic with mechanical final elements, offering a balance of reliability and diagnostic capabilities. Demand is strong in deepwater oil and gas operations, where remote monitoring and precise control are essential for asset protection.
- Solid-State HIPPS:Utilizing fully electronic components and programmable logic, these systems offer rapid response times and advanced self-diagnostic features. Petrochemical facilities in Europe are adopting solid-state solutions to meet stringent Seveso III Directive compliance for process safety.
- Mechanical HIPPS:These systems rely on purely mechanical components, such as self-actuated valves, for pressure protection without external power sources.
- Hybrid System HIPPS:Combining elements of mechanical, electro-mechanical, and solid-state designs, these systems offer tailored solutions for specific application requirements.
Mechanical HIPPS absorbs the bulk of installed capacity; Hybrid System HIPPS is expanding most quickly.
Technology:
The market for HIPPS technology is highly influenced by the specific application requirements, driving differentiation in system architecture.
- Valve-Based Technology:This core technology employs specialized, fast-acting valves as the final element to isolate pressure sources, forming the foundation of most HIPPS installations. Upstream oil and gas projects in the Gulf of Mexico prioritize valve-based systems for their proven reliability in extreme conditions.
- Sensor-Based Technology:Advanced sensors provide the critical input for HIPPS logic solvers, offering high accuracy and diagnostic coverage for pressure and flow. Petrochemical facilities in Southeast Asia are increasingly investing in sophisticated sensor arrays to enhance early detection and prevent incidents.
- Logic Solver-Based Technology:These systems utilize programmable electronic safety systems or relay-based logic to process sensor inputs and activate final elements.
- Pressure Switch Technology:Simple and robust, pressure switches act as direct input devices, triggering safety actions when a predefined pressure threshold is exceeded.
Innovations in sensor and logic solver technologies are continuously enhancing the diagnostic capabilities and response times of modern HIPPS installations.
Application:
Customer operational models and risk profiles heavily influence the type and complexity of HIPPS applications deployed across various industrial settings.
- Oil & Gas Upstream:This segment involves protecting high-pressure wells, pipelines, and subsea equipment from over-pressurization, particularly in deepwater exploration. Operators in offshore Brazil demand highly specialized HIPPS for their ultra-deepwater assets.
- Petrochemical Plant Protection:HIPPS safeguards critical reactors, vessels, and processing units in chemical plants against runaway reactions or pressure excursions. European chemical manufacturers are mandated by the Seveso III Directive to implement robust protective measures.
- Oilfield Safety Controls:These applications focus on general safety within oilfield operations, including wellhead control and emergency shutdown systems.
- Refinery Pressure Safety:HIPPS ensures the safe operation of distillation columns, reformers, and other high-pressure units within petroleum refineries.
- Subsea Systems:These specialized HIPPS installations are designed for underwater environments, protecting subsea pipelines and production equipment from extreme pressures.
The need for fail-safe operation in high-risk environments drives consistent investment in HIPPS across all application areas.
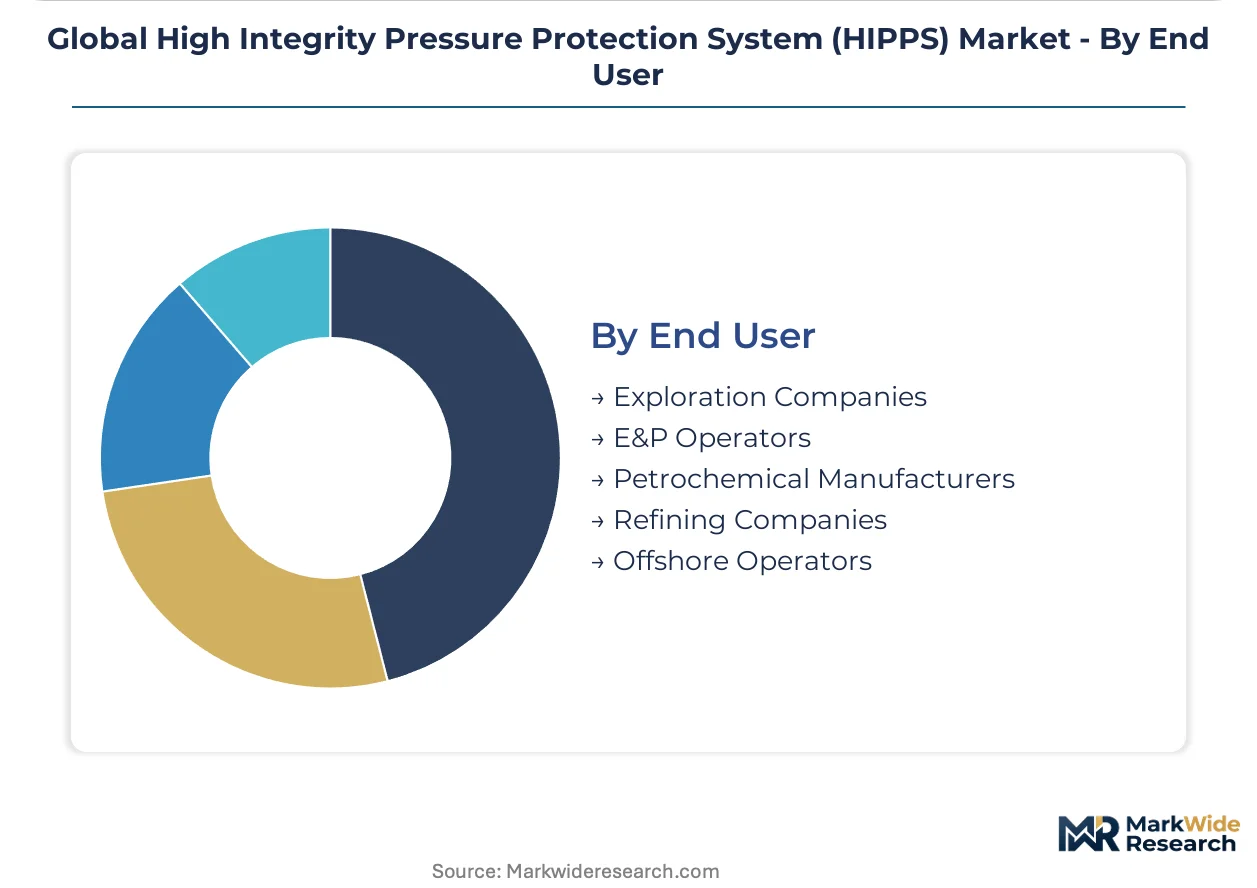
End User:
The maturity level of industrial infrastructure significantly shapes the procurement and deployment patterns for HIPPS among different end-user groups.
- E&P Operators:These companies manage the exploration and production of hydrocarbons, requiring HIPPS for wellhead protection, subsea systems, and pipeline integrity. Major E&P firms in Saudi Arabia are driving large-scale HIPPS deployments for new field developments.
- Petrochemical Manufacturers:Firms producing chemicals and plastics rely on HIPPS to prevent over-pressurization in reactors, storage tanks, and process lines. Compliance with EPA regulations in the United States necessitates advanced safety systems in these facilities.
- Exploration Companies:These entities focus on identifying new hydrocarbon reserves, often utilizing portable or temporary HIPPS for testing and appraisal activities.
- Refining Companies:Operators of oil refineries employ HIPPS to ensure the safe and continuous operation of their complex processing units.
- Offshore Operators:Companies managing offshore platforms and subsea infrastructure represent a specialized segment with unique requirements for marine-grade HIPPS.
Regulatory compliance and the imperative to protect personnel and assets remain paramount for all end-user segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's extensive hydrocarbon processing infrastructure anchors significant regional demand for High Integrity Pressure Protection Systems. This imperative to protect high-value assets and ensure operational safety drives substantial investment across diverse geographies. Strict regulatory frameworks globally reinforce the need for certified safety solutions in critical industrial applications.
United States
Deepwater and ultra-deepwater hydrocarbon asset development in the Gulf of Mexico necessitates specialized HIPPS for extreme pressures. EPA regulations indirectly mandate protective systems in high-risk facilities, compelling operators to implement advanced safety measures. The Houston energy corridor drives innovation in subsea control systems and pressure protection.
Saudi Arabia
Major capital projects in Saudi Arabia, particularly expanding hydrocarbon processing and export facilities, create large-scale demand for high-integrity protection systems. The Kingdom's national oil company mandates stringent safety standards for new field developments and infrastructure upgrades. Industrial hubs like Jubail see consistent HIPPS deployments for petrochemical and refining.
Germany
Specialized component manufacturing for HIPPS in Germany expands to meet stringent Safety Integrity Level (SIL) requirements for petrochemical facilities. Europe's Seveso III Directive compels high-risk chemical plants to implement verifiable protective systems, stimulating demand. The Rhine-Ruhr region, with its dense chemical industries, drives adoption of solid-state HIPPS.
Brazil
The development of ultra-deepwater hydrocarbon assets offshore Brazil necessitates highly specialized HIPPS to manage extreme pressures in subsea infrastructure. ANP regulations govern safety and operational integrity of offshore oil and gas production, requiring robust pressure protection. The Campos Basin and pre-salt regions remain focal points for advanced subsea HIPPS.
Indonesia
Rapid expansion of the petrochemical and LNG industries in Indonesia provides significant opportunity as the country upgrades industrial safety standards. National energy and industry regulators increasingly emphasize functional safety compliance for new and existing facilities. Industrial zones around Jakarta invest in sophisticated sensor arrays and logic solvers for enhanced detection.
Global High Integrity Pressure Protection System (HIPPS) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue integrated digital safety solutions. The market exhibits a tiered structure, with specialized component manufacturers at one end and large automation vendors offering turnkey solutions at the other. Strategic archetypes include niche component specialists, comprehensive system integrators, and software-centric service providers. Dominant competitive moves involve strategic partnerships for end-to-end solutions and continuous portfolio diversification to meet evolving safety standards.
Large automation vendors, capable of guaranteeing end-to-end SIL performance and providing a single point of responsibility, anchor the comprehensive solution segment. Emerson Electric, a US-based corporation, exemplifies this archetype with its extensive portfolio in final control elements and digital twins for complex oil and gas projects. Siemens AG, a German-based company, differentiates through integrated logic solvers and automation systems, providing certified safety solutions for petrochemical facilities. Honeywell International Inc., another US-based firm, occupies a similar position, leveraging its broad industrial automation and control systems expertise to offer integrated HIPPS solutions.
| Leading Market Players |
|---|
| Emerson Electric |
| Yokogawa Electric |
| Schneider Electric |
| Rockwell Automation |
| Siemens |
| Honeywell International |
| ABB |
| General Electric |
| Baker Hughes |
| Others |
Cost & Logistics Intelligence
Specialized component costs, particularly for SIL 3 certified valves, influence the project-based pricing for High Integrity Pressure Protection System installations. This upstream cost structure dictates downstream system integration and service contract values across the market. Supply chain vulnerabilities for these critical components can also impact overall system pricing and project timelines.
Pricing Analysis
Bundled warranty and long-term maintenance contracts often define the total cost of ownership for HIPPS solutions. The dominant pricing structure is project-based, reflecting the bespoke engineering required for each installation. Certification level, specifically SIL 3, and customization for deepwater applications are key differentiation drivers. Pricing softness emerges from increased competition among system integrators. Petrochemical facilities operating under strict budget constraints show higher price sensitivity than large E&P operators.
Supply Chain Analysis
Direct sales channels, often through large automation vendors, handle the complex procurement of HIPPS solutions. Supply concentration for critical components like fast-acting valves and certified logic solvers resides primarily in Germany and the United States. Raw material dependencies include high-grade stainless steel for valves and specialized electronics for logic solvers. Single-source vulnerability for specialized SIL 3 components poses a structural risk. Distribution runs through a network of authorized system integrators and EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HIPPS market is witnessing a vertical-integration race, as players pursue end-to-end control over certified component manufacturing and system integration. This drive optimizes project delivery and guarantees functional safety throughout the asset lifecycle.
For Market Incumbents: Deploy digital twin integration to enhance predictive maintenance and virtual proof testing capabilities. This move mitigates the threat from new entrants offering software-centric solutions and reinforces lifecycle service revenue. Consolidate specialized component manufacturers to secure supply chains for SIL 3 certified valves. Investment in advanced sensor R&D ensures diagnostic coverage leadership.
For New Entrants and Emerging Players: Specialized engineering firms represent a key channel partner for entering the HIPPS market, particularly for niche applications. Target the rapidly expanding petrochemical sector in Southeast Asia, focusing on compliance-driven upgrades. Offer modular, solid-state HIPPS packages with simplified integration for facilities with legacy systems. A go-to-market angle emphasizing rapid deployment and lower total cost of ownership can gain traction.
For Investors and Strategic Acquirers: The build-out of hydrogen economy infrastructure is the leading indicator that new high-pressure protection system demand will surge in the long term. This market offers stable returns over a 5-10 year window, driven by non-discretionary safety spending. Target mid-sized system integrators with strong functional safety engineering capabilities for acquisition. Monitor global regulatory updates for new industrial safety mandates as a key signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen functional safety engineering expertise | Addresses the skills gap and enhances project execution capacity for complex HIPPS installations. |
| Acquire specialized component manufacturers | Secures critical supply for SIL 3 certified valves and logic solvers against potential vulnerabilities. |
| Expand digital twin integration services | Offers asset owners reduced operational downtime and lower lifecycle costs through predictive maintenance. |
| Target hydrogen infrastructure projects | Positions the company for early leadership in a nascent, high-growth application vertical for pressure protection. |
| Form strategic alliances with EPC contractors | Facilitates turnkey HIPPS project delivery, especially for large-scale LNG and petrochemical facilities. |
Research Approach
Document review covered regulatory filings, industry association reports, and technical publications, complemented by interviews with functional safety engineers, plant managers, and procurement leads. Primary research involved discussions with HIPPS component manufacturers and system integrators. This approach combined bottom-up market sizing with top-down validation against macroeconomic indicators and project databases.
Market projections for HIPPS demand were generated using a multi-factor analytical framework across the modeling period. Segmentation dimensions included product type, technology, application, and end-user, alongside regional regulatory compliance levels. Compound annual growth rates were derived from historical trends, projected capital expenditures, and anticipated safety standard upgrades. Key forecast inputs included deepwater drilling forecasts and petrochemical plant expansion plans.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and drastic commodity price fluctuations. Forecasts reflect assumptions documented regarding technological advancements and regulatory enforcement. Practitioners should monitor global energy transition policies and regional industrialization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Advanced Persistent Threat (APT) Protection Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Asia Pacific Tank Protection Market
Critical Infrastructure Protection
Blast Resistant and Bulletproof Buildings Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Insider Threat Protection Market