
 Tank Protection Market | 2026-2036
Tank Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Tank Protection Market Analytics
API 653 certification is bifurcating the competitive landscape between qualified tank maintenance providers and uncertified contractors. Saint-Gobain leverages its materials science portfolio to dominate high-performance coating formulations for corrosive chemical environments. Owens Corning anchors its position through fiberglass-reinforced technology leadership in industrial tank construction. Rockwool International A/S specializes in fire-resistant insulation systems that meet stringent petrochemical safety protocols.
Tank protection encompasses engineered systems—coatings, liners, barriers, and structural tanks—designed to prevent corrosion, leakage, thermal loss, and catastrophic failure in liquid and gas storage vessels, typically employing polymer composites, elastomeric membranes, or mineral wool insulations rated for chemical resistance and temperature extremes from minus 40°C to 300°C. The technology dimension segments into polyurethanes, epoxy, PVC, and fiberglass, with epoxy formulations commanding the largest installed base due to their adhesion properties and solvent resistance, while fiberglass-reinforced systems represent the fastest-growing category as operators seek extended service intervals in aggressive chemical storage. Application demand concentrates in oil and gas and chemical storage, where regulatory mandates and asset integrity programs drive replacement cycles at higher margins than industrial water treatment.
EPA regulations under the Spill Prevention, Control, and Countermeasure program and OSHA process safety management standards shape product specifications and inspection frequencies for aboveground storage tanks in the United States, while REACH compliance in Europe restricts certain coating chemistries and drives reformulation investments. Stakeholders must monitor evolving carbon border adjustments and bio-based material certifications that will redefine supplier qualification criteria and capital allocation for tank protection upgrades.
Market Dynamics
Asset integrity mandates from EPA and API are compressing replacement cycles while chemical storage operators demand extended service intervals, creating tension between compliance-driven maintenance and capital efficiency goals.
Growth Catalysts
- API 653 Inspection Mandates:Certification requirements force tank farm operators to upgrade aging infrastructure, generating sustained demand for qualified coating applicators and inspection services across the US Gulf Coast.
- Fiberglass-Reinforced Technology:Extended corrosion resistance in aggressive chemical environments drives substitution away from conventional steel tanks in sulfuric acid and caustic soda storage applications.
- US Gulf Coast Petrochemical Corridor:Concentrated capacity expansions by ethylene and methanol producers create localized demand surges for fire-resistant insulation and secondary containment systems.
Market Restraints
- Epoxy Resin Input Volatility:Bisphenol-A and amine hardener prices fluctuate with crude oil derivatives, squeezing formulation margins for coating manufacturers serving price-sensitive municipal water markets.
- Qualified Applicator Scarcity:NACE and SSPC certification pipelines cannot match retirement rates, constraining project execution velocity for large-diameter tank recoating programs.
- Mineral Wool Substitution Risk:Aerogel and cellular glass insulations capture share in cryogenic LNG storage where thermal performance specifications exceed conventional rockwool ratings.
Strategic Opportunities
- Carbon Border Adjustment Mechanism:EU importers of Chinese and Indian tank components face embedded emissions tariffs, creating openings for domestic European coating and insulation suppliers with verified low-carbon production.
- Hydrogen Storage Infrastructure:High-pressure composite tanks and specialized barrier systems for liquid hydrogen present unpenetrated application space as European hydrogen backbone projects advance.
- Digital Inspection Integration:UAV-based ultrasonic thickness monitoring and AI-assisted corrosion mapping converge with traditional API 653 protocols, enabling predictive maintenance service models.
Industry Challenges
- API 653 Certification Bottlenecks:Examination backlogs and experience hour requirements delay inspector qualification, throttling contractor capacity to bid on federal and state-mandated tank rehabilitation projects.
- Legacy Coating System Compatibility:Surface preparation protocols for new high-solids epoxy formulations conflict with existing tank substrate conditions, complicating recoat specifications and warranty terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tank Protection Market |
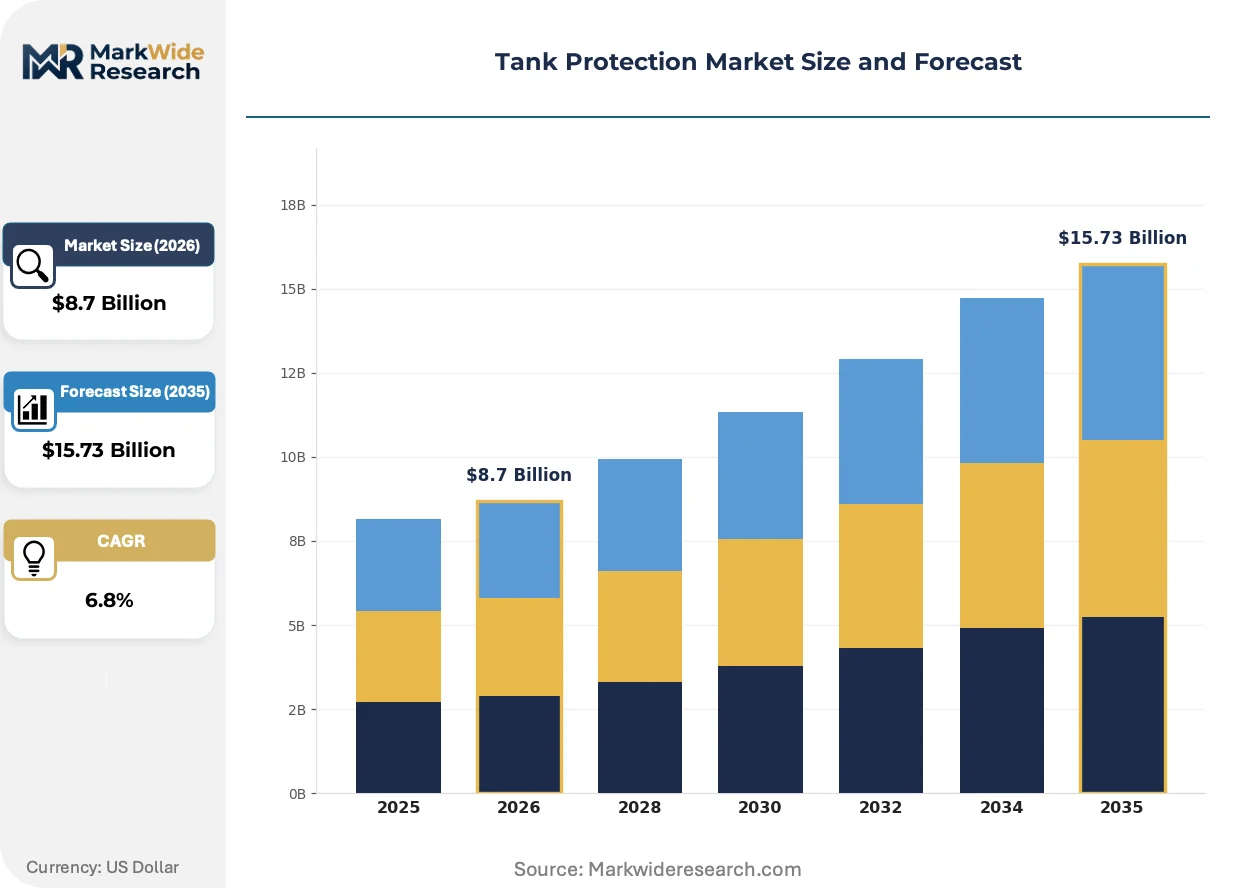
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Liners, Barriers, Tanks Application: Industrial, Oil & Gas, Water Treatment, Chemical Storage End User: Manufacturers, Contractors, Utilities, Distributors Technology: Polyurethanes, Epoxy, PVC, Fiberglass |
| Companies Covered | Saint Gobain, Rockwool International A/S, Owens Corning, Kingspan Group, Armacell International SA, Archtech Building Systems, Kumtek Thermotech, Roechling Group, Yutaka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tank Protection Market Evolving Landscape
Material science advances and inspection digitization are compressing traditional maintenance paradigms while regulatory tightening forces specification upgrades across chemical storage infrastructure.
Polyurea spray-applied linings is fragmenting the tank lining market by enabling rapid return-to-service protocols that conventional epoxy curing schedules cannot match. Chemical processors with batch-operated vessels adopt polyurea for turnaround windows under 72 hours. The technology is fragmenting project bidding structures as specialized spray contractors displace generalist applicators who lack plural-component equipment and heated hose capabilities.
EPA's Spill Prevention, Control and Countermeasure program amendments tighten secondary containment and integrity testing frequencies for facilities exceeding threshold storage volumes. Tank farm operators must install impermeable liners and leak detection systems or face escalating civil penalties. Aboveground storage terminals in the Houston Ship Channel and Corpus Christi regions accelerate capital deployment to meet phased compliance deadlines.
Specification authority is migrating from procurement departments to reliability engineering functions as total cost of ownership models displace first-cost bidding for tank protection contracts. Major chemical producers unbundle coating supply from application services, selecting materials based on predicted service life rather than unit price. This pattern concentrates in North American petrochemical complexes where unplanned tank outages carry downstream production penalties exceeding material cost differentials.
Tank Protection Market Segmentation
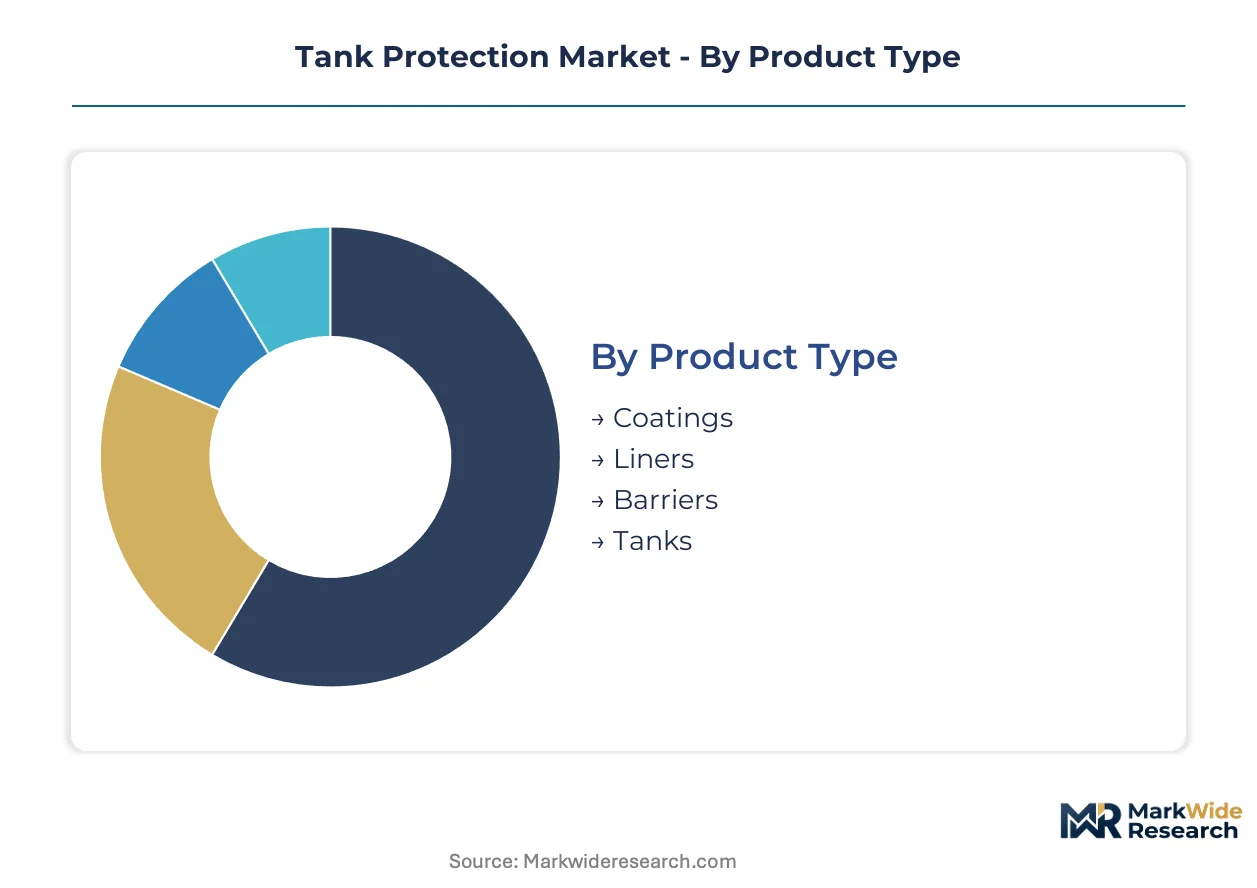
Segmentation in tank protection reveals how regulatory pressure and asset integrity economics fragment demand across material technologies and end-use applications. Understanding these divides helps suppliers align certification investments with the highest-margin specification tiers.
Product Type:
EPA spill prevention mandates and API 653 inspection standards differentiate product specifications by containment criticality, with secondary containment systems facing stricter impermeability testing than primary vessel coatings.
- Coatings:High-solids epoxy and polyurethane formulations dominate external tank protection, with solvent resistance specifications tightening for chemical storage facilities along the US Gulf Coast under EPA SPCC amendments. Demand concentrates in recoating cycles triggered by API 653 thickness inspection failures, where qualified applicator scarcity extends project timelines.
- Liners:Elastomeric membranes and polymer sheets provide internal corrosion barriers for existing steel tanks, enabling service extension without vessel replacement. Chemical processors in sulfuric acid storage favor fluoropolymer-lined systems for their extended service intervals compared to unlined carbon steel alternatives.
- Barriers:Impermeable liners and secondary containment systems satisfy EPA SPCC requirements for facilities exceeding threshold storage volumes. Installation accelerates in Houston Ship Channel terminals facing phased compliance deadlines.
- Tanks:Fiberglass-reinforced and dual-laminate vessels substitute for steel in aggressive chemical environments. Extended corrosion resistance drives adoption in caustic soda and chlorine storage applications where metal fatigue risks dominate total cost of ownership calculations.
Established volume favors coatings; emerging adoption favors tanks.
Application:
Cost tier differentiation separates specification-intensive chemical storage from price-sensitive municipal water markets, with petrochemical applications commanding premium material grades and certified installation protocols.
- Oil & Gas:Aboveground storage terminals require fire-resistant insulation and secondary containment under OSHA process safety management standards. US Gulf Coast capacity expansions concentrate demand for qualified coating applicators and inspection services.
- Chemical Storage:Aggressive chemistries drive specification toward fiberglass-reinforced systems and fluoropolymer linings with temperature ratings exceeding 150°C. Asset integrity programs at ethylene and methanol producers prioritize predictive maintenance over first-cost bidding.
- Industrial:Manufacturing facilities balance regulatory compliance against capital efficiency, with batch-operated vessels adopting polyurea spray linings for rapid return-to-service protocols under 72 hours.
- Water Treatment:Municipal and industrial water systems face budget constraints that favor conventional epoxy coatings over advanced barrier systems, though EPA lead and copper rules are tightening potable water tank lining specifications.
Margin concentration sits with chemical storage; volume scale favors industrial applications.
End User:
Procurement authority migration from purchasing departments to reliability engineering functions reshapes supplier relationships, with specification ownership shifting toward technical stakeholders who prioritize predicted service life over unit pricing.
- Contractors:NACE and SSPC certified applicators control project execution velocity for large-diameter tank recoating programs. Certification backlogs constrain capacity to bid on federal and state-mandated rehabilitation projects.
- Manufacturers:Chemical producers unbundle coating supply from application services, selecting materials based on total cost of ownership models that quantify unplanned outage penalties against material cost differentials.
- Utilities:Municipal water authorities face procurement regulations that favor lowest-bid awards, compressing margins for coating suppliers while creating specification gaps between regulatory minimums and asset integrity best practices.
- Distributors:Regional material distributors serve fragmented maintenance contractor markets, with inventory positioning determined by local API 653 inspection cycle timing and petrochemical turnaround schedules.
Specification authority favors manufacturers; execution capacity concentrates with contractors.
Technology:
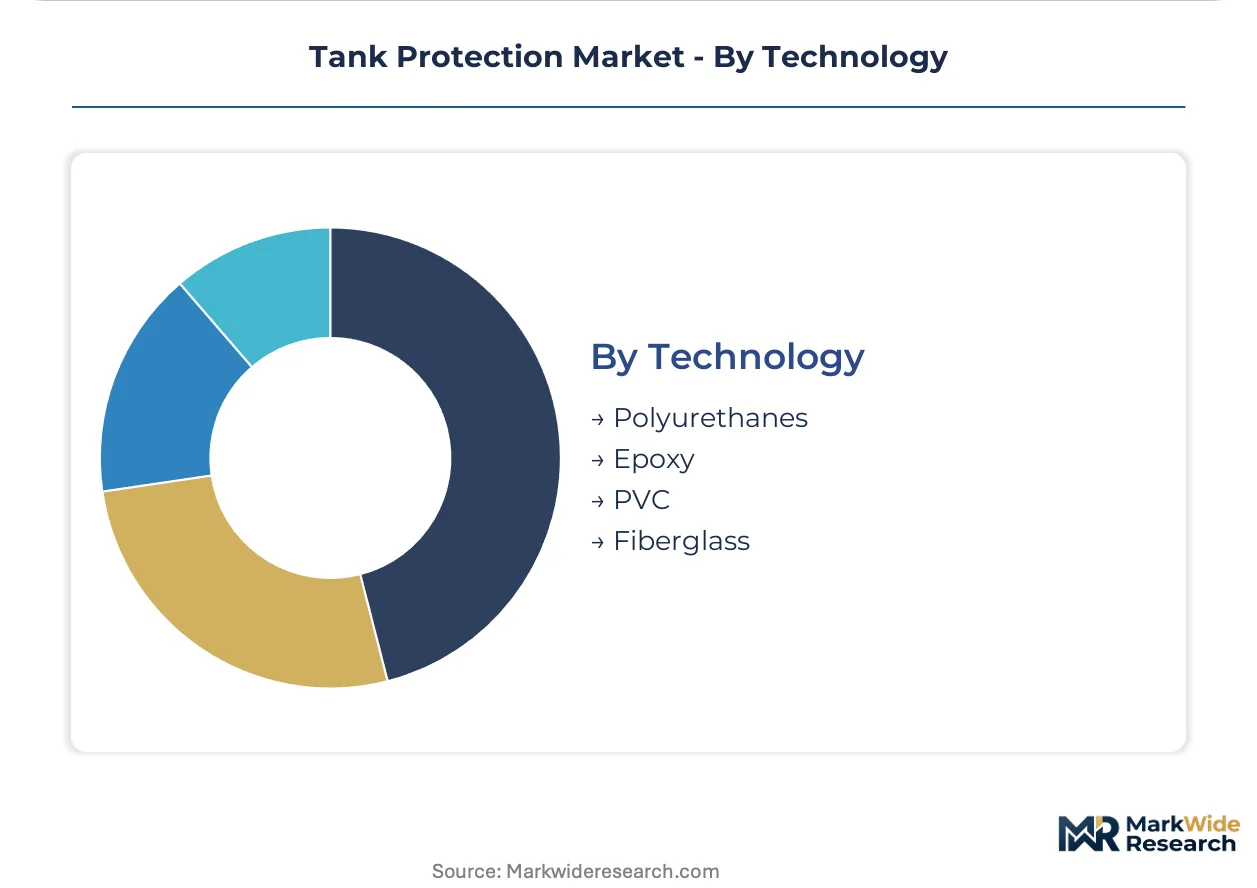
Maturity gradients separate established epoxy formulations with proven adhesion protocols from emerging fiberglass systems requiring new substrate preparation standards and warranty frameworks.
- Epoxy:Amine-cured and phenolic formulations command the largest installed base due to established surface preparation protocols and broad chemical resistance profiles. Bisphenol-A price volatility squeezes margins in price-sensitive municipal markets.
- Fiberglass:Filament-wound and contact-molded reinforced plastic systems gain share in new tank construction and aggressive chemical replacement applications. Owens Corning anchors technology leadership through corrosion-resistant resin formulations.
- Polyurethanes:Aliphatic and aromatic formulations serve external weathering protection and internal abrasion-resistant linings. Demand concentrates in railcar and portable tank applications requiring flexibility under thermal cycling.
- PVC:Thermoplastic liners and dual-laminate construction provide cost-effective corrosion barriers for moderate chemical environments. Specification limits in high-temperature applications constrain adoption above 60°C service conditions.
Installed base dominance favors epoxy; steepest expansion trajectory belongs to fiberglass.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA spill prevention mandates and API 653 inspection standards in the United States combine with REACH compliance pressures in Europe and carbon border adjustments in Asia to reshape regional demand patterns for tank protection systems.
United States
API 653 certification requirements and EPA SPCC amendments drive recoating cycles at aboveground storage terminals. OSHA process safety management standards mandate fire-resistant insulation for petrochemical facilities. The Houston Ship Channel and Corpus Christi regions accelerate capital deployment for secondary containment upgrades ahead of phased compliance deadlines.
Germany
REACH restrictions on coating chemistries force reformulation investments among suppliers serving chemical storage operators. The EU Green Deal and carbon border adjustment mechanism create openings for domestic coating producers with verified low-carbon production. The Rhine-Ruhr industrial corridor and Ludwigshafen chemical complex concentrate demand for high-performance barrier systems.
China
Dual carbon goals and tightening environmental standards under MEE supervision accelerate tank farm modernization at state-owned refineries. GB standards for chemical storage infrastructure tighten impermeability testing protocols. The Yangtze River Delta and Pearl River Delta petrochemical clusters drive localized demand for fiberglass-reinforced tank systems.
Saudi Arabia
Vision 2030 industrial diversification and SABIC capacity expansions generate demand for corrosion-resistant storage infrastructure. The national chemical regulator mandates asset integrity programs for aboveground tanks at Jubail and Yanbu industrial cities. The Eastern Province concentrates new ethylene and methanol storage terminal construction.
India
Petrochemical capacity additions under the PLI scheme and tightening Central Pollution Control Board norms drive adoption of advanced coating systems. BIS certification requirements for chemical storage tanks compress replacement cycles. The Gujarat chemical belt and Maharashtra industrial corridor anchor demand for qualified tank maintenance providers.
Tank Protection Market Competitive Landscape
Player mix skews toward materials science conglomerates with cross-industrial coating portfolios and specialized insulation manufacturers with petrochemical safety certifications. The competitive structure concentrates around three strategic archetypes: diversified materials conglomerates leveraging polymer chemistry expertise, dedicated insulation specialists commanding fire-resistant system specifications, and regional tank fabricators with localized API 653 certification networks. Dominant competitive moves include backward integration into resin formulation and strategic partnerships with UAV-based inspection service providers.
Within the diversified materials tier, Saint-Gobain and Owens Corning occupy positions that exemplify technology leadership through materials science depth. Rockwool International A/S sits within the specialized insulation archetype, anchoring fire-resistant system specifications for aggressive chemical environments. These three companies represent the competitive poles around which qualified applicator networks and certification hierarchies organize.
| Leading Market Players |
|---|
| Saint Gobain |
| Rockwool International A/S |
| Owens Corning |
| Kingspan Group |
| Armacell International SA |
| Archtech Building Systems |
| Kumtek Thermotech |
| Roechling Group |
| Yutaka Corporation |
| Others |
Value Network & Pricing Analysis
Fiberglass-reinforced tank systems displacing conventional steel vessels in sulfuric acid storage are redrawing procurement geography toward resin formulation hubs in Germany and China while compressing margins on commodity-grade epoxy coatings. This substitution dynamic concentrates pricing power with suppliers of certified composite systems and fragments bargaining leverage among steel-tank coating applicators serving municipal water markets.
Pricing Analysis
Certification level (API 653/NACE/SSPC-grade) creates the primary spread between qualified applicators and uncertified contractors. Project-based pricing dominates large-diameter tank recoating programs, with premium tiers commanding substantial markups for fire-resistant insulation systems meeting OSHA process safety management standards. Cost compression in municipal water treatment coatings is intensifying because bisphenol-A price volatility squeezes formulation margins. Municipal utilities exhibit highest price sensitivity due to lowest-bid procurement regulations, while petrochemical operators prioritize predicted service life over unit pricing.
Supply Chain Analysis
Strategic stockpiling of amine hardeners and epoxy resins prevails among Gulf Coast coating manufacturers facing hurricane-season supply disruptions, contrasting with just-in-time resin delivery preferred by European formulators under REACH compliance pressures. Raw material sourcing concentrates in Germany, China, and the United States for bisphenol-A derivatives and specialized corrosion-resistant resin formulations. The supply chain rests on petrochemical feedstock availability from crude oil derivatives, creating exposure to commodity price swings. Distribution runs through regional certified applicator networks that control project execution velocity for API 653-mandated rehabilitation programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tank protection incumbents face substitution defense imperatives as aerogel and cellular glass insulations capture share in cryogenic LNG storage applications where thermal performance specifications exceed conventional rockwool ratings.
For Market Incumbents: Compound technology leadership in fiberglass-reinforced systems through backward integration into corrosion-resistant resin formulation, securing captive supply chains against bisphenol-A price volatility. Deepen certification network control by acquiring NACE-accredited training facilities to alleviate qualified applicator scarcity constraining project execution velocity.
For New Entrants and Emerging Players: Anchor in hydrogen storage infrastructure as an unpenetrated application space, targeting high-pressure composite tank barriers for European hydrogen backbone projects. Pursue digital inspection integration partnerships with UAV-based ultrasonic monitoring providers to differentiate predictive maintenance service models from traditional API 653 protocol vendors.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized insulation manufacturers with verified low-carbon production credentials qualifying for EU carbon border adjustment mechanism advantages. Monitor inspector certification backlog durations as the inflection signal; sustained examination delays indicate contractor capacity constraints that elevate acquisition multiples for qualified service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive supply of bisphenol-A derivatives insulates margin structures from petrochemical feedstock volatility. |
| API 653 Certification Network Expansion | Qualified inspector capacity constraints create scarcity rents for certified contractors bidding on federal rehabilitation mandates. |
| Digital Inspection Platform Partnership | AI-assisted corrosion mapping converges with traditional protocols to enable predictive maintenance subscription models. |
| Low-Carbon Production Certification | Verified emissions profiles qualify European suppliers for carbon border adjustment mechanism preference against Chinese imports. |
| Hydrogen Storage Barrier Development | Liquid hydrogen containment specifications present first-mover advantages in European hydrogen backbone infrastructure deployment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, API inspection certification records, and petrochemical capital expenditure disclosures to validate market sizing assumptions. Primary interviews engaged tank farm reliability engineers, NACE-certified coating applicators, chemical storage procurement leads, and fiberglass tank fabricators across the US Gulf Coast, Rhine-Ruhr corridor, and Yangtze River Delta. Secondary sources incorporated customs trade data for epoxy resin imports, ACC industry statistics, and SEC filings from diversified materials conglomerates. Bottom-up project pipeline analysis triangulated against top-down petrochemical capacity expansion forecasts.
Segmentation dimensions modeled include product type (coatings, liners, barriers, tanks), application vertical (oil and gas, chemical storage, industrial, water treatment), technology platform (epoxy, fiberglass, polyurethane, PVC), and end-user archetype (contractors, manufacturers, utilities, distributors) across the projection horizon. CAGRs derive from regression analysis of historical replacement cycle frequencies against regulatory mandate implementation timelines. Industry-specific forecast inputs encompass API 653 inspection failure rates and EPA SPCC compliance deadline phasing.
Decision-makers should treat outputs as directional under assumptions of sustained EPA enforcement intensity and stable petrochemical feedstock pricing; material deviation would warrant model refresh. Revision becomes warranted when aerogel insulation cost curves cross rockwool parity thresholds or when hydrogen storage infrastructure deployment accelerates beyond base-case assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Insider Threat Protection Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Threat Lifecycle Services Market