
 Asia Pacific Tank Protection Market | 2026-2036
Asia Pacific Tank Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Tank Protection Market Insights
Preventive maintenance subscriptions for corrosion monitoring systems is hardening into a core revenue layer for equipment suppliers. Emerson Electric Co. leverages its automation portfolio to bundle sensor networks with long-term service contracts. Motherwell Tank Protection anchors its position through British engineering heritage adapted for Asian refinery specifications. Zhejiang Zhenchao Petroleum And Chemical Equipment Co. dominates domestic procurement channels for floating roof seals across China's state-owned oil majors.
Asia Pacific tank protection encompasses engineered systems that prevent leakage, corrosion, and structural degradation in liquid storage vessels, typically incorporating cathodic protection circuits rated for 20-50 year design lives and elastomeric seal assemblies rated to 120°C hydrocarbon service. The primary purpose spans emissions containment, fire risk reduction, and environmental compliance across bulk liquid handling operations. Floating roof systems command the largest installed base due to pervasive gasoline and crude storage requirements, while polymer-based secondary containment liners represent the fastest-expanding category as chemical processors retrofit aging concrete bunds. Steel remains the default material specification for new construction, though composite alternatives gain traction in coastal corrosion zones.
China's Ministry of Emergency Management enforces GB 50183 design codes for petroleum storage facilities, while India's PESO mandates periodic integrity assessments under the Static and Mobile Pressure Vessels rules. Japan's METI coordinates industrial safety inspections that directly specify tank protection upgrade timelines for refiners. Australia's Work Health and Safety Regulations impose duty-of-care obligations on tank farm operators with explicit reference to spill prevention engineering. Stakeholders must track how bilateral trade agreements between ASEAN members affect cross-border certification reciprocity for protection equipment.
Market Dynamics
India's PESO emission mandates for above-ground storage tanks are compressing upgrade timelines across the region's refining corridor. Refiners in Gujarat and Tamil Nadu face simultaneous pressure to retrofit floating roof seals while expanding crude handling capacity.
Growth Catalysts
- GB 50183 Design Codes:China's Ministry of Emergency Management enforces stricter petroleum storage facility standards that mandate cathodic protection upgrades across coastal refining clusters.
- Specialty Chemical Output Targets:Southeast Asian processors are expanding tank farm capacity to capture regional demand for agrochemical intermediates and electronic-grade solvents.
- Crude Import Volume Concentration:China's coastal refining corridors continue absorbing higher throughput volumes that strain legacy seal assemblies and accelerate replacement cycles.
Market Restraints
- Specialty Elastomer Supply Concentration:Fluoroelastomer feedstock for high-temperature seals concentrates among Japanese and Korean chemical suppliers, exposing buyers to input cost volatility.
- Technical Limitation in Composite Adoption:Fiber-reinforced polymer tank shells face certification gaps under India's Static and Mobile Pressure Vessels rules, slowing displacement of steel in coastal corrosion zones.
- Regulatory Friction in Cross-Border Certification:ASEAN bilateral trade agreements lack reciprocity protocols for tank protection equipment, fragmenting procurement across member states.
Strategic Opportunities
- Vietnam's Underpenetrated Chemical Processing Corridor:New petrochemical complexes in Ba Ria-Vung Tau province lack established protection system suppliers, creating first-mover positioning for integrated service providers.
- Dual Carbon Goals Convergence:China's MEE carbon intensity targets are accelerating demand for vapor recovery systems that integrate with floating roof retrofits.
- Preventive Maintenance Channel Innovation:Sensor-network subscriptions bundled with corrosion monitoring are displacing transactional equipment sales in Australian tank farm operations.
Industry Challenges
- Certification Timeline Compression:Japan's METI inspection schedules specify upgrade deadlines that outpace engineering procurement cycles for complex seal replacement projects.
- Capex Intensity in Bund Retrofitting:Polymer-based secondary containment liner installation requires extended tank downtime that conflicts with continuous refinery operations.
- Skill Scarcity in Cathodic Protection Design:Qualified engineers for 20-50 year rated protection circuit specification remain concentrated in established refining hubs, constraining rollout in emerging chemical clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Tank Protection Market |
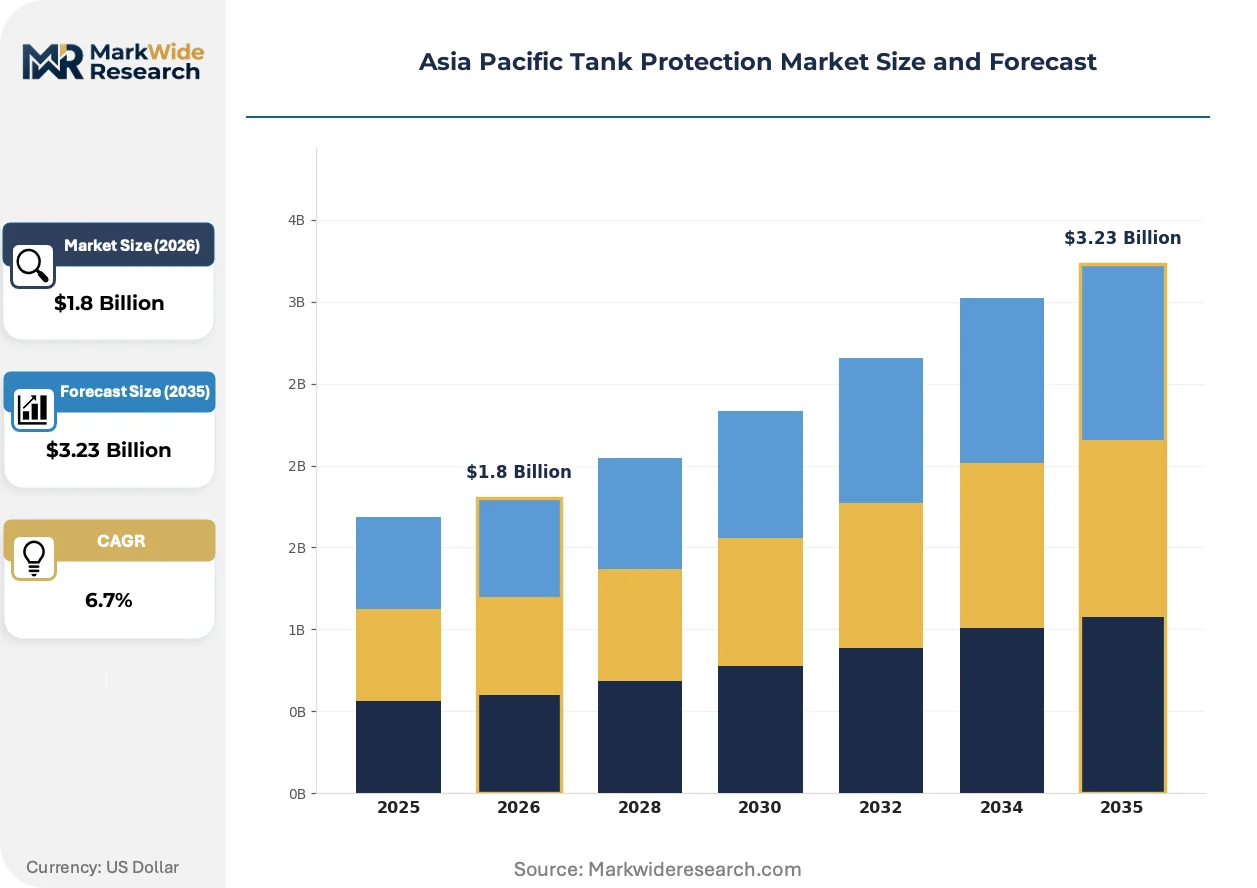
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Floating Roofs, Secondary Containment, Liners, Corrosion Inhibitors Installation Method: Above Ground, Underground, Mobile, Fixed End User: Oil & Gas, Water Treatment, Chemical Processing, Food & Beverage Material: Steel, Concrete, Polymer, Composite |
| Companies Covered | Emerson Electric Co., Zhejiang Zhenchao Petroleum And Chemical Equipment Co., L&J Technologies Inc., Oil Conservation Engineering Company, KMC Oil and Gas Equipment, Korean Steel Power Corp., Motherwell Tank Protection, NEOTECH Co., Valcrom Global DWC LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Tank Protection Market Trends and Innovations
Digital corrosion monitoring architectures are compressing maintenance decision cycles across the region's tank farm operators. Real-time sensor deployment is shifting from pilot programs to standard procurement specifications.
Wireless cathodic protection monitoring systems are decentralizing integrity management across geographically dispersed storage assets. Australian bulk liquid terminal operators are deploying mesh-networked reference electrodes to eliminate manual potential survey routines. This architecture is decentralizing maintenance resource allocation from centralized engineering teams to localized response units.
India's PESO mandates for periodic integrity assessments under Static and Mobile Pressure Vessels rules are forcing documented inspection protocols for all above-ground storage. Refinery operators must now submit digital corrosion rate records to regional explosives authorities. Floating roof seal replacement projects in Gujarat and Maharashtra are accelerating to meet compliance deadlines ahead of enforcement phase transitions.
After-sales service unbundling is fragmenting traditional equipment supply relationships across Southeast Asian chemical processors. Buyers are separating seal procurement from installation supervision and commissioning support. This pattern is most visible in Thailand's Eastern Economic Corridor, where state-owned oil storage operators now tender engineering services independently from material packages.
Asia Pacific Tank Protection Market Segmentation
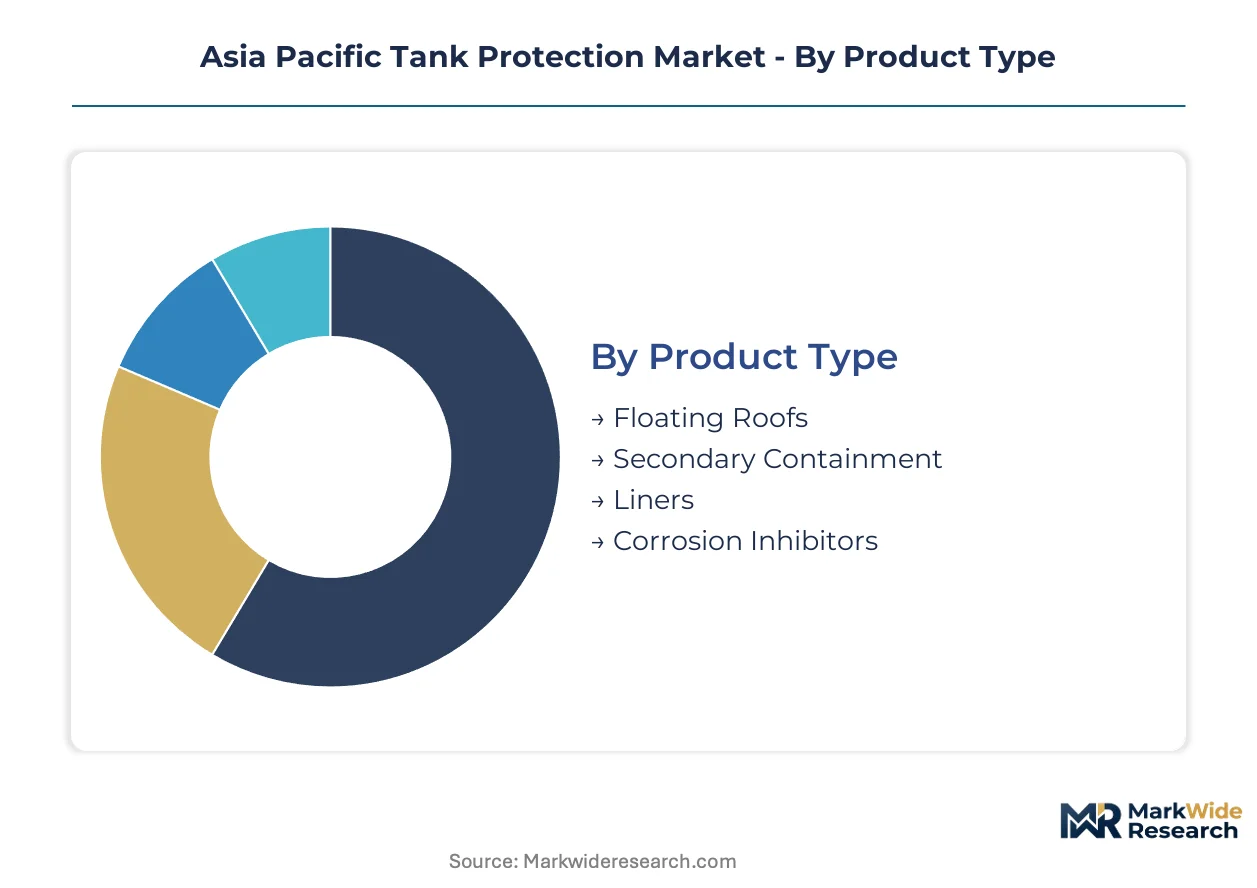
Segmentation in the Asia Pacific tank protection market reveals how engineering specifications diverge across coastal refining clusters, chemical processing corridors, and water treatment infrastructure. Procurement patterns track directly against regulatory enforcement intensity in each vertical.
Product Type:
Supply concentration for engineered protection systems tilts toward seal manufacturers with proven hydrocarbon service records and polymer formulators serving secondary containment retrofit demand.
- Floating Roofs:Aluminum or steel pontoon assemblies with elastomeric shoe seals rated for gasoline and crude vapor containment dominate installed base across China's coastal refineries. Gujarat and Tamil Nadu operators face compressed replacement timelines under India's PESO emission mandates.
- Secondary Containment:Polymer-based liner systems and concrete bund retrofits address India's Static and Mobile Pressure Vessels rules and Australia's Work Health and Safety duty-of-care obligations. Chemical processors in Thailand's Eastern Economic Corridor drive specification innovation for electronic-grade solvent containment.
- Liners:Geomembrane and elastomeric sheet systems seal aging concrete containment structures. Japanese chemical terminals specify fluoropolymer formulations for aggressive acid service.
- Corrosion Inhibitors:Cathodic protection circuits and chemical treatment programs extend steel tank design lives. Australian bulk liquid operators deploy wireless monitoring architectures to manage distributed asset integrity.
Floating roof systems absorb the bulk of installed capacity; secondary containment is expanding most quickly as regulatory deadlines force bund retrofit programs across the region.
Installation Method:
Application context determines specification trade-offs between structural permanence, inspection accessibility, and operational flexibility across tank farm configurations.
- Above Ground:Vertical cylindrical steel shells with fixed or floating roof configurations constitute the standard for petroleum and chemical storage. China's GB 50183 design codes mandate cathodic protection for all new above-ground construction in coastal refining zones.
- Underground:Double-walled steel or composite vessels with leak detection systems serve retail fuel stations and aviation depots. Japan's METI inspection protocols specify upgrade timelines for aging underground assets at industrial facilities.
- Mobile:Transportable tank containers and modular storage units support construction logistics and emergency response operations. Australia's mining and remote infrastructure sectors generate intermittent demand for rapid-deployment containment.
- Fixed:Permanent concrete or steel structures with integrated protection systems anchor water treatment and bulk chemical handling facilities. Vietnam's Ba Ria-Vung Tau petrochemical corridor lacks established suppliers for complex fixed-installation projects.
Above ground installations anchor regional capacity; underground systems are gaining specification share as urban density constraints intensify in Japanese and Korean industrial zones.
End User:
Customer procurement maturity varies sharply between consolidated national oil companies and fragmented chemical processors with diverging technical evaluation capabilities.
- Oil & Gas:Integrated refiners and terminal operators specify 20-50 year rated protection systems with documented inspection protocols. China's state-owned oil majors dominate regional procurement volume through centralized engineering standards.
- Water Treatment:Municipal and industrial wastewater facilities require corrosion-resistant containment for chemical dosing and sludge handling. Australian utilities specify polymer liners for concrete clarifier retrofits.
- Chemical Processing:Agrochemical and electronic-grade solvent producers drive demand for high-integrity secondary containment. Southeast Asian processors unbundle seal procurement from installation supervision to compress project costs.
- Food & Beverage:Edible oil and liquid food storage applications specify food-grade elastomeric seals and stainless steel contact surfaces. Indian FSSAI compliance requirements shape material selection for domestic refiners.
Oil and gas commands the dominant share of protection system deployment; chemical processing is climbing the fastest as Southeast Asian capacity expansion accelerates.
Material:
Cost-performance trade-offs between established steel specifications and emerging alternatives fragment supplier positioning across corrosion environments and regulatory jurisdictions.
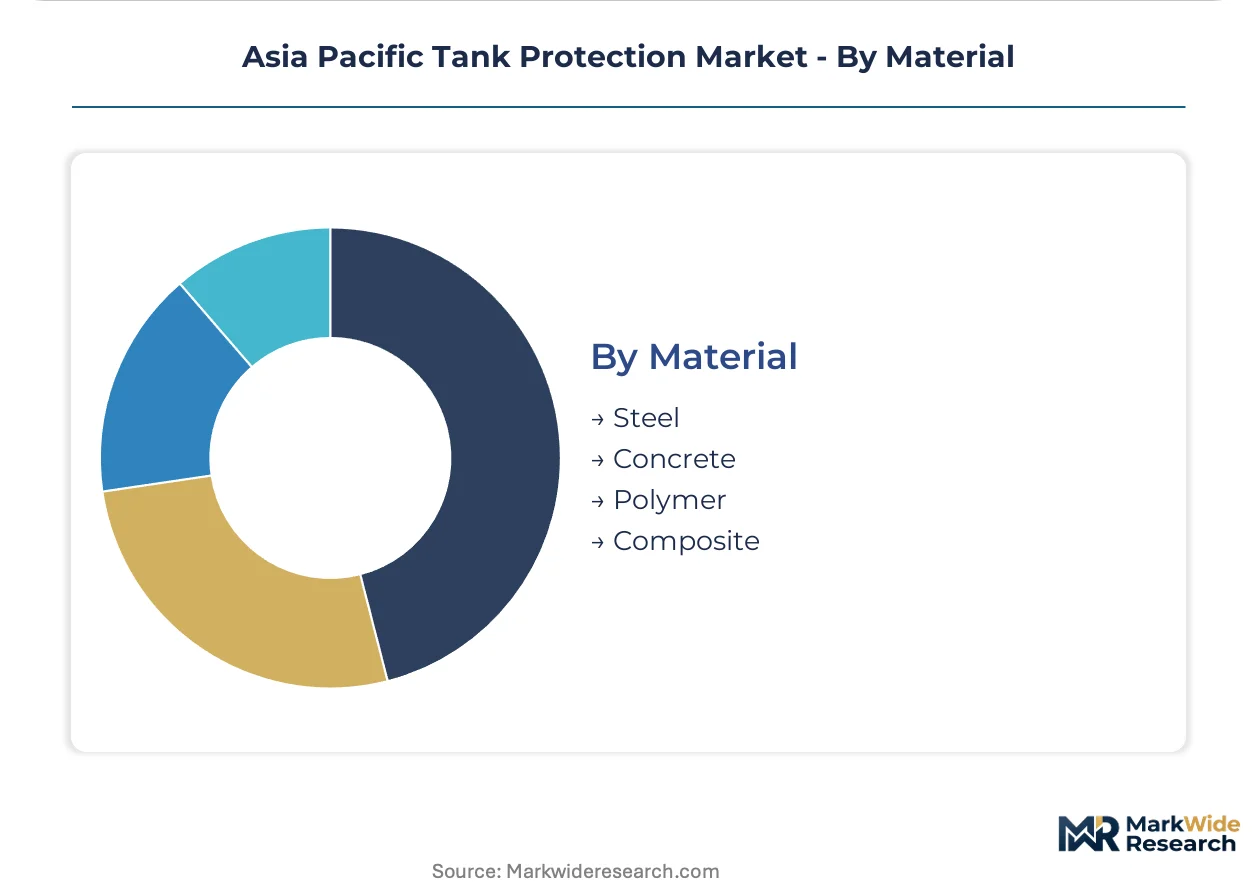
- Steel:Carbon and stainless steel remain the default specification for pressure-rated tank shells and floating roof pontoons. Japanese and Korean mills supply premium plate grades for high-sulfur crude service in Chinese refineries.
- Concrete:Reinforced concrete structures with protective linings anchor water treatment and bulk chemical containment. India's PESO mandates drive integrity assessment programs for aging concrete storage at explosives-handling facilities.
- Polymer:HDPE, PP, and fluoropolymer formulations enable chemical-resistant liners and modular tank construction. Certification gaps under India's Static and Mobile Pressure Vessels rules constrain polymer tank shell adoption despite corrosion advantages.
- Composite:Fiber-reinforced polymer shells and structures gain traction in coastal corrosion zones and lightweight mobile applications. Australian terminal operators pilot composite access platforms and secondary containment systems.
Steel absorbs the bulk of structural material demand; polymer formulations are expanding most quickly as chemical processors retrofit concrete bunds across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the bulk of regional tank protection capacity while Southeast Asian nations expand chemical processing infrastructure. Refining corridors in India and Australia drive retrofit demand through tightening emission mandates. Procurement patterns fragment across national certification regimes despite geographic proximity.
China
Coastal refining clusters in Shandong and Guangdong provinces absorb floating roof seal replacements as crude import volumes climb. The Ministry of Emergency Management enforces GB 50183 design codes that mandate cathodic protection for all new petroleum storage construction. State-owned oil majors in Dalian and Ningbo centralize procurement through domestic engineering standards that favor established suppliers.
India
Refiners in Gujarat and Tamil Nadu retrofit aging tank farms under compressed timelines from PESO emission mandates. The Static and Mobile Pressure Vessels rules require documented integrity assessments with digital corrosion rate submissions to regional explosives authorities. Mumbai-Pune industrial corridor operators unbundle seal procurement from installation supervision to compress project costs.
Japan
METI inspection protocols specify upgrade deadlines for aging underground storage assets at industrial facilities in Chubu and Kansai regions. Fluoroelastomer feedstock suppliers concentrate technical expertise for high-temperature seal specifications. Osaka Bay petrochemical terminals face compressed engineering procurement cycles for complex replacement projects.
Australia
Bulk liquid terminal operators in Queensland and Western Australia deploy wireless cathodic protection monitoring to eliminate manual potential survey routines. Work Health and Safety Regulations impose duty-of-care obligations with explicit reference to spill prevention engineering. Preventive maintenance subscriptions for sensor-network corrosion monitoring displace transactional equipment sales.
Vietnam
New petrochemical complexes in Ba Ria-Vung Tau province lack established protection system suppliers, creating positioning opportunities for integrated service providers. Underdeveloped domestic engineering capacity constrains rollout of 20-50 year rated protection circuit specifications. Foreign fabricators face certification gaps when bidding fixed-installation projects for emerging chemical clusters.
Asia Pacific Tank Protection Market Competitive Landscape
Top-tier vendors anchor premium engineering tiers, while mid-scale fabricators compete on domestic procurement channel access. The vendor base stratifies between automation-integrated multinationals and regional specialists with country-specific certification relationships. Two archetypes dominate: sensor-network service bundlers and seal manufacturers with proven hydrocarbon service records. Competitive moves concentrate on preventive maintenance channel innovation and geographic expansion into underpenetrated chemical processing corridors.
Within the automation-integrated tier, Emerson Electric Co. exemplifies sensor-network subscription bundling alongside long-term service contracts. Among Asia-Pacific fabricators, Zhejiang Zhenchao Petroleum And Chemical Equipment Co. and Korean Steel Power Corp. occupy positions tied to domestic procurement channels for state-owned oil majors. Motherwell Tank Protection represents British engineering heritage adapted for Asian refinery specifications. L&J Technologies Inc., Oil Conservation Engineering Company, and KMC Oil and Gas Equipment sit within mid-scale specialist tiers serving retrofit demand across fragmented national markets.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Zhejiang Zhenchao Petroleum And Chemical Equipment Co. |
| L&J Technologies Inc. |
| Oil Conservation Engineering Company |
| KMC Oil and Gas Equipment |
| Korean Steel Power Corp. |
| Motherwell Tank Protection |
| NEOTECH Co. |
| Valcrom Global DWC LLC |
| Others |
Pricing and Supply Chain Analysis
State-owned oil majors in China and India anchor procurement volume through centralized engineering standards, compressing margin capture for foreign suppliers while rewarding domestic fabricators with certification reciprocity advantages. Sovereign-backed procurement channels enforce pricing discipline across floating roof seal and cathodic protection system tenders.
Pricing Analysis
Margin tightening in premium-tier cathodic protection systems reflects Japanese fluoroelastomer feedstock concentration and extended 20-50 year design-life engineering costs. Three-tier pricing structure across premium, standard, and economy levels separates sensor-network subscription bundles from transactional equipment sales and basic seal replacement kits. China's state-owned oil majors exercise acute price sensitivity through consolidated tender volumes, while Australian bulk liquid operators demonstrate lowest sensitivity due to duty-of-care liability exposure under Work Health and Safety Regulations.
Supply Chain Analysis
Fluoroelastomer feedstock for high-temperature seals rests on Japanese and Korean specialty chemical producers, exposing buyers to input cost volatility. Steel plate for tank shells draws from Chinese and Japanese mills, while polymer liner formulations source from domestic Southeast Asian compounders. Single-source vulnerability concentrates in fluoroelastomer supply, with tariff exposure escalating across ASEAN bilateral trade gaps. Distribution runs through state-owned oil major procurement channels in China and India, fragmented engineering procurement in Southeast Asia, and subscription-based service models in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market is concentrating into a vertical-integration race, with sensor-network bundlers capturing recurring revenue streams and seal manufacturers securing captive fluoroelastomer supply.
For Market Incumbents: Deepen backward integration into fluoroelastomer compounding to neutralize Japanese-Korean feedstock concentration risk. Expand sensor-network subscription penetration in Australian bulk liquid terminals to displace transactional competitors. Anchor certification relationships with India's PESO and China's Ministry of Emergency Management to defend against emerging domestic fabricators. For New Entrants and Emerging Players: Launch via integrated service provision in Vietnam's Ba Ria-Vung Tau petrochemical corridor, where established suppliers lack presence. Target secondary containment retrofit demand in Thailand's Eastern Economic Corridor, where chemical processors unbundle procurement and compress project costs. Lead with wireless cathodic protection monitoring architectures to bypass incumbents' legacy installation relationships. For Investors and Strategic Acquirers: METI inspection schedule compression in Japan is the leading indicator that engineering procurement cycle mismatches will force consolidation among mid-scale seal specialists. Position acquisition focus on Australian sensor-network service providers with established preventive maintenance subscriptions. Monitor China's dual carbon goals convergence as the signal for vapor recovery system integration demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoroelastomer Supply | Neutralizes Japanese-Korean feedstock concentration and stabilizes input costs for seal manufacturers. |
| Sensor-Network Subscription Launch | Emerson Electric's bundled service model displaces transactional sales in Australian tank farm operations. |
| Vietnam Market Entry via Integrated Services | Ba Ria-Vung Tau petrochemical complexes lack established protection system suppliers. |
| Wireless Cathodic Protection Deployment | Queensland terminal operators eliminate manual potential survey routines through mesh-networked electrodes. |
| PESO Certification Investment | Mumbai-Pune corridor operators face compressed retrofit timelines under India's emission mandates. |
Research Methodology
Document review covered customs and trade databases, SEC filings from listed industrial automation suppliers, and national regulatory gazettes from China's Ministry of Emergency Management and India's PESO, complemented by interviews with maintenance directors at Southeast Asian refineries, procurement leads at Australian bulk liquid terminals, cathodic protection engineering specialists, and aftermarket service heads. Bottom-up triangulation against top-down capacity expansion announcements validated segment-level estimates.
Installed base projections across product type, installation method, end user, and material segmentation were derived through analysis window modeling. CAGRs were computed from historical replacement cycle data and regulatory enforcement phase transitions. Forecast inputs incorporated GB 50183 design code adoption timelines, PESO integrity assessment mandate compliance rates, and dual carbon goals vapor recovery integration assumptions.
The model assumes a particular technology adoption path for wireless cathodic protection monitoring; alternative pathways for fiber-reinforced polymer tank shells under India's Static and Mobile Pressure Vessels rules would alter the outlook. Forecasts reflect assumptions on ASEAN certification reciprocity progression and fluoroelastomer supply concentration persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Continuous Threat Exposure Management Market
Critical Infrastructure Protection
Counter Cyberterrorism Market
Critical Infrastructure Protection
North America Tank Protection Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
Tele Protection Market
Critical Infrastructure Protection
Global Airport and Marine Port Security Market
Critical Infrastructure Protection
Middle East Commercial Security Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Guardrail Protection System Market
Critical Infrastructure Protection
Middle East and Africa Explosion-Proof Equipment Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
Global High Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
GCC Protective Relay Market