
 Roundwood Market | 2026-2036
Roundwood Market Size, Share, and Industry Trends Forecast 2026-2036
Roundwood Market Outlook
The capital-intensity divergence between integrated sawmill operators and standalone log traders is collapsing as automated bucking and scanning systems democratize precision cutting. Fritz Kohl GmbH and Co. KG leverages its German kiln-drying expertise to dominate engineered-wood feedstock supply. Sierra Pacific Industries anchors West Coast softwood output through captive forestland and rail-linked mills. JD Forest Products competes in tropical hardwood niches via certified chain-of-custody networks.
Roundwood comprises felled trees retaining their natural cylindrical form, typically measured by diameter at breast height and merchantable length, destined for primary processing into dimensional lumber, veneer, or pulp furnish. The material serves as the foundational input for construction framing, mass-timber manufacturing, and chemical cellulose extraction across temperate and tropical supply basins. Logs and timber grades generate the bulk of revenue in mature North American and European markets, while poles and beams capture premium margins from utility infrastructure and cross-laminated timber projects. Pulp-grade roundwood commands volume scale in Nordic and South American markets where Fibria-Arauco integrated complexes anchor chemical cellulose output.
EU EUDR due-diligence obligations, US Lacey Act enforcement, and Indonesia's SVLK certification system collectively tighten legality verification across import channels. These frameworks redirect procurement toward documented supply streams and penalize opaque origin chains. Stakeholders must monitor evolving geolocation requirements and build traceability infrastructure before compliance deadlines harden market access rules.
Market Dynamics
Automated bucking and scanning systems are collapsing the historical capital-intensity gap between integrated sawmill operators and standalone log traders, forcing a rapid recalibration of competitive positioning across temperate and tropical supply basins.
Growth Catalysts
- EU Deforestation Regulation:The EU Deforestation Regulation (EUDR) mandates geolocation traceability for all timber imports, redirecting procurement toward documented supply streams and creating first-mover advantages for operators with established chain-of-custody infrastructure.
- Mass-timber construction:Cross-laminated timber and glulam projects are absorbing premium-grade structural roundwood, particularly in Nordic and Pacific Northwest markets where building codes now permit mid-rise timber frames.
- Kalimantan processing cluster:Indonesia's integrated plywood and veneer complexes concentrate tropical hardwood offtake, drawing logs from satellite concessions across Borneo and Sulawesi to achieve scale economies in chemical cellulose feedstock.
Market Restraints
- Fuel and hauling cost volatility:Diesel price swings and truck driver shortages in North American inland basins compress delivered log margins for non-rail-linked sawmills.
- Concentrated Nordic pulp supply:Fibria-Arauco integrated complexes dominate chemical cellulose-grade roundwood offtake, leaving limited spot market liquidity for independent chipping operations.
- Steel and concrete substitution:Reinforced concrete and light-gauge steel framing retain cost advantages in high-rise and seismic-zone construction, capping roundwood penetration in urban vertical build.
Strategic Opportunities
- Indonesian SVLK certification tailwind:The country's Timber Legality Assurance System opens preferential access to EU and Japanese import channels for certified operators, creating margin premiums over undocumented competitors.
- Utility pole electrification:Grid hardening and rural electrification programs in Southeast Asia are absorbing creosote-treated hardwood poles, an application with 40-60 year replacement cycles.
- Blockchain-IoT traceability convergence:Distributed ledger systems paired with harvest-site GPS tagging enable real-time legality verification, satisfying EUDR due-diligence obligations without paper-based documentation delays.
Industry Challenges
- Geolocation data infrastructure:Harvest operators must deploy GPS-enabled tracking from stump to mill gate before December 2024 compliance deadlines, requiring capital outlays for hardware and software integration in remote concessions.
- Kiln-drying technician scarcity:Precision moisture management for engineered-wood feedstock demands specialized operators, with training pipelines failing to match expansion rates in Central European and Southeast Asian processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roundwood Market |
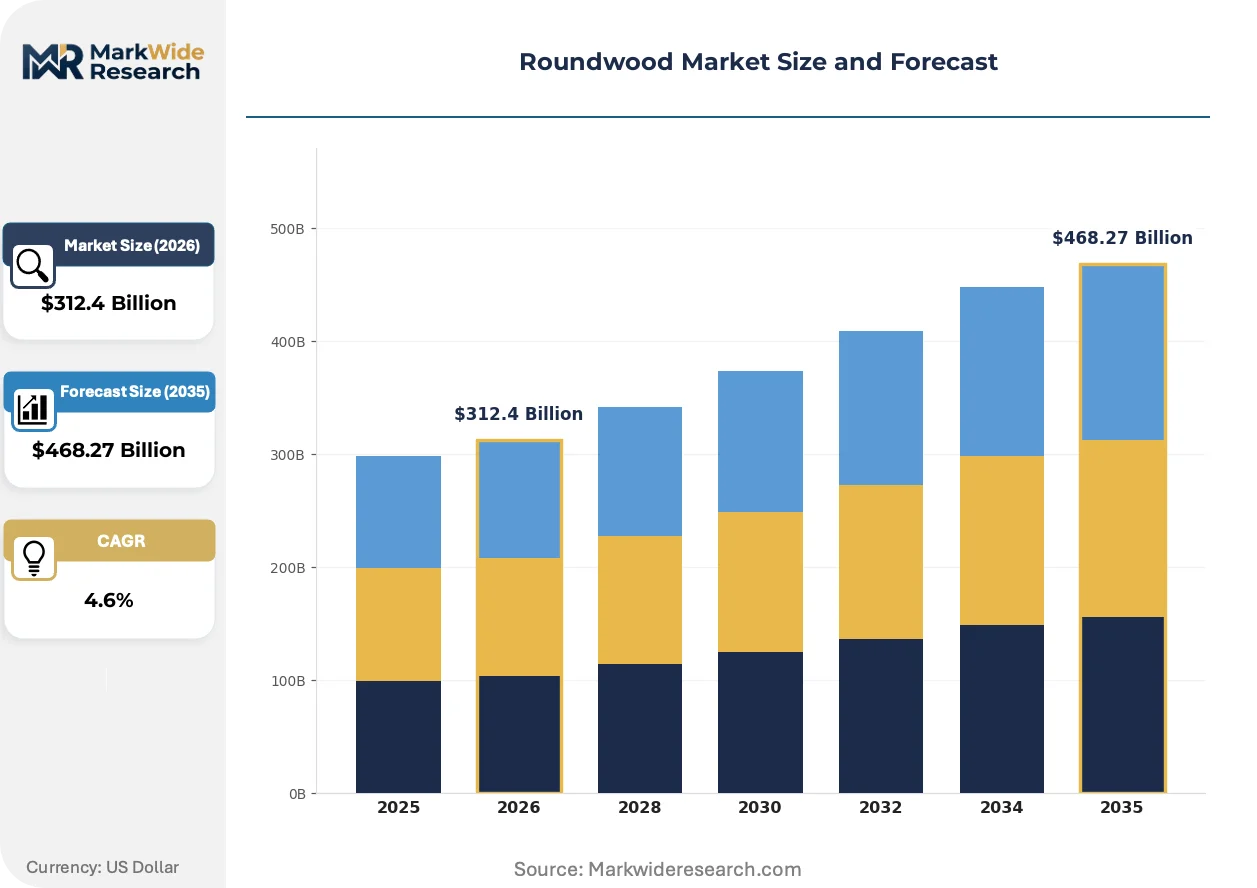
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $468.27 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Logs, Poles, Beams, Timber End Use Industry: Construction, Furniture, Pulp & Paper, Biomass Distribution Channel: Wholesale, Retail, Online, Direct Sales Grade: Premium, Select, Common, Industrial |
| Companies Covered | AFRITIMSU GROUP OF CO. LTD., Atlantis SA, Extra-Les LLC, Flexx Panel BV, Fritz Kohl GmbH and Co. KG, JD Forest Products, Johnson International Co., Sierra Pacific Industries, Timberlink Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roundwood Market Strategic Shifts
Digital sensing and automation are compressing processing yields while regulatory traceability mandates restructure procurement relationships, creating divergent capability requirements across temperate softwood and tropical hardwood supply chains.
Computed tomography log scanning is decomposing the traditional reliance on external grading for internal defect detection. Nordic and German sawmills are deploying industrial CT systems at scale, reducing fiber recovery waste by enabling precision bucking decisions before primary breakdown. This technology is decomposing the historical advantage of experienced sawyers, allowing greenfield mills in emerging basins to achieve comparable lumber recovery rates without decades of accumulated tacit knowledge.
REACH and the EU Deforestation Regulation are tightening chemical treatment and origin documentation requirements for all construction-grade roundwood entering European customs territory. Industrial consequence includes mandatory geolocation coordinates for every harvest batch and expanded due-diligence liability for downstream importers. Tropical hardwood traders are responding by pre-positioning compliance documentation through third-party verification bodies in Jakarta and Singapore.
Buyers are consolidating procurement relationships around vertically integrated suppliers with captive forestland and certified chain-of-custody systems. Large-scale mass-timber developers in British Columbia and Austria now specify single-source supply agreements spanning stump to structural panel, displacing spot-market log purchasing. This concentration is most visible in Pacific Northwest markets where Sierra Pacific Industries and similar operators offer bundled engineering, fabrication, and erection services alongside raw material supply.
Roundwood Market Segmentation
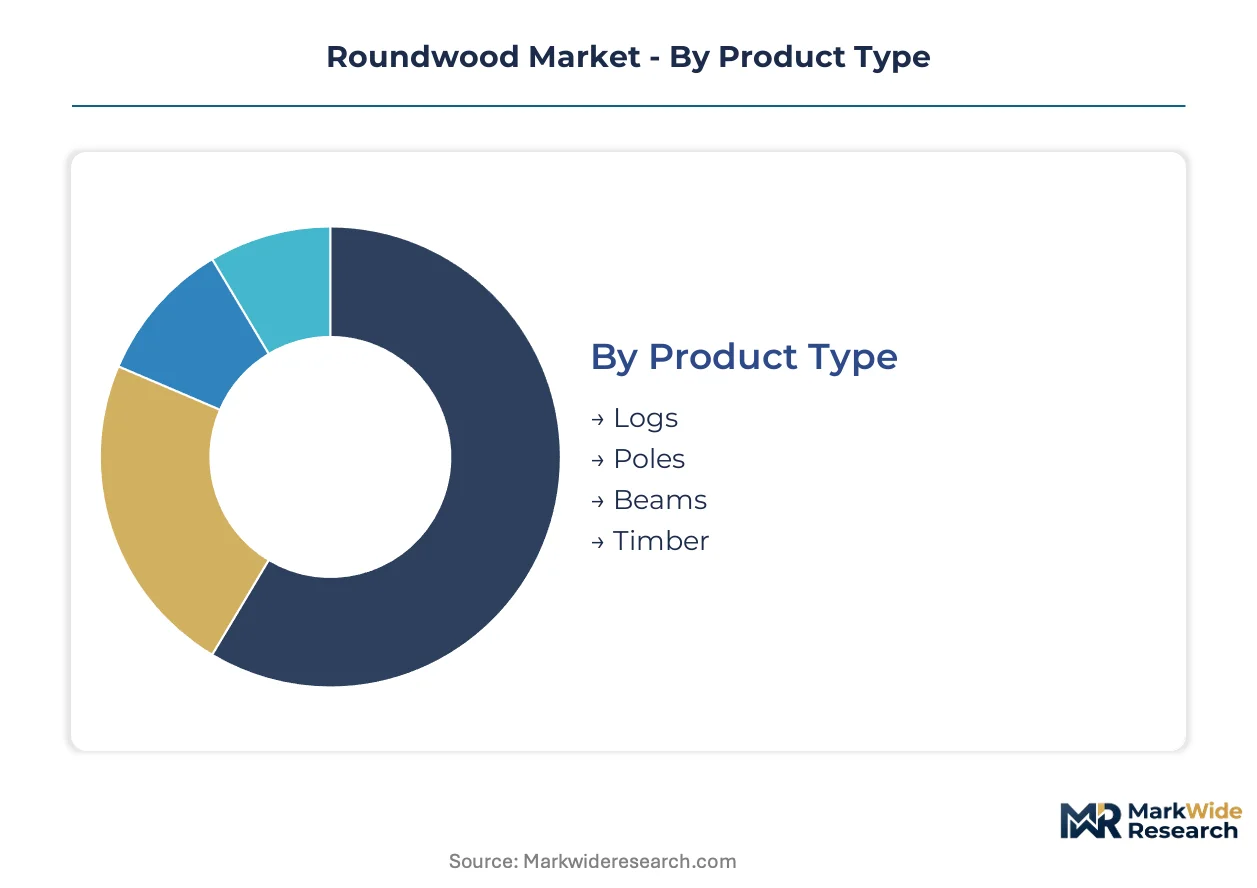
Roundwood segmentation reveals divergent supply chain configurations across product forms and end-use applications. Understanding these divisions exposes where capital concentrates, where margins compress, and where regulatory compliance costs reshape competitive boundaries.
Product Type:
Domestic consumption dominates timber and beam segments in North American and European construction basins, while logs and poles flow disproportionately into export channels serving Asian processing clusters and utility infrastructure programs.
- Logs:Retain natural cylindrical form with bark intact, measured by diameter at breast height and merchantable length for primary breakdown into dimensional lumber or veneer. Nordic and Baltic suppliers feed German and Austrian sawmills through short-haul rail corridors, though Kalimantan hardwood logs increasingly serve Japanese plywood manufacturers seeking SVLK-certified feedstock.
- Timber:Rough-sawn or hewn structural members graded for load-bearing applications in framing and mass-timber systems. British Columbia and Austria specify single-source timber supply agreements for cross-laminated timber projects, displacing spot-market purchasing as EUDR traceability mandates harden.
- Poles:Creosote-treated hardwood cylinders for utility transmission and distribution infrastructure. Southeast Asian grid hardening programs absorb Indonesian and Malaysian pole volumes on 40-60 year replacement cycles.
- Beams:Large-section structural members for heavy timber and post-and-beam construction. Japanese traditional building methods and North American heritage restoration projects sustain niche demand for old-growth dimensional material.
Timber commands the established base. The steepest expansion runs through logs.
End Use Industry:
Cost tier differentiation separates commodity pulp feedstock from premium structural applications, with certification premiums widening spreads between documented and undocumented supply streams.
- Construction:Structural framing, mass-timber manufacturing, and architectural finishes absorb graded roundwood across temperate and tropical basins. Nordic building code revisions permitting mid-rise timber frames redirect softwood offtake toward glulam and CLT producers.
- Pulp & Paper:Chemical cellulose extraction demands uniform fiber characteristics achieved through plantation eucalyptus and managed conifer stands. Fibria-Arauco integrated complexes in Brazil and Chile dominate volume offtake, constraining spot market access for independent chipping operations.
- Furniture:Appearance-grade hardwoods for veneer, cabinetry, and millwork applications. Italian and German manufacturers specify chain-of-custody documentation for tropical hardwood inputs to satisfy EU Timber Regulation due-diligence obligations.
- Biomass:Energy recovery through combustion or pelletization of low-grade fiber and processing residues. UK and Scandinavian district heating systems sustain demand for standardized chip specifications.
Construction anchors volume demand. Biomass is climbing the fastest as carbon accounting tightens.
Distribution Channel:
Customer type fragmentation separates large-scale mass-timber developers seeking bundled engineering services from small residential builders purchasing spot volumes through decentralized yard networks.
- Wholesale:Volume aggregation through broker networks and regional distributors serving multiple sawmill customers. North American inland basins rely on truck-based wholesale logistics where rail access remains limited.
- Direct Sales:Long-term supply agreements between integrated forestland owners and downstream processors. Sierra Pacific Industries and comparable operators bundle stump-to-panel traceability for British Columbia and Austrian mass-timber developers.
- Retail:Small-lot sales through lumber yards and building material dealers serving residential repair and remodeling contractors.
- Online:Digital platforms for specialty hardwood and reclaimed material matching niche specification requirements.
Direct sales commands the established base. Online channels are gaining share fastest among specialty and reclaimed segments.
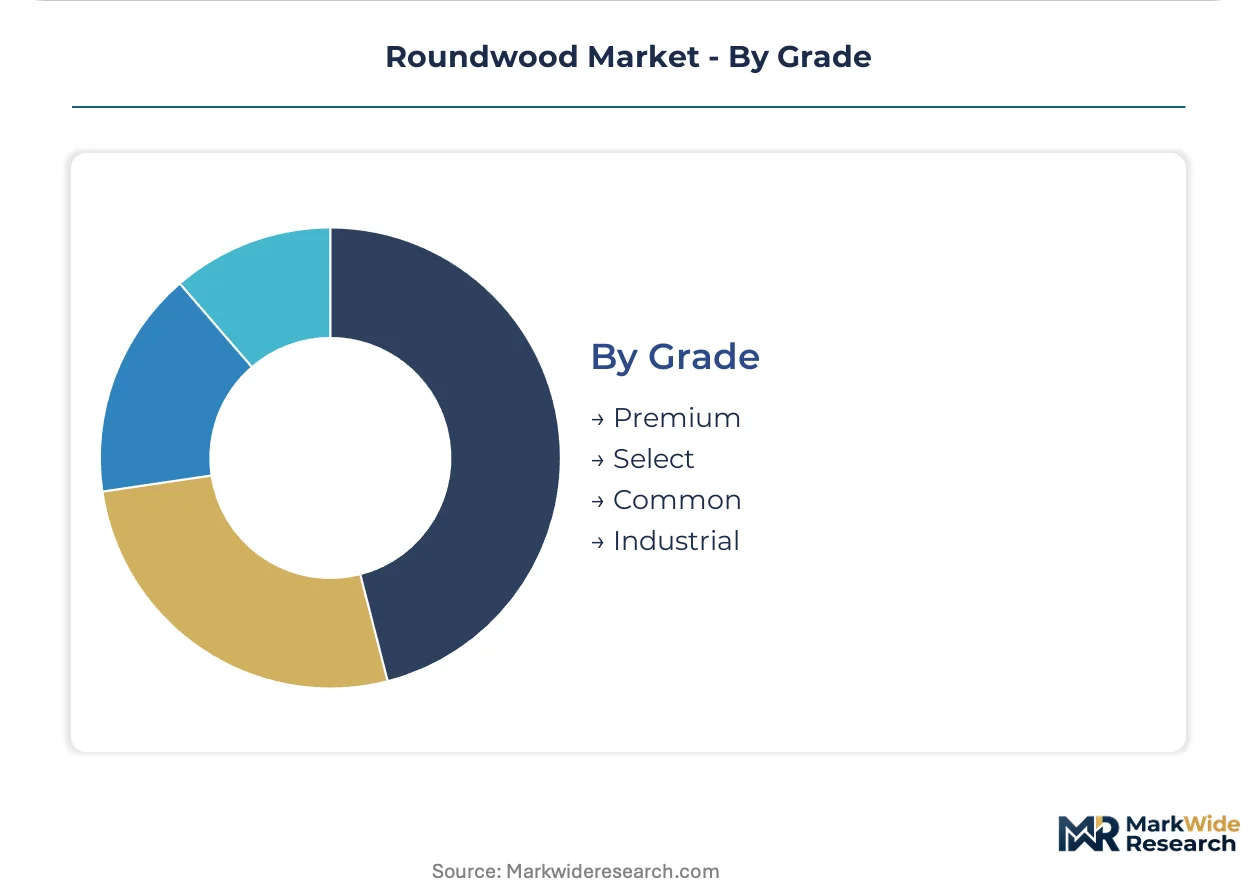
Grade:
Margin stratification concentrates in premium and select tiers where certification premiums and structural performance specifications justify price separation from common and industrial grades.
- Premium:Clear, straight-grained material free of defects for appearance and high-stress structural applications. Japanese post-and-beam builders and heritage restoration contractors specify premium grades with documented provenance.
- Select:Sound structural material with limited visual character for framing and engineered-wood feedstock. German kiln-drying operators achieve moisture precision that qualifies select-grade output for glulam manufacturing.
- Common:Construction-grade material with permitted defect levels for general framing and utility applications.
- Industrial:Low-grade fiber suitable for pallet manufacturing, crating, and non-structural industrial uses.
Select grade commands the established base. Premium grades are expanding most quickly as mass-timber performance specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pacific Northwest softwood commands premium structural grades while Kalimantan hardwood trades at volume-driven discounts, creating arbitrage opportunities for traders with dual-basin sourcing capabilities.
United States
West Coast mass-timber projects and Southern yellow pine framing sustain dimensional lumber offtake. EPA and OSHA oversee chemical treatment standards for utility poles. Sierra Pacific Industries anchors California and Oregon output through rail-linked mills serving British Columbia developers.
Germany
Engineered-wood feedstock demand from Austrian and domestic glulam producers absorbs kiln-dried spruce and fir. ECHA administers REACH compliance for creosote alternatives in pole treatment. Baden-Württemberg sawmills deploy CT scanning to optimize fiber recovery for CLT manufacturing.
Indonesia
Japanese plywood manufacturers and domestic veneer complexes drive tropical hardwood log consumption. SVLK certification administered by the Ministry of Environment and Forestry enables EU market access. Kalimantan processing clusters concentrate plywood output for export to East Asian construction markets.
Brazil
Fibria-Arauco integrated complexes dominate eucalyptus pulp-grade roundwood offtake for chemical cellulose export. ANVISA regulates biocide treatments for pole preservation. São Paulo state plantation managers supply uniform fiber to São Paulo and Paraná pulp mills.
Sweden
Nordic building code revisions permitting mid-rise timber frames redirect spruce offtake toward glulam producers. The Swedish Forest Agency enforces geolocation traceability ahead of EUDR alignment. Västerbotten and Norrbotten mechanized harvesting operations feed Baltic Sea export terminals.
Roundwood Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with precision-scanning specialists commanding premium structural grades while volume-scale plantation operators dominate pulp feedstock supply. The market exhibits tiered concentration: integrated forestland owners with captive mills occupy the upper tier, regional sawmill cooperatives form a fragmented middle layer, and commodity log traders compete on haulage efficiency at the base. Two archetypes define competitive positioning: vertically integrated operators bundling stump-to-panel traceability, and specialized kiln-drying houses achieving moisture precision for engineered-wood certification. Capacity expansion and strategic partnerships represent the dominant competitive moves, with rail-linked greenfield mills displacing truck-dependent inland processors.
Among German precision-processing specialists, Fritz Kohl GmbH and Co. KG exemplifies the kiln-drying archetype, while Sierra Pacific Industries anchors the integrated forestland-owner model on the US West Coast. JD Forest Products occupies a position within certified tropical hardwood sourcing networks. These three represent distinct geographic and capability positioning without overlapping strategic territory.
| Leading Market Players |
|---|
| AFRITIMSU GROUP OF CO. LTD. |
| Atlantis SA |
| Extra-Les LLC |
| Flexx Panel BV |
| Fritz Kohl GmbH and Co. KG |
| JD Forest Products |
| Johnson International Co. |
| Sierra Pacific Industries |
| Timberlink Ltd. |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day stump-to-mill lead times in Kalimantan concentrate pricing power with integrated plywood complexes while fragmenting margin capture among truck-dependent inland processors across North American basins. This temporal compression favors rail-linked mill operators with captive forestland holdings, forcing standalone log traders toward volume-discount positioning or certification-premium specialization to defend viability.
Pricing Analysis
Certification-premium spreads separate SVLK-documented tropical hardwood from undocumented spot-market supply by fifteen to twenty-five percent in EU-facing channels. Three-tier pricing structure across premium structural grades, standard framing tiers, and economy pulp feedstock anchors transactional models, with differentiation resting on chain-of-custody documentation and kiln-drying precision. Cost compression in standard-grade softwood intensifies as automated scanning democratizes lumber recovery rates, eroding historical tacit-knowledge premiums. Small residential builders exhibit highest price sensitivity through decentralized yard networks, while mass-timber developers accept structural-grade premiums for bundled stump-to-panel traceability.
Supply Chain Analysis
Strategic-stockpile preferences dominate pulp-grade procurement as Fibria-Arauco integrated complexes lock in multi-year eucalyptus offtake, while construction-grade timber flows through just-in-time rail corridors serving Nordic and Pacific Northwest glulam manufacturers. Geographic supply concentrates in Indonesia, Brazil, and Sweden, with raw material dependencies centering on diesel fuel for truck haulage, creosote alternatives for pole treatment, and precision moisture-management equipment for engineered-wood feedstock. Single-source vulnerability runs through Kalimantan hardwood channels exposed to geolocation compliance deadlines. Distribution runs through direct-sales agreements for mass-timber developers and wholesale broker networks for spot-market residential construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUDR traceability mandates constitute a regulatory inflection collapsing competitive advantage timelines from decades to hardware-deployment cycles, compressing incumbent adaptation windows while opening fast-follower entry paths for certified operators.
For Market Incumbents: Shield market position through captive forestland acquisition in Borneo and Sulawesi satellite concessions, securing geolocation-tagged supply streams ahead of December compliance hardening. Accelerate kiln-drying technician training pipelines in Central European and Southeast Asian hubs to offset precision-moisture scarcity threatening engineered-wood certification. Backward integration into rail-linked mill infrastructure displaces truck-dependent competitors in North American inland basins.
For New Entrants and Emerging Players: SVLK certification fast-tracks open preferential EU and Japanese import channels with margin premiums over undocumented competitors, creating viable entry path for capital-light traders. White-space concentrates in blockchain-IoT traceability services pairing harvest-site GPS tagging with distributed ledger verification, satisfying EUDR due-diligence without paper-documentation delays. Target Southeast Asian utility pole electrification programs absorbing creosote-treated hardwood on forty-to-sixty-year replacement cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified forestry conglomerates with underutilized Kalimantan processing capacity and latent SVLK infrastructure requiring activation capital. Long-term viability favors operators with demonstrated geolocation compliance and rail-linked mill networks over truck-dependent spot-market players. Signal to watch: EUDR enforcement intensity at Rotterdam and Hamburg entry points, with inspection rate acceleration indicating compliance-premium durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Geolocation Traceability Deployment | GPS-enabled stump-to-mill tracking satisfies EUDR due-diligence obligations for EU market access. |
| Kiln-Drying Capacity Expansion | Precision moisture management qualifies output for glulam and CLT structural certification tiers. |
| Rail-Linked Mill Acquisition | Captive rail infrastructure insulates delivered-log margins from diesel volatility and driver shortages. |
| SVLK Certification Investment | Timber Legality Assurance System opens preferential Japanese and EU import channels. |
| CT Scanning Technology Integration | Industrial computed tomography optimizes fiber recovery rates without decades of sawyer tacit knowledge. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade databases, forestry concession registries, and pulp mill production disclosures, validated through interviews with sawmill operations directors, procurement managers at mass-timber developers, SVLK certification auditors, and logistics coordinators at Baltic Sea export terminals. Bottom-up volume aggregation across product grades and end-use segments triangulates against top-down macroeconomic drivers and regulatory timeline assessments.
Segmentation dimensions modeled span product type, end-use industry, distribution channel, and grade tier across the projection horizon. CAGRs derive from historical volume trajectories adjusted for regulatory compliance deadlines, mass-timber building code adoption curves, and pulp complex capacity expansion schedules. Forecast inputs incorporate SVLK certification penetration rates and geolocation hardware deployment timelines in remote concessions.
Underlying assumptions cover EUDR enforcement consistency, diesel price band stability, and kiln-drying technician training pipeline throughput, with deviation risk concentrated in regulatory inspection intensity and tropical hardwood substitution elasticity. Revision becomes warranted when EUDR geolocation compliance rates among Indonesian exporters cross eighty-percent thresholds or mass-timber building code revisions accelerate beyond Nordic and Pacific Northwest pilot markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Sod Peat Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Straw Market