
 Soybean Derivatives Market | 2026-2036
Soybean Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Soybean Derivatives Market Analysis
Crush margin optimization is tilting toward higher-value protein isolates and lecithin fractions. Archer Daniels Midland Company leverages its North American crushing network to sustain origination advantages. Cargill anchors its position through integrated oilseed processing and food ingredient formulation capabilities. Wilmar International Limited dominates Asian crush capacity and navigates complex origin-sustainability certification requirements.
Soybean derivatives encompass the refined, fractionated, and chemically modified outputs of Glycine max processing, including protein concentrates with minimum 65% protein content, degummed and refined oils, and phospholipid-rich lecithin extracted through hexane or aqueous methods. These materials serve as functional ingredients, nutritional inputs, and industrial feedstocks across food, feed, and non-food applications. Soy protein isolates command premium positioning in food-grade applications where emulsification and water-binding properties determine formulation economics. Soy lecithin represents the fastest-growing product category as pharmaceutical and nutraceutical manufacturers adopt it for liposomal delivery systems. Feed-grade soy oil maintains mature volume throughput but faces margin compression from alternative lipid sources.
The USDA enforces country-of-origin labeling and grading standards that shape export eligibility and price discovery for U.S. soybean derivatives. The EU Green Deal and EUDR deforestation regulation are forcing supply chain restructuring for European-bound soy products, requiring geolocation traceability and compliance documentation. China's GB standards and import quarantine protocols administered by SAMR determine market access timing and specification requirements for foreign suppliers. Stakeholders must monitor evolving sustainability certification thresholds and their cascading effects on procurement premiums and supplier qualification costs.
Market Dynamics
EU Green Deal deforestation regulations are forcing supply chain restructuring across the soybean derivatives sector, compelling processors to invest in geolocation traceability systems and compliance documentation infrastructure that reshapes procurement economics.
Growth Catalysts
- Aquaculture Feed Expansion:China's expanding aquaculture sector is concentrating demand for high-protein soy meal formulations. SAMR import protocols are streamlining entry for certified suppliers meeting GB standards.
- Plant-Based Protein Mandates:Brazil's food manufacturers are expanding soy protein procurement for meat alternatives. ANVISA food safety frameworks support ingredient innovation in processed foods.
- Liposomal Delivery Adoption:Pharmaceutical manufacturers are integrating soy lecithin into drug delivery systems. Hexane-extracted phospholipid fractions command premium positioning in nutraceutical formulations.
Market Restraints
- Input Cost Volatility:Crush margin compression from weather-driven soybean price swings constrains processor profitability. Argentine drought cycles disrupt South American origination reliability.
- Regulatory Friction:EUDR geolocation documentation requirements impose supplier qualification costs that disadvantage smaller crushing operations. EU-bound shipments face extended compliance timelines.
- Substitution Threat:Alternative lipid sources including palm oil and canola oil displace feed-grade soy oil in ruminant nutrition. Rendered fats and synthetic amino acids erode protein meal volumes.
Strategic Opportunities
- Underpenetrated Nutrition Markets:India's FSSAI regulatory alignment creates entry pathways for soy protein isolates in fortified foods. BIS standardization supports ingredient grade certification.
- Regulatory Tailwind:China's dual carbon goals accelerate demand for plant-based protein as livestock emission reduction strategy. MEE enforcement tightens feed-to-farm traceability.
- Technology Convergence:Aqueous extraction methods combined with membrane filtration enable cleaner-label lecithin production. Food-grade applications absorb premium fractions previously diverted to industrial uses.
Industry Challenges
- Traceability System Integration:Geolocation data collection across fragmented smallholder networks in Brazil and Argentina strains IT infrastructure. Farm-level compliance documentation requires processor investment in mobile data platforms.
- Certification Timeline Compression:EUDR delegated act implementation deadlines compress supplier audit cycles. Third-party sustainability verification bottlenecks delay European market access.
- Skill Scarcity in Fractionation:Specialized protein isolate processing expertise concentrates at major crushing complexes. Regional facilities face recruitment competition for chemical engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soybean Derivatives Market |
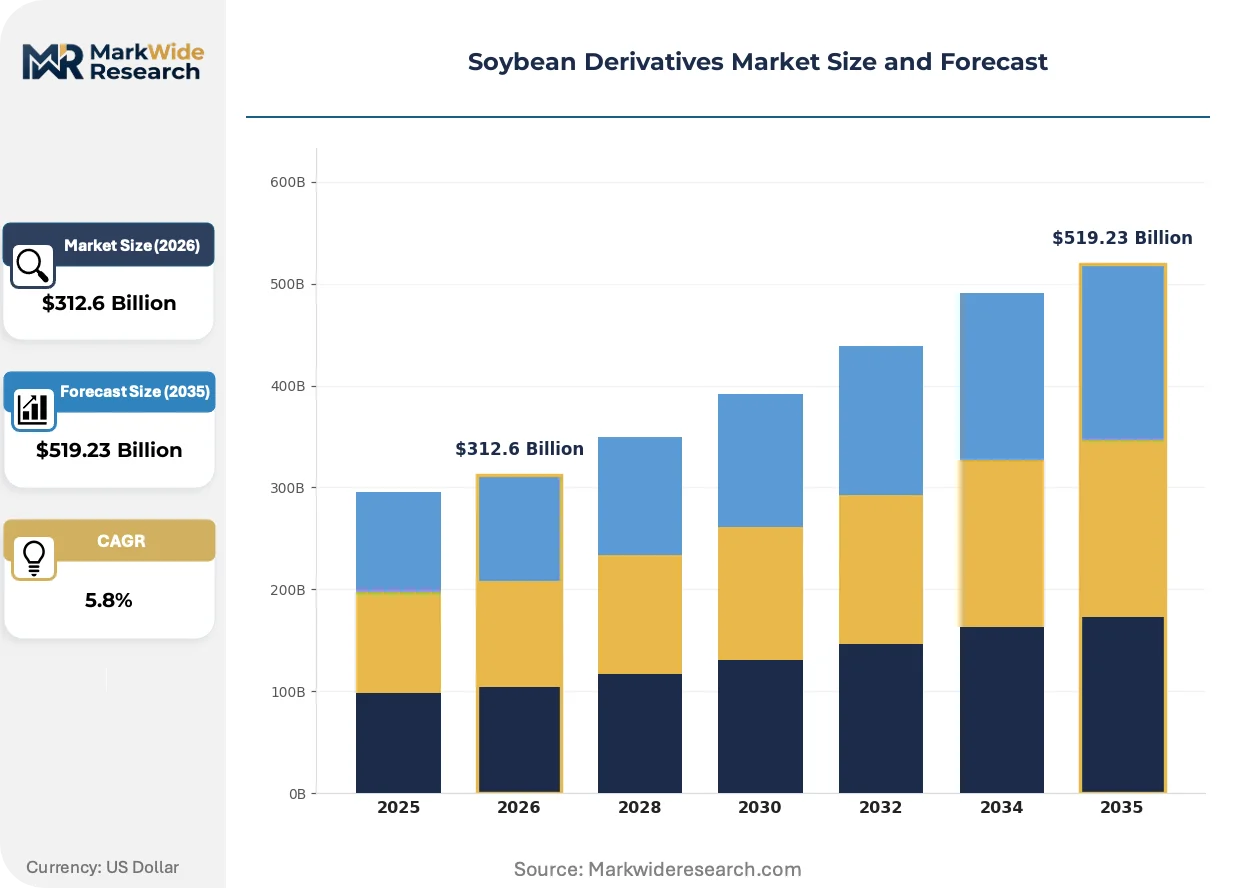
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $519.23 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Soy Oil, Soy Lecithin, Soy Flour Application: Food & Beverage, Animal Feed, Personal Care, Industrial Grade: Food Grade, Feed Grade, Pharmaceutical Grade, Industrial Grade End User: Food Manufacturers, Feed Producers, Cosmetics Companies, Biofuel Industries |
| Companies Covered | Louis Dreyfus Company, CHS Inc, Archer Daniels Midland Company, Fuji Oil Holdings Inc, AG Processing Inc, Cargill, Wilmar International Limited, The Scoular Company, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soybean Derivatives Market Emerging Trajectories
Processing technology advances and regulatory traceability mandates are converging to reshape competitive positioning in soybean derivatives, with sustainability certification emerging as the primary axis of supplier differentiation.
Membrane filtration systems for aqueous protein extraction are rendering obsolete conventional hexane-based isolate production in premium food-grade applications. European ingredient formulators are accelerating adoption to meet clean-label procurement specifications from retail brand owners. The technology is compressing capital recovery timelines for processors investing in dual-stream oil and protein fractionation.
REACH chemical registration requirements and EUDR deforestation regulations are tightening documentation standards for European-bound soy derivatives. Processors must now maintain chain-of-custody records from farm gate to final formulation. The compliance burden falls most heavily on traders lacking integrated crushing and origination assets.
Brand-owner sustainability scorecards are reshaping supplier selection criteria in food manufacturing procurement. Third-party certified deforestation-free soy commands contract premiums over conventional supply in European and North American formulations. The shift is most visible in meat-alternative product lines where ESG marketing claims drive ingredient sourcing decisions.
Soybean Derivatives Market Segmentation
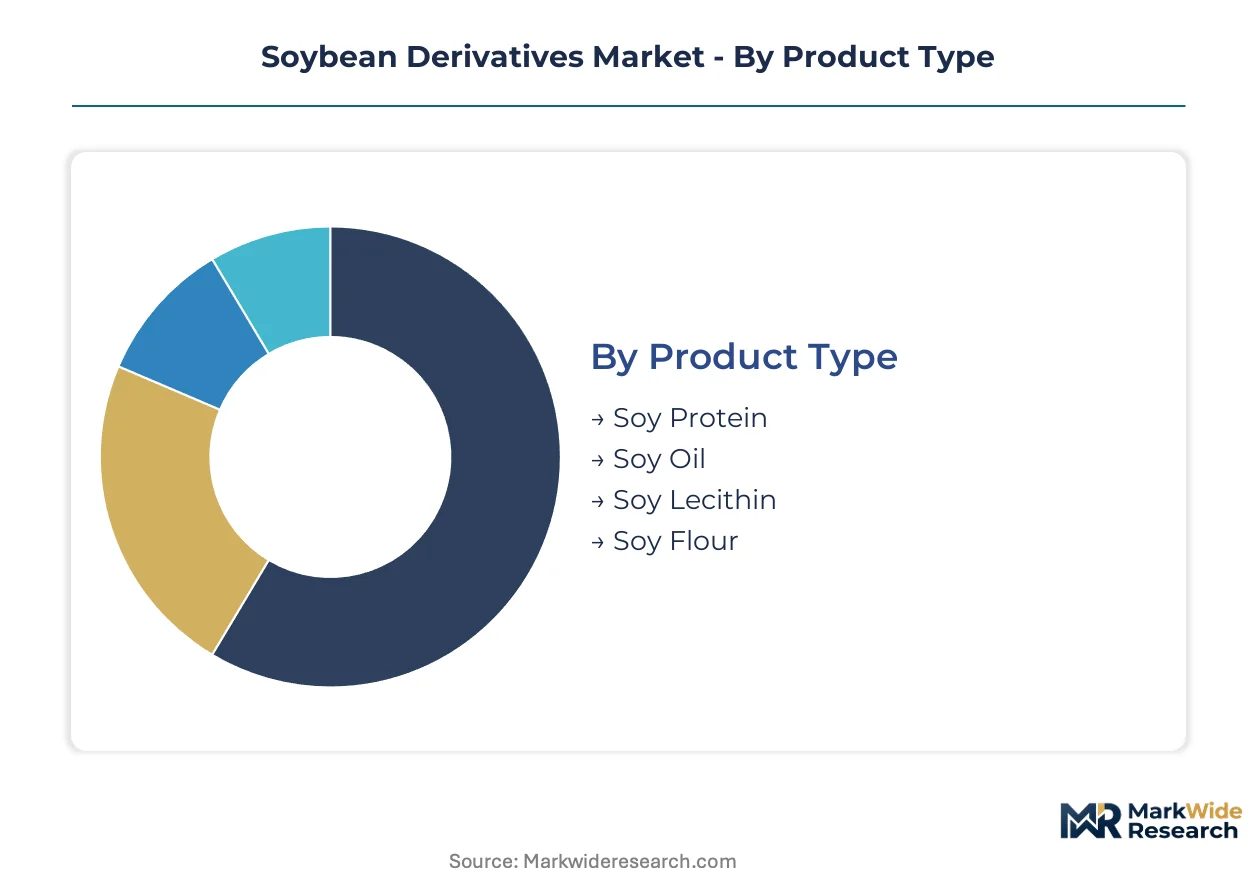
Soybean derivatives fragment across four intersecting dimensions that determine formulation economics and procurement premiums. Product type governs margin structure, while application and grade specifications dictate regulatory compliance burdens. End-user concentration shapes contract volumes and technical service intensity.
Product Type:
After-sales technical support intensity varies dramatically across protein, oil, and phospholipid fractions, with food-grade isolates demanding sustained formulation assistance.
- Soy Protein:Concentrates and isolates deliver minimum 65% protein content with functional emulsification and water-binding properties. China's expanding aquaculture feed sector concentrates demand for high-protein meal formulations meeting SAMR import protocols. Brazil's food manufacturers expand procurement for meat-alternative applications under ANVISA frameworks.
- Soy Lecithin:Hexane-extracted or aqueous-processed phospholipid fractions serve pharmaceutical liposomal delivery systems and food emulsification. Pharmaceutical manufacturers in Europe adopt these fractions for drug delivery, commanding premium positioning in nutraceutical formulations under EMA guidance.
- Soy Oil:Degummed and refined grades serve food frying, feed energy supplementation, and industrial oleochemical feedstocks. Argentine drought cycles disrupt origination reliability for bulk oil shipments.
- Soy Flour:Full-fat and defatted milled fractions provide baking functionality and protein fortification at lower cost tiers. Indian FSSAI alignment creates entry pathways for fortified food applications.
By volume, soy oil leads. By growth pace, soy lecithin is ahead.
Application:
Cost tier stratification separates commodity feed applications from premium food and pharmaceutical formulations with diverging margin profiles.
- Food & Beverage:Plant-based meat alternatives, dairy analogs, and bakery applications absorb protein isolates and lecithin emulsifiers. EU Green Deal deforestation regulations force supply chain restructuring for European-bound formulations.
- Animal Feed:High-protein meal and extracted oil serve aquaculture, poultry, and swine nutrition. China's dual carbon goals accelerate plant-based protein demand as livestock emission reduction strategy under MEE enforcement.
- Personal Care:Lecithin fractions function as natural emollients and delivery vehicles in cosmetic formulations. Clean-label procurement specifications from retail brand owners drive aqueous extraction adoption.
- Industrial:Biodiesel feedstock, lubricants, and oleochemical precursors utilize refined oil and fatty acid derivatives. Rendered fats and alternative lipids displace feed-grade volumes in ruminant applications.
Feed applications dominate tonnage. Food and beverage formulations capture value expansion.
Grade:
Customer type segmentation separates commodity buyers from specification-intensive pharmaceutical and food manufacturers with distinct qualification requirements.
- Food Grade:Refined isolates, concentrates, and lecithin meeting EFSA and FDA purity standards for direct human consumption. Membrane filtration systems render hexane-based production obsolete in premium European applications.
- Feed Grade:Meal and oil fractions optimized for amino acid profiles and energy density in animal nutrition. Crush margin compression from weather-driven soybean price swings constrains processor profitability.
- Pharmaceutical Grade:Ultra-pure lecithin fractions for liposomal drug delivery and parenteral formulations. REACH chemical registration requirements tighten documentation standards for European-bound shipments.
- Industrial Grade:Technical specifications for biodiesel, adhesives, and coating applications with minimal refinement. Alternative lipid sources including palm oil displace volumes in non-food oleochemical uses.
Feed grade moves the most volume. Pharmaceutical grade commands the steepest premium expansion.
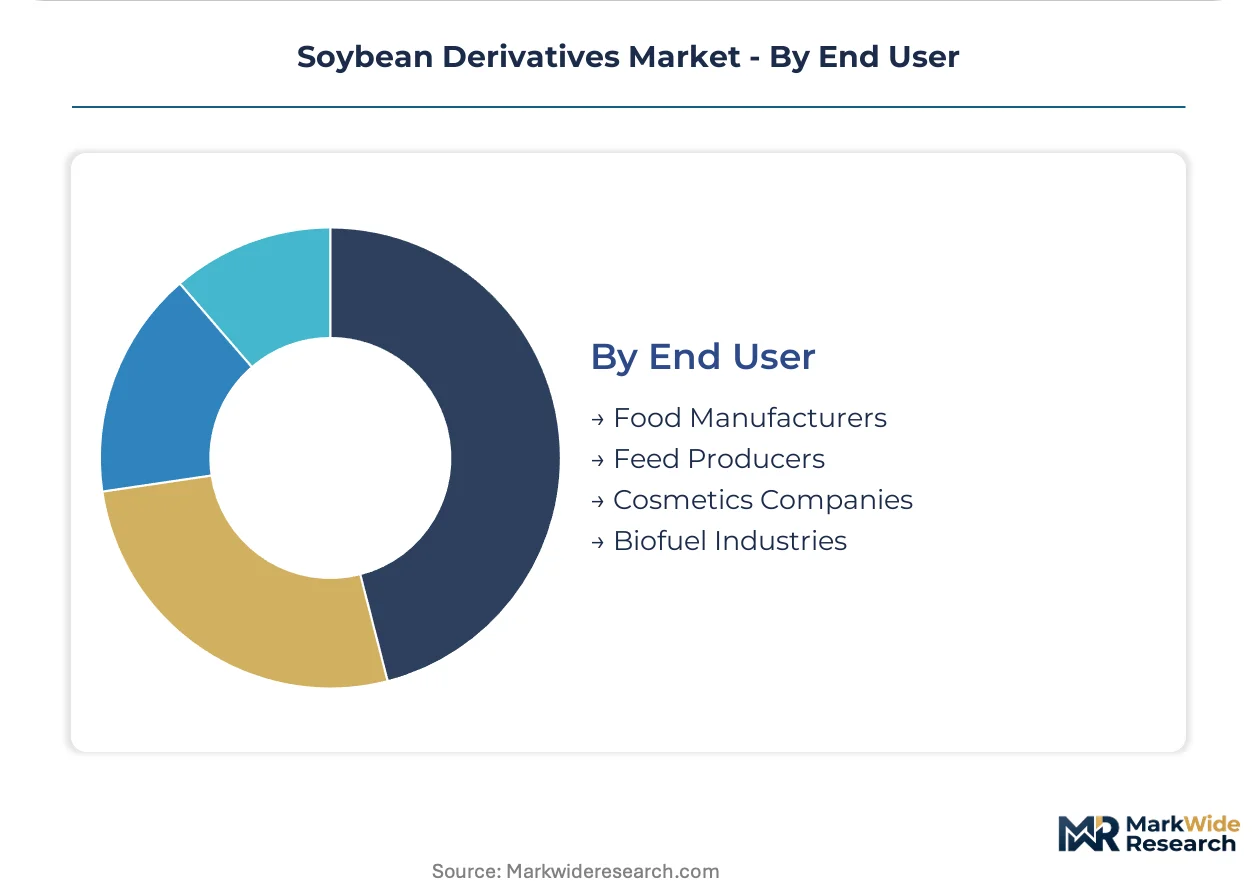
End User:
Supply concentration aligns with crushing complex proximity, favoring integrated processors over merchant traders for high-specification accounts.
- Food Manufacturers:Meat-alternative specialists and bakery formulators procure isolates and functional flours. Brand-owner sustainability scorecards reshape supplier selection criteria in European and North American procurement.
- Feed Producers:Aquaculture compounders and integrated livestock operations source protein meals and extracted oils. Geolocation traceability systems strain IT infrastructure across fragmented smallholder networks.
- Cosmetics Companies:Natural and clean-label formulators specify aqueous-extracted lecithin for emollient applications. Third-party certified deforestation-free soy commands contract premiums in ESG-marketed product lines.
- Biofuel Industries:Renewable diesel and biodiesel producers utilize refined oil and fatty acid methyl esters. USDA country-of-origin labeling shapes export eligibility and price discovery for U.S. derivatives.
Feed producers absorb the largest tonnage. Cosmetics companies drive the fastest specification upgrading.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese aquaculture feed compounders exhibit the lowest price elasticity, absorbing premium protein isolates regardless of cost fluctuations, while European food manufacturers face acute margin compression from EUDR compliance investments.
China
Dual carbon goals under MEE enforcement accelerate plant-based protein procurement for livestock emission reduction. SAMR import protocols streamline entry for certified suppliers meeting GB standards. Yangtze River Delta crushing complexes concentrate aqueous extraction capacity for pharmaceutical-grade lecithin.
Brazil
Food manufacturers expand soy protein procurement for meat-alternative formulations under ANVISA frameworks. EU Green Deal deforestation regulations force geolocation traceability investments across Mato Grosso and Pará supply sheds. São Paulo-based processors anchor integrated oilseed-to-ingredient production networks.
United States
USDA country-of-origin labeling shapes export eligibility and price discovery for crush-origin derivatives. EPA biofuel mandates sustain demand for refined oil in renewable diesel applications. Iowa and Illinois crushing corridors concentrate protein isolate capacity serving North American food manufacturers.
Germany
REACH chemical registration requirements tighten documentation standards for pharmaceutical-grade lecithin shipments. EFSA purity standards govern food-grade isolate procurement from third-country suppliers. Hamburg port infrastructure anchors European import and re-export logistics for oilseed derivatives.
India
FSSAI regulatory alignment creates entry pathways for soy protein isolates in fortified foods and nutritional applications. BIS standardization supports ingredient grade certification for domestic formulators. Maharashtra and Gujarat processing clusters expand solvent extraction capacity for edible oil and meal production.
Soybean Derivatives Market Vendor Landscape
Capability concentration sits with integrated processors commanding origination-to-formulation control; scale advantage sits with merchant traders leveraging arbitrage across dislocated regional markets. The vendor base stratifies into three tiers: multinational agribusiness conglomerates with captive crushing networks, regional specialists dominating single-origin sustainability certification, and toll processors serving brand-owner private label requirements. Dominant competitive moves include backward integration into farm-level traceability systems and portfolio diversification into pharmaceutical-grade phospholipid fractions.
Among North American agribusiness conglomerates, Archer Daniels Midland Company and Cargill exemplify the integrated processor archetype, anchoring positions through captive origination networks and food ingredient formulation capabilities. Wilmar International Limited represents the Asian crush capacity leader, navigating complex origin-sustainability certification requirements across fragmented supplier bases. These three entities occupy positions that define competitive intensity for premium-tier protein isolates and pharmaceutical-grade lecithin fractions.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| CHS Inc |
| Archer Daniels Midland Company |
| Fuji Oil Holdings Inc |
| AG Processing Inc |
| Cargill |
| Wilmar International Limited |
| The Scoular Company |
| Bunge Limited |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European pharmaceutical-grade lecithin fractionation drives aggressive capacity expansion announcements from Asian processors while simultaneously elevating spot premiums for EU-bound shipments. Crush margin volatility across Argentine and Brazilian origination zones feeds directly into processor pricing posture, with integrated operators leveraging captive soybean supply to maintain contract stability against merchant traders exposed to spot meal and oil swings.
Pricing Analysis
After-sales technical support contracts for food-grade protein isolate formulation assistance generate lifetime value multiples exceeding base ingredient sales. Three-tier pricing structure across pharmaceutical, food, and feed grades separates premium lecithin fractions from standard isolates and commodity meal. Pricing pressure stems from alternative lipid sources including palm oil and rendered fats displacing feed-grade soy oil volumes. Feed compounders exhibit highest price sensitivity, while pharmaceutical manufacturers absorb premium positioning regardless of cost fluctuations.
Supply Chain Analysis
Extended payment terms from integrated processors to Brazilian and Argentine farm cooperatives strain working capital across Mato Grosso and Pará supply sheds. Raw material flows draw from US Midwest crushing corridors, Brazilian Cerrado origination zones, and Argentine Pampas production belts. Single-source vulnerability concentrates in Yangtze River Delta aqueous extraction capacity for pharmaceutical-grade fractions. Distribution runs through Hamburg port infrastructure for European re-export and Shanghai customs clearance for Asia-Pacific formulation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainability certification services and geolocation traceability documentation represent the fastest-expanding recurring-revenue layer, outpacing base crushing and fractionation margins as EU Green Deal compliance mandates deepen.
For Market Incumbents: Insulate origination advantages through backward integration into farm-level traceability systems across Brazilian Mato Grosso supply sheds. Expand aqueous extraction capacity for pharmaceutical-grade lecithin before technology convergence renders hexane-based production obsolete in premium European applications. Regulatory friction from EUDR delegated act deadlines compresses supplier audit cycles, favoring operators with existing compliance infrastructure. For New Entrants and Emerging Players: Pursue toll processing arrangements for brand-owner private label requirements in Indian fortified food applications under FSSAI-aligned pathways. India's underpenetrated nutrition markets offer lowest competitive density for soy protein isolate entry. Partner with established crushing complexes to bypass capital-intensive fractionation infrastructure while building formulation expertise. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional specialists dominating single-origin sustainability certification with integrated traceability platforms. Long-term viability centers on processors controlling origination-to-formulation value chains rather than merchant traders exposed to arbitrage compression. Monitor EUDR implementation enforcement intensity as the critical inflection signal for procurement premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farm-Level Traceability | EUDR geolocation requirements force processor investment in mobile data platforms across Brazilian smallholder networks. |
| Aqueous Extraction Capacity Expansion | Membrane filtration systems enable cleaner-label lecithin production meeting EFSA purity standards for European pharmaceutical formulators. |
| Pharmaceutical-Grade Fractionation Investment | Liposomal delivery adoption by EMA-regulated manufacturers commands premium positioning for hexane-extracted phospholipid fractions. |
| Sustainability Certification Program Development | Third-party verified deforestation-free soy captures contract premiums in ESG-marketed meat-alternative product lines. |
| Joint Venture in Indian Processing Infrastructure | FSSAI regulatory alignment and BIS standardization create entry pathways for soy protein isolates in fortified foods. |
Methodological Framework
Operator-level perspectives from crushing plant managers, food manufacturer procurement leads, pharmaceutical formulation scientists, and sustainability certification auditors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through USDA country-of-origin labeling records, EU Green Deal delegated act documentation, SAMR import protocol filings, and customs trade data. Bottom-up volume modeling from individual crushing complex capacities triangulated against top-down demand estimates from end-use sector consumption patterns.
Scenario-bracketing around regulatory implementation timelines and climate-driven origination volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application grade, end-user concentration, and regional regulatory cluster. CAGRs derived from weighted average growth rates across these segments, with specific inputs from crush margin optimization trends and pharmaceutical liposomal delivery adoption curves.
Sensitivities concentrate around EUDR enforcement intensity, Argentine drought cycle frequency, and alternative lipid substitution rates in ruminant nutrition. Forecasts reflect documented assumptions on regulatory implementation and technology diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Blood Meal Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Europe Feed Amino Acids Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Beet Pulp Pellets Market
Agricultural Commodities
Straw Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Cottonseed Hulls Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Middle East Feed Amino Acids Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
Feed Sucrose Market