
 Middle East Feed Amino Acids Market | 2026-2036
Middle East Feed Amino Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Amino Acids Market Outlook
Formulation-as-a-service is pivoting how amino acid suppliers engage Middle East feed mills, shifting transactions from bulk commodity sales to precision premix subscriptions tied to flock performance metrics. Evonik Industries AG leverages its methionine analog portfolio to anchor long-term supply contracts with Gulf poultry integrators. Cargill, Incorporated competes through its regional premix network, while DSM-Firmenich AG differentiates via its enzyme-amino acid synergies for heat-stressed birds.
Feed amino acids are crystalline or purified organic compounds containing amino and carboxyl functional groups, produced through fermentation of carbohydrate feedstocks or chemical synthesis, with minimum purity thresholds typically exceeding 98.5 percent for lysine and methionine grades used in commercial formulations. Their primary purpose is to precisely balance the amino acid profile of compound feeds, correcting deficiencies in locally sourced ingredients such as corn gluten or soybean meal to optimize nitrogen retention and reduce crude protein waste. Lysine dominates volume flows across the Middle East due to its role as the first limiting amino acid in corn-soy poultry diets, while methionine commands premium positioning because synthetic dl-methionine and hydroxy analog production remains concentrated among a handful of technology holders. Fermentation-derived threonine and tryptophan represent faster-growing niches as least-cost formulation software penetrates mid-sized Saudi and Egyptian feed mills.
The Saudi Food and Drug Authority enforces feed additive registration and Good Manufacturing Practice compliance for all imported amino acid products, while the Gulf Standardization Organization harmonizes maximum contaminant limits across GCC states. Egypt's Ministry of Agriculture and Land Reclamation operates parallel import licensing for fermentation-derived feed additives, creating a dual-track regulatory environment that shapes supplier market access strategies. Stakeholders must monitor evolving halal certification requirements for fermentation substrates and the potential extension of carbon intensity disclosures to feed ingredient supply chains.
Market Dynamics
Precision formulation software is compressing procurement cycles across Middle East feed mills, shifting amino acid purchasing from annual bulk contracts to algorithm-driven, flock-performance-tied subscriptions that demand real-time technical support.
Growth Catalysts
- SFDA Feed Safety Mandates:The Saudi Food and Drug Authority's tightened maximum residue limits are compelling integrators to adopt certified amino acid premixes, creating compliance-driven replacement demand.
- Controlled-Environment Poultry Expansion:Vertically integrated producers in Saudi Arabia's central corridor are scaling house capacities, multiplying tonnage requirements for lysine and methionine fortification.
- Fermentation Substrate Diversification:Advances in halal-certified carbohydrate feedstocks are expanding supplier eligibility for Gulf markets previously constrained by religious certification barriers.
Market Restraints
- Crude Glycerol Price Volatility:Methionine analog production depends on glycerol availability, and spot market swings in this petrochemical derivative compress margin predictability for formulators.
- Technology Holder Concentration:Synthetic dl-methionine and hydroxy analog manufacturing remains captive to a handful of European and Asian producers, creating supply security anxiety among Gulf integrators.
- Dual-Track Egyptian Licensing:Egypt's Ministry of Agriculture and Land Reclamation operates parallel import authorization tracks for fermentation-derived additives, extending market access timelines by 8-14 months versus GCC neighbors.
Strategic Opportunities
- Mid-Sized Saudi Feed Mill Digitization:Least-cost formulation software penetration below the top-tier integrator level creates white space for amino acid suppliers offering bundled technical service subscriptions.
- Enzyme-Amino Acid Convergence:Heat-stress formulations combining exogenous enzymes with crystalline amino acids address performance losses in Gulf summer conditions, commanding premium positioning.
- Carbon Intensity Disclosure Extension:Anticipated supply chain emissions reporting requirements for EU-exporting Gulf poultry producers will favor fermentation-derived amino acids with verifiable low-carbon credentials.
Industry Challenges
- Halal Certification Complexity:Fermentation substrate traceability requirements for religious compliance demand dedicated audit trails that strain legacy supplier documentation systems.
- Technical Talent Scarcity:Gulf feed mills face acute shortages of nutritionists capable of operating precision formulation platforms, forcing suppliers to embed field technical staff at customer sites.
- Reformulation Cycle Compression:Raw ingredient price volatility in corn and soybean meal markets is accelerating diet recalculation frequency, stretching amino acid inventory management capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Amino Acids Market |
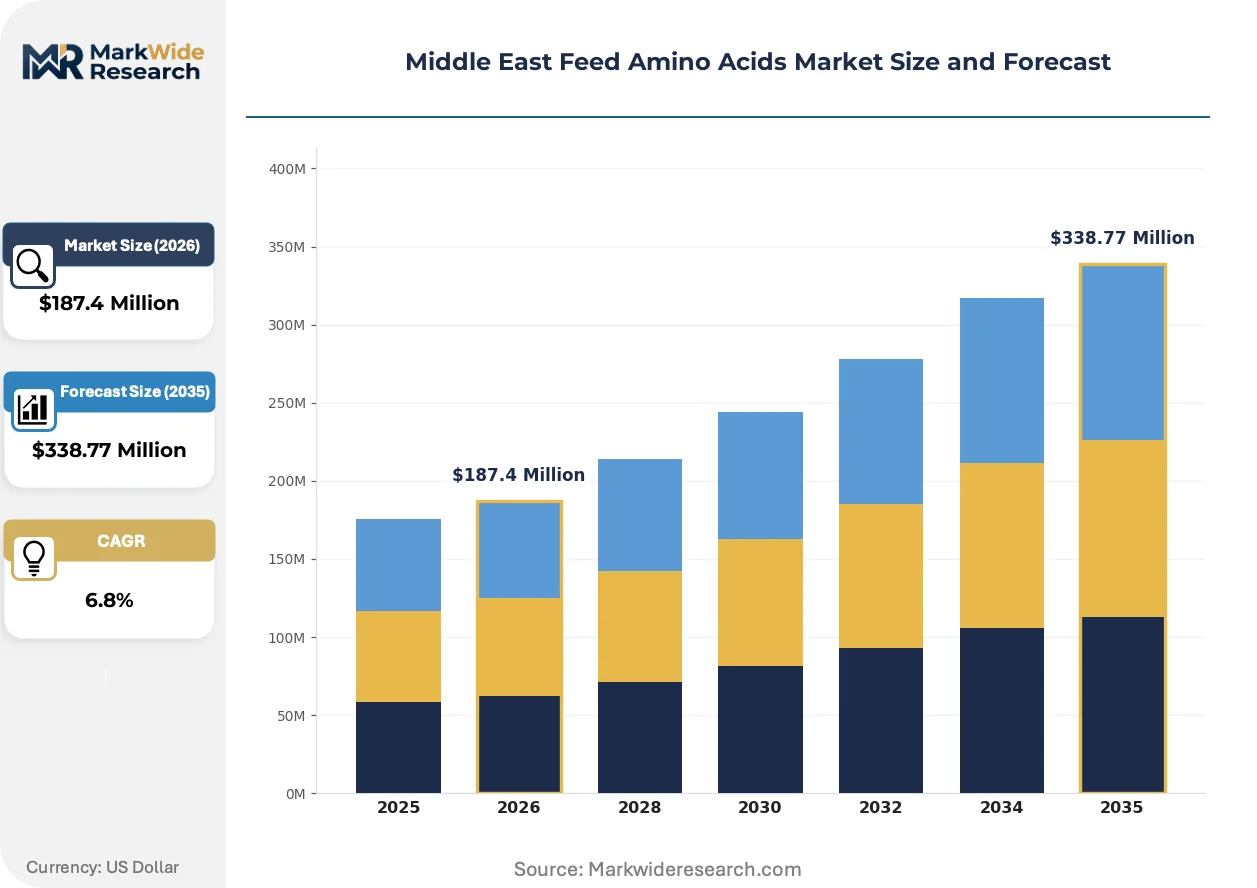
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lysine, Methionine, Threonine, Tryptophan Source: Animal-Based, Plant-Based, Synthetic, Fermentation Application: Poultry Nutrition, Ruminant Nutrition, Aquaculture, Pet Food Form: Powder, Liquid, Granular, Pellet |
| Companies Covered | Adisseo, Alltech, Inc., Archer Daniels Midland Co., Evonik Industries AG, IFF (Danisco Animal Nutrition), Ajinomoto Co., Inc., DSM-Firmenich AG, Cargill, Incorporated, CJ CheilJedang Corp, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Amino Acids Market Strategic Shifts
Bioprocess engineering advances and regulatory disclosure mandates are converging to transform how amino acid suppliers demonstrate value, shifting competitive differentiation from purity specifications to verified sustainability credentials and flock-performance outcomes.
Continuous fermentation monitoring using spectroscopic in-line analytics is rewriting process control economics for threonine and tryptophan production. Saudi and Emirati integrators adopting these higher-purity fermentation grades are reducing dietary crude protein levels by 1.5-2.0 percentage points. This protein reduction is compressing nitrogen excretion volumes and easing environmental compliance burdens for large-scale controlled-environment operations.
The Gulf Standardization Organization's harmonized maximum contaminant limits are forcing feed additive registration consolidation across GCC states. Suppliers previously navigating six distinct national filing procedures now face unified testing protocols and centralized certification pathways. Egyptian operators remain outside this harmonization, maintaining separate SFDA-aligned documentation requirements that fragment regional supply chain planning.
Poultry integrators are unbundling amino acid procurement from compound feed purchasing, establishing direct supplier relationships that bypass traditional feed mill intermediaries. This channel disintermediation concentrates volume with technology-holding manufacturers capable of delivering flock-specific premix formulations. The shift is most visible among Saudi Arabia's top-five vertically integrated producers, which now contract amino acid supply independently of their compound feed sourcing arrangements.
Middle East Feed Amino Acids Market Segmentation
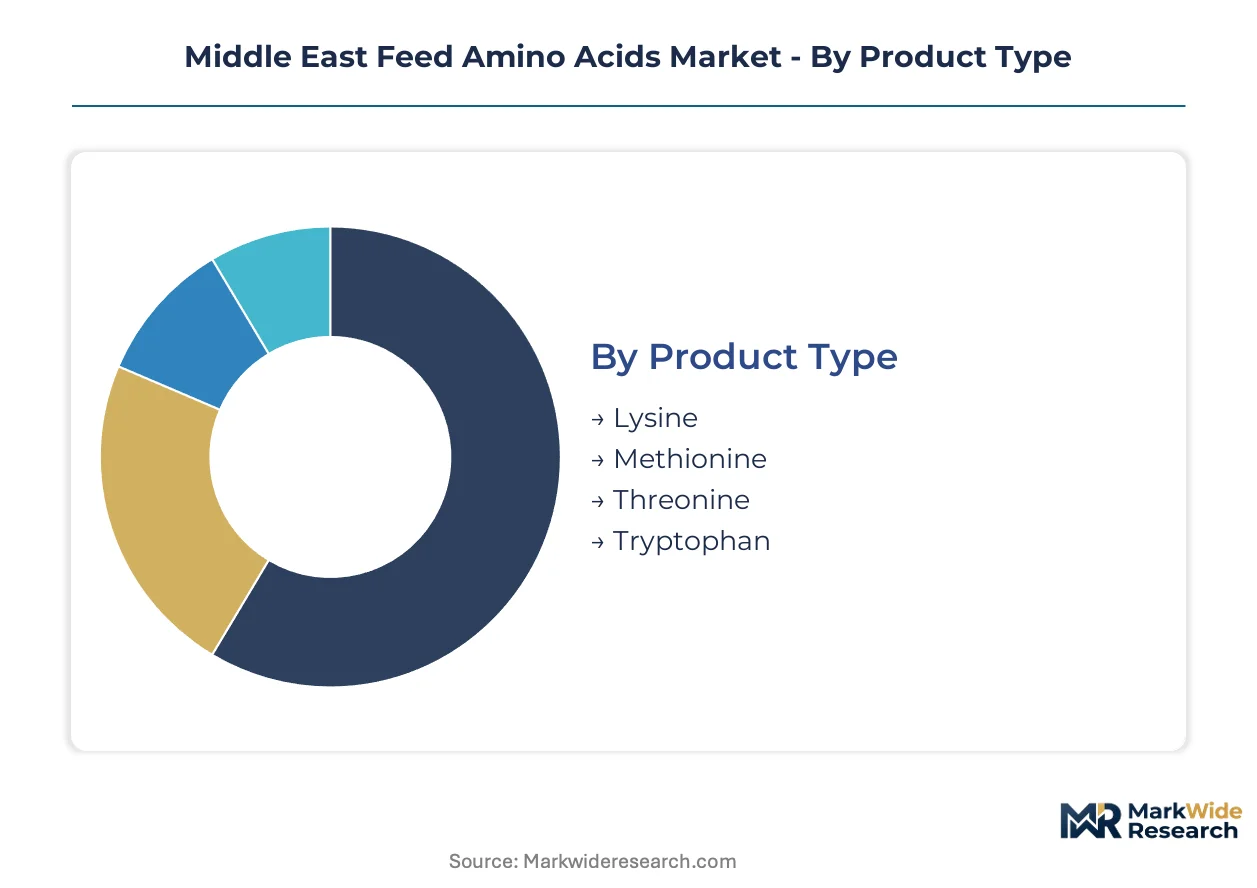
Segmentation in Middle East feed amino acids determines which certification pathways suppliers must navigate and where formulation complexity concentrates. Product type and source classifications dictate halal compliance burdens, while application segments reveal divergent performance requirements across species-specific nutrition protocols.
Product Type:
SFDA registration requirements vary sharply by molecular complexity, with synthetic amino acids facing stricter residue documentation than fermentation-derived alternatives. Lysine and methionine carry the heaviest regulatory scrutiny due to their volume dominance in poultry integrator procurement.
- Lysine:Crystalline L-lysine monohydrochloride, typically 98.5% purity minimum, serves as the first limiting amino acid in corn-soy poultry diets across Saudi Arabia's central corridor. Demand concentrates with vertically integrated broiler producers scaling controlled-environment houses, where precise lysine fortification directly governs feed conversion ratios and nitrogen retention efficiency.
- Methionine:Available as DL-methionine, liquid hydroxy analog (MHA), or MHA-FA calcium salt, this segment commands premium positioning due to technology-holder concentration among European and Asian manufacturers. Saudi and UAE poultry integrators prioritize methionine analogs for their superior bioavailability in heat-stressed flocks, though crude glycerol price volatility compresses margin predictability for regional formulators.
- Threonine:Fermentation-derived L-threonine enables crude protein reduction strategies in Egyptian and Saudi feed mills adopting least-cost formulation software.
- Tryptophan:Crystalline L-tryptophan addresses deficiency correction in low-protein diet formulations, gaining traction among mid-sized Saudi mills digitizing procurement cycles.
Leading the category by volume: Lysine. Growing fastest: Tryptophan.
Source:
Cost tier stratification separates premium fermentation grades from commodity synthetic production, with halal certification premiums widening price spreads in Gulf markets.
- Synthetic:Chemically synthesized amino acids via Strecker or hydantoin processes deliver consistent purity at scale, dominating methionine supply chains. Saudi Food and Drug Authority mandates detailed impurity profiling for synthetic grades, extending registration timelines versus fermentation alternatives.
- Fermentation:Microbial cultivation using Corynebacterium glutamicum or Escherichia coli strains on carbohydrate substrates produces lysine, threonine, and tryptophan. Egyptian operators face dual-track licensing through the Ministry of Agriculture and Land Reclamation, creating 8-14 month delays versus GCC harmonized pathways.
- Plant-Based:Protein hydrolysates from soybean or wheat gluten provide amino acid complexes rather than crystalline isolates, serving niche organic feed formulations.
- Animal-Based:Hydrolyzed feather meal and fish protein concentrates supply amino acids in crude form, constrained by halal certification complexity and maximum residue limits.
Lowest cost position: Synthetic. Steepest expansion trajectory: Fermentation.
Application:
Customer type differentiation separates high-volume integrator contracts from fragmented aquaculture and pet food procurement, with technical service intensity varying accordingly.
- Poultry Nutrition:Broiler and layer diets absorb the majority of crystalline amino acid tonnage across Saudi Arabia and the UAE, driven by controlled-environment expansion and precision formulation adoption. Vertically integrated producers now contract amino acid supply independently of compound feed sourcing, concentrating volume with technology-holding manufacturers capable of flock-specific premix delivery.
- Ruminant Nutrition:Dairy and beef feedlot applications utilize rumen-protected methionine and lysine formulations, with demand clustering in Jordanian and Lebanese dairy operations.
- Aquaculture:Marine and freshwater fish diets require precise amino acid balancing for protein-sparing effects, though regional aquaculture scale remains limited versus poultry.
- Pet Food:Premium companion animal nutrition drives small-volume demand for high-purity tryptophan and taurine co-formulations.
Highest volume concentration: Poultry Nutrition. Gaining share fastest: Aquaculture.
Form:
Supply concentration dynamics favor powder and liquid production infrastructure, with granular and pellet investments concentrated among Gulf premix specialists.
- Powder:Crystalline amino acids in powder form dominate bulk commodity flows, preferred by large Saudi feed mills with automated handling systems and precision dosing equipment.
- Liquid:Methionine hydroxy analog in aqueous or oil-based suspensions enables uniform distribution in total mixed rations, with Evonik Industries AG anchoring long-term supply contracts through liquid delivery systems.
- Granular:Agglomerated particles reduce dust generation and improve flowability, addressing occupational safety requirements in Egyptian milling operations.
- Pellet:Extruded amino acid premixes integrate with compound feed pelleting lines, serving smaller Saudi mills lacking independent micro-ingredient handling capacity.
Dominant form by tonnage: Powder. Climbing fastest: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's central corridor hosts the densest concentration of vertically integrated poultry operations in the Middle East, with controlled-environment houses driving concentrated demand for lysine and methionine fortification.
Saudi Arabia
Vertically integrated poultry producers in Riyadh and the Eastern Province are scaling controlled-environment house capacities, multiplying tonnage requirements for crystalline amino acids. The Saudi Food and Drug Authority enforces tightened maximum residue limits and feed additive registration protocols, compelling integrators to adopt certified premix formulations. Al-Qassim and Hail regions host expanding broiler operations where precision formulation software is compressing procurement cycles from annual bulk contracts to flock-performance-tied subscriptions.
United Arab Emirates
Dubai and Abu Dhabi poultry integrators prioritize methionine analogs for heat-stressed flocks, with premium positioning for bioavailable grades in summer formulations. The Ministry of Climate Change and Environment aligns with Gulf Standardization Organization harmonized contaminant limits, streamlining additive registration across emirates. Sharjah's feed milling cluster is adopting least-cost formulation platforms that demand real-time technical support from amino acid suppliers.
Egypt
Cairo and the Nile Delta concentrate fermentation-derived threonine demand as mid-sized feed mills digitize procurement cycles. The Ministry of Agriculture and Land Reclamation operates parallel import licensing tracks for fermentation-derived additives, creating 8-14 month delays versus GCC neighbors. Alexandria's port infrastructure handles bulk amino acid flows while local formulators navigate dual-track regulatory complexity.
Jordan
Amman and the northern highlands cluster dairy operations utilizing rumen-protected methionine and lysine formulations for beef and dairy feedlots. The Jordan Food and Drug Administration maintains SFDA-aligned registration requirements, easing supplier market access for Saudi-certified products. Irbid's agricultural processing zone hosts regional premix blending capacity serving Levantine markets.
Kuwait
Kuwait City's integrated poultry producers contract amino acid supply independently of compound feed sourcing, concentrating volume with technology-holding manufacturers. The Public Authority for Food and Nutrition applies Gulf Standardization Organization unified testing protocols for feed additive registration. Al-Jahra's expanding controlled-environment poultry facilities are driving methionine analog demand for heat-stress formulations.
Middle East Feed Amino Acids Market Competitive Environment
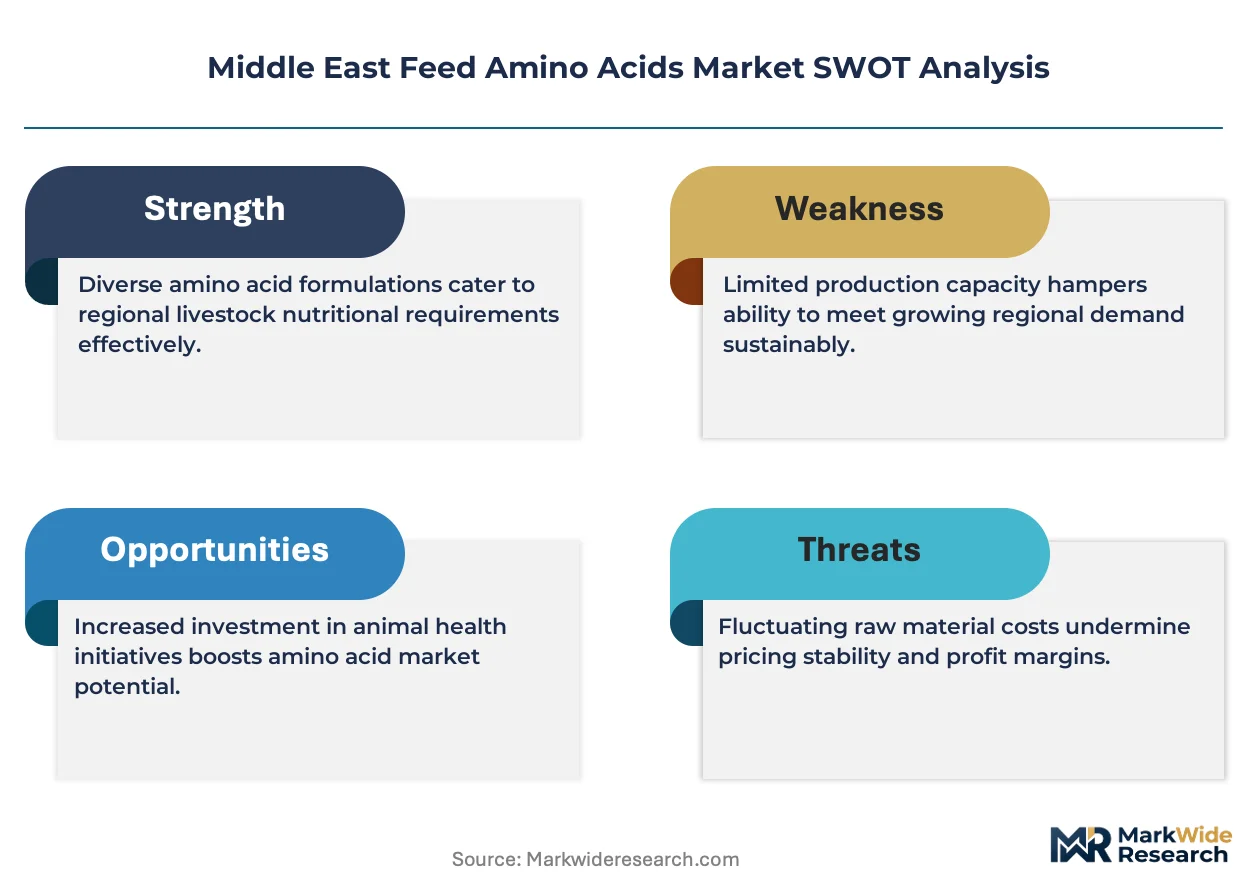
Capital-heavy fermentation producers compete with asset-light formulation specialists across Middle East supply chains. Technology holders anchor long-term supply contracts through captive methionine analog production, while regional premix networks compete on technical service intensity. Three archetypes dominate: European-Asian technology holders with synthetic production assets, Gulf premix specialists with embedded field technical staff, and diversified agribusiness conglomerates with backward integration into amino acid sourcing. Competitive moves concentrate on strategic partnerships with poultry integrators and geographic expansion through localized blending capacity.
Within the technology-holder tier, Evonik Industries AG and DSM-Firmenich AG represent European-anchored manufacturers with concentrated methionine and enzyme-amino acid synergies portfolios. Cargill, Incorporated exemplifies the diversified agribusiness archetype, competing through regional premix networks and captive supply relationships. Among Asian fermentation specialists, Ajinomoto Co., Inc. and CJ CheilJedang Corp occupy positions tied to lysine, threonine, and tryptophan production scale. Adisseo and Alltech, Inc. sit within the nutrition-specialist segment, while Archer Daniels Midland Co. and IFF (Danisco Animal Nutrition) represent North American-originated players with regional distribution infrastructure.
| Leading Market Players |
|---|
| Adisseo |
| Alltech, Inc. |
| Archer Daniels Midland Co. |
| Evonik Industries AG |
| IFF (Danisco Animal Nutrition) |
| Ajinomoto Co., Inc. |
| DSM-Firmenich AG |
| Cargill, Incorporated |
| CJ CheilJedang Corp |
| Others |
Value Chain & Pricing Dynamics
Nutritionist talent scarcity in Saudi Arabia's central corridor widens labor-cost differentials between Gulf integrators and Egyptian formulators, compressing pricing-tier spreads for technical service bundles while elevating premiums for embedded field support.
Pricing Analysis
Flock-performance-based pricing anchors Middle East amino acid contracts, with integrators paying premiums tied to feed conversion ratio improvements rather than commodity tonnage. Three-tier pricing structure across premium, standard, and economy levels separates certified halal fermentation grades from synthetic methionine analogs and unbundled commodity lysine. Cost compression in standard-tier methionine is intensifying because crude glycerol spot volatility erodes formulator margins. Mid-sized Saudi feed mills exhibit highest price sensitivity due to limited formulation software capabilities, while vertically integrated poultry producers prioritize yield-linked subscriptions over unit costs.
Supply Chain Analysis
Workforce availability constraints in European methionine analog production and Asian fermentation hubs concentrate supply security anxiety among Gulf integrators seeking captive supplier relationships. Manufacturing gravity centers on Germany and China for synthetic dl-methionine, while Thailand and South Korea anchor fermentation-derived lysine and threonine capacity. Raw material flows draw from Brazilian corn gluten, Argentine soybean meal, and regional petrochemical glycerol derivatives. Single-source vulnerability pervades hydroxy analog technology licensing, where three European-Asian producers control global output. Distribution runs through Jeddah and Dubai bulk terminals into regional premix blending facilities serving controlled-environment poultry clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East feed amino acids market sits in a technology-transition phase, with precision formulation software displacing legacy annual bulk contracting and algorithm-driven procurement becoming the operational standard for competitive integrators.
For Market Incumbents: Lock in long-term supply contracts with Saudi Arabia's top-five vertically integrated poultry producers before channel disintermediation fully concentrates volume with technology-holding manufacturers. Deepen backward integration into halal-certified fermentation substrate sourcing to defend against emerging bioprocess specialists threatening certification premiums. Prioritize embedded field technical staff deployment to address acute Gulf nutritionist shortages and secure flock-performance-tied subscription renewals. For New Entrants and Emerging Players: SFDA feed additive registration harmonization across GCC states opens a window for mid-sized Saudi feed mills digitizing procurement cycles with bundled technical service offerings. Target Egypt's Nile Delta threonine demand as dual-track licensing delays deter established suppliers, using local formulator partnerships to navigate Ministry of Agriculture and Land Reclamation complexity. Penetrate through least-cost formulation software integration rather than commodity price competition. For Investors and Strategic Acquirers: Re-rating potential sits with Gulf premix specialists possessing embedded field technical capabilities given accelerating channel disintermediation and integrator demand for flock-specific formulations. Long-term viability favors fermentation-derived amino acid producers with verifiable low-carbon credentials as EU-exporting Gulf poultry producers anticipate supply chain emissions disclosure mandates. Watch for carbon intensity reporting extension to feed ingredients as the inflection signal favoring bioprocess assets over synthetic production.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halal Substrate Sourcing | Captive supply of certified carbohydrate feedstocks secures SFDA registration pathways against fermentation competitors. |
| Embedded Technical Staff Deployment | Field nutritionists at Saudi integrator sites lock in flock-performance-tied subscription renewals amid talent scarcity. |
| Precision Formulation Platform Partnership | Software integration with mid-sized Saudi feed mills creates white space beyond top-tier integrator concentration. |
| Carbon Intensity Verification Investment | Low-credential certification positions fermentation grades for EU-exporting Gulf poultry producer procurement. |
| Regional Premix Blending Capacity Expansion | Localized facilities in Riyadh and Dubai reduce logistics costs and accelerate SFDA registration consolidation. |
Study Parameters
Independent corroboration across primary interviews with poultry nutrition directors, feed mill procurement managers, SFDA regulatory affairs specialists, and amino acid supplier technical directors underwrites the qualitative findings in this analysis. Secondary validation draws from Gulf Standardization Organization harmonization protocols, Saudi Food and Drug Authority registration databases, Egyptian Ministry of Agriculture import licensing records, and trade flow documentation through Jeddah and Alexandria ports. Bottom-up volume estimates from individual feed mill consumption patterns triangulate against top-down amino acid production and import statistics.
Rate-of-change decomposition separates volume growth drivers from price evolution across the projection horizon. The analytical framework models segmentation dimensions including product type crystallinity grades, source certification tiers, application species protocols, and form handling requirements. CAGRs derive from regression analysis of historical consumption patterns against controlled-environment poultry capacity expansion trajectories and least-cost formulation software penetration curves. Industry-specific forecast inputs incorporate SFDA maximum residue limit tightening schedules and anticipated carbon disclosure extension timelines.
The model assumes a particular technology adoption path; alternative pathways for precision formulation software penetration among Egyptian mid-sized mills would alter the outlook. Forecasts reflect assumptions regarding SFDA-GSO harmonization completion and halal certification substrate traceability standardization. Material deviation in crude glycerol price stability or European-Asian methionine technology holder consolidation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
Vietnam Compound Feed Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Black Pellet Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Castor Oil Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Europe Ruminant Feed Market