
 Global Inventory Optimization Software Market | 2026-2036
Global Inventory Optimization Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Inventory Optimization Software Market Foresight
Germany's industrial software corridor is reconfiguring how inventory optimization platforms penetrate European manufacturing networks. SAP SE leverages its deep ERP integration to anchor deployment across automotive and chemical supply chains. Oracle Corporation competes through database-native analytics that sustain high-velocity replenishment calculations for wholesale distribution clients. Kinaxis Inc. differentiates via concurrent planning architecture that dominates aerospace and defense procurement cycles.
Inventory optimization software encompasses algorithmic platforms that calculate safety stock thresholds, reorder points, and multi-echelon network balances using stochastic demand models and lead-time variability parameters. These systems primarily serve to minimize carrying costs while maintaining target service levels across geographically dispersed stock locations. Cloud-based deployment now leads solution uptake because subscription economics reduce capital barriers for mid-market manufacturers. Demand forecasting modules within the solution layer are expanding fastest, driven by SKU proliferation in e-commerce channels where warehouse management functions require granular velocity predictions. Replenishment optimization commands the deepest margin pools among solution categories due to the specialized operations research expertise embedded in its solvers.
The EU AI Act imposes transparency requirements on automated inventory decisions, compelling vendors to document algorithmic logic for high-risk supply chain applications. FDA traceability rules for pharmaceutical distribution in the United States further shape product standards by mandating lot-level tracking that inventory systems must reconcile in real time. ISO 28000 supply chain security frameworks add compliance overhead for logistics companies operating across multiple jurisdictions. Stakeholders must evaluate whether their current platform architectures can absorb escalating regulatory documentation burdens without degrading computational throughput.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for inventory optimization platforms, forcing incumbent vendors to re-engineer legacy codebases while mid-market manufacturers bypass capital-intensive on-premises implementations entirely.
Growth Catalysts
- EU AI Act transparency mandates:Automated decision documentation requirements are accelerating replacement cycles for black-box legacy systems across pharmaceutical and automotive supply chains in Germany, France, and Italy.
- Multi-node fulfillment networks:Third-party logistics providers operating cross-border e-commerce corridors require real-time synchronization across distributed warehouse nodes, driving platform adoption.
- Stochastic demand modeling:Machine learning-enhanced forecasting modules are penetrating SKU-heavy retail verticals where velocity predictions determine automated replenishment triggers.
Market Restraints
- Specialized operations research talent scarcity:Solver development for multi-echelon optimization requires PhD-level expertise concentrated in academic and defense-adjacent labor pools.
- Legacy ERP integration friction:Proprietary data schemas in incumbent enterprise systems create API mapping costs that inflate total cost of ownership for mid-market buyers.
- Data residency requirements:Russia, China, and Saudi Arabia mandate local server presence, fragmenting cloud economics for vendors pursuing standardized global architectures.
Strategic Opportunities
- India PLI scheme manufacturing incentives:Electronics and automotive component production subsidies are creating greenfield facility demand for inventory optimization in Gujarat and Tamil Nadu industrial corridors.
- FDA pharmaceutical traceability rules:Lot-level serialization mandates for drug distribution are opening specialized compliance modules for vendors with validated cold-chain tracking capabilities.
- Digital twin convergence:Integration between inventory optimization platforms and physics-based simulation engines enables scenario modeling for supply network disruption response.
Industry Challenges
- Algorithmic audit documentation:EU AI Act high-risk system classifications require technical file maintenance that consumes engineering resources without generating direct revenue.
- ISO 28000 security framework implementation:Multi-jurisdiction logistics operators face certification timeline compression as customs authorities harden supply chain security requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Inventory Optimization Software Market |
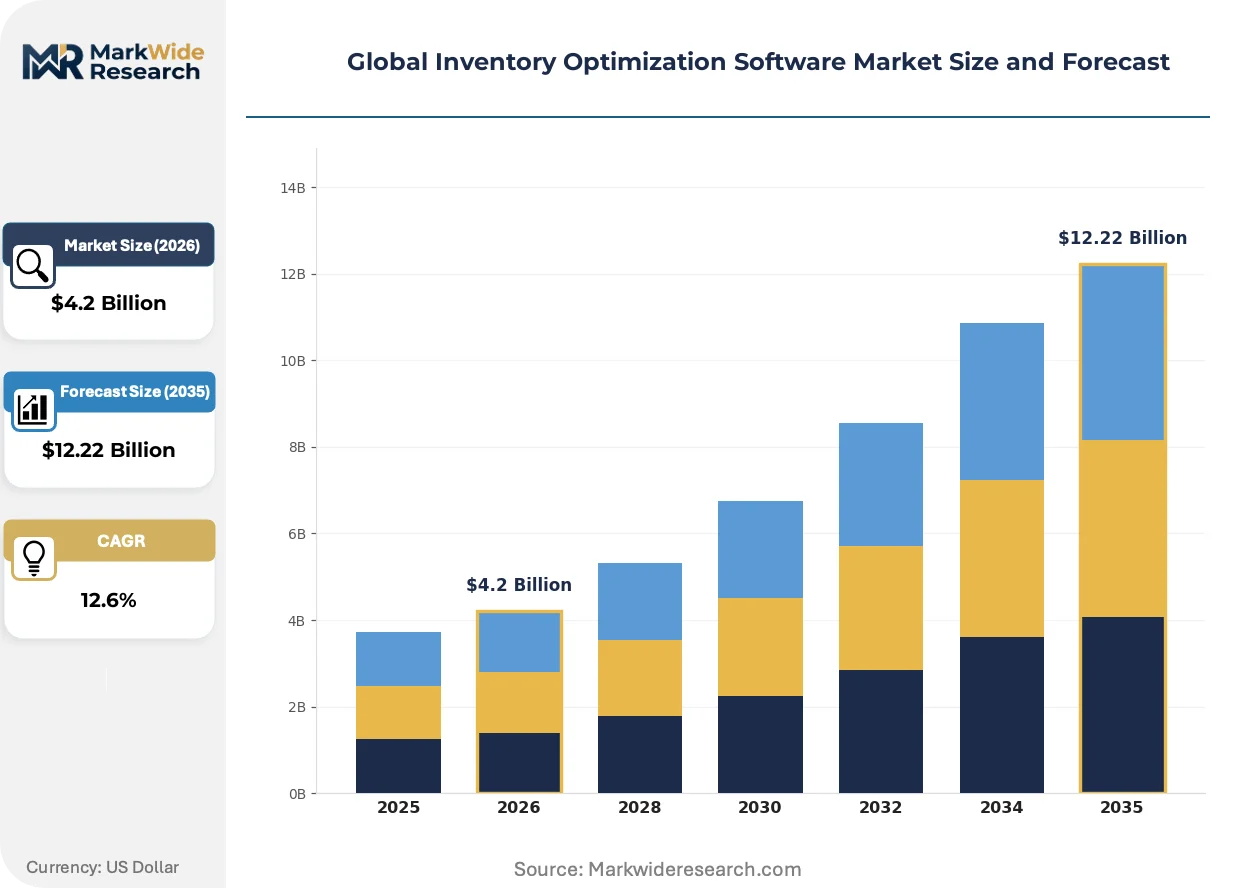
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $12.22 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Solution: Demand Forecasting, Supply Chain Planning, Order Management, Warehouse Management, Replenishment Optimization Application: Manufacturing, Wholesale Distribution, E-Commerce, Healthcare Providers, Consumer Goods End User: Logistics Companies, Retail Chains, Third-Party Logistics, Food & Beverage Firms |
| Companies Covered | SAP SE, Oracle Corporation, Blue Yonder Group, Inc., Manhattan Associates, Inc., IBM Corporation, Kinaxis Inc., o9 Solutions, Inc., Epicor Software Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Inventory Optimization Software Market Shifts & Advancements
Real-time data streaming architectures are displacing batch-processed inventory calculations, enabling continuous replanning cycles that compress safety stock buffers without service level degradation.
Graph neural networks for demand correlation mapping are rendering obsolete traditional time-series forecasting approaches that treat SKU demand as independent variables. Aerospace and defense contractors with highly engineered component portfolios are adopting these architectures fastest. The technology is compressing forecast error rates for long-tail inventory positions that previously required excessive manual intervention.
CSRD sustainability reporting mandates in the European Union are forcing inventory optimization vendors to embed carbon accounting modules that calculate scope 3 emissions from stock positioning decisions. Pharmaceutical distributors in Germany and the Netherlands must now reconcile lot-level traceability with emissions disclosure requirements. Vendors are responding with dual-purpose dashboards that serve both operational and compliance stakeholders.
Subscription pricing for cloud-native platforms is displacing perpetual license models in mid-market manufacturing procurement patterns. Procurement teams in industrial machinery and chemical processing verticals now prioritize operational expenditure classification over capital budget approval cycles. This shift is most visible in the German Mittelstand sector where family-owned manufacturers previously avoided SaaS commitments due to governance conservatism.
Global Inventory Optimization Software Market Segmentation
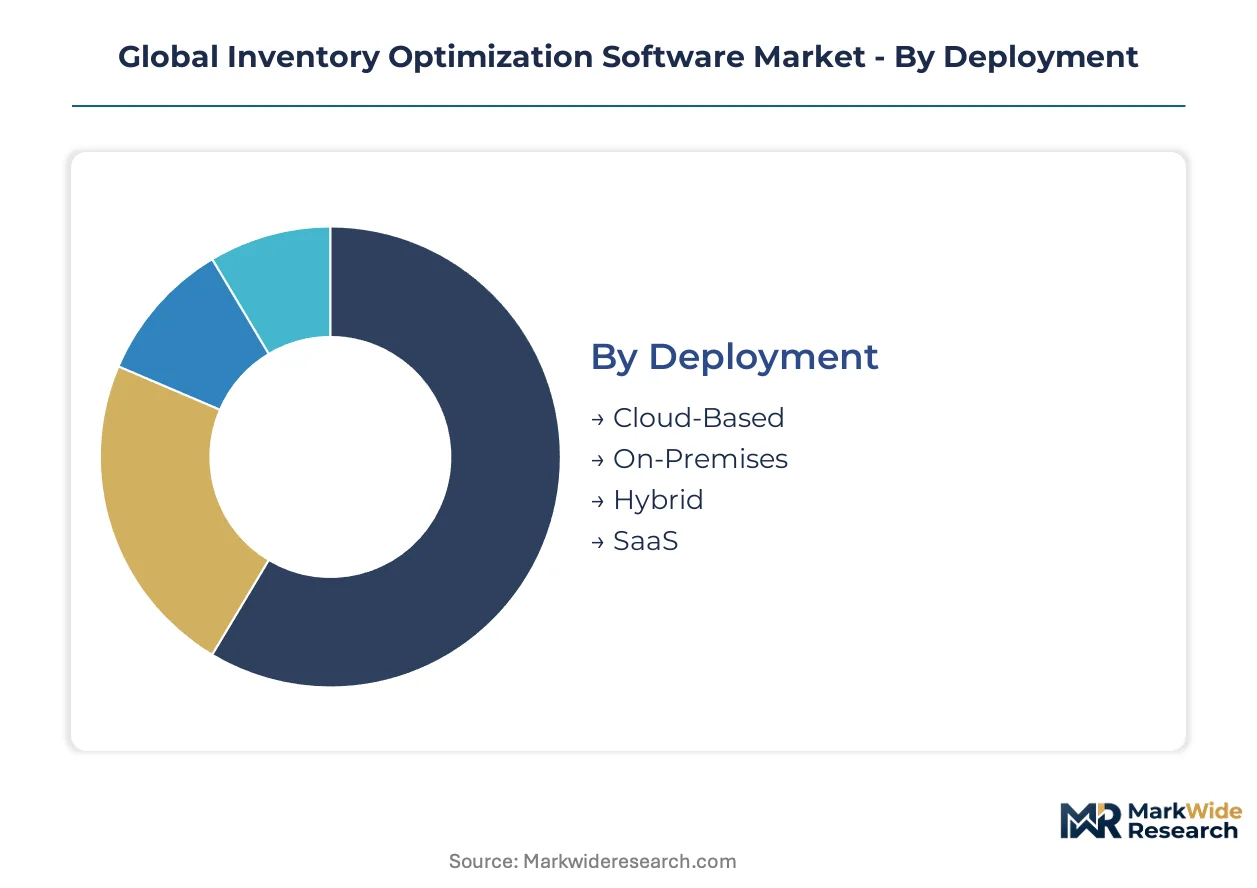
Segmentation in inventory optimization software reveals how deployment economics, functional depth, and vertical specialization create divergent margin pools. Procurement patterns across these dimensions determine whether vendors capture recurring SaaS revenue or one-time license fees.
Deployment:
Cost tier separates buyers with capital budget flexibility from those prioritizing operational expenditure classification.
- Cloud-Based:Multi-tenant architectures enable rapid provisioning without infrastructure capital. German automotive suppliers and Dutch pharmaceutical distributors are migrating from legacy systems to meet EU AI Act documentation requirements.
- SaaS:Subscription billing aligns procurement with annual operational budgets rather than capital cycles. Mid-market manufacturers in India's Gujarat industrial corridor favor this model for electronics assembly facilities.
- On-Premises:Perpetual licenses persist in defense-adjacent supply chains with air-gapped security mandates.
- Hybrid:Split workloads accommodate data residency requirements in Russia and Saudi Arabia while leveraging cloud analytics.
On-Premises holds installed capacity. Cloud-Based is rotating up the share rankings.
Solution:
Functional application determines which operational pain points vendors address and where specialized operations research expertise commands premium pricing.
- Replenishment Optimization:Operations research solvers calculate multi-echelon safety stock using stochastic lead-time distributions. Aerospace contractors in France and Germany deploy these modules for engineered component portfolios with high obsolescence risk.
- Demand Forecasting:Machine learning pipelines ingest SKU velocity signals from e-commerce channels. Retail chains operating cross-border fulfillment in Italy and Spain require granular predictions for automated trigger generation.
- Supply Chain Planning:Concurrent architecture synchronizes procurement, production, and distribution decisions.
- Warehouse Management:Slotting algorithms optimize pick-path efficiency in high-velocity distribution centers.
- Order Management:Allocation engines split inventory commitments across competing demand streams.
Supply Chain Planning holds installed capacity. Demand Forecasting is climbing the fastest.
Application:
Vertical specialization dictates regulatory compliance burdens and integration complexity with incumbent ERP systems.
- Manufacturing:Multi-echelon synchronization across tiered supplier bases requires real-time API connectivity. Automotive OEMs in Germany and chemical processors in Belgium drive deployment for just-in-sequence production.
- E-Commerce:Distributed fulfillment networks demand continuous replanning across warehouse nodes. Third-party logistics providers operating corridors between Netherlands and Germany prioritize this application.
- Wholesale Distribution:High-velocity replenishment calculations sustain margin in low-turnover categories.
- Healthcare Providers:Lot-level traceability mandates from FDA and EMA shape cold-chain tracking requirements.
- Consumer Goods:SKU proliferation creates forecasting complexity in seasonal demand patterns.
Wholesale Distribution holds installed capacity. E-Commerce is gaining share fastest.
End User:
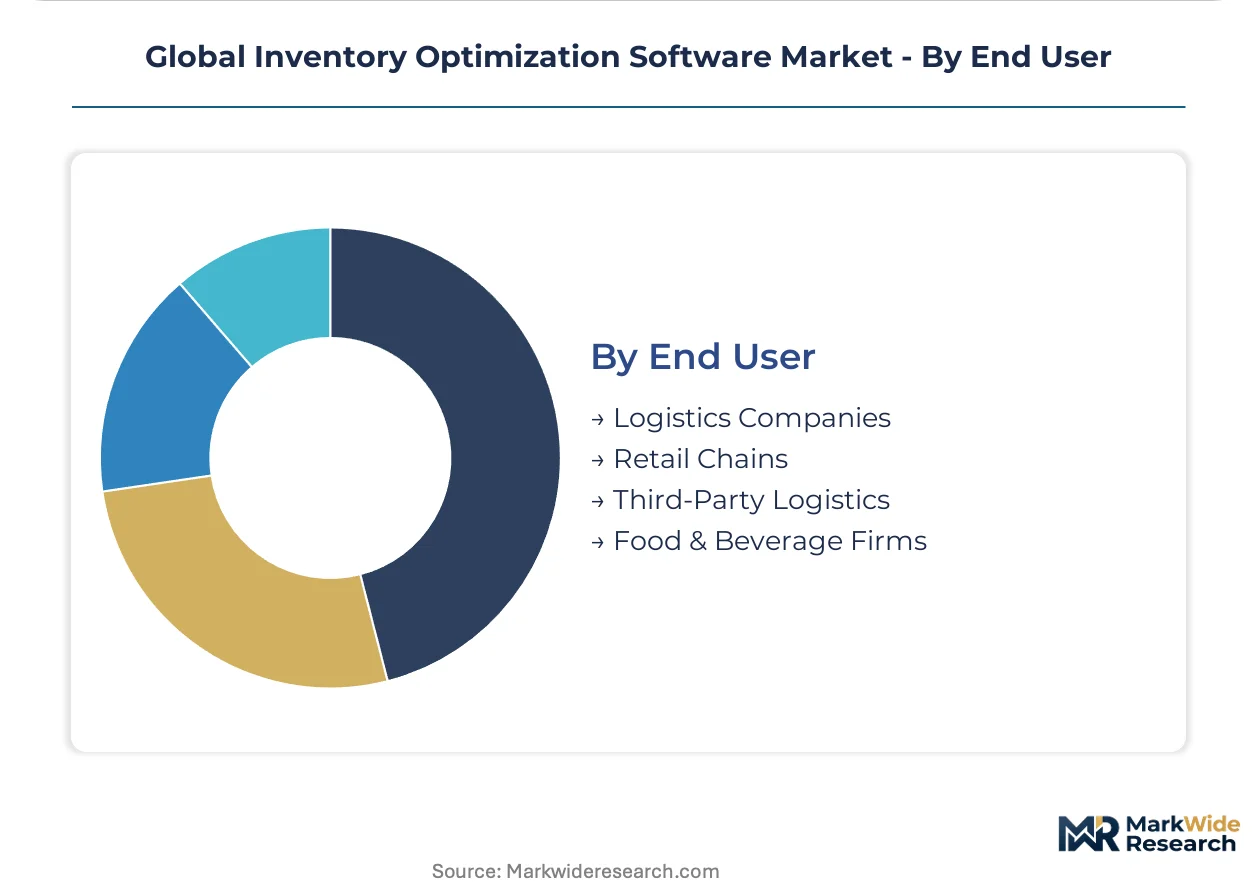
Customer type determines contract scale, integration timeline, and whether procurement centers on operational or compliance stakeholders.
- Third-Party Logistics:Multi-tenant platform requirements span client-specific inventory policies while maintaining unified infrastructure. Operators in Germany and Netherlands manage cross-border e-commerce fulfillment with real-time synchronization demands.
- Retail Chains:Store-level replenishment with distribution center coordination drives demand forecasting module adoption. French and Italian fashion retailers deploy these systems for seasonal collection launches.
- Logistics Companies:Asset-light network orchestration requires visibility across contracted carrier capacity.
- Food & Beverage Firms:Shelf-life constraints and FSSAI traceability rules shape perishable inventory policies.
Logistics Companies holds installed capacity. Third-Party Logistics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp port complex anchors European inventory optimization deployment through dense chemical and pharmaceutical distribution networks. German automotive corridors and Dutch pharmaceutical hubs drive continental demand concentration.
United States
Third-party logistics providers and pharmaceutical distributors dominate software procurement. FDA traceability mandates for drug lot-level tracking force system upgrades across cold-chain networks. The New Jersey-Pennsylvania pharmaceutical corridor sees concentrated deployment for serialized inventory reconciliation.
Germany
Automotive OEMs and chemical processors require multi-echelon synchronization across tiered supplier bases. EU AI Act transparency requirements accelerate replacement of legacy black-box systems. The Stuttgart industrial cluster anchors deployment for just-in-sequence production coordination.
India
Electronics assembly and automotive component manufacturing expand platform adoption. PLI scheme subsidies for greenfield facilities create demand in Gujarat and Tamil Nadu industrial corridors. The Bangalore-Chennai manufacturing belt drives cloud-native procurement for mid-market exporters.
Netherlands
Cross-border e-commerce fulfillment and pharmaceutical distribution shape platform requirements. CSRD sustainability reporting mandates force carbon accounting module integration. The Amsterdam-Rotterdam logistics corridor concentrates third-party logistics provider adoption.
China
Domestic e-commerce giants and electronics manufacturers deploy stochastic demand modeling for SKU-heavy operations. Data residency requirements fragment cloud economics, favoring hybrid architectures. The Yangtze River Delta manufacturing belt anchors localization of inventory optimization platforms.
Global Inventory Optimization Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in solver development and demand forecasting modules. The vendor base concentrates around ERP-native providers with deep enterprise integration capabilities and pure-play supply chain specialists with concurrent planning architectures. Two strategic archetypes dominate: database-anchored platforms leveraging existing enterprise data infrastructure, and cloud-native specialists compressing deployment timelines for mid-market manufacturers. Competitive moves center on API ecosystem expansion and vertical-specific compliance module development.
Within the ERP-integrated tier, SAP SE and Oracle Corporation anchor platform deployment through deep enterprise system connectivity. Kinaxis Inc. occupies a position exemplifying concurrent planning specialization for aerospace and defense procurement cycles. These three entities represent the dominant competitive anchors: German-origin ERP integration, database-native analytics, and Canadian-based concurrent architecture specialization.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Blue Yonder Group, Inc. |
| Manhattan Associates, Inc. |
| IBM Corporation |
| Kinaxis Inc. |
| o9 Solutions, Inc. |
| Epicor Software Corporation |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Overcapacity in cloud infrastructure regions is compressing vendor margins and forcing subscription pricing models toward volume-tiered structures that reward multi-year commitments from automotive and pharmaceutical buyers.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with SaaS vendors offering premium, standard, and economy tiers differentiated by API call limits and dedicated support levels. Price differentiation hinges on EU AI Act compliance certification and vertical integration depth into ERP systems. Cost compression in the mid-market tier is intensifying because cloud-native entrants are undercutting legacy license maintenance fees. Small and mid-market manufacturers exhibit highest price sensitivity, while defense contractors and pharmaceutical distributors prioritize compliance over cost.
Supply Chain Analysis
Contract manufacturing concentration rests with specialized operations research boutiques in Germany, Canada, and the United States that develop solver engines for multi-echelon optimization. Software development draws from PhD-level talent pools concentrated in academic corridors near Stuttgart, Toronto, and Boston. Supply chain risk centers on single-source vulnerability for stochastic demand modeling algorithms licensed from defense-adjacent research institutions. Distribution runs through direct enterprise sales teams and hyperscaler marketplaces serving mid-market manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inventory optimization software faces substitution pressure from native AI modules embedded within ERP platforms, requiring incumbents to articulate differentiation through specialized solver performance and regulatory compliance depth.
For Market Incumbents: Pre-empt ERP-native AI encroachment by deepening vertical integration into pharmaceutical cold-chain tracking and automotive just-in-sequence production workflows. Anchor renewal rates through EU AI Act documentation services that generic platforms cannot replicate. Prioritize solver performance benchmarking against Kinaxis concurrent planning benchmarks in aerospace procurement cycles.
For New Entrants and Emerging Players: India's Gujarat and Tamil Nadu industrial corridors offer underpenetrated greenfield demand from PLI-subsidized electronics assembly facilities. Target mid-market manufacturers bypassing capital-intensive on-premises implementations entirely. Lead with rapid-deployment cloud-native architectures that compress implementation timelines below incumbent benchmarks.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized operations research boutiques with validated solver engines and existing FDA pharmaceutical traceability certifications. Long-term viability favors vendors with concurrent planning architecture patents and established aerospace contractor relationships. Watch for inflection when EU AI Act enforcement accelerates replacement cycles for black-box legacy systems in Germany and France.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep API connectivity with SAP and Oracle ERP systems anchors enterprise renewal rates in automotive supply chains. |
| Acquisition of Specialist Firm | Operations research boutiques with PhD-level solver expertise command premium multiples from aerospace procurement vendors. |
| Geographic Expansion | Localization in India's PLI corridor captures greenfield demand from electronics and automotive component manufacturers. |
| Product Launch | CSRD-compliant carbon accounting modules differentiate offerings for Dutch pharmaceutical distributors facing dual reporting mandates. |
| Strategic Partnership | Hyperscaler marketplace distribution compresses customer acquisition costs for mid-market SaaS penetration. |
Research Methodology
A spread of perspectives from supply chain executives at third-party logistics providers, procurement officers at automotive OEMs, regulatory affairs leads at pharmaceutical distributors, and platform engineers at cloud-native vendors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, EU regulatory documentation, hyperscaler capex disclosures, and customs trade data. Bottom-up deployment modeling and top-down market sizing triangulated on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry, integration complexity with incumbent ERP systems, and regional regulatory adoption patterns. CAGRs were derived from install-base growth rates and replacement-cycle acceleration signals. Industry-specific forecast inputs incorporated EU AI Act implementation timelines and FDA pharmaceutical traceability rule enforcement phases.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-native AI platforms or ERP-embedded supply chain modules would shift outcomes beyond modeled ranges. Quarterly review of EU AI Act technical file submission rates and pharmaceutical distributor system upgrade announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Marketing Software Market
Digital Solutions
AI In Packaging Design Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Europe Digital Signage Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
Data Converter Market
Digital Solutions
HIPAA-Compliant Messaging Services Market
Digital Solutions
Legal Technology Market
Digital Solutions
Global Integration Platform As a Service (IPAAS) Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Mobile Collaboration Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Next Generation Search Engines Market