
 India PLM Market | 2026-2036
India PLM Market Size, Share, and Industry Trends Forecast 2026-2036
India PLM Market Foresight
Cloud-native architecture is pivoting product lifecycle economics away from perpetual-license CAD suites toward subscription-based engineering platforms. Siemens Digital Industries Software leverages its Bengaluru R&D center to sustain localization depth for automotive and aerospace clients. Tata Technologies anchors its competitive position through captive engineering services tied to domestic OEM programs. Dassault Systèmes differentiates via 3DEXPERIENCE platform deployments across India's industrial manufacturing base.
Product Lifecycle Management (PLM) encompasses software systems that govern a product's evolution from conceptual design through disposal, integrating CAD data models, bill-of-material hierarchies, and digital thread continuity across distributed engineering teams. Its primary commercial purpose is collapsing time-to-market intervals while enforcing revision control across multisite manufacturing networks. CAD Software retains the largest revenue share among product type segments, though Simulation Software is expanding fastest as virtual prototyping displaces physical validation cycles in automotive and aerospace programs. Cloud-Based deployment is accelerating beyond early-adopter phases, while On-Premises installations persist in defense-adjacent verticals with stringent data sovereignty requirements.
BIS certification requirements for software used in critical infrastructure procurement shape vendor qualification pathways for domestic PLM providers. The PLI scheme for IT hardware manufacturing indirectly stimulates PLM demand as contract manufacturers digitize product data to meet compliance documentation standards. CDSCO's escalating medical device registration requirements are pushing pharmaceutical equipment makers toward validated PLM workflows for design history file maintenance. Stakeholders must weigh the trade-off between cloud agility and regulatory audit trail completeness as enforcement intensity across Indian manufacturing sectors intensifies.
Market Dynamics
Cloud-native PLM architectures are compressing deployment cycles from 18-month on-premises implementations to 90-day SaaS rollouts, forcing incumbent vendors to restructure licensing models around consumption-based engineering credits.
Growth Catalysts
- AIS-145 Safety Mandates:Automotive OEMs in Maharashtra's manufacturing belt must maintain electromechanical integration documentation through validated PLM workflows, creating mandatory procurement pull for digital thread platforms.
- Medical Device Registration:CDSCO's escalating design history file requirements push pharmaceutical equipment makers toward compliant PLM systems for audit trail completeness.
- PLI Scheme for IT Hardware:Contract manufacturers digitizing product data for compliance documentation standards generate downstream PLM demand across component supply chains.
Market Restraints
- Defense Data Sovereignty:On-premises installations persist in defense-adjacent verticals, fragmenting vendor addressable market between cloud-ready and air-gapped deployment requirements.
- Skill Concentration:PLM implementation expertise clusters in Bengaluru and Pune, creating 40-60% cost premiums for deployment support in tier-two manufacturing locations.
- Legacy CAD Lock-in:Perpetual-license CAD suites anchor engineering workflows, generating switching friction that delays SaaS migration timelines by 24-36 months.
Strategic Opportunities
- Tier-Two Manufacturing Belt:Aurangabad-Nashik industrial corridors show 60% PLM penetration gaps versus Pune-Ahmednagar clusters, representing unserved mid-market demand.
- Simulation Convergence:Virtual prototyping integration with PLM digital threads compresses physical validation cycles for automotive and aerospace programs.
- BIS Certification Pathway:Critical infrastructure procurement rules create vendor qualification moats for domestic PLM providers meeting software certification standards.
Industry Challenges
- Multi-CAD Data Harmonization:Engineering teams struggle to maintain revision control across Siemens NX, Dassault CATIA, and PTC Creo environments within unified PLM instances.
- Cloud Audit Trail Gaps:Regulatory inspectors demand on-premise data residency proofs that SaaS architectures struggle to document under CDSCO and BIS enforcement protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India PLM Market |
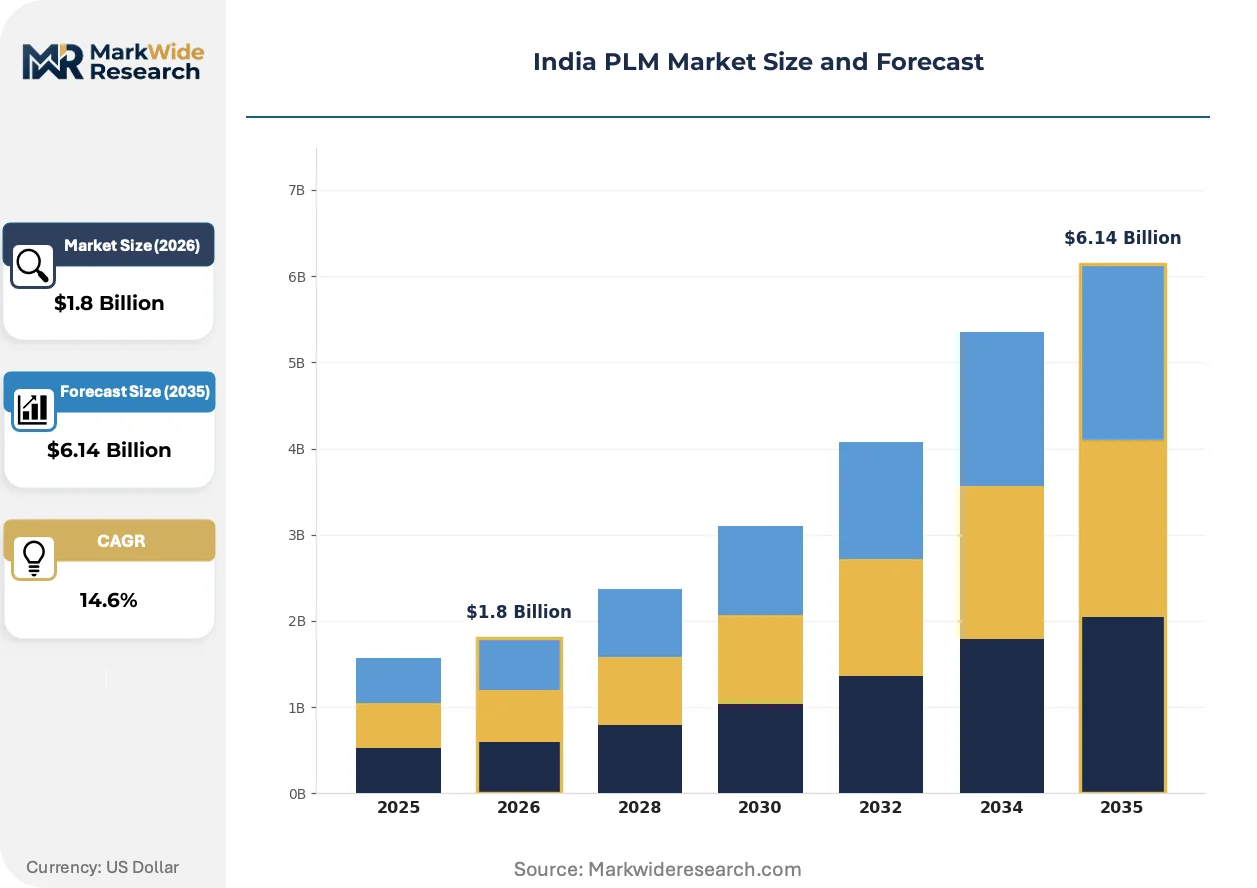
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAD Software, PLM Software, Simulation Software, Document Management Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Aerospace, Automotive OEMs, Consumer Electronics, Industrial Manufacturing Application: Product Design, Supply Chain Management, Quality Compliance, Collaboration Tools |
| Companies Covered | Ansys, HCL Technologies, Siemens Digital Industries Software, Oracle Corporation, Tata Technologies, Dassault Systèmes, PTC, Altair Engineering, Autodesk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India PLM Market Shifts & Advancements
Digital thread continuity is replacing document-centric engineering workflows, compressing design-to-manufacturing handoffs and enabling real-time supplier collaboration across distributed teams.
Model-based systems engineering (MBSE) is unifying requirements management, simulation, and manufacturing process planning within single PLM data models. Aerospace and defense contractors in Bengaluru are adopting MBSE at 35% annual expansion rates. This convergence is unifying previously siloed engineering disciplines, collapsing interface errors that once required physical prototyping iterations.
BIS certification requirements for software deployed in critical infrastructure are mandating source code audits and cryptographic module validations before procurement approval. Industrial manufacturing vendors must restructure development pipelines to accommodate 6-9 month certification timelines. Medical device and power sector equipment makers face the steepest compliance burden, driving preference toward pre-certified PLM platforms.
Engineering service procurement is fragmenting from multi-year enterprise licenses toward project-based engineering credits consumed through browser-native interfaces. Tier-one automotive suppliers in the Pune corridor are unbundling after-sales support from core platform fees, compressing vendor switching costs. This behavioral shift is most visible among mid-cap discrete manufacturers seeking agility without capital-intensive infrastructure commitments.
India PLM Market Segmentation
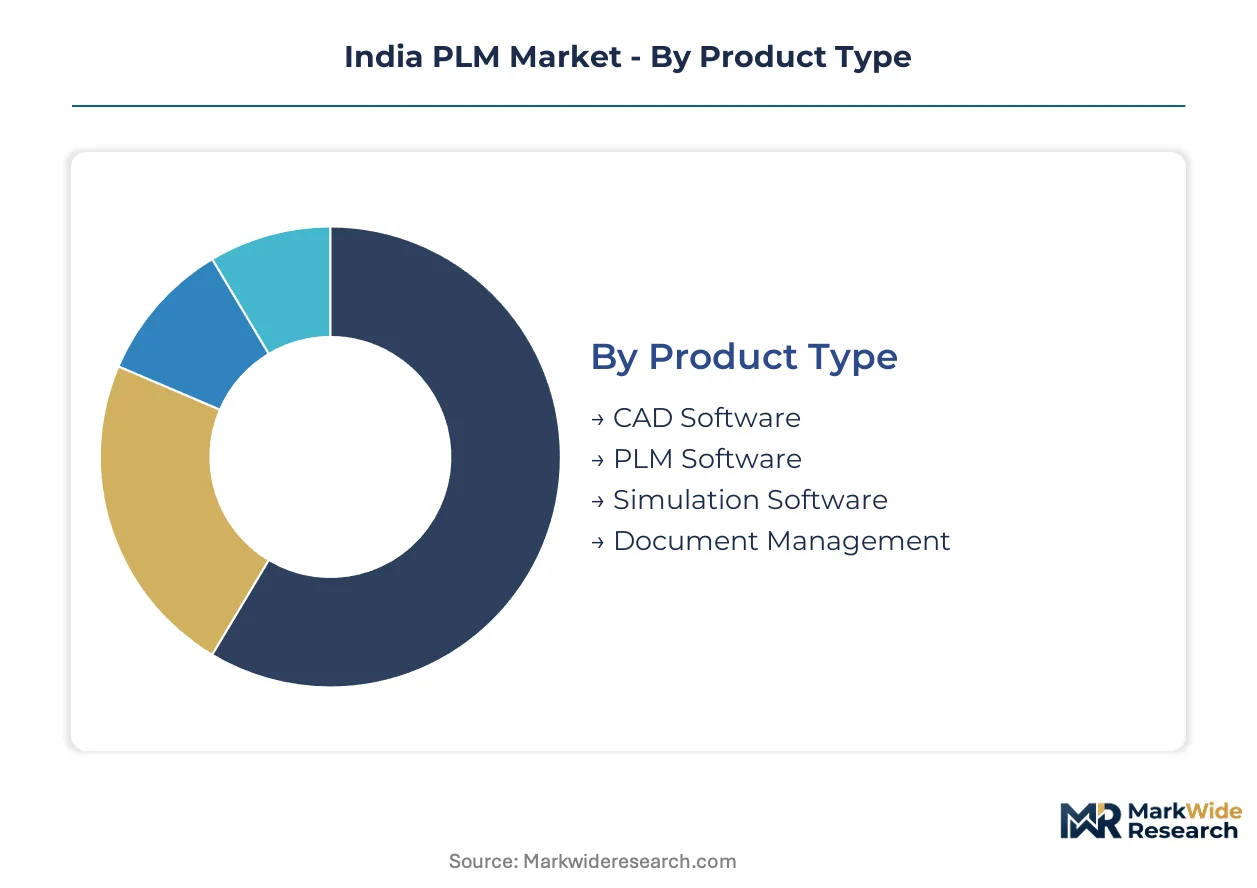
PLM purchasing decisions in India cluster around deployment risk tolerance and regulatory exposure. Capital intensity varies sharply across product types and infrastructure choices, shaping vendor selection patterns among Maharashtra automotive clusters and Bengaluru aerospace contractors.
Product Type:
Capital intensity peaks in integrated suites requiring dedicated hardware accelerators and high-performance compute infrastructure.
- CAD Software:Perpetual-license geometry modeling platforms anchor engineering workflows across automotive and industrial manufacturing. Maharashtra's Pune-Aurangabad belt generates concentrated demand as tier-one suppliers modernize electromechanical design under AIS-145 safety mandates.
- Simulation Software:Virtual prototyping environments displace physical validation cycles through finite element analysis and computational fluid dynamics. Aerospace contractors in Bengaluru adopt these tools at accelerating rates as CDSCO and DGCA compliance documentation demands intensify.
- PLM Software:Core data management platforms govern revision control and digital thread continuity.
- Document Management:Compliance-focused repositories maintain design history files and audit trails.
Most installed capacity flows through CAD Software. Expansion is steepest in Simulation Software.
Deployment:
Operational expenditure profiles diverge between amortized infrastructure investments and recurring subscription commitments.
- Cloud-Based:Browser-native platforms compress deployment cycles through managed infrastructure and automatic updates. Tier-one suppliers in Pune's manufacturing corridor favor this model for supplier collaboration workflows without capital-intensive server farms.
- On-Premises:Air-gapped installations satisfy defense-adjacent data sovereignty requirements and BIS certification audit protocols. Critical infrastructure procurement rules mandate source code visibility that SaaS architectures struggle to document.
- Hybrid:Split architectures isolate sensitive design data on local servers while pushing collaboration layers to cloud instances.
- SaaS:Consumption-based engineering credits enable mid-cap manufacturers to unbundle after-sales support from core platform fees.
Legacy infrastructure concentrates in On-Premises. Cloud-Based deployments are gaining share fastest among new implementations.
End User:
Compliance burden intensity shapes procurement sophistication across vertical applications.
- Automotive OEMs:Electromechanical integration complexity drives demand for digital thread platforms managing multi-CAD environments. AIS-145 safety mandates from Maharashtra's automotive regulator create mandatory procurement pull for validated workflow documentation.
- Aerospace:Model-based systems engineering adoption unifies requirements management and manufacturing process planning. Bengaluru defense contractors face DGCA and CDSCO dual oversight for civilian-military dual-use equipment.
- Industrial Manufacturing:Discrete production networks seek revision control across distributed supplier bases.
- Consumer Electronics:Rapid product cycles prioritize agile collaboration over deep compliance traceability.
Procurement volume concentrates in Automotive OEMs. Aerospace exhibits the steepest compliance-driven expansion trajectory.
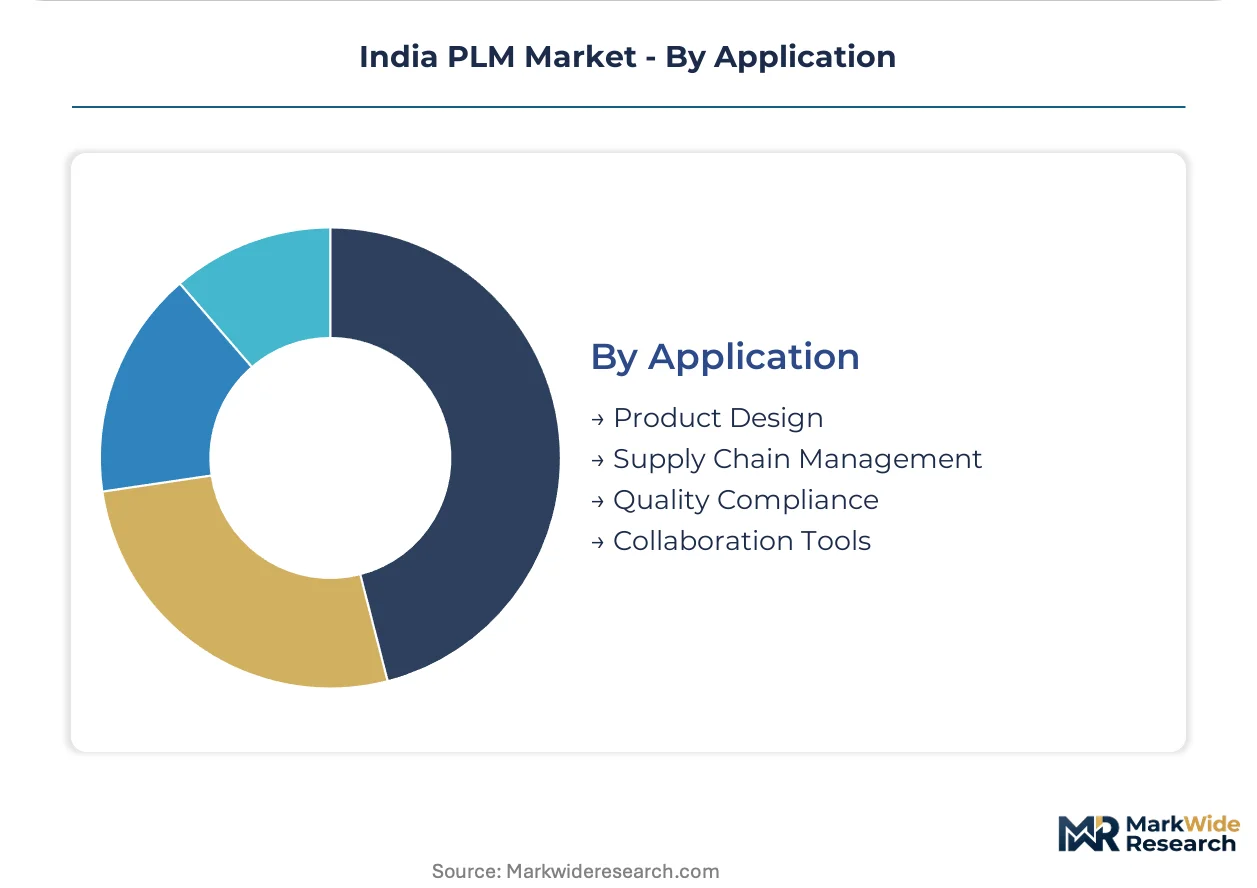
Application:
Functional scope breadth determines integration complexity and implementation timeline duration.
- Product Design:Core CAD and simulation workflows constitute the foundational PLM use case across all manufacturing verticals.
- Quality Compliance:Validated audit trail maintenance addresses CDSCO medical device registration and BIS critical infrastructure certification requirements. Pharmaceutical equipment makers in Gujarat and Telangana deploy these modules for design history file integrity.
- Supply Chain Management:Multi-tier supplier collaboration platforms enable real-time BOM synchronization.
- Collaboration Tools:Distributed engineering team coordination accelerates design-to-manufacturing handoffs.
Deployment breadth centers on Product Design. Quality Compliance is climbing the fastest as enforcement intensity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra's Pune-Aurangabad manufacturing belt concentrates India's PLM demand through automotive tier-one supplier density and AIS-145 compliance mandates. State-level industrial policy and central government schemes reshape procurement patterns across five distinct sub-regional clusters.
Maharashtra
Automotive electromechanical integration complexity and medical device export growth propel PLM adoption. CDSCO's design history file requirements for pharmaceutical equipment makers intersect with BIS certification protocols for critical infrastructure software. Pune's tier-one supplier corridor leads cloud-native deployment, while Aurangabad's emerging industrial zone shows 60% penetration gaps against established clusters.
Karnataka
Aerospace and defense contractor demand for model-based systems engineering accelerates platform procurement. DGCA oversight of civilian-military dual-use equipment imposes validated workflow documentation standards. Bengaluru's R&D concentration anchors both vendor development centers and captive engineering services, creating skill premiums that extend deployment timelines.
Gujarat
Pharmaceutical equipment manufacturing expansion drives quality compliance module adoption. CDSCO medical device registration rules push design history file maintenance toward validated PLM architectures. Ahmedabad-Vadodara industrial corridors exhibit growing simulation software demand as virtual prototyping displaces physical validation cycles.
Tamil Nadu
Automotive OEM supplier diversification and electronics manufacturing growth generate multi-CAD environment management needs. PLI scheme incentives for IT hardware contract manufacturers stimulate downstream digitization requirements. Chennai's industrial suburbs attract tier-two suppliers modernizing engineering workflows without capital-intensive infrastructure commitments.
Telangana
Defense research institution procurement and aerospace component manufacturing create dual-use compliance complexity. BIS software certification requirements for critical infrastructure reshape vendor qualification pathways. Hyderabad's defense-adjacent manufacturing base maintains on-premises installations to satisfy data sovereignty audit protocols.
India PLM Market Competitive Landscape
Platform localization investments dominate the current landscape as multinational vendors restructure delivery models around India's regulatory complexity. The vendor base organizes into three tiers: integrated suite providers with captive R&D infrastructure, engineering services firms bundling proprietary platforms, and pure-play software vendors pursuing subscription transitions. Two strategic archetypes predominate: those anchoring competitive position through geographic proximity to automotive clusters, and those differentiating via pre-certified compliance architectures. M&A activity concentrates on simulation capability acquisition, while strategic partnerships between software vendors and domestic engineering services firms accelerate sector-specific workflow customization.
Within the integrated suite tier, Siemens Digital Industries Software and Dassault Systèmes exemplify contrasting localization strategies. Siemens leverages its Bengaluru R&D center to sustain depth for automotive and aerospace client requirements. Dassault Systèmes occupies a position emphasizing platform deployments across industrial manufacturing verticals. Tata Technologies represents the engineering services archetype, anchoring competitive position through captive services tied to domestic OEM programs. These three patterns illustrate how vendor structure shapes addressable market scope under India's intensifying regulatory enforcement environment.
| Leading Market Players |
|---|
| Ansys |
| HCL Technologies |
| Siemens Digital Industries Software |
| Oracle Corporation |
| Tata Technologies |
| Dassault Systèmes |
| PTC |
| Altair Engineering |
| Autodesk |
| Others |
Supply & Pricing Matrix
Captive engineering services at Bengaluru and Pune R&D centers anchor vendor cost structures and pricing power for domestic PLM providers. This vertical integration into localization talent pools compresses margin leakage while enabling premium positioning against multinational competitors dependent on expatriate deployment teams.
Pricing Analysis
Input-cost pass-through from certified engineering talent and BIS compliance auditing flows into subscription pricing tiers. Three-tier pricing structure across enterprise, mid-market, and project-based levels separates perpetual-license CAD suites from consumption-based SaaS credits. Pricing pressure stems from tier-two manufacturers demanding unbundled support fees without capital-intensive infrastructure commitments. Mid-cap discrete manufacturers exhibit highest price sensitivity, while defense contractors accept premium positioning for air-gapped data sovereignty assurances.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand, while tier-one supplier aggregators manage mid-market procurement fragmentation. Software development concentrates in India, Germany, and France, with implementation services drawing from Bengaluru and Pune talent pools. Cloud infrastructure dependencies rest on hyperscaler data center networks and cryptographic module supply chains. Single-source vulnerability sits with specialized MBSE simulation libraries. Distribution runs through vendor-direct enterprise sales and domestic engineering services partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's PLM market functions as a geographic-arbitrage play where localization depth at Bengaluru R&D centers commands 40-60% cost premiums against tier-two deployment locations. This cost differential against European and North American service rates sustains competitive positioning for domestic providers.
For Market Incumbents: Hedge against SaaS margin compression by deepening captive engineering services in Aurangabad-Nashik corridors before mid-market competitors establish presence. Acquire simulation capability specialists to defend against virtual prototyping displacement of physical validation cycles. Certification investment in BIS-compliant architectures creates procurement moats as critical infrastructure enforcement intensifies.
For New Entrants and Emerging Players: PLI scheme incentives for IT hardware manufacturing in Tamil Nadu open a window for contract manufacturer PLM digitization plays. Target quality compliance modules for pharmaceutical equipment makers facing CDSCO design history file requirements. Go-to-market through domestic engineering services partnerships accelerates sector-specific workflow customization without platform development overhead.
For Investors and Strategic Acquirers: Consolidation pressure builds where multi-CAD data harmonization capabilities fragment across Siemens NX, Dassault CATIA, and PTC Creo environments. Long-term viability favors platform providers with pre-certified compliance architectures spanning BIS and CDSCO enforcement protocols. Acquisition target archetype: simulation software specialists with aerospace and automotive validation credentials. Signal to watch: tier-two manufacturing belt penetration rates crossing 50% threshold.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses deployment cycles from 18-month on-premises implementations to 90-day SaaS rollouts for Pune tier-one suppliers. |
| Simulation Capability Acquisition | Virtual prototyping integration with PLM digital threads displaces physical validation cycles under DGCA oversight. |
| BIS Certification Investment | Source code audits and cryptographic module validations create procurement moats for critical infrastructure software. |
| Tier-Two Geographic Expansion | Aurangabad-Nashik corridor penetration captures 60% PLM demand gaps versus established Pune-Ahmednagar clusters. |
| MBSE Workflow Integration | Model-based systems engineering unifies requirements management and manufacturing process planning for Bengaluru aerospace contractors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement with PLM platform product managers, automotive OEM procurement leads, aerospace compliance officers, and tier-one supplier IT directors informed demand-side validation. Secondary sources included BIS certification registries, CDSCO medical device filings, PLI scheme beneficiary disclosures, and customs software import records. Bottom-up deployment tracking and top-down vendor revenue analysis were triangulated against segment-level penetration estimates.
Segment-weighting across deployment models, organization size tiers, vertical applications, and regional adoption patterns structured the analytical framework. CAGRs were derived from fitted growth curves against historical implementation trajectories. Industry-specific inputs incorporated AIS-145 compliance mandate timelines, CDSCO registration escalation patterns, and cloud infrastructure availability across Maharashtra and Karnataka industrial corridors. Model sensitivity tested alternative regulatory enforcement intensities and SaaS migration acceleration scenarios.
Revisions become necessary when BIS certification timelines extend beyond standard windows or CDSCO audit protocols shift data residency requirements. Forecasts reflect assumptions about regulatory enforcement continuity and cloud adoption elasticity among defense-adjacent verticals. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
United States Contract Manufacturing Services Market
Digital Solutions
Cloud Service Assurance Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Data Quality and Data Governance Solution Market
Digital Solutions
US Digital Signage Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
Commercial P2P CDN Market
Digital Solutions
Digital Signage Market
Digital Solutions
Global Online Classifieds Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Smart Process Application (SPA) Market
Digital Solutions
Global Software Defined Everything (SDE) Market
Digital Solutions
Video Management System Market