
 Asia-Pacific API Management Market | 2026-2036
Asia-Pacific API Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific API Management Market Insights
ISO 27001 certification is rotating as a baseline qualification for enterprise API management procurement across Asia-Pacific financial institutions. Microsoft Corp leverages its Azure API Management footprint to sustain dominance in Australian banking infrastructure. Oracle Corp anchors its position through database-integrated gateway solutions that dominate on-premise installations in Japanese enterprises. Google LLC competes via Anthos-backed hybrid deployment tools that extend Kubernetes-native API control across Singaporean cloud regions.
API management encompasses the lifecycle governance, security enforcement, and traffic orchestration of application programming interfaces through gateway proxies, policy engines, and developer portals with sub-50ms latency thresholds. The technology enables enterprises to expose internal systems to external partners while maintaining authentication, rate limiting, and audit compliance. Cloud deployment configurations now capture the fastest expansion as India's UPI ecosystem and Australia's CDR framework push banks toward elastic, multi-tenant gateway architectures. API analytics segments concentrate margin pools where real-time monetization dashboards command premium pricing from telecommunications operators in South Korea and Thailand.
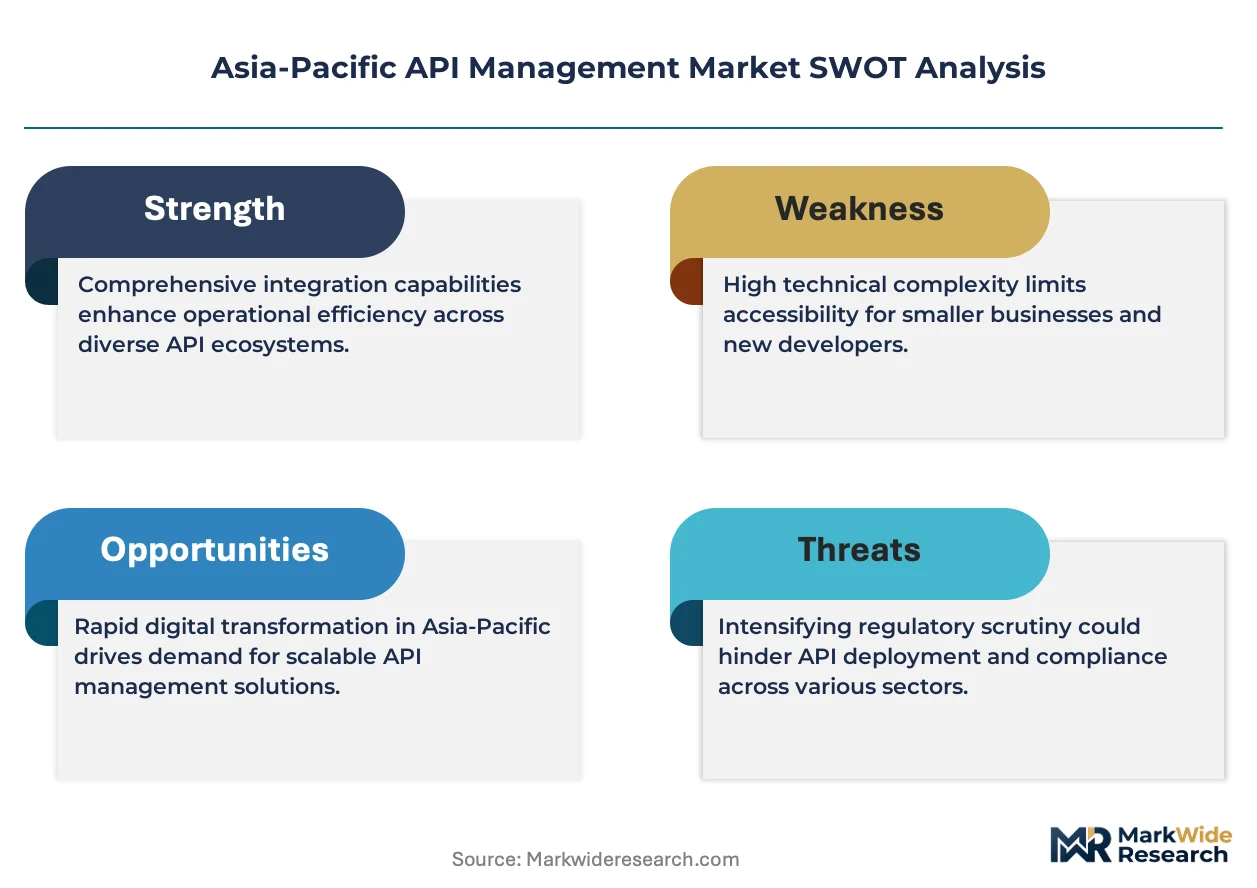
Japan's METI guides API interoperability standards for manufacturing supply chains, while India's TRAI mandates API-based number portability interfaces for telecom providers. China's SAMR enforces data sovereignty requirements that shape hybrid deployment architectures for multinational API platforms. Australia's ACCC administers Consumer Data Right regulations that compel banks to expose standardized APIs under strict security protocols. Stakeholders must monitor how divergent national data residency rules fragment otherwise unified API gateway procurement strategies across the region.

Market Dynamics
Cloud-native API gateway architectures are displacing legacy on-premise installations across Asia-Pacific financial infrastructure, driven by India's UPI real-time payment mandates and Australia's Consumer Data Right enforcement requiring elastic, multi-tenant deployment models.
Growth Catalysts
- Open Banking Mandates:Australia's ACCC-administered Consumer Data Right compels major banks to expose standardized APIs under strict security protocols, forcing wholesale infrastructure replacement cycles.
- Sovereign Cloud Requirements:China's MIIT data localization rules and India's digital public infrastructure rollout accelerate hybrid deployment models that keep sensitive traffic within national boundaries.
- Real-Time Payment Rails:India's UPI ecosystem processes billions of monthly transactions through API-connected bank interfaces, creating insatiable demand for sub-50ms latency gateway solutions.
Market Restraints
- Data Residency Fragmentation:Divergent national rules across Singapore, Australia, Japan, and China force vendors to maintain separate gateway instances per jurisdiction, inflating operational overhead.
- Certification Timeline Compression:ISO 27001 baseline requirements now extend to 18-month validation cycles for financial sector procurement, delaying revenue recognition for gateway vendors.
- Legacy System Entrenchment:Japanese enterprises maintain deep integration with database-integrated gateway architectures that resist cloud migration despite regulatory pressure.
Strategic Opportunities
- Telecommunications Monetization:South Korean and Thai operators seek real-time API analytics dashboards for traffic-based pricing, opening premium-margin service layers beyond basic gateway licensing.
- Manufacturing Supply Chain Integration:Japan's METI-guided API interoperability standards for industrial supply chains create first-mover advantages for vendors embedding gateway services into ERP platforms.
- Number Portability Mandates:India's TRAI-mandated API-based mobile number portability interfaces force telecom providers to expose subscriber management systems, expanding addressable market beyond banking.
Industry Challenges
- Multi-Cloud Orchestration Complexity:Financial institutions in Singapore and Hong Kong struggle to maintain consistent policy enforcement across AWS, Azure, and Alibaba Cloud gateway instances simultaneously.
- API Security Talent Scarcity:Specialized expertise in OAuth 2.0, mTLS certificate management, and zero-trust architecture concentrates in Sydney, Singapore, and Bangalore, leaving secondary markets underserved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific API Management Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Multi-Cloud End User: Banking, Retail, Healthcare, Telecommunications Product Type: API Gateway, API Portal, API Analytics, API Design Tools Service Type: Consulting, Maintenance, Integration, Support |
| Companies Covered | International Business Machines Corp, Microsoft Corp, Oracle Corp, Google LLC, Broadcom Inc, Software AG, Akamai Technologies Inc, SAP SE, Amazon Web Services Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific API Management Market Trends and Innovations
Gateway deployment patterns are splitting between hyperscale cloud-native stacks and sovereign-controlled edge installations, with regulatory pressure rather than technical merit determining architectural choice across the region.
Kubernetes-native API control planes are bifurcating the vendor landscape. These containerized gateways enable policy-as-code definitions that travel with microservices across cloud boundaries. Australian banks and Singaporean fintechs adopt these tools fastest, compressing procurement cycles from 24 months to under 9 months for greenfield deployments. The technology is bifurcating traditional hardware gateway vendors from software-only challengers, with incumbents forced to acquire container expertise or retreat to regulated on-premise niches.
China's SAMR data sovereignty enforcement now requires multinational platforms to maintain physically separated API infrastructure for domestic versus cross-border traffic. This industrial consequence fragments previously unified gateway architectures into parallel instances with no data flow between them. Multinational financial services firms operating in Shanghai and Hong Kong respond by deploying hybrid models that route sensitive transactions through locally certified cloud zones while maintaining global connectivity for non-regulated operations.
Developer portal self-service procurement is displacing traditional enterprise sales cycles for API management platforms. Banking technology teams in Melbourne and Bangkok now evaluate gateway solutions through 30-day sandbox trials before engaging vendor sales organizations, compressing traditional 12-month procurement timelines. This behavioral shift is most visible in Australian neobanks and Indian payment startups, where technical teams hold budget authority previously concentrated with procurement departments.
Asia-Pacific API Management Market Segmentation
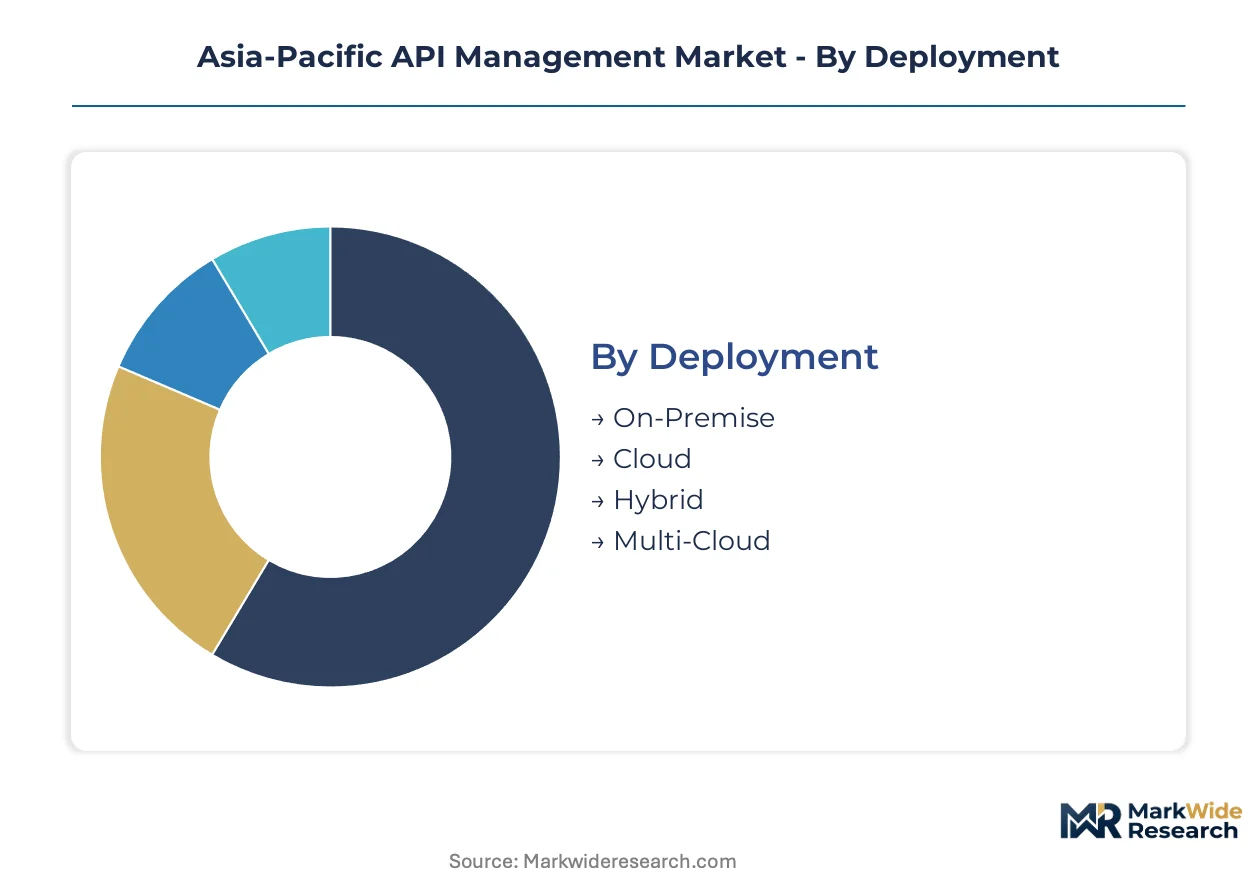
Deployment architecture choices determine vendor selection criteria across Asia-Pacific financial infrastructure, with regulatory mandates in Australia and China forcing divergence from unified global gateway strategies. End-user concentration in banking and telecommunications creates segment-specific latency and certification requirements that reshape product roadmaps.
Deployment:
Hybrid configurations face the strongest substitution pressure as sovereign cloud mandates fragment previously unified gateway architectures into jurisdiction-specific instances.
- On-Premise:Database-integrated gateway installations persist in Japanese enterprise data centers where METI-guided manufacturing supply chains require localized traffic orchestration. Deep ERP system entrenchment and multi-year amortization cycles delay cloud migration despite regulatory pressure from Japan's data residency frameworks.
- Cloud:Elastic, multi-tenant gateway architectures capture procurement preference from Australian banks responding to ACCC-administered Consumer Data Right mandates for standardized API exposure. India's UPI real-time payment ecosystem processes billions of monthly transactions through cloud-connected bank interfaces demanding sub-50ms latency thresholds.
- Hybrid:Split-traffic models route sensitive transactions through locally certified cloud zones while maintaining global connectivity for non-regulated operations. China's SAMR data sovereignty enforcement requires physically separated infrastructure for domestic versus cross-border API traffic.
- Multi-Cloud:Concurrent AWS, Azure, and Alibaba Cloud gateway instances create policy enforcement complexity for Singaporean and Hong Kong financial institutions. Consistent authentication and rate limiting across heterogeneous environments demands specialized orchestration tooling.
Cloud deployments anchor the volume base while hybrid configurations gain share at the steepest rate.
End User:
Cost tier differentiation separates regulated financial infrastructure from retail implementations with lighter compliance burdens.
- Banking:Open banking compliance in Australia and India's digital public infrastructure rollout drive premium gateway procurement with ISO 27001 certification requirements. Singaporean financial services firms expand API adoption for cross-border payment integration.
- Telecommunications:South Korean and Thai operators deploy real-time API analytics dashboards for traffic-based pricing, opening premium-margin service layers beyond basic gateway licensing. India's TRAI mandates API-based number portability interfaces.
- Healthcare:Patient data exchange protocols require encrypted gateway tunnels with audit-compliant logging architectures. Australia's healthcare sector adapts Consumer Data Right principles to medical record sharing.
- Retail:Inventory synchronization and payment gateway integration dominate API traffic patterns with lower security certification thresholds than financial services.
Banking represents the highest-margin segment while telecommunications expands most quickly.
Product Type:
Technology maturity separates established gateway functions from emerging analytics layers with differentiated pricing power.
- API Gateway:Core traffic orchestration and policy enforcement layer processing authentication, rate limiting, and request routing through proxy architectures. Japanese enterprises maintain preference for database-integrated gateway solutions from incumbent vendors.
- API Analytics:Real-time monetization dashboards command premium pricing from telecommunications operators in South Korea and Thailand. Traffic-based pricing models create recurring revenue streams beyond perpetual licensing.
- API Portal:Developer self-service interfaces displace traditional enterprise sales cycles through 30-day sandbox trials. Australian neobanks and Indian payment startups compress procurement timelines from 12 months to under 9 months.
- API Design Tools:Specification editors and testing frameworks accelerate microservices development for Kubernetes-native control planes. Singaporean fintechs adopt policy-as-code definitions fastest.
API Gateway anchors the volume base while API Analytics gains share at the steepest rate.
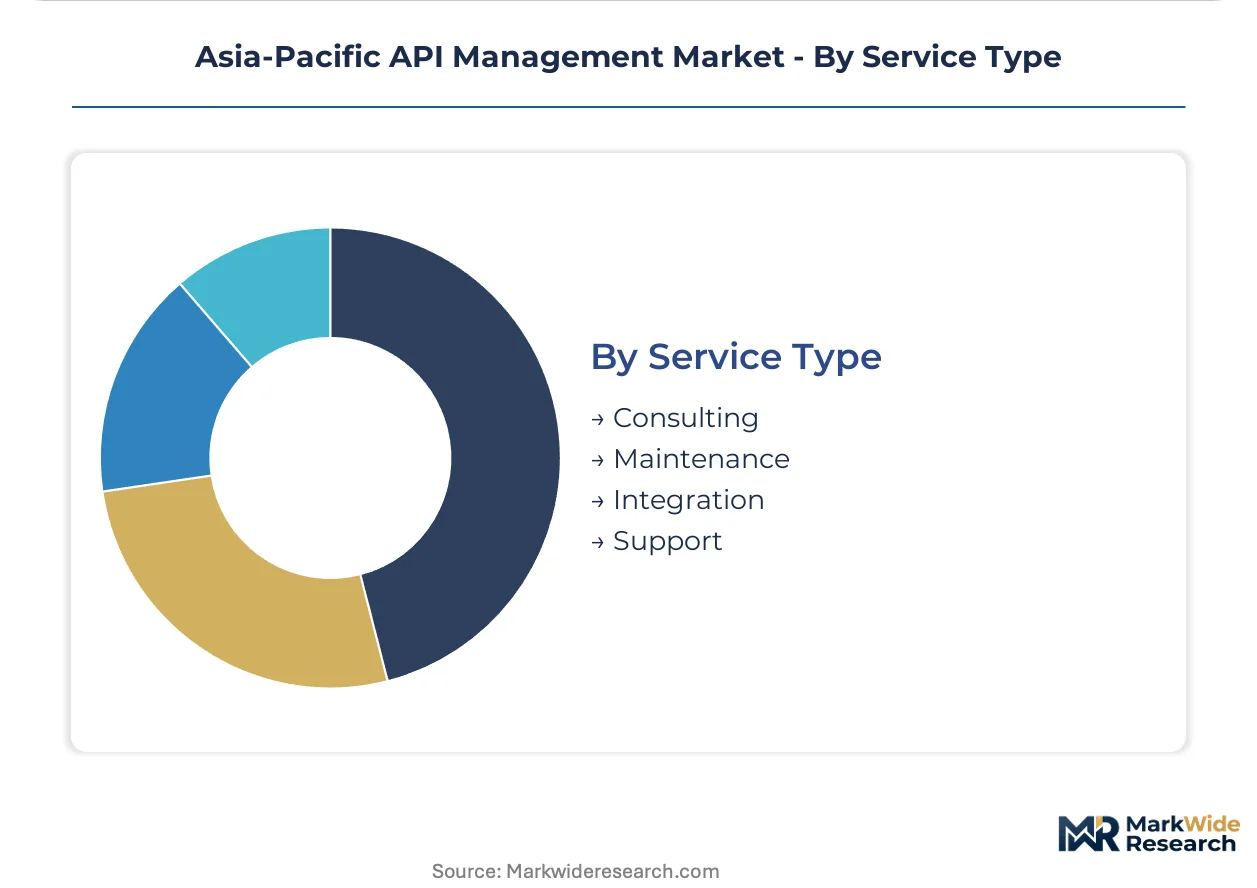
Service Type:
Customer capability gaps determine outsourcing depth, with integration complexity highest in multi-cloud financial deployments.
- Integration:Kubernetes-native gateway deployment and legacy system connectivity commands premium day rates from specialized boutiques. Multi-cloud orchestration complexity concentrates expertise in Sydney, Singapore, and Bangalore.
- Consulting:Architecture design and regulatory compliance mapping for China's SAMR data sovereignty requirements. Hybrid deployment strategy formulation for multinational platforms operating across Shanghai and Hong Kong.
- Maintenance:Certificate rotation, patch management, and gateway version upgrades for on-premise installations in Japanese manufacturing supply chains.
- Support:24/7 incident response with sub-50ms latency SLA enforcement for India's UPI real-time payment infrastructure.
Integration services anchor the volume base while consulting gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Open banking mandates and data sovereignty frameworks are fragmenting procurement strategies across Asia-Pacific financial infrastructure, forcing vendors to maintain jurisdiction-specific gateway instances. National regulators impose divergent compliance timelines that reshape deployment architectures. Cloud-native solutions capture preference in markets with elastic payment infrastructure requirements.
Australia
Australian banks accelerate API gateway replacement cycles under ACCC-administered Consumer Data Right enforcement requiring standardized exposure protocols. The country's financial regulator mandates strict security certifications that compress vendor qualification timelines. Sydney's fintech cluster drives sandbox-based procurement evaluations that shorten traditional enterprise sales cycles.
China
China's MIIT data localization rules compel multinational platforms to deploy physically separated infrastructure for domestic versus cross-border API traffic. SAMR enforcement requires hybrid architectures that route sensitive transactions through locally certified cloud zones. Shanghai's financial district anchors sovereign cloud deployment models for foreign banks operating under cross-border data restrictions.
India
India's UPI real-time payment ecosystem processes billions of monthly transactions through API-connected bank interfaces demanding sub-50ms latency. TRAI mandates API-based number portability interfaces that expand addressable market beyond financial services into telecommunications. Bangalore's technology corridor concentrates Kubernetes-native gateway expertise that serves domestic payment startups.
Japan
Japanese enterprises maintain database-integrated gateway architectures resistant to cloud migration despite METI-guided API interoperability standards for manufacturing supply chains. Deep ERP system entrenchment and multi-year amortization cycles delay infrastructure modernization. Nagoya's industrial belt anchors localized traffic orchestration for supply chain integration requirements.
Singapore
Singaporean financial services firms expand API adoption for cross-border payment integration while struggling with multi-cloud policy enforcement complexity across AWS, Azure, and Alibaba Cloud instances. The country's monetary authority emphasizes ISO 27001 certification as baseline procurement qualification. The island's fintech hub adopts developer portal self-service models that compress evaluation timelines.
Asia-Pacific API Management Market Competitive Landscape
Listed leaders compete with private specialists across certification-heavy procurement environments where ISO 27001 validation cycles extend vendor qualification timelines. The vendor base clusters around three strategic archetypes: hyperscale cloud platforms with native integration advantages, database-integrated incumbents defending on-premise installations, and container-native challengers attacking greenfield deployments. Competitive positioning hardens through M&A activity targeting Kubernetes expertise and strategic partnerships with sovereign cloud operators.
Within the hyperscale platform tier, Microsoft Corp leverages its Azure footprint to sustain dominance in Australian banking infrastructure, while Oracle Corp anchors its position through database-integrated gateway solutions that dominate Japanese enterprise data centers. Google LLC competes via Anthos-backed hybrid deployment tools extending Kubernetes-native API control across Singaporean cloud regions.
| Leading Market Players |
|---|
| International Business Machines Corp |
| Microsoft Corp |
| Oracle Corp |
| Google LLC |
| Broadcom Inc |
| Software AG |
| Akamai Technologies Inc |
| SAP SE |
| Amazon Web Services Inc |
| Others |
Pricing and Supply Chain Analysis
Cloud-native gateway architectures displacing legacy on-premise hardware simultaneously concentrate procurement leverage with hyperscale cloud providers and compress pricing power for traditional database-integrated vendors across Australian and Japanese financial infrastructure.
Pricing Analysis
Certification level creates the primary spread between gateway tiers, with ISO 27001-validated solutions commanding premium subscription rates from Singaporean and Australian banks under ACCC and monetary authority mandates. Three-tier pricing structure across premium certified, standard compliant, and economy self-managed levels stratifies by audit depth and latency SLA guarantees. Pricing pressure stems from developer portal self-service models that displace traditional enterprise sales cycles and compress procurement timelines. Indian payment startups and Australian neobanks exhibit highest price sensitivity, while Japanese enterprises with deep ERP entrenchment show lowest elasticity due to multi-year amortization cycles.
Supply Chain Analysis
India and Singapore anchor Kubernetes-native gateway development talent, while Australia and Japan concentrate legacy integration expertise for hybrid deployment architectures. Component dependencies include container orchestration platforms, certificate management infrastructure, and sovereign cloud zones certified under national data residency frameworks. Supply chain risk centers on single-source vulnerability for specialized OAuth 2.0 and mTLS expertise concentrated in Sydney, Singapore, and Bangalore. Distribution runs through direct hyperscaler marketplaces and specialized systems integrators serving financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific API management market is entering a cyclical recovery phase as open banking mandate enforcement in Australia and India's UPI infrastructure expansion create replacement demand for elastic gateway architectures.
For Market Incumbents: Consolidate Kubernetes expertise through targeted capability acquisition to defend against container-native challengers attacking Australian neobank and Indian fintech greenfield deployments. Deepen vertical integration into sovereign cloud operator partnerships to maintain position under China's SAMR data sovereignty enforcement and India's digital public infrastructure requirements. For New Entrants and Emerging Players: Anchor in South Korean and Thai telecommunications API analytics segments where real-time monetization dashboards command premium margins beyond basic gateway licensing. Target India's TRAI-mandated number portability implementations as the most penetrable expansion vector beyond saturated banking verticals, leveraging Bangalore-based engineering talent for rapid deployment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed container-native specialists holding Kubernetes policy-as-code capabilities. Long-term viability hinges on regulatory fragmentation persistence across Asia-Pacific data residency frameworks. Monitor ACCC Consumer Data Right enforcement timeline acceleration as the key inflection signal for Australian banking infrastructure replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Container-Native Specialist | Kubernetes policy-as-code capabilities compress procurement cycles for Australian neobank deployments. |
| Sovereign Cloud Partnership | MIIT-certified zones enable multinational platform operation under China's cross-border data restrictions. |
| API Analytics Platform Launch | Real-time monetization dashboards capture premium margins from South Korean telecommunications operators. |
| Developer Portal Self-Service Model | Thirty-day sandbox trials displace traditional enterprise sales cycles in Singaporean fintech procurement. |
| ISO 27001 Certification Investment | Baseline qualification unlocks Singaporean and Australian financial institution procurement pipelines. |
Research Methodology
Initial hypotheses were tested against primary input from platform engineering directors, financial services CTOs, regulatory compliance officers, and systems integration specialists and refined through secondary validation across vendor SEC filings, hyperscaler capex disclosures, and Asia-Pacific banking regulator enforcement notices. Bottom-up deployment volume estimates triangulated with top-down market sizing derived from UPI transaction volumes and ACCC Consumer Data Right compliance timelines.
Variance decomposition across deployment architecture, end-user vertical, and product type segments shaped the analytical framework over the projection horizon. CAGRs were derived from elasticity-adjusted adoption curves modeling India's digital public infrastructure rollout and Australia's open banking mandate enforcement. Industry-specific inputs included TRAI number portability implementation schedules and METI manufacturing supply chain API interoperability guidelines.
Material uncertainties — regulatory timeline delays, sovereign cloud certification bottlenecks, and legacy system entrenchment persistence — sit outside the modeled envelope. Forecasts reflect assumptions about mandate enforcement acceleration and container-native adoption rates. Recalibration cycles align with material shifts in national data residency rule implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Experience Technology Market
Digital Solutions
Synthetic Monitoring Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Online on-Demand Home Services Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Warehouse Digital Twin Simulation and Optimization Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
New Zealand ICT Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Warranty Management System Market
Digital Solutions
Mobile Sharing Power Bank Rental Service Market
Digital Solutions
North America Digital Pen Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Brazil Digital Twin Market