
 Express Digitizer Market | 2026-2036
Express Digitizer Market Size, Share, and Industry Trends Forecast 2026-2036
Express Digitizer Market Foresight
High-resolution 16-bit sampling tiers is collapsing the performance gap between mid-range and premium digitizer hardware. Keysight Technologies leverages its calibration laboratory network to sustain instrument traceability across aerospace test sites. Teledyne SP Devices anchors its position through proprietary ADC architectures that dominate time-of-flight mass spectrometry applications. Guzik Technical Enterprises specializes in magnetic recording channel test systems that occupy a defensible niche in disk drive R&D.
An express digitizer is a high-speed electronic instrument that converts analog voltage signals into discrete digital samples at rates exceeding one gigasample per second, typically employing flash or pipelined ADC architectures with resolution ranging from 8 to 16 bits and interfacing through PCIe or PXIe buses for real-time data streaming to host processors. The hardware component commands the dominant share of value as semiconductor foundries and automotive EMC labs require dedicated front-end amplifiers, clock distribution circuits, and cooling subsystems that cannot be virtualized. Cloud-based deployment is expanding fastest among semiconductor design teams that need elastic compute for post-acquisition signal analysis without capital outlay for local server farms. Signal processing functionality captures disproportionate margin as firmware-integrated FPGA pulse detection algorithms reduce downstream CPU load for radar and communications system verification.
FDA scrutiny of electromagnetic compatibility in medical imaging equipment shapes digitizer shielding and isolation specifications for healthcare end users. FCC Part 15 emissions rules constrain clock jitter and harmonic output for instruments deployed in wireless communications test environments. ISO 17025 accreditation requirements from national metrology institutes in Germany, Japan, and the United States determine which suppliers qualify for defense and aerospace procurement contracts. Stakeholders must monitor how export control revisions affecting high-speed ADC integrated circuits redistribute competitive advantage between domestic and foreign instrument manufacturers.
Market Dynamics
PCIe Gen4 and Gen5 interface standards are compressing replacement cycles across industrial automation buyers, forcing incumbent suppliers to redesign clock distribution and thermal management subsystems while defense procurement rules harden around ISO 17025 traceability requirements.
Growth Catalysts
- Radar Signal Validation Demand:Aerospace and defense test labs are expanding hardware procurement for phased-array and synthetic aperture radar characterization, requiring sustained gigasample-per-second throughput with sub-picosecond jitter.
- REACH and RoHS Compliance:European industrial buyers are retiring legacy digitizers containing restricted substances, triggering hardware refresh cycles that favor modular PXIe form factors with documented material compliance.
- Time-of-Flight Mass Spectrometry:Proprietary ADC architectures purpose-built for high dynamic range in analytical instrumentation are penetrating proteomics and metabolomics research facilities.
Market Restraints
- High-Speed ADC Export Controls:Multilateral restrictions on gallium arsenide and indium phosphide converter chips concentrate supply risk among domestic foundries in Germany, Japan, and the United States.
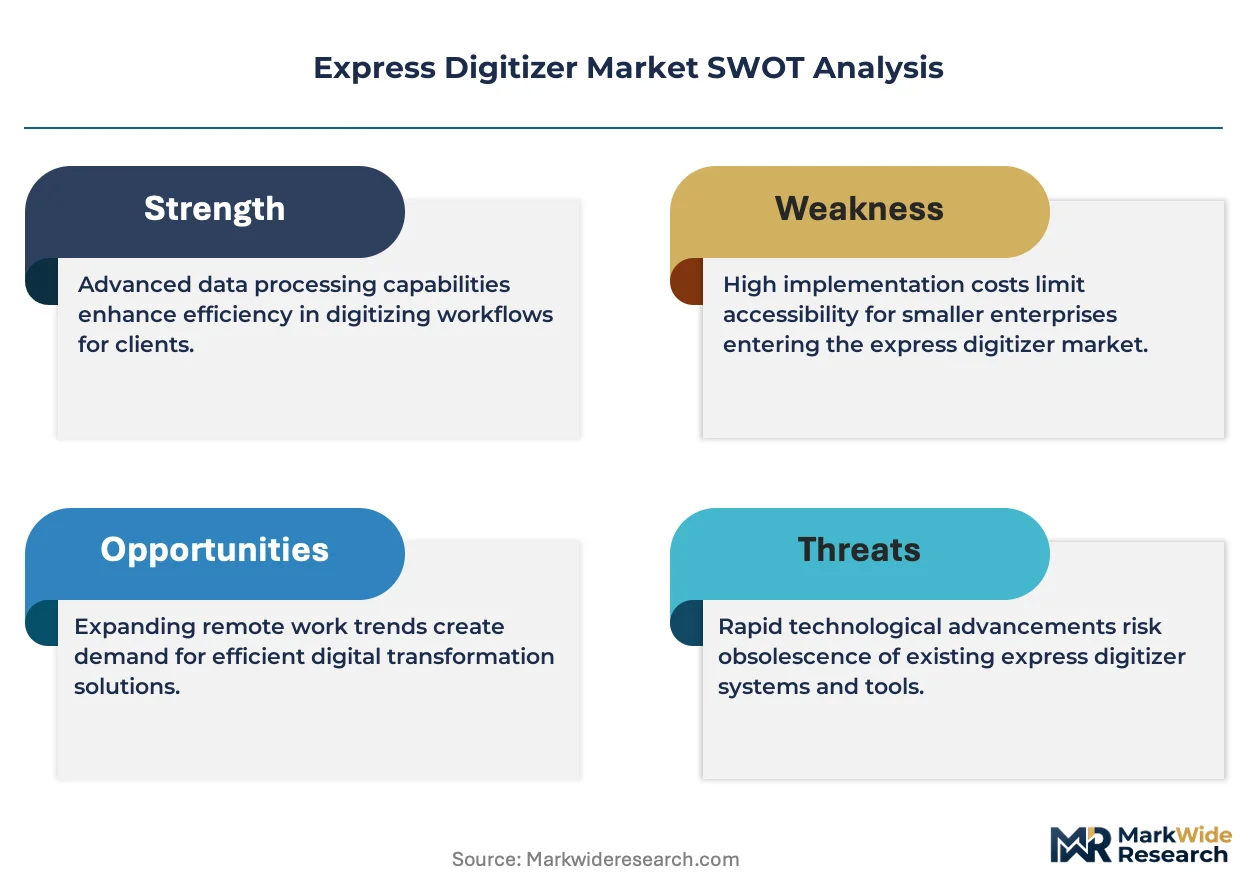
- Clock Jitter Floor:Thermal noise in sapphire-based oscillator circuits imposes fundamental limits on interleaving accuracy for 16-bit sampling tiers.
- Capital Equipment Intensity:Semiconductor foundries and automotive EMC labs require dedicated front-end amplifiers and liquid cooling subsystems that resist virtualization.
Strategic Opportunities
- Cloud-Based Signal Analysis:Elastic compute deployment allows semiconductor design teams to offload post-acquisition processing without local server farm investment.
- FDA Electromagnetic Compatibility Rules:Shielding and isolation specifications for medical imaging equipment create certified-supplier preference in healthcare procurement.
- Quantum Computing Readout:Superconducting qubit control systems demand cryogenic-compatible digitizers with real-time feedback loops, opening adjacent physics instrumentation markets.
Industry Challenges
- FPGA Firmware Talent Scarcity:Pulse detection algorithm development requires rare expertise in VHDL and high-level synthesis tools for Xilinx and Intel programmable logic.
- ISO 17025 Accreditation Timelines:National metrology institutes in Germany, Japan, and the United States impose multi-year qualification periods that delay defense contract eligibility.
- Legacy PXI System Integration:Mixed-vendor chassis compatibility issues complicate upgrades for installed bases of cabled instrumentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Express Digitizer Market |
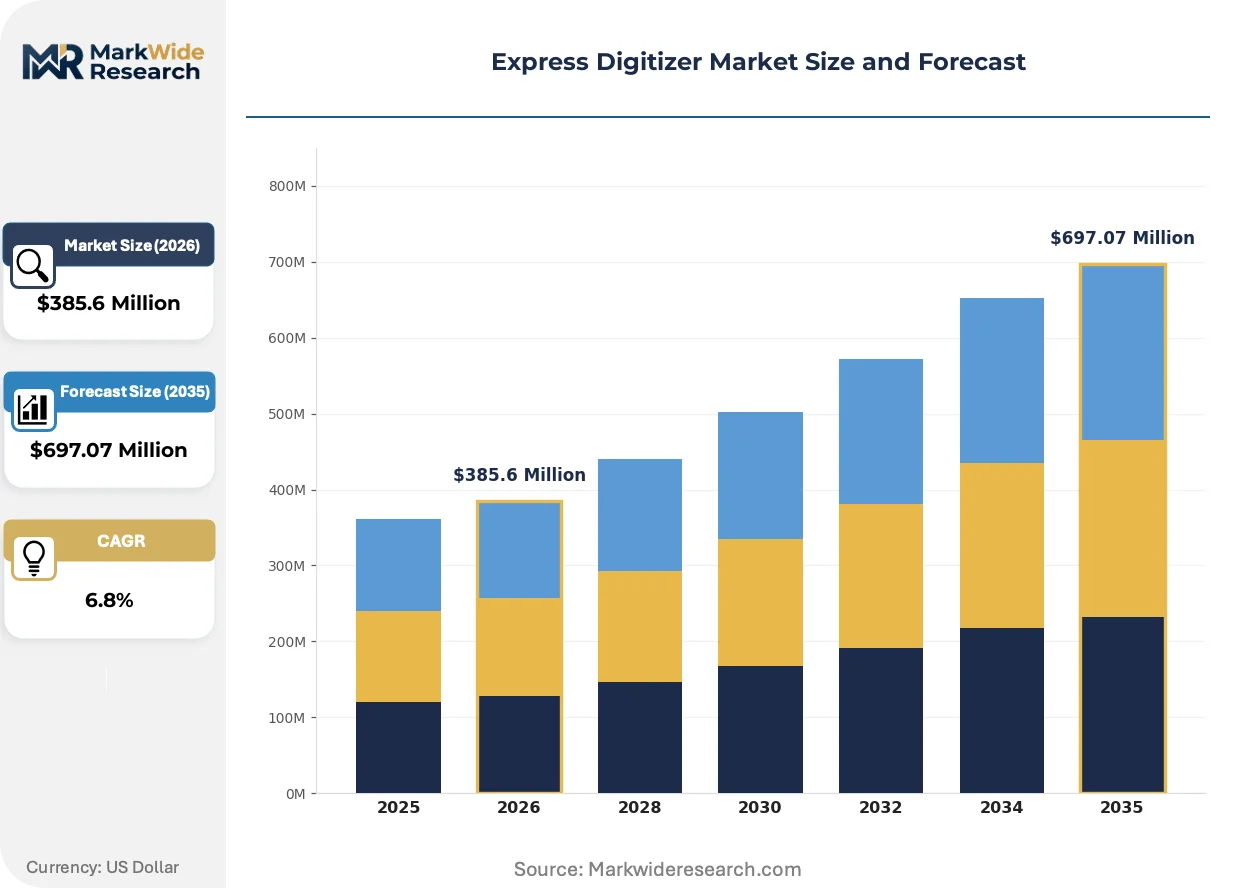
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component: Hardware, Software, Firmware, Connectivity End User: Retail, Manufacturing, Healthcare, Government Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Functionality: Data Acquisition, Image Capture, Data Processing, Signal Processing |
| Companies Covered | Keysight Technologies, National Instruments, Teledyne SP Devices, Guzik Technical Enterprises, Tektronix, ADLINK Technology, Wacom Co., Ltd., Huion Technology Corporation, Spectrum Instrumentation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Express Digitizer Market Shifts & Advancements
Signal processing functionality is capturing disproportionate margin as firmware-integrated intelligence reduces downstream computational load, while interface standard evolution and regulatory certification requirements reshape competitive positioning across end-use verticals.
Deep submicron CMOS processes are enabling 16-bit pipelined ADC architectures with power efficiency gains that flash converters cannot match. Automotive LiDAR developers and software-defined radio manufacturers are adopting these devices for battery-constrained platforms. The performance gap between mid-range and premium hardware is bifurcating procurement decisions into traceability-critical and cost-optimized segments.
FCC Part 15 emissions rules are tightening constraints on clock harmonic output for instruments deployed in wireless communications test environments. Manufacturers are redesigning shielding enclosures and spread-spectrum clocking circuits to maintain compliance. The United States wireless infrastructure test segment is absorbing these redesign costs most acutely as 5G mmWave validation expands.
Semiconductor design teams are unbundling hardware acquisition from post-processing software licenses, preferring subscription-based analysis tools that scale with project volume. Traditional instrument vendors face margin compression as cloud-native competitors capture recurring revenue streams. This pattern is most visible in the United States and Germany, where fabless design houses dominate RF and mixed-signal development.
Express Digitizer Market Segmentation
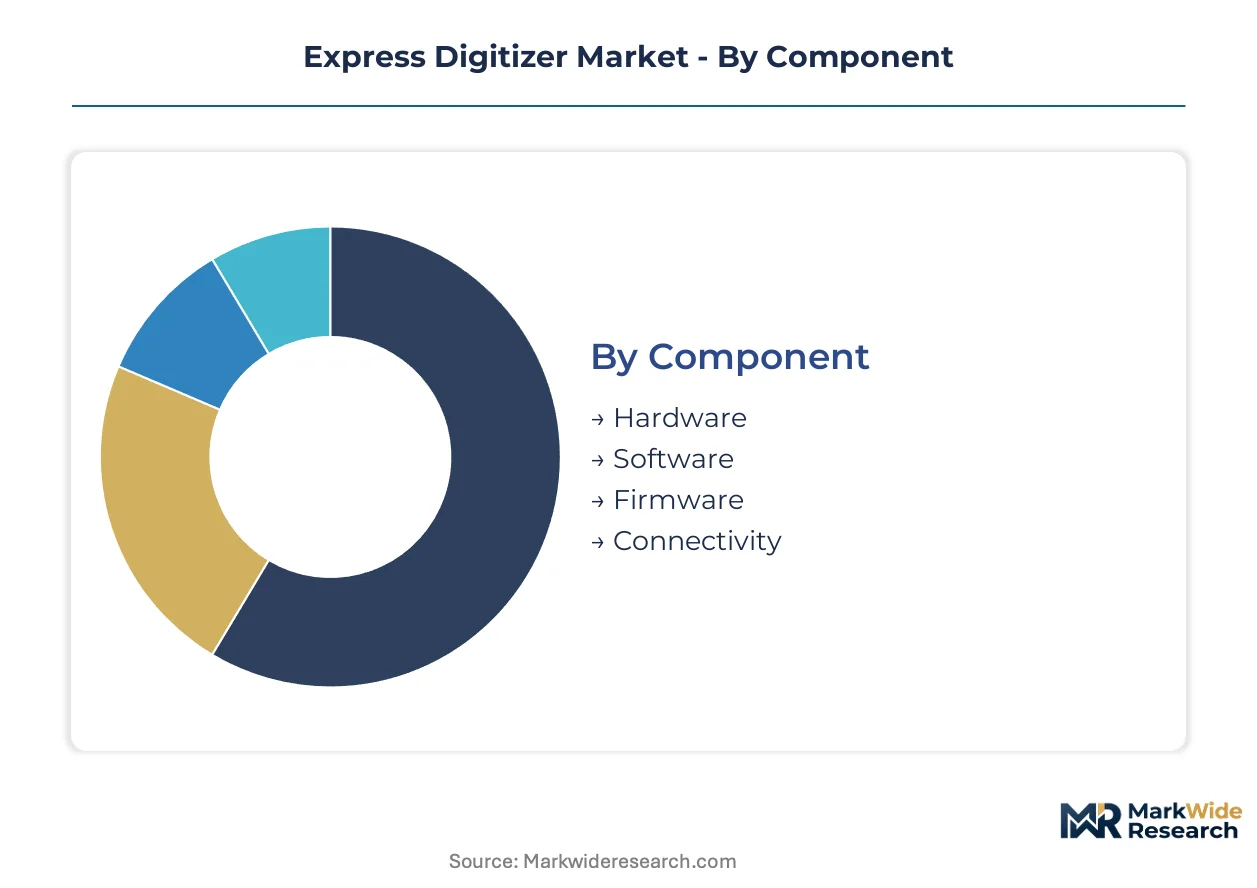
Express digitizer procurement patterns diverge sharply across component types and deployment models, with aerospace and semiconductor buyers prioritizing hardware traceability while analytical instrumentation labs favor software elasticity. Segmentation reveals where export control restrictions, FDA certification requirements, and cloud infrastructure investments reshape vendor strategies.
Component:
Hardware and firmware segments concentrate domestic production in Germany, Japan, and the United States due to export controls on high-speed ADC integrated circuits, while software and connectivity elements draw from distributed development centers across multiple geographies.
- Hardware:Front-end amplifiers, clock distribution circuits, and liquid cooling subsystems constitute the value core for semiconductor foundries and automotive EMC labs. Keysight Technologies and Teledyne SP Devices anchor this tier through proprietary ADC architectures and calibration laboratory networks serving aerospace test sites in the United States and Germany.
- Software:Post-acquisition signal analysis tools are unbundling from hardware licenses as semiconductor design teams adopt subscription-based models. Cloud-native competitors capture recurring revenue streams from fabless RF and mixed-signal developers in the United States and Germany.
- Firmware:FPGA-integrated pulse detection algorithms reduce downstream CPU load for radar and communications verification. VHDL and high-level synthesis expertise scarcity constrains development velocity.
- Connectivity:PCIe Gen4 and Gen5 interface standards force redesign of thermal management subsystems across industrial automation installations.
Hardware commands the established base. The steepest expansion runs through software.
End User:
Cost tier differentiation separates traceability-critical defense procurement from cost-optimized commercial deployments, with manufacturing and healthcare segments occupying intermediate positions on compliance intensity.
- Retail:Point-of-sale and inventory management applications employ lower-sampling-rate digitizers for barcode and RFID signal processing. Cost sensitivity dominates procurement criteria.
- Manufacturing:Industrial automation buyers in Germany, Japan, and the United States are compressing replacement cycles around PCIe Gen4 and Gen5 upgrades. REACH and RoHS compliance triggers hardware refreshes favoring modular PXIe form factors.
- Healthcare:FDA electromagnetic compatibility scrutiny shapes shielding and isolation specifications for medical imaging equipment. Certified-supplier preference creates procurement friction for non-accredited vendors.
- Government:Aerospace and defense test labs require ISO 17025 traceability from national metrology institutes. Multi-year qualification periods delay contract eligibility for new entrants.
Government anchors the established base. The steepest expansion runs through healthcare.
Deployment:
Volume concentration favors on-premise installations for capital-intensive semiconductor and automotive EMC facilities, while customer type differentiation separates enterprise design teams from project-based research operations.
- On-Premise:Dedicated server farms and local processing infrastructure remain mandatory for semiconductor foundries requiring sub-picosecond jitter validation. Capital equipment intensity resists virtualization.
- Cloud-Based:Elastic compute deployment allows semiconductor design teams to offload post-acquisition processing without local infrastructure investment. This model gains fastest among fabless houses in the United States and Germany.
- Hybrid:Edge acquisition with cloud analysis splits workloads for distributed radar test facilities and multi-site pharmaceutical development.
- Mobile:Battery-constrained platforms in automotive LiDAR and software-defined radio adopt power-efficient 16-bit pipelined architectures.
On-premise anchors the established base. Cloud-based deployment is climbing the fastest.
Functionality:
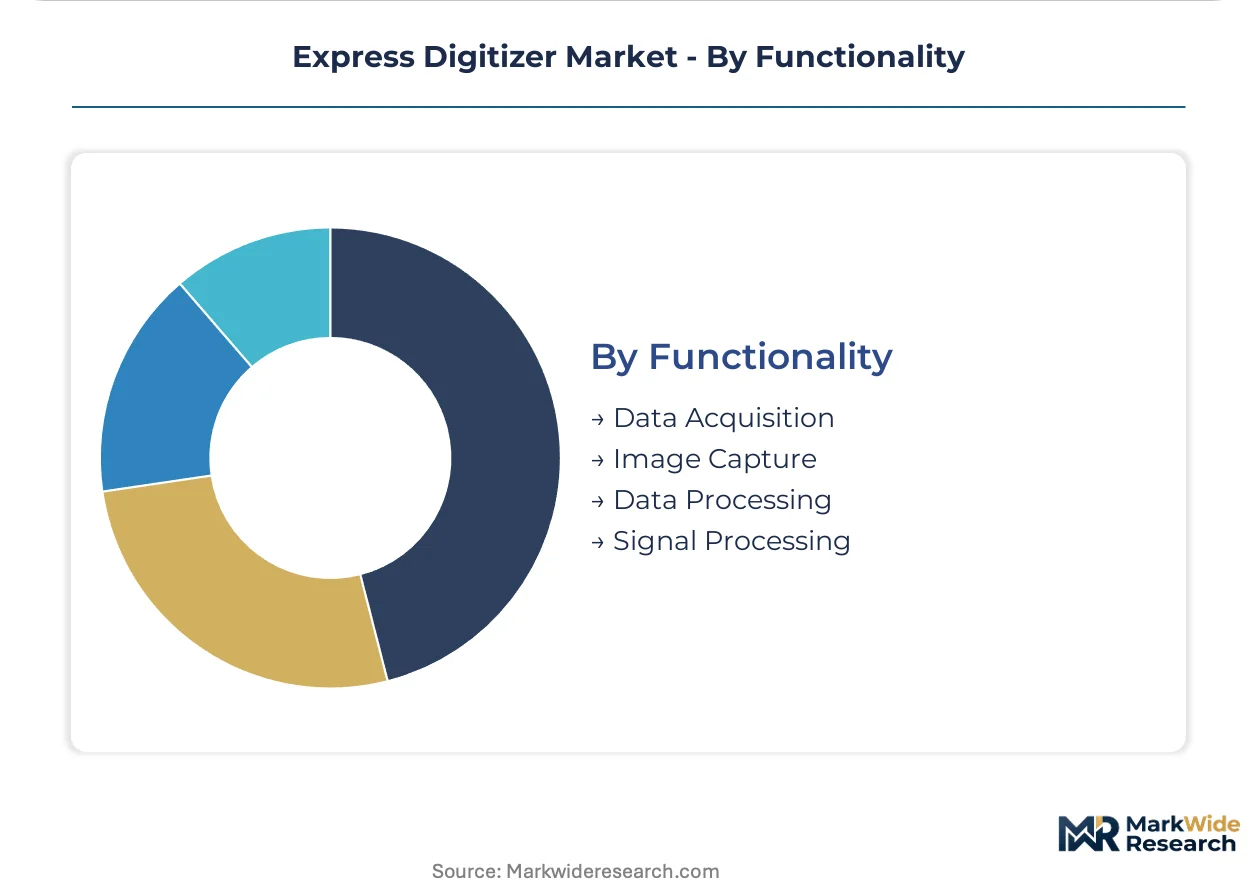
Margin capture concentrates in signal processing as firmware-integrated intelligence reduces downstream computational load, while data acquisition maintains volume leadership through instrumentation hardware replacement cycles.
- Data Acquisition:Core analog-to-digital conversion at gigasample-per-second rates serves as the foundational layer for all downstream applications. Aerospace radar validation and time-of-flight mass spectrometry drive specification intensity.
- Image Capture:Medical imaging and industrial inspection applications require high dynamic range sampling with electromagnetic interference shielding compliant with FDA and FCC Part 15 rules.
- Data Processing:Post-acquisition analytics and storage management scale with project volume through subscription licensing models.
- Signal Processing:FPGA-embedded algorithms for real-time pulse detection and feature extraction capture disproportionate margin by reducing host processor requirements. Quantum computing readout applications for superconducting qubit control represent adjacent market development.
Data acquisition anchors the established base. Signal processing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-speed ADC fabrication concentrates in Germany, Japan, and the United States due to multilateral export controls on gallium arsenide and indium phosphide converter chips. Defense procurement rules harden around ISO 17025 traceability requirements from national metrology institutes. Interface standard evolution and regulatory certification reshape competitive positioning across end-use verticals.
United States
Aerospace and defense test labs in California and Texas expand hardware procurement for phased-array radar characterization. FCC Part 15 emissions rules constrain clock jitter and harmonic output for instruments deployed in wireless communications test environments. The Boston corridor hosts semiconductor design teams adopting cloud-based signal analysis tools.
Germany
Industrial automation buyers compress replacement cycles around PCIe Gen4 and Gen5 upgrades. REACH and RoHS compliance triggers hardware refreshes favoring modular PXIe form factors with documented material compliance. The Munich-Stuttgart axis anchors automotive EMC lab concentration requiring dedicated front-end amplifiers and liquid cooling subsystems.
Japan
METI standards shape procurement specifications for time-of-flight mass spectrometry applications in proteomics and metabolomics research facilities. National metrology institute accreditation requirements determine supplier qualification for defense contracts. The Tokyo-Yokohama corridor hosts precision instrument manufacturers advancing 16-bit pipelined ADC architectures.
China
MIIT regulations govern domestic high-speed data converter development amid import substitution pressures. The Yangtze River Delta cluster houses semiconductor foundries requiring sub-picosecond jitter validation infrastructure. Shenzhen-based hardware developers face sourcing constraints from multilateral restrictions on advanced ADC integrated circuits.
South Korea
MFDS electromagnetic compatibility scrutiny shapes medical imaging equipment digitizer specifications. The Seoul Capital Area anchors memory semiconductor test lab concentration demanding sustained gigasample-per-second throughput. Busan-Ulsan industrial zones drive industrial automation digitizer deployment for manufacturing quality control.
Express Digitizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary ADC architecture specialists occupying premium tiers while modular platform vendors capture volume segments. The vendor base spans calibration laboratory networks, purpose-built analytical instrumentation developers, and magnetic recording channel test system specialists. Three archetypes dominate: traceability-critical defense suppliers, cost-optimized commercial platform vendors, and niche analytical instrumentation specialists. Competitive moves center on FPGA firmware talent acquisition and ISO 17025 accreditation timeline acceleration.
Among United States-based instrument manufacturers, Keysight Technologies and Tektronix exemplify the calibration-network archetype serving aerospace test sites. Teledyne SP Devices represents the proprietary ADC architecture specialist position in analytical instrumentation. These three occupy positions shaped by export control compliance requirements and national metrology institute qualification timelines.
| Leading Market Players |
|---|
| Keysight Technologies |
| National Instruments |
| Teledyne SP Devices |
| Guzik Technical Enterprises |
| Tektronix |
| ADLINK Technology |
| Wacom Co., Ltd. |
| Huion Technology Corporation |
| Spectrum Instrumentation |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with domestic foundries in Germany, Japan, and the United States lock in gallium arsenide and indium phosphide converter chip access while anchoring price visibility for defense and aerospace procurement tiers. These arrangements insulate ISO 17025-accredited suppliers from spot-market volatility in high-speed ADC inputs.
Pricing Analysis
ISO 17025 accreditation dictates the pricing tier structure across express digitizer procurement, with traceability-certified hardware commanding premium positioning over cost-optimized commercial tiers. Pricing stratifies across defense-grade, industrial-automation, and analytical-instrumentation tiers based on calibration network access and jitter specification stringency. Cost compression in mid-range 16-bit sampling tiers is intensifying because deep submicron CMOS processes erode flash converter cost advantages. Semiconductor foundries exhibit the least price sensitivity due to capital equipment intensity, while retail barcode and RFID applications remain highly cost-constrained.
Supply Chain Analysis
Container availability on transpacific trade lanes shapes inbound logistics costs for sapphire-based oscillator circuits and specialized cooling subsystems sourced from Japanese precision manufacturers. Gallium arsenide and indium phosphide converter chip fabrication concentrates in Germany, Japan, and the United States due to multilateral export controls. Front-end amplifiers, clock distribution circuits, and liquid cooling subsystems draw from captive production in these same jurisdictions. Single-source vulnerability around ISO 17025-accredited calibration laboratory networks presents structural risk for defense contract eligibility. Distribution runs through direct OEM relationships for semiconductor and automotive EMC labs, with modular PXIe platform vendors serving industrial automation through distribution partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Express digitizer markets sit in early-cycle expansion as PCIe Gen5 interface adoption accelerates replacement demand across industrial automation buyers in Germany, Japan, and the United States.
For Market Incumbents: Secure FPGA firmware talent pools through acquisition of specialized VHDL development teams in the Tokyo-Yokohama corridor and Munich-Stuttgart axis. Accelerate ISO 17025 accreditation timelines to preempt defense contract eligibility delays from national metrology institutes. Vertical integration into sapphire-based oscillator circuit production mitigates clock jitter floor constraints from thermal noise limits. For New Entrants and Emerging Players: FDA electromagnetic compatibility certification fast-track creates procurement preference in healthcare imaging equipment, the most penetrable segment given certified-supplier friction for non-accredited vendors. Target cloud-based signal analysis software licensing for fabless semiconductor design houses in the Boston corridor and German RF development clusters. Go-to-market through subscription-based elasticity models unbundles hardware acquisition from post-processing tools. For Investors and Strategic Acquirers: Proprietary ADC architecture specialists with time-of-flight mass spectrometry positioning represent the priority acquisition archetype, given defensible niche dominance in proteomics and metabolomics research facilities. Long-term viability hinges on quantum computing readout application development for cryogenic-compatible digitizers with real-time feedback loops. Watch for export control revision announcements affecting gallium arsenide converter chip sourcing as the inflection signal for competitive redistribution between domestic and foreign instrument manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| PCIe Gen5 Platform Migration | Forces thermal management redesign across industrial automation installations in Germany and Japan. |
| ISO 17025 Accreditation Acceleration | Compresses multi-year qualification periods for defense contract eligibility in the United States. |
| Cloud-Native Signal Analysis Launch | Captures recurring revenue from fabless semiconductor design teams adopting subscription elasticity. |
| Quantum Computing Readout Development | Opens adjacent physics instrumentation markets for cryogenic-compatible digitizer architectures. |
| FDA EMC Certification Pathway | Creates certified-supplier preference in medical imaging equipment procurement decisions. |
Research Methodology
Operator-level perspectives from test lab managers, semiconductor foundry engineers, aerospace procurement officers, and analytical instrumentation R&D directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with these stakeholders alongside secondary validation from FCC Part 15 filings, FDA electromagnetic compatibility guidance documents, METI standards publications, and ISO 17025 accreditation registries. Bottom-up segment sizing across hardware, software, firmware, and connectivity components triangulated against top-down market consolidation from trade data and national metrology institute procurement disclosures.
Sensitivity analysis tested forecast robustness across PCIe interface adoption curves, export control stringency scenarios, and cloud deployment penetration rates. The modeling framework segmented by component type, end user vertical, deployment architecture, and functionality tier, with additional dimensionality around jitter specification intensity and calibration traceability requirements. CAGRs derived from replacement cycle compression analysis and greenfield application penetration in quantum computing readout. Industry-specific inputs included radar signal validation throughput requirements and time-of-flight mass spectrometry dynamic range specifications.
Underlying assumptions cover sustained gigasample-per-second demand from aerospace test labs, stable multilateral export control regimes on high-speed ADC integrated circuits, and continued REACH and RoHS compliance enforcement in European industrial procurement, with deviation risk concentrated in regulatory revision timelines for electromagnetic compatibility standards and foundry capacity constraints for gallium arsenide converter chip production. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Cloud Video Conferencing Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Industrial Operational Intelligence Solution Market
Digital Solutions
Passenger Ticket Vending Machine Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Global Transport Management Software Market
Digital Solutions
Data Integration Market
Digital Solutions
Platform Architecture Market
Digital Solutions
Ad Network Software Market
Digital Solutions
Automatic Identification and Data Capture Market
Digital Solutions
Audio Over IP Solutions Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
API Management Market
Digital Solutions
Europe Multichannel Order Management Market
Digital Solutions
Cloud-Based POS Market