
 North America Digital Pen Market | 2026-2036
North America Digital Pen Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Pen Market Intelligence
Canadian component suppliers is broadening the upstream base for pressure-sensing modules used in advanced styluses. Microsoft Corp. leverages its Surface ecosystem to anchor enterprise deployment of active pens across productivity suites. Wacom Co., Ltd. dominates professional creative segments with specialized digitizer technology that sustains premium positioning among design professionals.
A digital pen is an electrostatic or electromagnetic input device containing precision tip sensors, onboard processors, and wireless transmitters that convert handwriting or drawing motions into digital signals for capture by computing systems. The device typically operates at pressure sensitivity levels exceeding four thousand distinct gradations, enabling nuanced stroke variation for professional illustration and annotation tasks. Active pen configurations lead product type segmentation due to integrated power circuits that enable tilt recognition and palm rejection, while Bluetooth connectivity commands the largest share of interface protocols as tablet and laptop manufacturers standardize wireless pairing architectures. Graphics pen demand concentrates among artists and design professionals where pressure fidelity determines purchasing decisions.
FCC Part 15 regulations govern radio frequency emissions from Bluetooth and NFC-enabled styluses sold in the United States, compelling manufacturers to certify transmit power and spectrum occupancy before market entry. Health Canada maintains parallel equipment authorization requirements that affect cross-border product harmonization for vendors serving both countries. Stakeholders must monitor evolving USB-IF certification standards and state-level procurement preferences for education technology to anticipate shifts in institutional purchasing criteria.
Market Dynamics
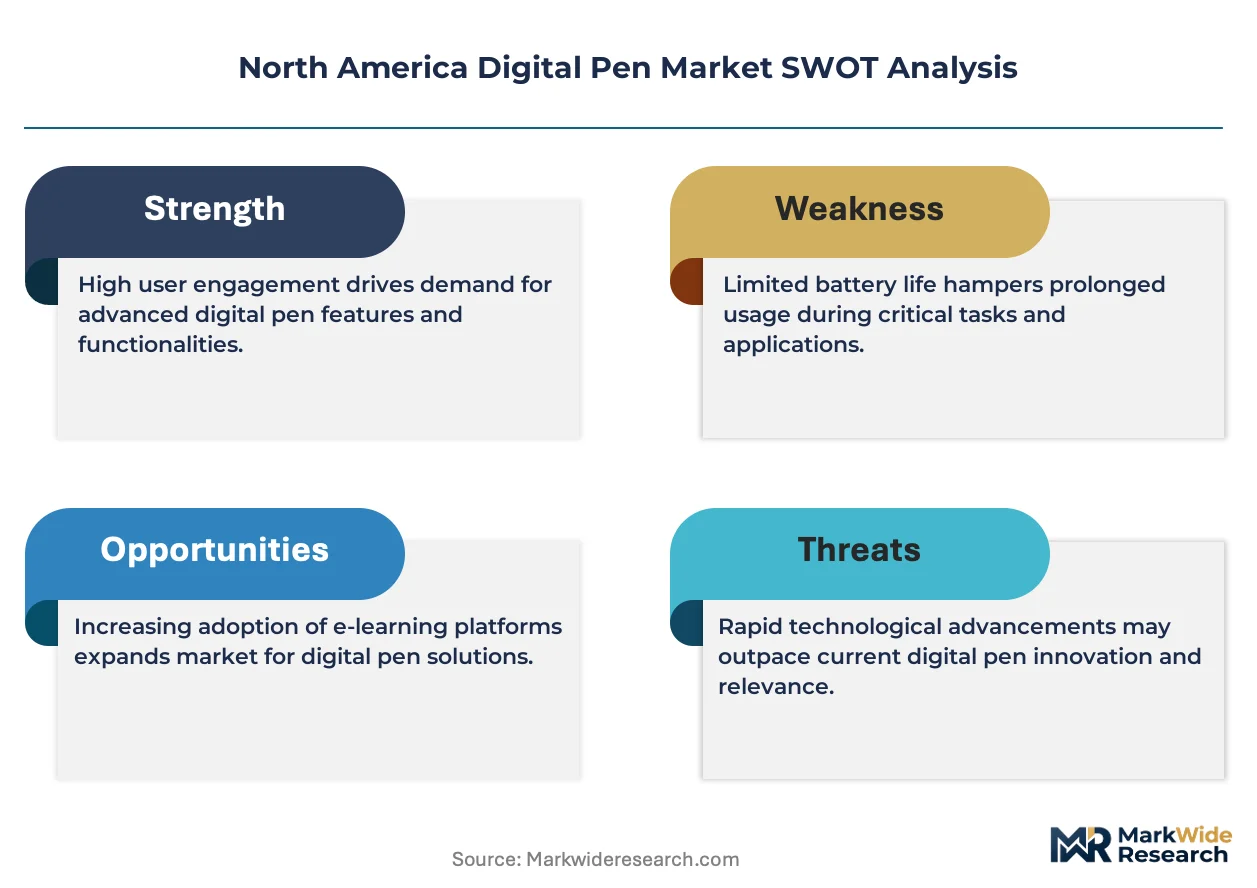
The North America digital pen market pivots on FCC equipment authorization requirements that compress product development timelines while elevating compliance costs for wireless-enabled styluses targeting healthcare and enterprise segments.
Growth Catalysts
- HIPAA-compliant documentation:Healthcare providers across the United States deploy active pens to streamline electronic health record capture, reducing transcription errors in clinical workflows.
- USB-IF certification standardization:Universal Serial Bus Implementers Forum protocols for stylus-to-host communication accelerate hardware interoperability across tablet and laptop ecosystems.
- California technology corridor concentration:Silicon Valley's device manufacturers and design studios sustain concentrated demand for pressure-sensitive digitizer technology in professional creative applications.
Market Restraints
- Pressure-sensing module supply concentration:Canadian component suppliers dominate upstream sourcing for advanced stylus sensors, creating geographic vulnerability in the supply chain.
- FCC Part 15 certification timelines:Radio frequency emission testing for Bluetooth-enabled devices extends market entry cycles by four to six months for new product introductions.
- Capacitive touchscreen substitution:Finger-based input improvements in tablet and smartphone displays erode addressable market for basic passive stylus configurations.
Strategic Opportunities
- K-12 education procurement mandates:State-level technology acquisition programs in Texas and Florida prioritize digital ink solutions for standardized testing and remote learning infrastructure.
- AI-powered handwriting recognition convergence:Neural network-based text interpretation is converging with stylus hardware to enable real-time transcription for legal and medical dictation workflows.
- Northeast financial services hubs:New York and Boston banking institutions present underpenetrated demand for secure digital signature capture in wealth management and commercial lending operations.
Industry Challenges
- Electromagnetic interference engineering talent:Scarce RF design expertise delays product optimization for FCC compliance in smaller hardware vendors.
- Cross-border Health Canada harmonization:Divergent equipment authorization testing requirements between the United States and Canada force redundant certification expenditures for vendors serving both markets.
- Legacy EMR system integration:Hospital information systems built on decade-old architectures resist seamless stylus input adoption without costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Pen Market |
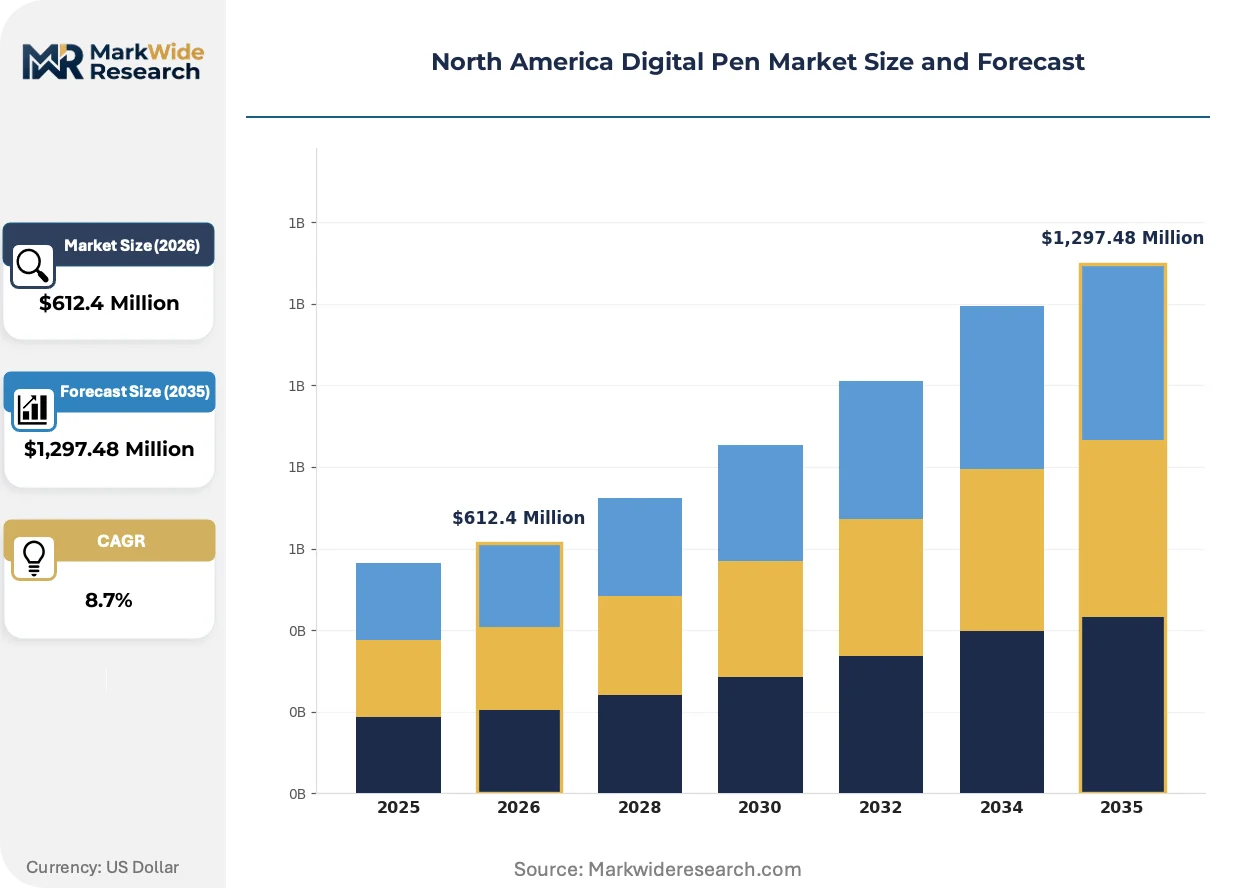
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Pen, Passive Pen, Graphics Pen, Smart Pen End User: Education, Corporate, Design Professionals, Artists Connectivity: Bluetooth, USB, NFC, Wired Battery Type: Rechargeable, Non-Rechargeable, Solar-Powered, Others |
| Companies Covered | Samsung Electronics Co., Ltd., Lenovo Limited, Apple Inc., ASUSTeK Computer Inc., Hewlett-Packard Development Company, L.P., Microsoft Corp., Dell Technologies, Inc., Logitech, Wacom Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Pen Market Strategic Shifts & Innovations
Three forces reshape the North America digital pen landscape: electromagnetic sensing architectures advance precision thresholds, regulatory frameworks tighten wireless emission standards, and procurement patterns shift toward institutional volume contracts.
Active pen electromagnetic resonance technology is converging with low-power Bluetooth Low Energy protocols to enable sub-10-millisecond latency in professional illustration tablets. Adobe Creative Cloud subscribers and industrial design studios in Austin and Seattle drive replacement cycles as tilt recognition and barrel rotation sensing become baseline expectations. The technology convergence compresses addressable market differentiation for mid-tier hardware vendors lacking proprietary digitizer IP.
FCC Part 15 Subpart C regulations governing intentional radiators now mandate expanded spectrum occupancy testing for styluses operating in the 2.4 GHz ISM band. Hardware manufacturers face retooling costs for transmit power calibration to satisfy updated measurement bandwidth requirements. Small and mid-size vendors serving the education technology channel absorb disproportionate compliance burden relative to integrated ecosystem players with captive testing laboratories.
Enterprise procurement teams in healthcare and financial services consolidate stylus purchasing under managed device programs rather than departmental ad-hoc acquisition. Dell Technologies and HP enterprise sales organizations displace retail channel volume through bundled active pen configurations with mobile workstation deployments. This concentration pattern concentrates most visibly in California's integrated delivery networks and Massachusetts mutual insurance headquarters.
North America Digital Pen Market Segmentation
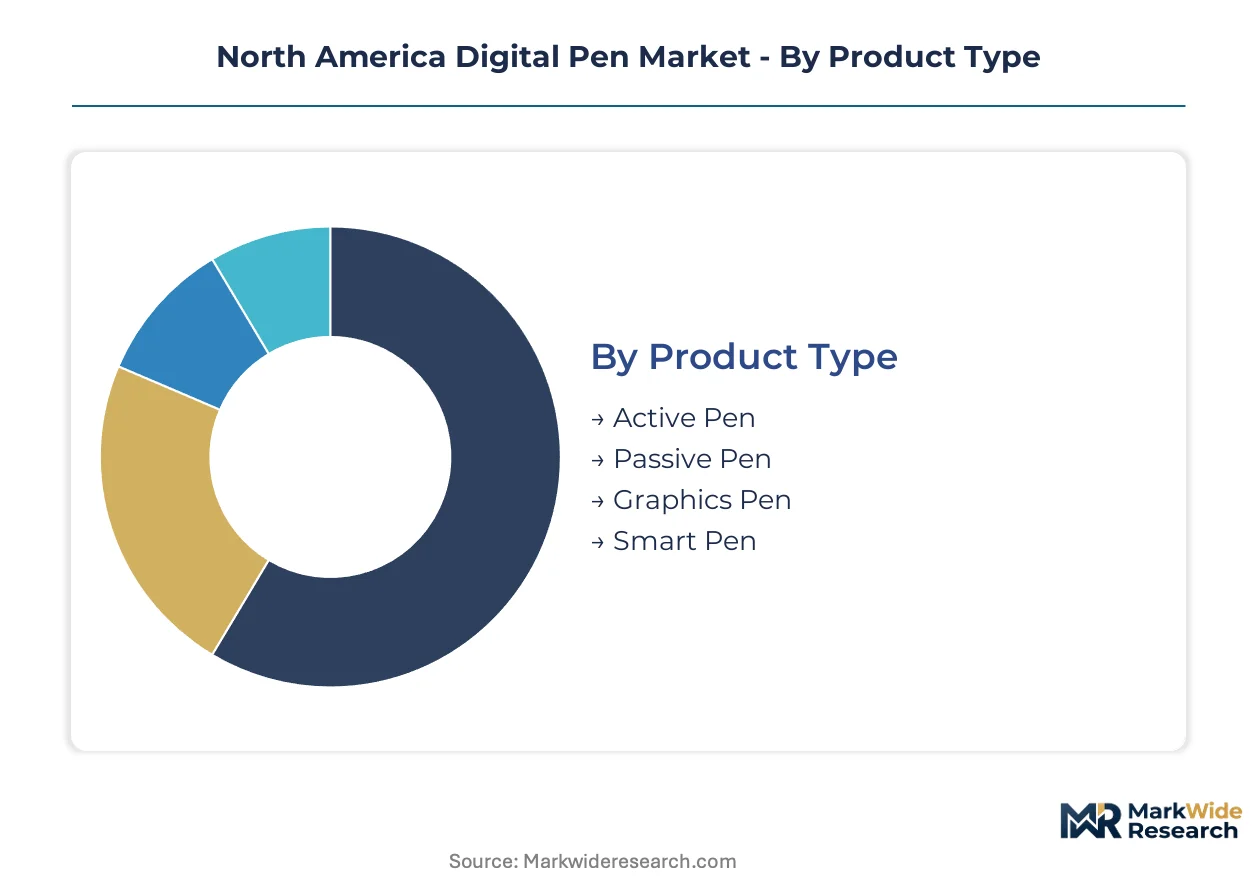
Digital pen procurement decisions diverge sharply across North American buyer segments. Healthcare enterprises prioritize FCC-certified wireless configurations, while educational institutions weigh total cost of ownership against durability specifications. Understanding these segment-specific value hierarchies exposes where hardware vendors capture margin versus where price competition dominates.
Product Type:
Pressure sensitivity thresholds and power integration separate professional-grade investments from commoditized alternatives.
- Active Pen:Electromagnetic resonance architecture with integrated power circuits enables tilt recognition, palm rejection, and sub-10-millisecond latency. Demand concentrates among Texas and Massachusetts healthcare systems deploying HIPAA-compliant electronic health record workflows where transcription accuracy justifies premium hardware spend.
- Graphics Pen:Pressure sensitivity exceeding four thousand distinct gradations combined with barrel rotation sensing targets Adobe Creative Cloud subscribers in California's design studios and Seattle industrial design firms. Austin's gaming concept art houses sustain replacement cycles as precision thresholds advance.
- Passive Pen:Capacitive rubber-tipped designs without onboard electronics serve basic annotation needs in K-12 classrooms where budget constraints override performance requirements.
- Smart Pen:Onboard processors with real-time handwriting-to-text conversion address legal and medical dictation workflows in Northeast financial services and healthcare documentation.
Active Pen leads on scale; Smart Pen leads on momentum.
End User:
Institutional procurement volume versus individual professional purchasing power determines channel strategy and pricing architecture.
- Corporate:Managed device programs at Dell Technologies and HP bundle active pen configurations with mobile workstation deployments. Northeast banking institutions in New York and Boston underpenetrate secure digital signature capture for wealth management operations.
- Education:State-level technology acquisition mandates in Texas and Florida prioritize digital ink solutions for standardized testing infrastructure. Volume procurement compresses per-unit margins while extending replacement cycle visibility.
- Design Professionals:Individual purchasing decisions hinge on pressure fidelity and tilt recognition precision among Adobe Creative Cloud subscribers in California and Washington.
- Artists:Freelance illustrators and independent creators drive mid-tier hardware demand where Wacom digitizer technology sustains premium positioning against ecosystem-locked alternatives.
Education dominates procurement volume; Corporate offers steepest expansion trajectory.
Connectivity:
Wireless protocol standardization across tablet and laptop ecosystems eliminates proprietary interface advantages.
- Bluetooth:Low-energy protocols command the largest protocol share as manufacturers standardize wireless pairing architectures. FCC Part 15 Subpart C certification requirements extend market entry timelines by four to six months for new product introductions.
- USB:USB-IF certification standardization accelerates hardware interoperability across enterprise mobile workstation deployments where IT departments prioritize plug-and-play reliability.
- NFC:Near-field communication enables tap-to-pair simplicity in healthcare environments where workflow efficiency trumps configuration complexity.
- Wired:Tethered configurations persist in high-security government and financial installations where radio frequency emission elimination satisfies information assurance protocols.
Bluetooth leads on scale; USB leads on institutional standardization momentum.
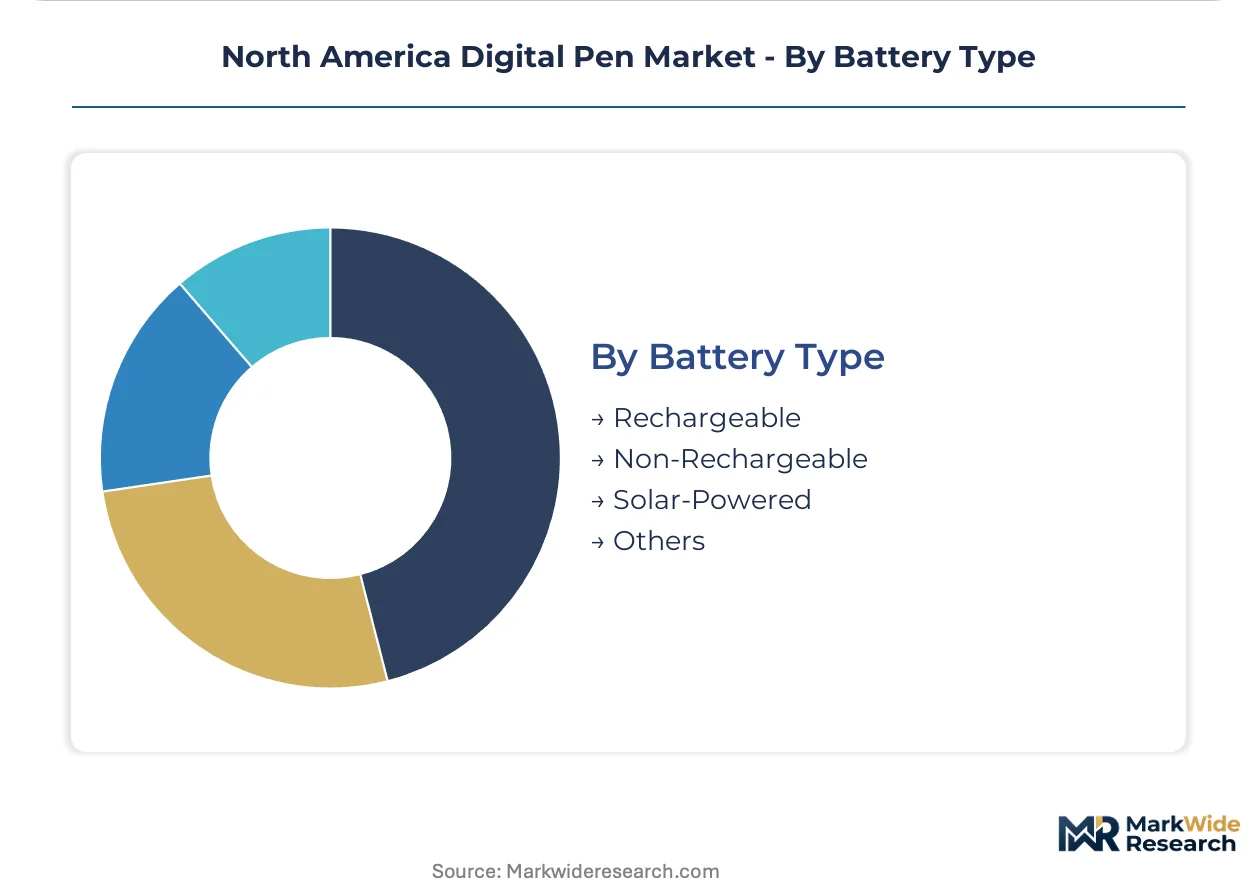
Battery Type:
Operational uptime requirements and total cost of ownership calculations separate rechargeable infrastructure investments from disposable convenience.
- Rechargeable:Lithium-ion cells with USB-C charging dominate professional creative and enterprise healthcare segments where continuous workflow availability justifies infrastructure investment. California's integrated delivery networks specify rechargeable configurations for clinical documentation.
- Non-Rechargeable:Replaceable coin-cell batteries serve education technology channels where IT support capacity limits and upfront hardware cost minimization override lifecycle economics.
- Solar-Powered:Photovoltaic integration targets outdoor fieldwork applications and sustainability-mandated institutional procurement programs with intermittent usage patterns.
- Others:Kinetic energy harvesting and wireless power reception remain experimental configurations without commercial scale in North American deployment.
Rechargeable leads on scale; Solar-Powered gains share fastest among sustainability-mandated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between FCC certification timelines and Health Canada harmonization drive hardware vendors to concentrate product development in jurisdictions with streamlined testing infrastructure. Regulatory-arbitrage pressures intensify as smaller vendors seek single-certification pathways serving both markets.
United States
HIPAA-compliant healthcare documentation and enterprise mobile workstation deployments anchor demand concentration. FCC Part 15 Subpart C mandates expanded spectrum occupancy testing for 2.4 GHz Bluetooth styluses, extending market entry cycles. California's integrated delivery networks and Silicon Valley design studios sustain premium-tier hardware procurement.
Canada
Health Canada equipment authorization requirements run parallel to FCC standards, forcing redundant certification expenditures for cross-border vendors. Ontario and Quebec host component suppliers specializing in pressure-sensing modules for advanced stylus architectures. Toronto's medtech corridor accelerates clinical documentation hardware adoption.
Mexico
Manufacturing cost advantages attract final assembly operations for education-technology channel products targeting North American distribution. Federal telecommunications regulations under IFT govern wireless device importation and commercialization. Guadalajara's electronics manufacturing cluster supports mid-tier hardware production for K-12 procurement programs.
North America Digital Pen Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue ecosystem-locked distribution through tablet and laptop bundling arrangements. The vendor base stratifies across three tiers: integrated device manufacturers with captive stylus programs, specialized digitizer technology developers, and component suppliers serving upstream sensor modules. Strategic archetypes include ecosystem-anchored players leveraging hardware-software integration, premium-positioned specialists targeting creative professionals, and volume-oriented suppliers competing on per-unit cost in education channels. Dominant competitive moves encompass strategic partnerships with enterprise IT vendors and portfolio diversification into adjacent input peripherals.
Within the ecosystem-anchored tier, Microsoft Corp. and Apple Inc. exemplify hardware-software integration strategies that bundle active pen configurations with productivity and creative platforms. Wacom Co., Ltd. occupies a specialist position representing premium digitizer technology development for professional creative segments. Samsung Electronics Co., Ltd. demonstrates scale-driven competitive positioning across multiple device categories with integrated stylus offerings.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Lenovo Limited |
| Apple Inc. |
| ASUSTeK Computer Inc. |
| Hewlett-Packard Development Company, L.P. |
| Microsoft Corp. |
| Dell Technologies, Inc. |
| Logitech |
| Wacom Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Bluetooth Low Energy protocol standardization in active pen architectures compresses manufacturing cost curves while redistributing value capture toward electromagnetic sensor suppliers. FCC Part 15 Subpart C certification requirements elevate fixed compliance costs, forcing smaller vendors toward contract manufacturing partnerships that surrender margin to integrated ecosystem players.
Pricing Analysis
Distributor markups of 15-25 percent on enterprise healthcare bundles compress net margins for standalone hardware vendors competing against Dell Technologies and HP direct-to-OEM discount structures. Pricing stratifies across premium digitizer-integrated configurations, standard Bluetooth-enabled tablets, and economy passive stylus tiers, with certification grade and volume scale driving price differentiation. Cost compression in education channels intensifies as Texas and Florida state procurement programs consolidate purchasing power. K-12 technology coordinators exhibit highest price sensitivity; Massachusetts mutual insurance underwriting teams show lowest.
Supply Chain Analysis
RF design engineering talent scarcity in Guadalajara and Shenzhen final assembly corridors elevates labor costs for electromagnetic interference optimization. Pressure-sensing module production concentrates in Ontario and Quebec; lithium-ion cell supply draws from South Korean and Chinese sources; precision tip sensor fabrication rests on Taiwanese semiconductor foundries. Single-source vulnerability in Canadian upstream sensor modules threatens continuity. Distribution runs through enterprise IT vendor direct sales organizations and education technology resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America digital pen market compounds steadily as HIPAA-compliant healthcare documentation mandates institutional replacement cycles regardless of consumer electronics volatility.
For Market Incumbents: Extend proprietary digitizer IP licensing into adjacent input peripherals to capture recurring royalty streams beyond hardware replacement cycles. Deepen backward integration into pressure-sensing module production to offset Canadian supplier concentration risk. Anchor enterprise sales organizations with Dell Technologies and HP through exclusive active pen bundling arrangements that freeze out emerging entrants. For New Entrants and Emerging Players: The mid-tier price-point gap between Wacom premium positioning and education-channel economy products offers white-space entry. Northeast financial services secure signature capture remains underpenetrated relative to healthcare saturation. Pursue USB-IF certification as primary go-to-market credential to bypass FCC timeline disadvantages facing Bluetooth-dependent competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers specializing in electromagnetic resonance sensors rather than integrated device manufacturers. Five-to-ten year viability favors upstream sensor technology holders over downstream hardware assemblers. Monitor Health Canada-FCC harmonization progress as inflection signal—converged testing standards would compress compliance costs and expand addressable vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| FCC Part 15 Certification Investment | Accelerates market entry timelines for Bluetooth-enabled healthcare stylus configurations. |
| Backward Integration into Sensor Modules | Captures margin from Canadian pressure-sensing suppliers while securing supply continuity. |
| Enterprise IT Vendor Partnership | Locks in volume through Dell Technologies and HP managed device program bundling. |
| USB-IF Standardization Alignment | Reduces interoperability friction in education technology procurement channels. |
| AI Handwriting Recognition Integration | Differentiates Smart Pen offerings for legal and medical dictation workflow capture. |
Research Approach
Multiple input streams — primary interviews with electromagnetic design engineers and healthcare IT procurement directors, secondary validation through FCC equipment authorization databases and USB-IF certification registries, and customs trade data on pressure-sensing module imports — were reconciled through bottom-up and top-down triangulation. Conversations with Texas and Florida state education technology coordinators, hospital biomedical engineering leads, and Adobe Creative Cloud subscriber panels informed demand-side assumptions. SEC 10-K filings from integrated device manufacturers and Health Canada authorization records supplied vendor-side validation.
Data-stream reconciliation across product type, connectivity protocol, battery configuration, and end-user industry dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by procurement volume concentration. Forecast inputs incorporated HIPAA compliance mandate implementation timelines and K-12 state technology acquisition program renewal cycles.
Caveats apply where FCC Part 15 Subpart C testing requirement revisions or Health Canada harmonization delays could materially shift the outlook for new product introduction timelines. Forecasts reflect assumptions about institutional procurement consolidation and electromagnetic sensor supply continuity. Material deviation in certification burden or upstream supply concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Ad Network Software Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Electronic Data Interchange [EDI] Solution Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Distributed Performance and Availability Management Software Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Crew Management Systems Market
Digital Solutions
Service Mesh Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Global Document Scanning Services Market
Digital Solutions
Europe Digital Shipyard Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Real Time Bidding Market