
 Mechanically Separated Meat Market | 2026-2036
Mechanically Separated Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanically Separated Meat Market Foresight
Food service procurement is broadening as quick-service chains and institutional caterers expand mechanically separated meat purchases for patties, nuggets, and emulsified products. Tyson Foods sustains manufacturing scale across multiple protein species through vertically integrated slaughter and deboning complexes. JBS anchors South American supply with integrated cattle and poultry processing networks that feed both domestic and export channels. Cargill competes through diversified protein sourcing and direct relationships with multinational food manufacturers.
Mechanically separated meat denotes skeletal muscle tissue recovered through mechanical means from flesh-bearing bones after manual trimming, typically containing bone particles not exceeding specified size thresholds and fat content varying by species and application. High-pressure processing and blade separation technologies govern yield rates, microbiological stability, and final texture profiles for emulsion-type products. Pork and chicken categories lead volume due to cost efficiency and formulation versatility in processed foods, while beef mechanically separated meat occupies a narrower niche constrained by stricter regulatory limits on bone particle content. Thermal processing applications are expanding fastest among processing technologies as pasteurization requirements tighten across export destinations.
USDA-FSIS oversight in the United States mandates specific labeling and limits on bone solids content, while EFSA and EU hygiene regulations govern species eligibility and cold chain documentation for intra-European trade. These frameworks shape product standards, determine market access corridors, and influence capital allocation toward compliant processing equipment. Stakeholders must monitor evolving maximum residue limits and emerging mechanical recovery method classifications that could reclassify products across regulatory jurisdictions.
Market Dynamics
USDA-FSIS labeling revisions and EU hygiene recasts are compressing product specifications across export corridors, forcing capital redeployment into compliant recovery equipment and cold-chain documentation systems.
Growth Catalysts
- Quick-service protein formulations:Food service operators are expanding mechanically separated poultry procurement for emulsified patties and nuggets, driving volume throughput at integrated slaughter-to-processing facilities.
- REACH-aligned export eligibility:EU hygiene regulations governing species eligibility and cold chain documentation are opening intra-European trade corridors for compliant Brazilian and Thai suppliers.
- High-pressure blade separation:Advanced recovery technologies are improving yield rates and microbiological stability, enabling broader formulation flexibility in processed meat applications.
Market Restraints
- Feedstock cost volatility:Live cattle and broiler price swings in Brazil and the United States transmit directly into mechanically separated meat input costs, squeezing processor margins.
- Bone particle thresholds:USDA-FSIS limits on bone solids content below 1% for beef mechanically separated meat constrain viable supply sources and elevate compliance testing expenditure.
- Plant-based substitution:Pea and soy protein isolates are capturing formulation share in emulsion-type products across European and North American retail channels.
Strategic Opportunities
- Southeast Asian cold chain buildout:Vietnam and Indonesia are expanding refrigerated distribution infrastructure, creating first-mover access for export-compliant mechanically separated poultry suppliers.
- Thermal processing retrofit demand:Pasteurization requirement tightening across Middle Eastern import destinations is accelerating equipment upgrade cycles at legacy recovery facilities.
- Pet food protein diversion:Non-human-grade mechanically separated meat streams are finding offtake in premium pet food formulations, opening margin-recovery channels for sub-specification output.
Industry Challenges
- Microbiological control specialization:Pathogen reduction protocol expertise remains concentrated among veteran plant operators, constraining workforce scalability at new processing installations.
- Multi-jurisdiction certification lag:Simultaneous USDA-FSIS, EFSA, and destination-country approvals extend product launch timelines by 8-14 months for cross-border formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanically Separated Meat Market |
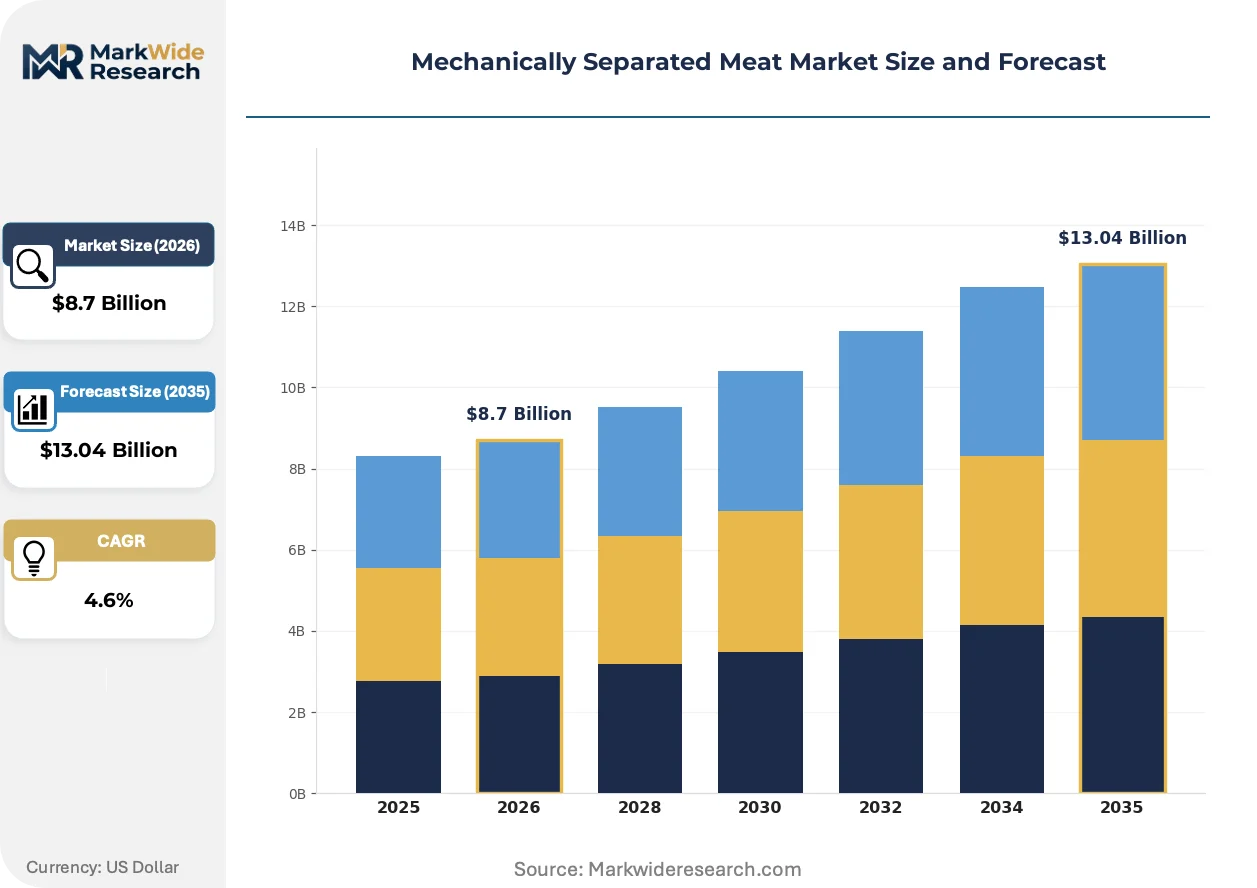
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork, Chicken, Turkey, Beef Processing Technology: High-Pressure Processing, Blade Separation, Vacuum Cooling, Thermal Processing End User: Food Manufacturers, Retail Chains, Food Service, Exporters Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BRF, Hormel, Tyson Foods, Sanderson Farms, Perdue, JBS, Smithfield, OSI Group, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanically Separated Meat Market Shifts & Advancements
Recovery technology refinement and regulatory harmonization pressures are restructuring competitive capability requirements, while downstream formulation demands pull innovation toward precision-controlled texture engineering.
High-pressure processing systems with integrated blade separation modules are electrifying yield optimization and microbiological control at integrated poultry complexes. Quick-service chain suppliers are adopting these platforms at replacement-cycle pace to meet tightening pasteurization standards. The technology is compressing viable operation to facilities with capital depth for full-system overhaul.
EFSA's evolving mechanical recovery method classifications are recategorizing product eligibility across EU member states. Processors face reformulation mandates or reclassification into lower-value product categories depending on recovery technique documentation. Beef mechanically separated meat faces the steepest compliance burden given stricter bone particle thresholds under revised hygiene regulations.
Direct procurement contracts between protein recovery operators and multinational food manufacturers are displacing spot-market purchasing for emulsion-grade supply. This consolidation concentrates volume allocation decisions among fewer procurement desks at Tyson Foods, JBS, and Cargill. Brazil and Thailand exhibit the most pronounced contract penetration as integrated slaughter networks capture downstream formulation relationships.
Mechanically Separated Meat Market Segmentation
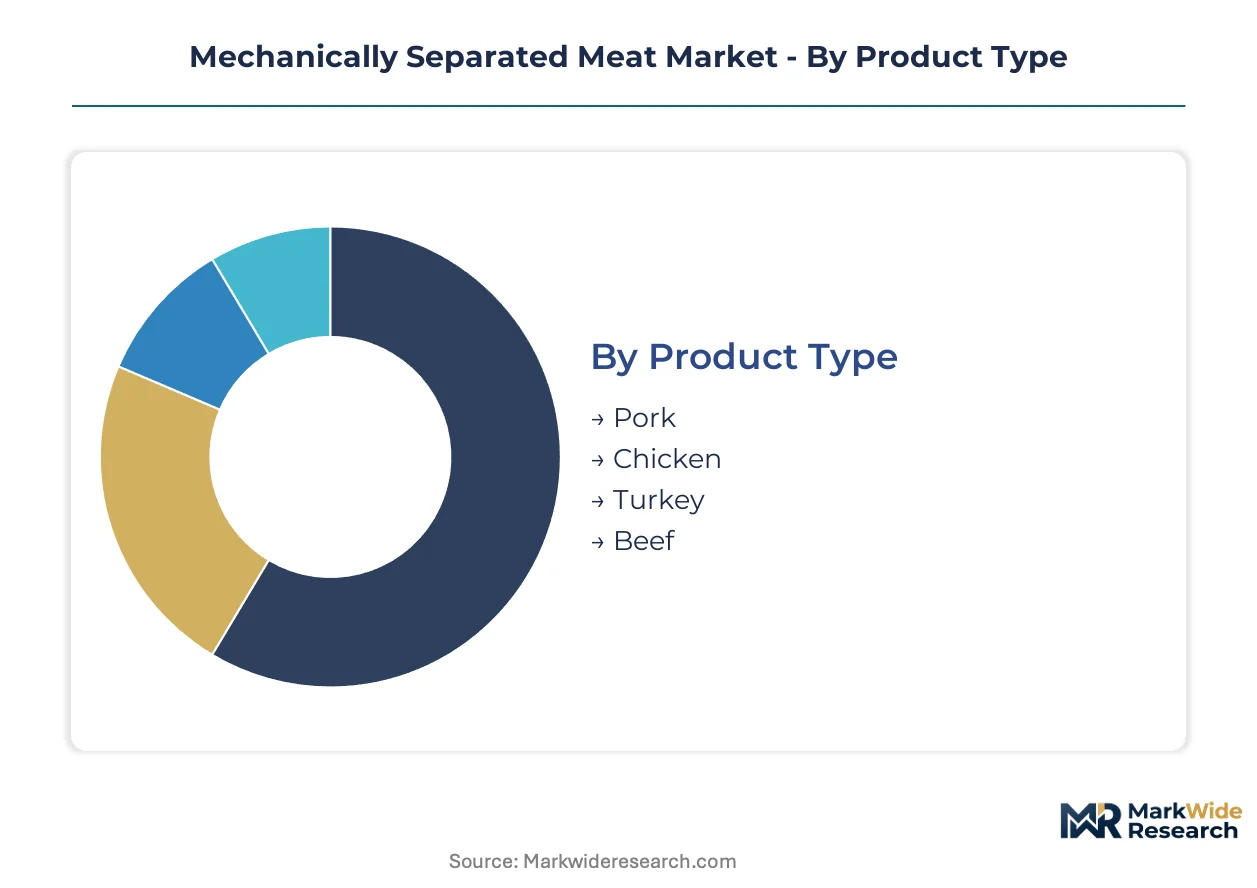
Segmentation in mechanically separated meat markets determines equipment investment, regulatory compliance pathways, and margin structure. Buyers select species and recovery methods based on end-product specifications, export eligibility, and formulation requirements.
Product Type:
Species selection drives bone particle thresholds, fat content limits, and cross-border trade permissions under USDA-FSIS and EFSA frameworks.
- Chicken:Mechanically separated poultry contains higher moisture retention and lower bone solids than red meat alternatives. Quick-service chains in Brazil and Thailand concentrate procurement here for emulsified nugget and patty formulations, drawn by cost efficiency and USDA-FSIS export eligibility.
- Pork:This category offers intermediate fat content and superior binding properties for processed sausage applications. European food manufacturers prioritize compliant pork supply under EFSA hygiene regulations for intra-continental distribution, though bone particle documentation requirements elevate testing costs.
- Turkey:Leaner profile suits health-positioned retail products with reduced saturated fat claims. Domestic US processors supply institutional caterers seeking label-friendly protein sources.
- Beef:Stricter USDA-FSIS bone solids limits below 1% constrain viable supply sources to specialized recovery operations. Niche positioning in premium emulsion products limits volume scale relative to poultry alternatives.
Volume sits with chicken; growth tilts toward pork as EFSA regulatory clarity expands intra-European trade corridors.
Processing Technology:
Capital deployment into recovery systems reflects pasteurization mandates, yield targets, and microbiological control requirements across export destinations.
- High-Pressure Processing:Integrated blade separation modules optimize yield rates while reducing pathogen loads. Brazilian integrated processors at JBS and BRF facilities deploy these systems to meet tightening Middle Eastern import standards.
- Thermal Processing:Pasteurization-centered configurations dominate retrofit demand as Saudi and UAE regulators tighten cold chain documentation. Equipment upgrades compress viable operation to facilities with capital depth for full-system overhaul.
- Blade Separation:Mechanical recovery through precision cutting governs texture profiles in emulsion-type products. Legacy installations remain prevalent in Southeast Asian facilities serving domestic food manufacturers.
- Vacuum Cooling:Rapid temperature reduction preserves microbiological stability in high-throughput poultry operations. Adoption concentrates in Thai export-oriented complexes supplying multinational food manufacturers.
Installed base concentrates in blade separation; expansion tilts most quickly toward thermal processing as pasteurization requirements proliferate.
End User:
Procurement scale and specification stringency vary sharply across customer categories, influencing contract structures and spot market participation.
- Food Manufacturers:Multinational processed meat producers negotiate direct procurement contracts for emulsion-grade supply. Tyson Foods and Cargill procurement desks concentrate volume allocation decisions through integrated slaughter relationships.
- Food Service:Quick-service chains and institutional caterers expand mechanically separated poultry purchases for patties, nuggets, and emulsified products. Menu standardization across US and Brazilian operations drives specification consistency.
- Exporters:Compliance-focused intermediaries navigate multi-jurisdiction certification for Brazilian and Thai supply reaching Middle Eastern and European destinations. Documentation burdens extend launch timelines substantially.
- Retail Chains:Private-label processed meat programs source specified grades for value-tier product lines. European retailers face plant-based substitution pressure in emulsion categories.
Contract volume concentrates with food manufacturers; participation expansion tilts toward food service as quick-service chains vertically integrate procurement functions.
Distribution Channel:
Channel selection reflects order scale, specification complexity, and cold chain infrastructure requirements in destination markets.
- Direct Sales:Multinational food manufacturers and integrated processors transact directly for high-volume, specification-critical supply. Tyson Foods and JBS maintain captive distribution networks for core accounts.
- Distributors:Regional intermediaries aggregate fragmented food service demand across secondary cities in Brazil and Southeast Asia. Cold chain capabilities determine competitive viability.
- Wholesalers:Volume aggregation serves smaller food manufacturers and retail chains without direct procurement infrastructure. Price transparency remains limited relative to direct channels.
- Online Retail:Emerging channel for specialty and non-human-grade product streams entering pet food formulations. Premium positioning supports margin recovery for sub-specification output.
Transaction volume concentrates in direct sales; channel development tilts toward distributors as Southeast Asian cold chain infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's SUDAM tax incentive zone concentrates integrated slaughter-to-processing complexes, while Thailand's Board of Investment privileges anchor Southeast Asian export capacity. Cold chain buildouts in Vietnam and Indonesia are redrawing procurement corridors for mechanically separated poultry.
United States
Quick-service chains drive mechanically separated poultry procurement for emulsified nuggets and patties. USDA-FSIS labeling standards and bone solids limits below 1% for beef mechanically separated meat shape compliance costs. Arkansas and Georgia processing clusters concentrate Tyson Foods and Sanderson Farms capacity serving domestic food manufacturers.
Brazil
JBS and BRF leverage integrated cattle and poultry networks to supply both domestic processors and export channels. ANVISA hygiene regulations align with EU cold chain documentation requirements for intra-European trade eligibility. São Paulo and Paraná slaughter-to-processing corridors anchor South American mechanically separated meat output.
Germany
EFSA mechanical recovery method classifications are recategorizing product eligibility across EU member states. REACH-aligned export standards govern species eligibility and documentation for compliant Brazilian and Thai suppliers. North Rhine-Westphalia food manufacturing clusters process imported mechanically separated pork for continental sausage formulations.
Thailand
Board of Investment privileges accelerate high-pressure processing system adoption at export-oriented poultry complexes. EFSA hygiene regulations and cold chain documentation standards determine Middle Eastern and European market access. Bangkok and surrounding provinces concentrate vacuum cooling installations supplying multinational food manufacturers.
Saudi Arabia
SFDA pasteurization requirement tightening accelerates thermal processing retrofit demand at legacy recovery facilities. Import documentation burdens extend product launch timelines for Brazilian and Thai suppliers reaching Gulf markets. Riyadh and Jeddah distribution hubs aggregate mechanically separated poultry for domestic processed meat manufacturers.
Mechanically Separated Meat Market Competitive Landscape
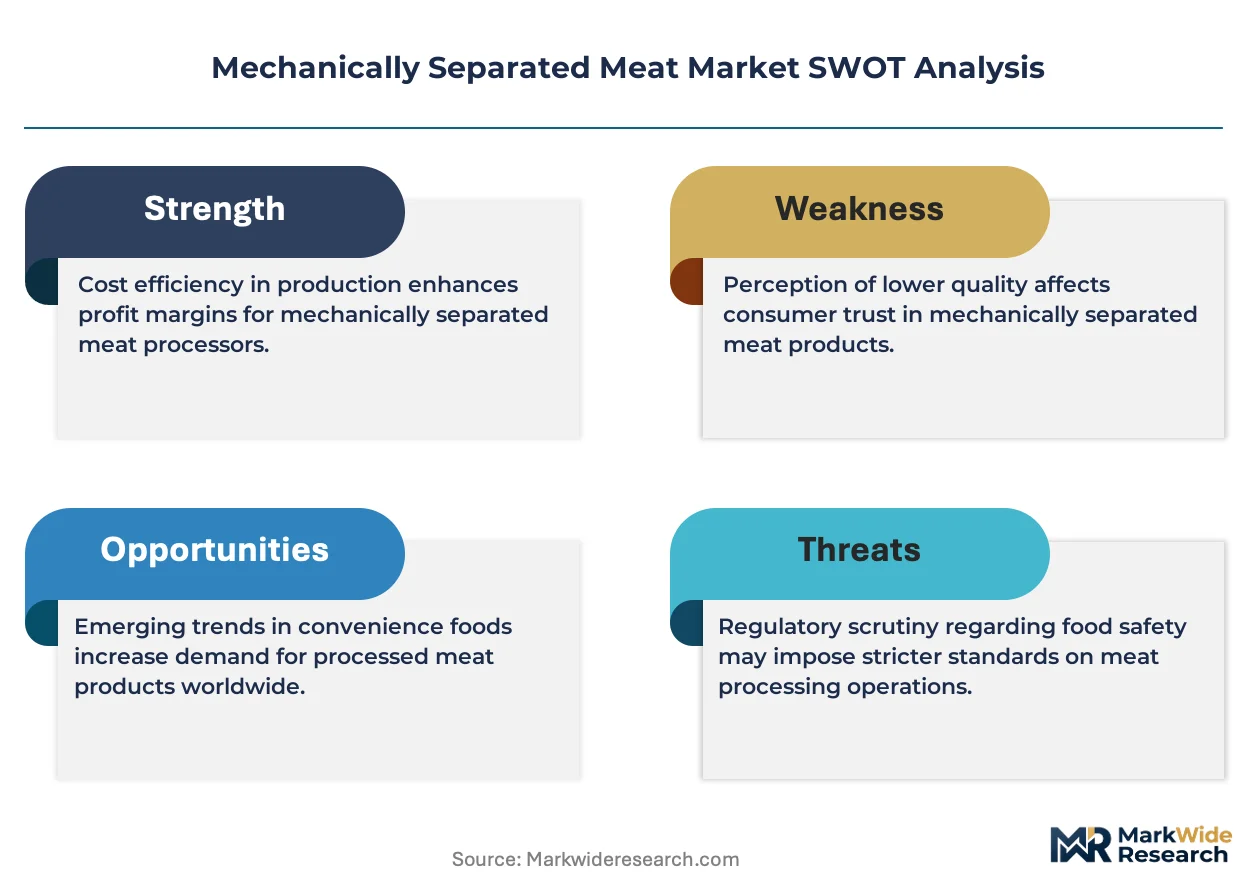
Top-tier vendors anchor integrated slaughter-to-processing infrastructure, while mid-scale operators compete through specialized recovery equipment and regional cold chain relationships. The market exhibits tiered concentration around species-specific capabilities and multi-jurisdiction certification depth. Three archetypes dominate: integrated protein majors with captive supply networks, equipment-technology specialists, and compliance-focused export intermediaries. Capacity expansion and direct procurement contract consolidation represent the primary competitive moves reshaping volume allocation.
Within the integrated protein major tier, Tyson Foods, JBS, and Cargill exemplify scale-driven positioning through vertically controlled slaughter and deboning complexes. These entities occupy positions that concentrate procurement desk influence over emulsion-grade supply allocation. Tyson Foods represents North American poultry integration, JBS anchors South American multi-species networks, and Cargill exemplifies diversified protein sourcing strategies serving multinational food manufacturers.
| Leading Market Players |
|---|
| BRF |
| Hormel |
| Tyson Foods |
| Sanderson Farms |
| Perdue |
| JBS |
| Smithfield |
| OSI Group |
| Cargill |
| Others |
Supply & Pricing Matrix
Live cattle and broiler procurement costs transmit directly from Brazilian and US slaughter complexes into mechanically separated meat pricing tiers, with bone particle compliance grades separating premium contract supply from spot-market economy grades.
Pricing Analysis
Short lead-time premiums command substantial contract uplifts as quick-service chains prioritize specification-consistent supply for emulsified patty formulations. Three-tier pricing structure across premium, standard, and economy levels reflects bone particle thresholds, USDA-FSIS certification depth, and volume commitment scale. Pricing pressure stems from feedstock volatility in Brazilian live markets and plant-based substitution in European retail channels. Food service operators exhibit highest price sensitivity due to menu cost constraints, while multinational food manufacturers absorb premiums for supply security.
Supply Chain Analysis
USDA-FSIS and EFSA qualification gates filter viable suppliers into export-eligible tiers, with documentation burdens extending product launch timelines substantially. Supply concentrates in Brazil, Thailand, and the United States as integrated slaughter-to-processing complexes anchor global mechanically separated poultry output. Raw material flows draw from live cattle, broiler, and turkey operations tethered to cold chain infrastructure. Single-source vulnerability concentrates in Brazilian SUDAM zone complexes serving Middle Eastern import destinations. Distribution runs through direct sales channels for multinational food manufacturers, with regional distributors aggregating fragmented food service demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure blade separation systems are displacing legacy mechanical recovery platforms, compressing viable operation to facilities with capital depth for full-system overhaul and integrated microbiological control.
For Market Incumbents: Deploy thermal processing retrofit programs to capture pasteurization-mandate upgrade cycles across Middle Eastern import destinations. Integrate backward into captive slaughter supply to offset feedstock volatility exposure from Brazilian live cattle markets. Prioritize EFSA mechanical recovery method documentation to defend premium tier positioning against reclassification risk. For New Entrants and Emerging Players: Pet food protein diversion channels offer white-space entry for sub-specification mechanically separated meat streams, with premium positioning supporting margin recovery. Southeast Asian cold chain buildout in Vietnam and Indonesia represents the most penetrable geography for export-compliant poultry supply. Partner with regional distributors possessing refrigerated infrastructure to bypass direct sales channel barriers. For Investors and Strategic Acquirers: EFSA mechanical recovery method reclassification announcements are the leading indicator that compliance-focused equipment specialists will command acquisition premiums. Long-term viability centers on facilities with multi-jurisdiction certification depth spanning USDA-FSIS, EFSA, and destination-country approvals. Target integrated processors with captive slaughter networks in Brazil or Thailand.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal Processing Retrofit | Pasteurization mandate tightening across Saudi SFDA and UAE MOHAP accelerates equipment replacement cycles. |
| Backward Integration into Slaughter | Captive live cattle and broiler supply insulates processors from Brazilian feedstock price volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous USDA-FSIS and EFSA approvals unlock intra-European and Middle Eastern export corridors. |
| Pet Food Channel Development | Premium pet food formulations absorb sub-specification output, recovering margins on non-human-grade streams. |
| Southeast Asian Distribution Partnership | Cold chain infrastructure expansion in Vietnam and Indonesia creates first-mover access for compliant poultry suppliers. |
Research Methodology
USDA-FSIS regulatory filings, EFSA hygiene regulation updates, and Brazilian ANVISA compliance records formed the secondary backbone for mechanical recovery method classifications and cross-border trade eligibility mapping. Primary interviews with plant operations managers at integrated slaughter complexes, regulatory affairs leads at export-focused processors, procurement directors at multinational food manufacturers, and cold chain logistics specialists validated yield rate assumptions and certification timeline estimates. Bottom-up volume modeling from facility-level throughput data triangulated against top-down trade flow analysis across the analysis window.
Bottom-up segmentation modeling anchored volume projections, with species-specific recovery rates, processing technology adoption curves, and end-user procurement contract penetration serving as core analytical lenses. Segmentation dimensions spanned product type, processing technology, end-user category, and distribution channel, with regulatory framework clusters overlaying geographic splits. CAGRs derived from fitted growth curves applied to base-year market sizing, with export eligibility thresholds and pasteurization mandate schedules as industry-specific forecast inputs throughout the projection horizon.
Caveats apply where EFSA mechanical recovery method reclassifications, Brazilian live cattle price shocks, or Middle Eastern import documentation shifts could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
GCC Red Meat Market
Meat Products
Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Blended Meat Market
Meat Products
India Animal Protein Market
Meat Products
Organic Halal Meat Market
Meat Products
Beef Fat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Europe Processed Meat Market
Meat Products
Chicken Fat Market
Meat Products
Global Poultry Meat Market
Meat Products
Shark Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Non-Veg Rte and Rtc Market