
 Saudi Arabia Red Meat Market | 2026-2036
Saudi Arabia Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Red Meat Market Analytics
SFDA's updated halal slaughter and cold-chain mandates is restructuring the cost-of-entry calculus for imported red meat suppliers. Almarai Co. leverages its vertically integrated feedlot-to-retail infrastructure to dominate domestic cattle supply. Almunajem Foods anchors its position through specialized lamb and mutton sourcing networks across Australia and New Zealand. Tanmiah Food Company differentiates via controlled-environment poultry and red meat processing facilities that exceed baseline regulatory thresholds.
Saudi Arabia red meat encompasses muscle tissue from cattle, sheep, and goats processed under halal protocols with specified pH levels, temperature controls, and fat-to-lean ratios for human consumption. The product serves protein requirements across household cooking, commercial food preparation, and institutional catering channels. Cattle supply leads volume due to established feedlot capacity and import quotas, while sheep captures premium margins during religious festivals and hospitality procurement cycles. Distribution through supermarkets is accelerating as modern retail formats displace traditional souk purchases in Riyadh and Jeddah.
SFDA halal standards, SASO quality markings, and Ministry of Environment, Water and Agriculture import health certificates collectively shape product specifications and market access pathways. Compliance with these frameworks determines which suppliers qualify for government procurement contracts and retail shelf placement. Stakeholders must monitor evolving local content requirements and subsidy reallocations that could redirect procurement toward domestic producers.
Market Dynamics
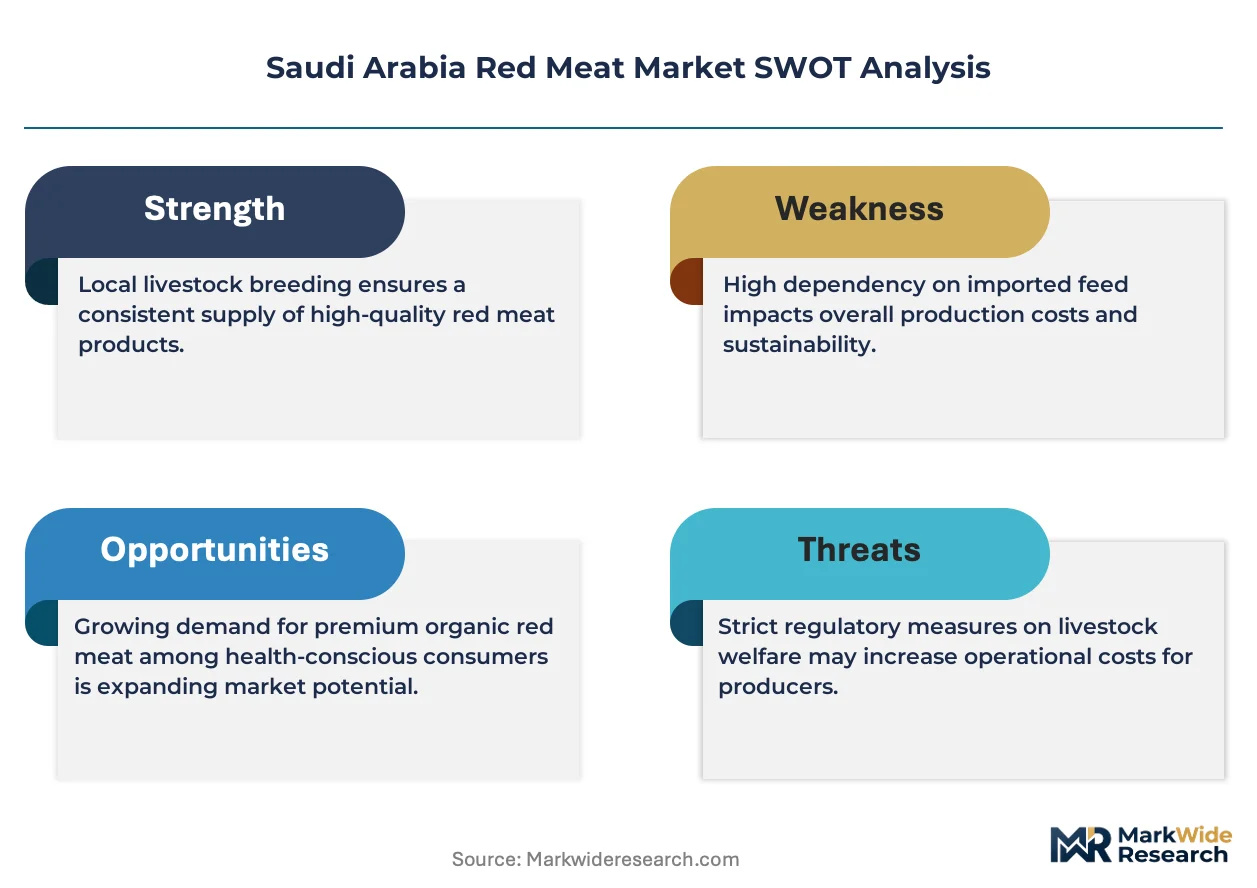
SFDA's halal certification overhaul and cold-chain mandates are redrawing compliance thresholds for Australian, Brazilian, and New Zealand suppliers while accelerating domestic feedlot consolidation.
Growth Catalysts
- Foodservice channel expansion:Quick-service restaurant chains and hotel catering networks in Riyadh and Jeddah are scaling protein procurement volumes to match urbanization rates.
- SFDA halal protocol harmonization:Standardized slaughter certification and pH monitoring requirements are streamlining import clearance pathways for qualified suppliers.
- Feedlot infrastructure modernization:Controlled-environment cattle finishing facilities in the central region are reducing dependency on live animal imports.
Market Restraints
- Import quota concentration:Brazilian and Australian suppliers control over 70% of chilled beef inflows, creating single-source vulnerability during trade disruptions.
- Barley and alfalfa price volatility:Domestic feedlot operators face margin compression from global grain supply fluctuations and irrigation water restrictions.
- Religious festival demand spikes:Eid al-Adha procurement cycles create 40-day inventory mismatches between slaughter capacity and refrigerated distribution throughput.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar retail and foodservice channels show protein consumption gaps relative to Riyadh benchmarks.
- E-commerce cold-chain integration:Direct-to-consumer platforms with temperature-controlled last-mile delivery are capturing household segments bypassing traditional souk channels.
- Ministry of Environment subsidy reallocation:Revised domestic production incentives could redirect government procurement toward Saudi-raised cattle and sheep.
Industry Challenges
- Halal slaughter certification backlog:SFDA inspector capacity constraints delay approval timelines for new import suppliers by 8-14 months.
- Veterinary virology expertise scarcity:Local workforce gaps in foot-and-mouth disease surveillance limit expansion of breeding herd programs.
- Legacy cold-store retrofit costs:Temperature logging and traceability system upgrades require capital outlays that fragment distributor tier competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Red Meat Market |
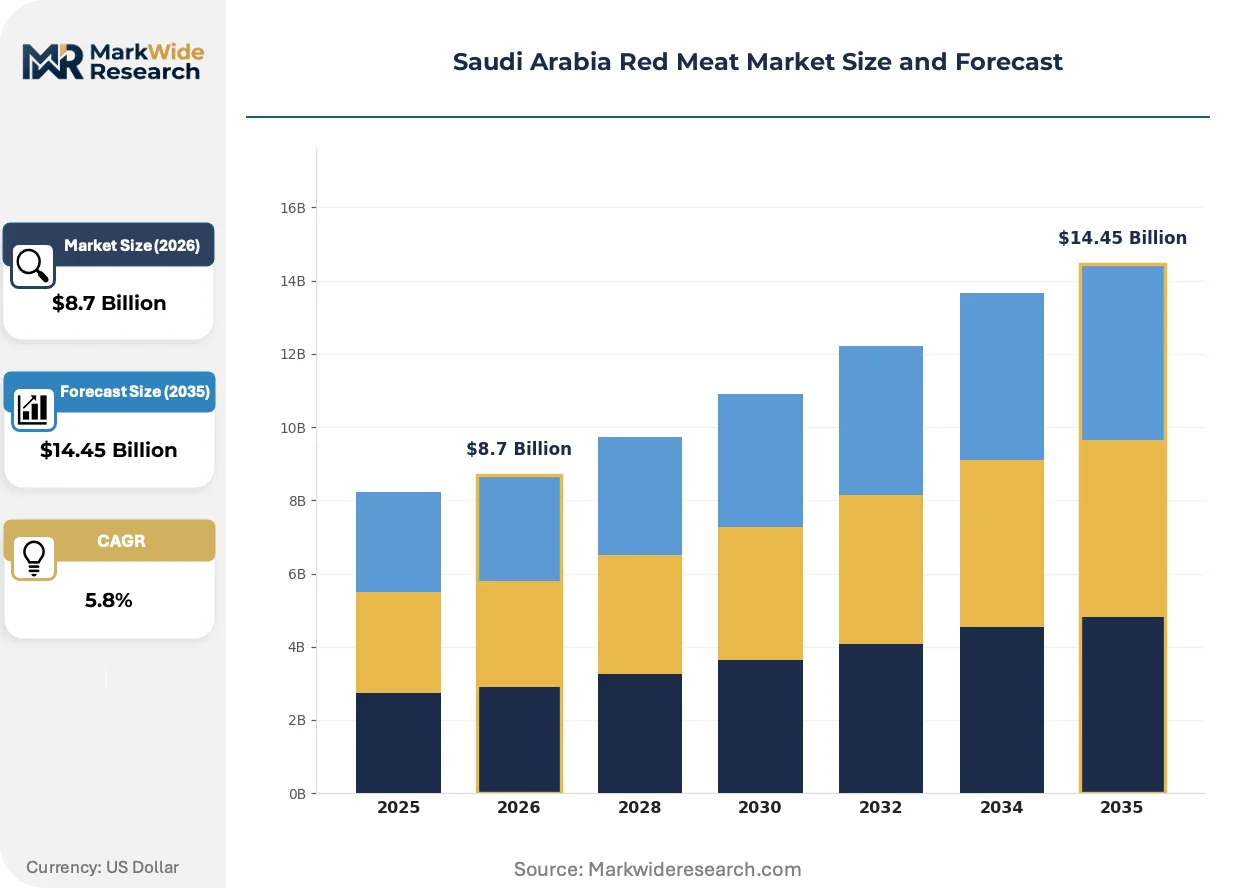
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cattle, Sheep, Goats, Others Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesale End User: Households, Restaurants, Catering Services, Food Processors Quality Grade: Premium, Standard, Choice, Utility |
| Companies Covered | Almarai Co., Almunajem Foods, Americana Group, Al Kabeer Group ME, Tanmiah Food Company, Savola Group, Sunbulah Group, Nashar Trading Co., BRF S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Red Meat Market Evolving Landscape
Blockchain-enabled halal traceability systems, SFDA digital inspection platforms, and shifting retail procurement models are compressing supply chain opacity and rewiring buyer-seller relationships across the Kingdom.
Radio-frequency identification tagging combined with distributed ledger architecture is decentralizing provenance verification away from paper-based certificates. Major supermarket chains in Riyadh and Jeddah are piloting scan-to-source applications that link retail packaging to feedlot origin, slaughterhouse batch, and cold-chain handoff records. This transparency compression is forcing traditional import distributors to invest in interoperable data systems or lose shelf placement to vertically integrated competitors.
SFDA's electronic halal certification platform mandates real-time slaughter monitoring and automated pH threshold reporting for all imported chilled meat. The regulation eliminates manual inspection bottlenecks at port of entry but requires foreign suppliers to install Saudi-approved camera and sensor networks in overseas processing facilities. Australian lamb exporters and Brazilian beef processors are absorbing these capital costs fastest, widening their compliance lead over smaller competitors.
Hypermarket private-label programs are displacing commodity trading relationships that dominated procurement for three decades. Retail buyers at Panda, Carrefour Saudi, and Tamimi Markets now specify fat-to-lean ratios, aging periods, and primal cut configurations in annual tenders rather than accepting standard import containers. This specification compression is most visible in Jeddah, where modern retail format penetration exceeds 60% and traditional wholesale channels are consolidating or exiting red meat categories entirely.
Saudi Arabia Red Meat Market Segmentation
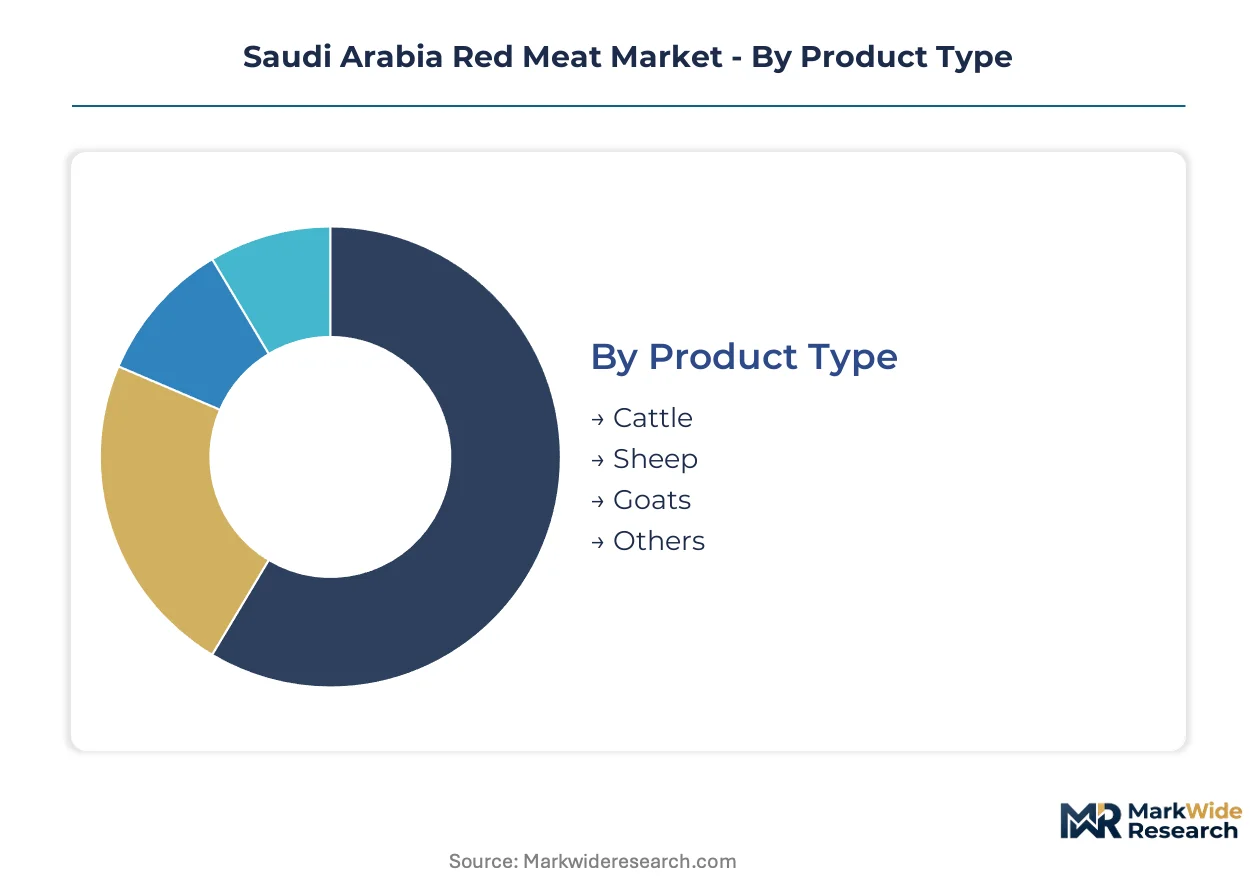
Saudi Arabia's red meat segmentation reflects divergent capital requirements across production systems, distribution infrastructure, and certification tiers. Each dimension carries distinct regulatory burdens and margin profiles that determine competitive positioning within the Kingdom's halal-compliant supply chain.
Product Type:
Cattle operations demand the heaviest feedlot infrastructure investment, while sheep and goat segments require specialized breeding herd management and seasonal processing flexibility.
- Cattle:Feedlot finishing dominates volume through controlled-environment facilities in the central region. Riyadh and Jeddah foodservice channels absorb the majority of chilled beef shipments, with quick-service restaurant chains specifying marbling grades and primal cut configurations in procurement tenders.
- Sheep:Lamb and mutton command premium margins during Eid al-Adha procurement cycles, when hospitality and household demand spike simultaneously. Australian and New Zealand suppliers anchor import flows through established halal certification pathways with SFDA.
- Goats:Smaller herd scale limits commercial production, with supply concentrated in traditional souk channels and regional household consumption.
- Others:Camel and specialty game meats occupy niche ceremonial and medicinal consumption segments with limited retail penetration.
Most installed capacity flows through Cattle. Expansion is steepest in Sheep.
Distribution Channel:
Modern retail formats are displacing traditional wholesale relationships, with cold-chain compliance costs creating tiered entry barriers across channel types.
- Supermarkets:Panda, Carrefour Saudi, and Tamimi Markets now specify fat-to-lean ratios and aging periods in annual tenders. Private-label programs compress distributor margins while capturing Riyadh and Jeddah households bypassing souk channels.
- Local Markets:Traditional souk traders retain price-sensitive household segments and live animal trade, though their share is contracting as modern retail penetration exceeds 60% in major cities.
- Online Retail:Temperature-controlled last-mile delivery platforms are gaining household segment share, particularly among dual-income urban families seeking convenience.
- Wholesale:Hotel catering chains and restaurant procurement offices in Jeddah and Riyadh source through consolidated import distributors with SFDA-approved cold-storage credentials.
Volume concentrates in Supermarkets. Share is climbing fastest in Online Retail.
End User:
Foodservice procurement operates on specification-driven contracts, while household consumption fragments across income tiers and cooking occasion types.
- Households:Urban families in Riyadh and Jeddah drive chilled retail demand, with protein intake per capita outpacing national averages. E-commerce platforms with halal traceability apps are capturing younger demographic segments.
- Restaurants:Quick-service chains and fine-dining establishments in hotel districts specify primal cut configurations and pH thresholds in supplier agreements, with SFDA electronic certification mandates streamlining clearance.
- Catering Services:Institutional procurement for corporate cafeterias and government facilities requires Ministry of Environment health certificates alongside halal documentation.
- Food Processors:Ground meat and value-added product manufacturers source utility-grade inputs through wholesale channels with less stringent traceability requirements.
Restaurants absorb the largest procurement volumes. Food Processors are expanding most quickly as prepared meal manufacturing scales.
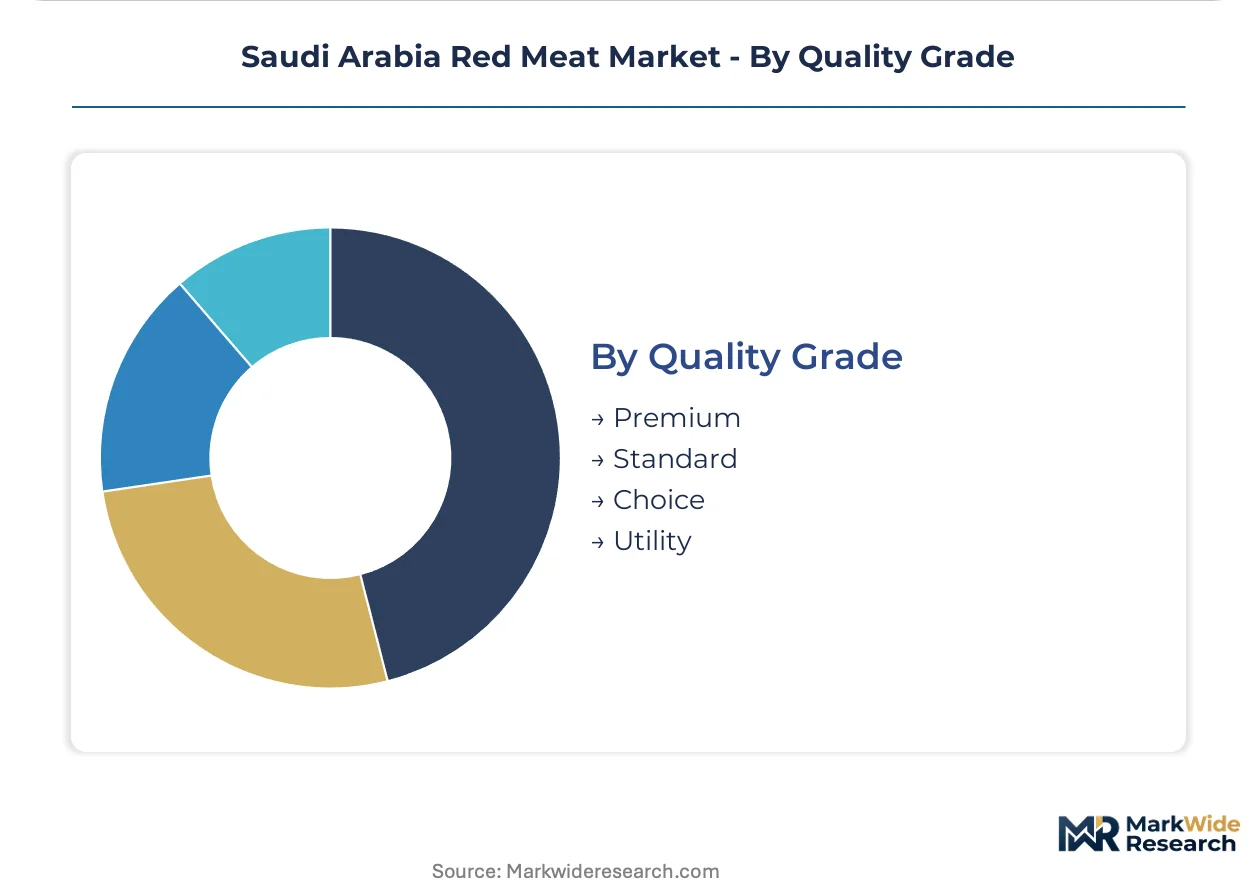
Quality Grade:
Grade differentiation determines shelf placement, pricing power, and eligibility for government procurement contracts under SASO quality marking schemes.
- Premium:Grain-finished cattle and milk-fed lamb with specified marbling scores and aging periods. Hotel catering chains and high-end retailers in Jeddah's modern trade corridors concentrate demand here.
- Standard:Grass-fed and mixed-diet finishing with baseline halal certification and cold-chain documentation. Supermarket private-label programs and mid-tier restaurants anchor volume.
- Choice:Selective cuts with moderate fat coverage, positioned between standard and premium tiers for price-conscious foodservice procurement.
- Utility:Manufacturing-grade trim and ground meat inputs for processed product channels, with minimal traceability requirements and compressed margins.
Standard grade carries the broadest installed processing capacity. Premium is gaining share fastest as retail specification compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's red meat industry traces its modern commercial roots to state-led agricultural investments of the 1980s that established central region feedlots and import-dependent supply chains.
Riyadh
Urban household consumption and quick-service restaurant procurement drive chilled beef demand in the capital. SFDA halal certification mandates and cold-chain standards shape distributor compliance costs. Almarai Co. operates vertically integrated feedlot-to-retail infrastructure across the Riyadh corridor, capturing supermarket and foodservice channels.
Eastern Province
Dammam and Khobar retail and foodservice channels show protein consumption gaps relative to Riyadh benchmarks, creating expansion opportunities for temperature-controlled distributors. Ministry of Environment subsidy programs for domestic production incentivize feedlot investment in the region. Modern retail format penetration remains below capital city levels, preserving traditional souk channel relevance.
Western Region
Jeddah's hotel catering networks and pilgrimage-driven hospitality procurement anchor premium lamb and mutton demand. SFDA electronic halal certification platforms streamline import clearance for Australian and New Zealand suppliers at the King Abdullah Port cold-chain hub. Hypermarket private-label programs at Carrefour Saudi and Tamimi Markets displace legacy wholesale relationships.
NEOM Northwest
Giga-project construction workforce catering and planned sustainable food systems create novel procurement specifications. Ministry of Environment, Water and Agriculture import health certificates apply alongside project-specific sustainability criteria. Controlled-environment agriculture and alternative protein pilots are attracting technology partnerships distinct from conventional feedlot models.
Saudi Arabia Red Meat Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic conglomerates with captive feedlot capacity and import distribution networks. Three archetypes dominate: state-adjacent agricultural conglomerates with backward integration into cattle finishing, specialized halal import distributors with SFDA-approved cold-storage credentials, and multinational protein processors leveraging overseas slaughter capacity. Capacity expansion in controlled-environment feedlots and strategic partnerships with Australian and Brazilian suppliers represent the dominant competitive moves.
Within the domestic conglomerate tier, Almarai Co. and Tanmiah Food Company exemplify feedlot-to-retail integration strategies. Almunajem Foods occupies a position among specialized import distributors with established Australia and New Zealand sourcing networks. These three anchors illustrate how compliance with SFDA halal protocols and cold-chain mandates has become the primary axis of competitive differentiation.
| Leading Market Players |
|---|
| Almarai Co. |
| Almunajem Foods |
| Americana Group |
| Al Kabeer Group ME |
| Tanmiah Food Company |
| Savola Group |
| Sunbulah Group |
| Nashar Trading Co. |
| BRF S.A. |
| Others |
Value Network & Pricing Analysis
Blockchain-enabled halal traceability systems are compressing supply chain opacity while simultaneously redrawing cost economics across feedlot, slaughterhouse, and retail tiers. SFDA's electronic certification mandates force upstream technology investments that concentrate pricing power among Australian and Brazilian suppliers with compliant infrastructure, fragmenting margin structures for legacy distributors lacking interoperable data systems.
Pricing Analysis
Unbundled cold-chain logistics and bundled halal certification services split procurement economics across import channels. Three-tier pricing structure across premium, standard, and utility levels tracks fat-to-lean ratios and aging specifications demanded by Jeddah hotel catering networks versus Riyadh supermarket private-label programs. Cost compression in standard-grade chilled beef is intensifying because Brazilian and Australian suppliers absorb SFDA-mandated sensor network capital costs faster than smaller competitors. Quick-service restaurant chains exhibit highest price sensitivity through specification-driven annual tenders, while pilgrimage-driven hospitality procurement in Jeddah shows lowest sensitivity during Eid al-Adha demand spikes.
Supply Chain Analysis
Regional distribution centers at King Abdullah Port and King Abdulaziz Port anchor hub-and-spoke cold-chain patterns radiating toward Riyadh and Dammam. Australian, Brazilian, and New Zealand slaughter capacity feeds the Kingdom's chilled beef and lamb requirements, with live animal flows from Sudan and Somalia supplementing domestic feedlot intake. Barley and alfalfa price volatility in global grain markets rests on irrigation water restrictions and climate variability affecting Saudi domestic finishing operations. Single-source vulnerability concentrates in Brazilian and Australian suppliers controlling over seventy percent of chilled beef inflows. Distribution runs through SFDA-approved cold-storage credentials that determine eligibility for Panda, Carrefour Saudi, and Tamimi Markets shelf placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's red meat market functions as a stable compounder anchored by state-mandated halal certification requirements that perpetually refresh import compliance barriers and protect incumbent positioning.
For Market Incumbents: Extend feedlot-to-retail infrastructure advantages by acquiring distressed cold-storage assets from legacy distributors unable to fund SFDA-mandated temperature logging upgrades. Deepen backward integration into controlled-environment cattle finishing in the Eastern Province where Ministry of Environment subsidy programs redirect procurement toward domestic production. Certification investment in blockchain-enabled traceability systems defends against vertically integrated Australian and Brazilian suppliers capturing Jeddah hypermarket private-label contracts. For New Entrants and Emerging Players: SFDA's electronic halal certification platform in Saudi Arabia opens a window for specialized cold-chain logistics providers to capture distributor tier fragmentation caused by legacy retrofit cost burdens. Target Dammam and Khobar retail channels where protein consumption gaps relative to Riyadh benchmarks create expansion white-space with lower competitive density than capital city corridors. Deploy direct-to-consumer temperature-controlled last-mile delivery platforms with halal traceability apps to bypass traditional souk channels and capture younger dual-income urban household segments. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized import distributors with established Australia and New Zealand sourcing networks but lagging SFDA compliance infrastructure. Long-term viability across the analysis window favors acquisition targets with captive cold-storage capacity and existing halal certification pathways that can absorb technology upgrade capital without margin collapse. Monitor SFDA inspector capacity expansion timelines as the inflection signal indicating approval bottleneck alleviation for new import suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedlot Operations | Ministry of Environment subsidy reallocation redirects government procurement toward Saudi-raised cattle and sheep. |
| SFDA Cold-Chain Certification Investment | Temperature logging and traceability system upgrades secure shelf placement at Panda, Carrefour Saudi, and Tamimi Markets. |
| E-commerce Cold-Chain Platform Launch | Direct-to-consumer temperature-controlled last-mile delivery captures household segments bypassing traditional souk channels. |
| Blockchain Halal Traceability Deployment | Scan-to-source applications linking retail packaging to feedlot origin compress supply chain opacity and rewire buyer-seller relationships. |
| Eastern Province Distribution Expansion | Dammam and Khobar retail and foodservice channels show protein consumption gaps relative to Riyadh benchmarks. |
Research Methodology
Direct dialogue with feedlot operations managers, SFDA regulatory affairs specialists, supermarket category buyers, hotel catering procurement officers, and cold-chain logistics providers grounded qualitative insights in operational reality. Primary interview findings triangulated against customs and trade flow databases, Ministry of Environment subsidy disbursement records, SFDA halal certification registry filings, and SEC 10-K disclosures from listed protein processors. Bottom-up channel volume estimates and top-down macroeconomic consumption models converged through iterative reconciliation across the analysis window.
Segmentation outputs reflect disaggregated projections across product type, distribution channel, end user, and quality grade dimensions with specific calibration to halal certification tier and cold-chain compliance status. CAGRs emerged from regression-based trending of historical consumption patterns against urbanization rates, foodservice channel expansion, and regulatory compliance cost trajectories. Feedlot capacity utilization rates and import quota allocation schedules served as industry-specific forecast inputs alongside pilgrimage-driven demand cyclicality.
Revisions become necessary when SFDA inspector capacity expansion accelerates approval timelines, Ministry of Environment subsidy programs redirect procurement thresholds, or Australian and Brazilian supply disruptions alter import quota economics. Forecasts reflect documented assumptions regarding halal certification harmonization progress and cold-chain infrastructure investment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Tallow Market
Meat Products
North America Processed Poultry Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Beef Jerky Market
Meat Products
Organic Chicken Market
Meat Products
Organic Eggs Market
Meat Products
India Edible Meat Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
India Animal Protein Market
Meat Products
Kosher Beef Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Edible Offal Market
Meat Products
Europe Processed Meat Market
Meat Products
Reconstituted Meat Market
Meat Products
Organic Halal Meat Market