
 Graphics DDR SDRAM Market | 2026-2036
Graphics DDR SDRAM Market Size, Share, and Industry Trends Forecast 2026-2036
Graphics DDR SDRAM Market Insights
Software-defined memory tuning subscriptions is repositioning how OEMs monetize performance headroom in discrete GPUs. Samsung Electronics leverages captive wafer supply to dominate GDDR6X and HBM3 stacks. SK Hynix anchors next-generation AI accelerator sockets with its advanced packaging roadmap. Micron Technology competes through vertical control over DRAM process nodes from Idaho fabs to module assembly.
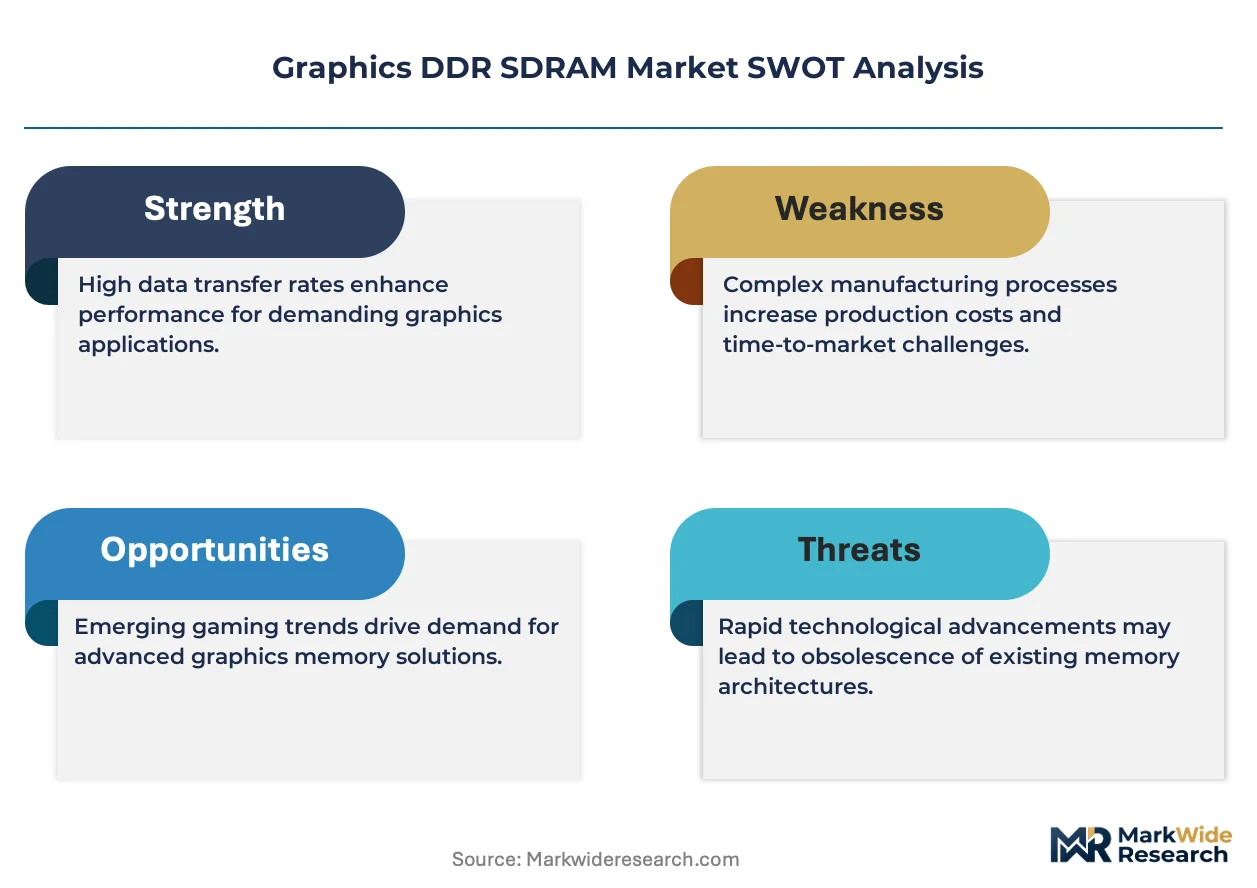
Graphics DDR SDRAM denotes specialized double-data-rate synchronous dynamic random-access memory engineered for high-throughput parallel processing, with GDDR6 modules achieving data rates exceeding 16 Gbps per pin and operating at 1.35V to feed GPU memory controllers. This memory class serves the primary commercial purpose of eliminating bandwidth bottlenecks in rasterization, tensor operations, and frame buffer streaming. DDR5 modules for gaming PCs command premium positioning as overclocking ecosystems mature, while high bandwidth memory stacks capture margin pools in AI training silicon where interposer-based 3D integration justifies cost premiums. Standard memory configurations across workstations face commoditization pressure as channel inventory normalizes.
FDA oversight of medical imaging workstations indirectly shapes reliability requirements for VR-ready memory subsystems in surgical planning suites. The EU AI Act and REACH chemical restrictions are forcing module makers to document supply chain provenance for flame-retardant PCB substrates. China's MIIT dual carbon goals are accelerating domestic GDDR pilot lines toward energy-efficiency benchmarks. Stakeholders must monitor how JEDEC's pending GDDR7 specification reshapes R&D allocation between incumbent foundry partners and emerging packaging houses.
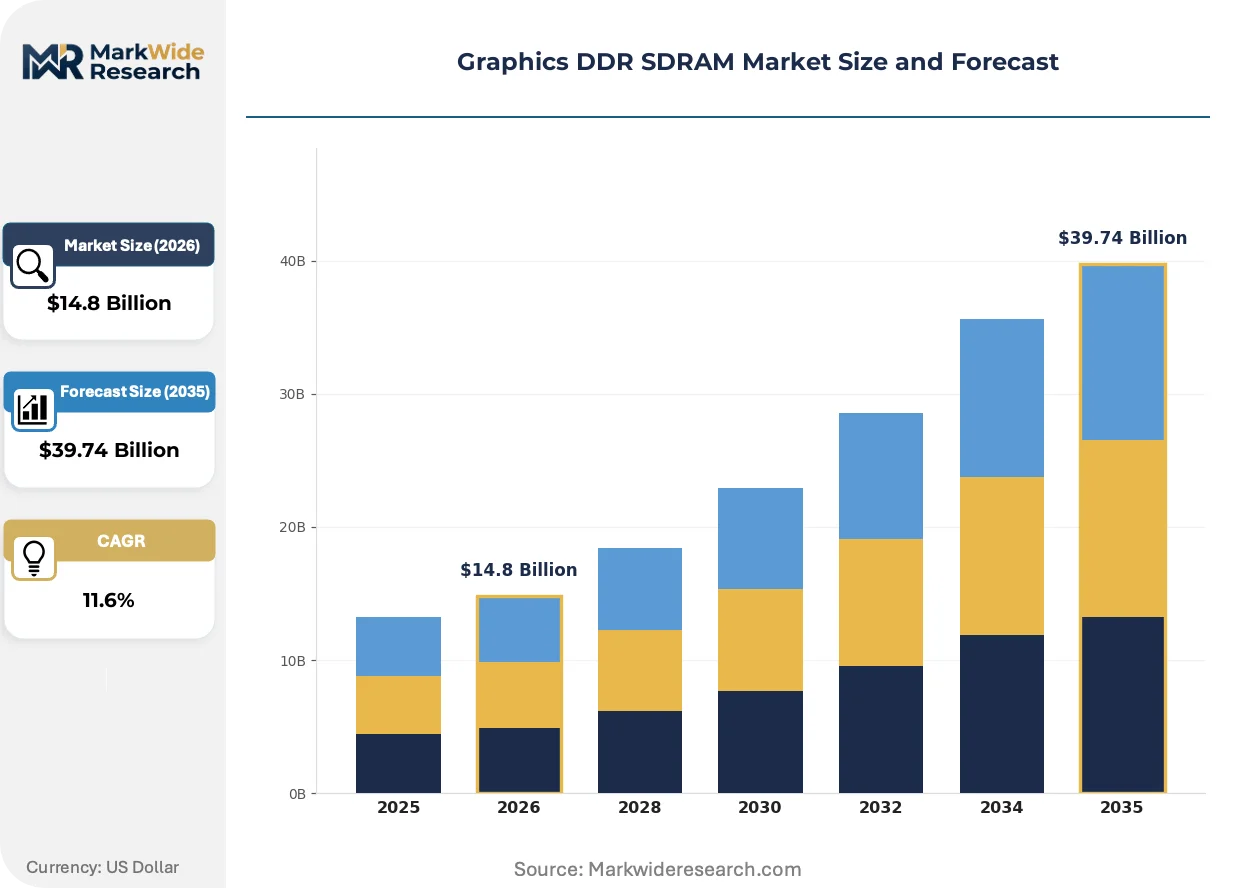
Market Dynamics
AI training clusters are absorbing high-bandwidth memory modules at unprecedented rates, compressing supply availability for discrete GPU segments and forcing foundry allocation decisions toward advanced packaging nodes.
Growth Catalysts
- EU F-Gas Regulation:Pressure toward lower thermal profiles is accelerating module redesigns that reduce cooling overhead in dense server farms.
- AI training clusters:Exponential bandwidth requirements from tensor operations are pulling HBM3 and next-generation stack architectures into mass production.
- Taiwan's semiconductor packaging corridor:Concentration of 2.5D/3D interposer capacity is enabling rapid scaling of memory-module throughput for accelerator sockets.
Market Restraints
- Silicon interposer cost volatility:Advanced substrate pricing swings compress margin pools for mid-range discrete GPU configurations.
- Taiwan packaging concentration:Geographic chokepoint in CoWoS and similar technologies creates supply vulnerability for AI accelerator memory stacks.
- Thermal density limitations:Power dissipation ceilings in 1.35V operating envelopes constrain per-pin data rate scaling for GDDR6X modules.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Incentives for semiconductor assembly and testing are attracting module packaging investments outside traditional East Asian hubs.
- Software-defined memory tuning:Subscription-based performance optimization creates recurring revenue streams from overclocking ecosystems in gaming PCs.
- GDDR7 specification convergence:JEDEC's pending standard opens white space for foundry partnerships beyond incumbent packaging houses.
Industry Challenges
- Advanced packaging talent scarcity:Shortage of interposer design and thermal-mechanical engineering expertise slows HBM stack qualification timelines.
- REACH chemical documentation:EU flame-retardant PCB substrate provenance requirements extend compliance cycles for module imports.
- Legacy GDDR5 inventory absorption:Channel normalization pressures create pricing friction against newer node transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graphics DDR SDRAM Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR3, DDR4, DDR5, GDDR6 End User: Gaming Consoles, Workstations, PCs, Mobile Devices Technology: Standard Memory, High Bandwidth Memory, Stacked Memory, Low Power Memory Application: Artificial Intelligence, Virtual Reality, Video Editing, Graphic Design |
| Companies Covered | Kingston Technology, G.Skill, Samsung Electronics, Crucial, ADATA, SK Hynix, Corsair, TeamGroup, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graphics DDR SDRAM Market Trends and Innovations
Memory architectures are bifurcating between bandwidth-optimized stacks for AI accelerators and latency-tuned modules for real-time rendering, with packaging technology determining competitive position.
Hybrid bonding is integrating copper-to-copper interconnects at sub-10 micron pitches, replacing microbump stacking in HBM3E production. Hyperscale AI deployers are qualifying these modules for training clusters exceeding 100k GPU sockets. The technology is integrating memory and logic dies into unified thermal envelopes that simplify system-level cooling design.
China's MIIT dual carbon goals are mandating energy-efficiency benchmarks for domestic GDDR pilot lines, forcing process node optimizations that reduce per-bit power consumption. Module makers are responding with low-voltage signaling architectures and substrate materials selected for thermal conductivity. Domestic foundries in Shanghai and Hefei are prioritizing these specifications for local AI accelerator supply chains.
Enterprise buyers are consolidating procurement around qualified supplier lists, displacing spot-market purchasing for high-volume AI infrastructure builds. System integrators are bundling memory-module warranties with accelerator socket contracts to reduce qualification overhead. This concentration is most visible in North American hyperscale deployments where single-source HBM agreements now span multi-year horizons.
Graphics DDR SDRAM Market Segmentation
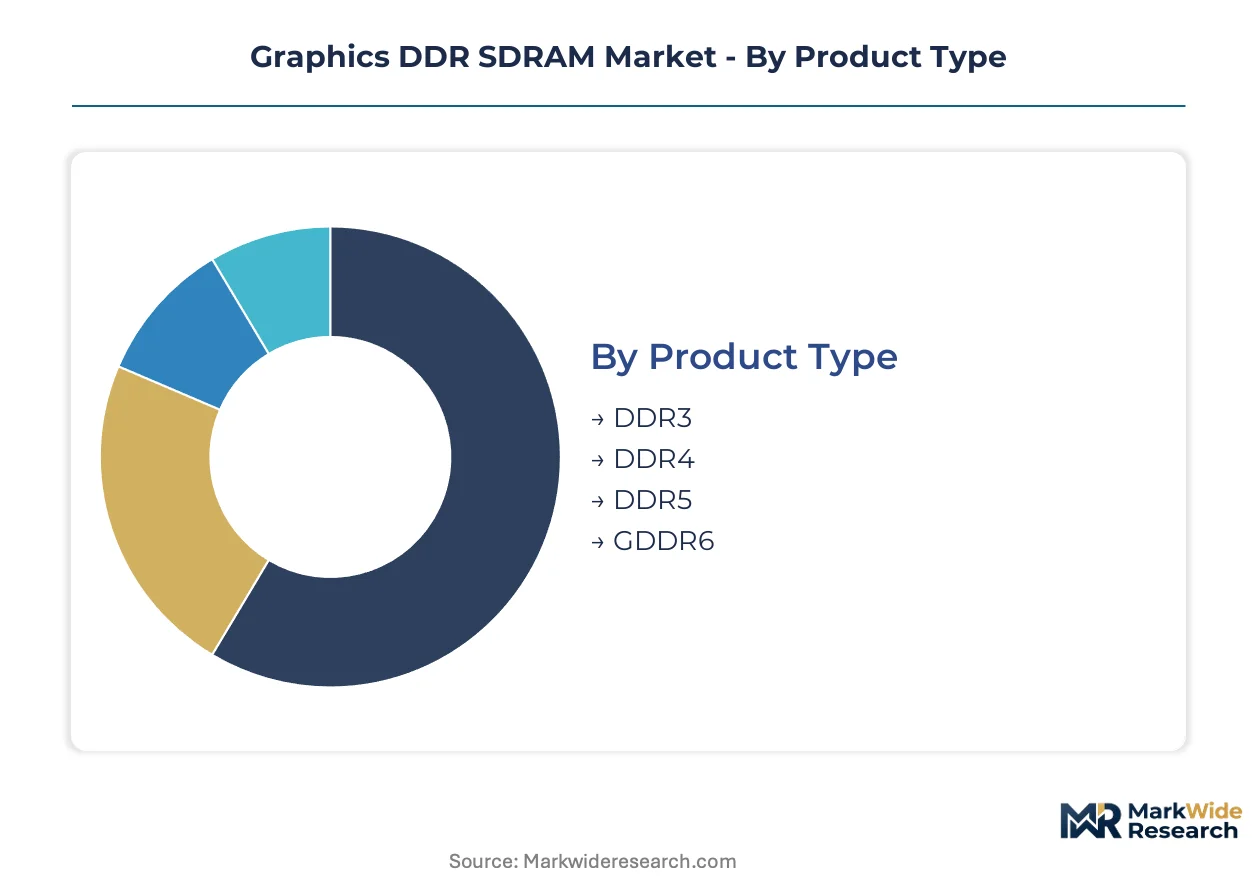
Graphics DDR SDRAM segmentation reveals how capital allocation, thermal constraints, and workload parallelism dictate memory architecture choices. Foundries prioritize interposer capacity for high-bandwidth stacks while channel vendors manage inventory mix across legacy and current-generation modules.
Product Type:
Capital intensity escalates sharply from commodity DDR modules through advanced GDDR architectures, with lithography node transitions and packaging complexity driving fab investment thresholds.
- DDR3:Mature 30nm-class process technology with single-ended signaling at 1.5V. Legacy gaming console refurbishment programs in Mexico and Eastern Europe sustain residual demand amid declining wafer allocation.
- DDR4:1.2V operating envelope with burst-length-8 prefetch architecture. Corporate workstation refresh cycles in Germany and Japan absorb volume for enterprise visualization pipelines.
- DDR5:Dual 32-bit subchannels and on-die ECC enable 4800 MT/s baseline throughput. Gaming PC builds in South Korea and the United States pull supply as overclocking ecosystems mature around XMP 3.0 profiles.
- GDDR6:16 Gbps per-pin data rates via quad data rate signaling at 1.35V. Discrete GPU configurations for AI inference at the edge concentrate demand in Taiwan's packaging corridor, where thermal interface material selection determines module reliability.
GDDR6 absorbs the bulk of installed capacity; DDR5 is expanding most quickly.
End User:
Volume concentration varies by thermal design power tolerance and qualification rigor, with hyperscale deployers imposing the most stringent burn-in protocols.
- Gaming Consoles:Unified memory architectures sharing bandwidth between CPU and GPU complexes. Sony and Microsoft procurement cycles in Japan and the United States drive GDDR6 contract volumes with 5-7 year supply agreements.
- Workstations:ECC-enabled modules for professional visualization and CAD pipelines. German automotive design centers and California media production facilities specify error-correction for render farm reliability.
- PCs:Channel-driven demand with price elasticity around DDR4-to-DDR5 migration. Southeast Asian system integrators in Vietnam and Indonesia manage inventory exposure through spot-market purchasing.
- Mobile Devices:LPDDR5X at 8.5Gbps for integrated graphics in ARM SoCs. Chinese handset OEMs in Shenzhen and Dongguan dominate procurement for gaming-centric smartphones.
Gaming consoles lock in the longest contract horizons; mobile devices are climbing the fastest.
Technology:
Margin structure inverts between commodity standard modules and interposer-based stacks, with packaging yield rates determining economic viability.
- Standard Memory:Conventional wire-bond or flip-chip BGA packages for discrete DIMMs. Channel distribution in the United States and Germany faces pricing pressure as DDR5 supply normalizes.
- High Bandwidth Memory:TSV-interconnected die stacks with 1024-bit interface widths. NVIDIA and AMD accelerator sockets in Taiwan and California consume HBM3E output as hybrid bonding displaces microbump stacking.
- Stacked Memory:2.5D interposer integration for bandwidth-constrained AI workloads. South Korean packaging houses qualify these modules for training clusters exceeding 50,000 GPU sockets.
- Low Power Memory:Sub-1.1V signaling for thermal-constrained form factors. China's MIIT energy-efficiency benchmarks accelerate domestic LPDDR pilot lines toward per-bit power reduction targets.
Standard memory ships the highest unit volumes; high bandwidth memory commands the steepest expansion trajectory.
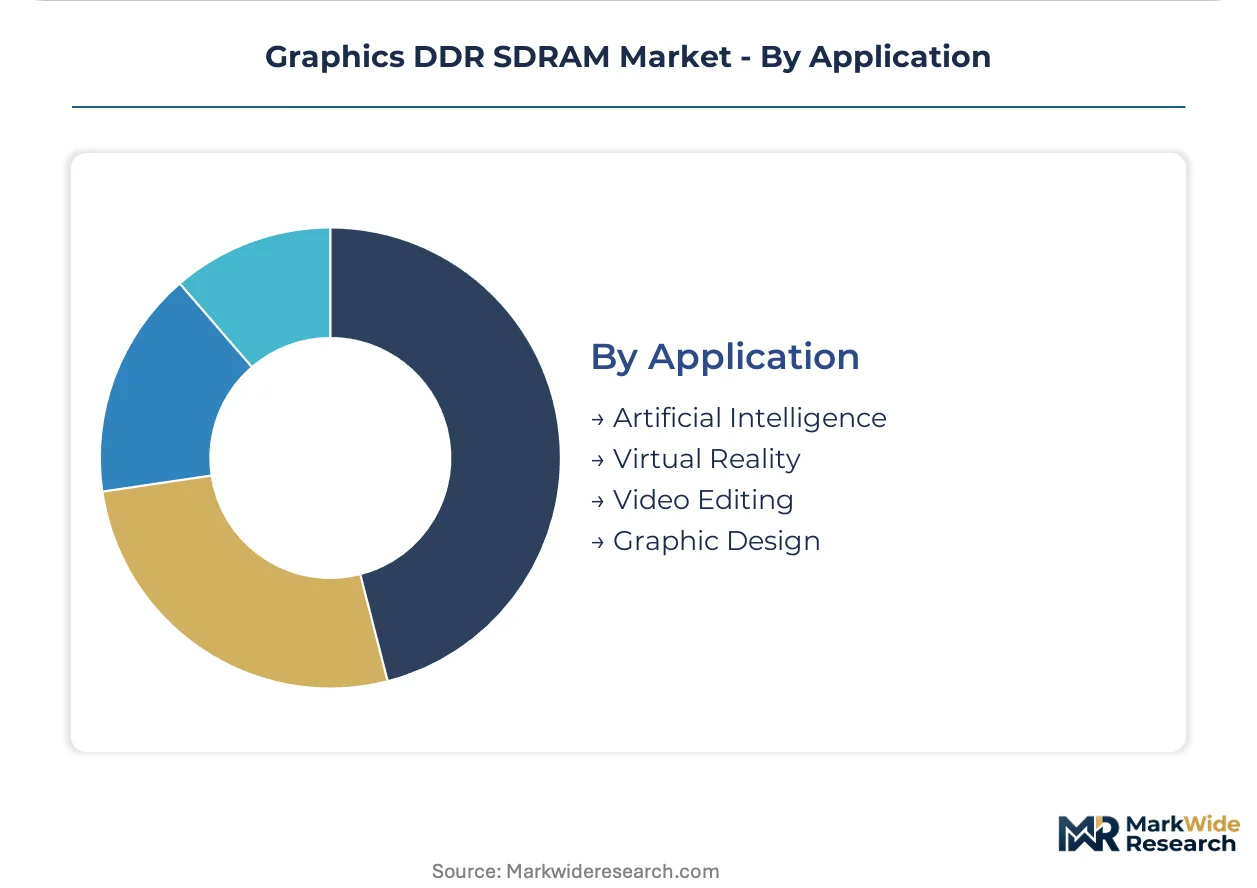
Application:
Workload parallelism requirements segment memory architectures between bandwidth-optimized tensor operations and latency-sensitive frame delivery.
- Artificial Intelligence:Training clusters demand HBM3 stacks with terabyte-per-second aggregate bandwidth. Hyperscale deployers in Virginia and Frankfurt consolidate procurement around qualified supplier lists spanning multi-year horizons.
- Virtual Reality:Sub-20ms motion-to-photon latency mandates GDDR6 frame buffer capacity. Surgical planning suites in Swiss university hospitals and Japanese medical centers specify VR-ready memory subsystems under FDA and PMDA oversight.
- Video Editing:Large contiguous memory spaces for 8K timeline scrubbing. Adobe and DaVinci Resolve workstations in California and London prioritize capacity over bandwidth for proxy-free workflows.
- Graphic Design:Moderate bandwidth with color-accurate display pipeline support. Creative agencies in Paris and Milan standardize on DDR5 configurations for Adobe Creative Cloud performance tiers.
Artificial intelligence dominates capital deployment; virtual reality is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian packaging corridors while consumption spreads across North American hyperscale deployments and European industrial automation. Taiwan and South Korea anchor wafer-level output, yet demand pull originates from AI training clusters in Virginia and Frankfurt.
United States
Hyperscale AI deployers in Virginia and California consolidate procurement around qualified supplier lists spanning multi-year horizons. The SEC's climate disclosure rules pressure data center operators toward energy-efficient memory subsystems. Austin and Phoenix host accelerator socket design centers where HBM3E qualification timelines compress.
Taiwan
CoWoS and 2.5D interposer capacity concentrates in Hsinchu and Taichung packaging corridors. The National Development Council's semiconductor advancement programs subsidize advanced packaging R&D. Tainan's science parks absorb hybrid bonding equipment for next-generation stack architectures.
South Korea
Samsung and SK Hynix anchor HBM3 output for NVIDIA and AMD accelerator sockets. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt initiative funds domestic packaging expansion. Pyeongtaek and Icheon host memory die fabrication where process node transitions accelerate.
China
Domestic GDDR pilot lines in Shanghai and Hefei scale toward MIIT dual carbon energy-efficiency benchmarks. The National Integrated Circuit Industry Investment Fund channels capital toward local interposer capacity. Yangtze Memory Technologies and CXMT represent emerging captive supply for AI accelerator supply chains.
Germany
Automotive design centers in Munich and Stuttgart specify ECC-enabled modules for autonomous vehicle validation pipelines. The EU F-Gas Regulation and REACH chemical documentation extend compliance cycles for flame-retardant PCB substrate imports. Dresden's wafer fab cluster attracts packaging investments for industrial-grade memory reliability.
Graphics DDR SDRAM Market Competitive Landscape
Top-tier vendors anchor advanced packaging and captive wafer supply, while mid-tier module assemblers compete on channel velocity and overclocking ecosystem loyalty. The vendor base stratifies across three tiers: integrated device manufacturers controlling DRAM process nodes, specialized memory module brands, and contract assembly houses serving spot-market demand. Two dominant competitive moves define positioning: backward integration into wafer-level output and subscription-based software tuning for performance differentiation.
Within the integrated device manufacturer tier, Samsung Electronics, SK Hynix, and Micron Technology exemplify divergent geographic and structural positioning. Samsung Electronics represents Korean chaebol-scale captive supply spanning memory die fabrication through module assembly. SK Hynix occupies a position as a dedicated memory specialist with advanced packaging roadmap concentration. Micron Technology anchors American vertical control over Idaho-based DRAM process nodes. These three entities collectively shape foundry allocation decisions and interposer capacity expansion timelines.
| Leading Market Players |
|---|
| Kingston Technology |
| G.Skill |
| Samsung Electronics |
| Crucial |
| ADATA |
| SK Hynix |
| Corsair |
| TeamGroup |
| Micron Technology |
| Others |
Pricing and Supply Chain Analysis
Silicon interposer substrate costs cascade through three pricing tiers from AI accelerator stacks to mid-range discrete GPUs, with Taiwan packaging corridor concentration amplifying margin compression when CoWoS capacity tightens. Foundry allocation decisions between HBM3E and GDDR6X module lines reshape per-gigabyte economics across gaming and datacenter segments.
Pricing Analysis
Margin tightening in mid-range discrete GPU modules reflects silicon interposer cost volatility as CoWoS capacity prioritizes AI accelerator sockets. Three-tier pricing structure across premium HBM3E, standard GDDR6X, and economy GDDR6 levels separates hyperscale deployers from gaming OEMs and channel distributors. Pricing pressure stems from Taiwan packaging concentration forcing foundry allocation trade-offs. Hyperscale AI deployers exhibit lowest price sensitivity through multi-year offtake agreements; Southeast Asian system integrators face highest spot-market exposure.
Supply Chain Analysis
Packaging engineer shortages in Hsinchu and Taichung constrain hybrid bonding equipment deployment timelines for HBM3E stack qualification. Supply concentrates in Taiwan, South Korea, and the United States for advanced interposer capacity and DRAM die fabrication. Raw material dependencies span silicon wafers, ABF substrates, and thermal interface materials. Single-source vulnerability in CoWoS technology creates supply chokepoints for AI training cluster memory stacks. Distribution runs through qualified supplier lists for hyperscale deployers and channel distributors for gaming PC builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graphics DDR SDRAM vendor consolidation accelerates as captive wafer supply and advanced packaging capacity concentrate among integrated device manufacturers, forcing module assemblers toward niche overclocking ecosystems or exit.
For Market Incumbents: Acquire interposer design and thermal-mechanical engineering talent pools in Taiwan and South Korea to defend HBM3E qualification timelines against packaging capacity constraints. Secure captive wafer supply through Idaho or Pyeongtaek DRAM process node investments to reduce foundry allocation vulnerability. Prioritize software-defined memory tuning subscriptions to monetize performance headroom in gaming PC channels. For New Entrants and Emerging Players: The premium-to-economy pricing gap in DDR5 gaming modules offers entry points through XMP 3.0 profile optimization and channel velocity in Vietnam and Indonesia spot markets. Target India's PLI scheme for electronics manufacturing to establish semiconductor assembly and testing capacity outside East Asian packaging corridors. Bundle memory-module warranties with system integrator contracts to reduce qualification overhead for workstation segments. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier module assemblers with established overclocking ecosystem loyalty in European gaming channels. Long-term viability hinges on backward integration into wafer-level output or forward integration into AI accelerator socket partnerships. Monitor JEDEC GDDR7 specification convergence as inflection indicator for foundry partnership reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Adoption | Copper-to-copper interconnects at sub-10 micron pitches displace microbump stacking in Samsung and SK Hynix HBM3E production. |
| Software-Defined Memory Tuning Launch | Subscription-based XMP 3.0 profile optimization creates recurring revenue streams from Corsair and G.Skill overclocking ecosystems. |
| India PLI Scheme Manufacturing Entry | Semiconductor assembly and testing investments in India reduce geographic concentration risk in Taiwan packaging corridors. |
| GDDR7 Specification Partnership | JEDEC standard convergence opens white space for foundry partnerships beyond incumbent CoWoS packaging houses. |
| Low-Voltage Signaling Architecture Development | Sub-1.1V designs meet China's MIIT dual carbon energy-efficiency benchmarks for domestic AI accelerator supply chains. |
Research Methodology
Document review covered JEDEC specification filings, SEC 10-K disclosures from memory vendors, and customs trade data, complemented by interviews with DRAM process node engineers, packaging equipment specialists, hyperscale procurement officers, and gaming PC system integrators. Secondary validation drew from EIA datacenter energy reports, Taiwan National Development Council semiconductor advancement program documents, and EU REACH chemical restriction filings. Bottom-up module shipment estimates triangulated against top-down AI accelerator socket deployment forecasts.
Cross-referencing historical GDDR and HBM adoption curves against panel input from foundry allocation specialists shaped the analytical framework across the analysis window. Segmentation dimensions modeled include memory architecture type, end-user application, packaging technology tier, and regional regulatory cluster. CAGRs derived from die shipment trajectories and per-pin data rate scaling assumptions, with AI training cluster bandwidth requirements and EU F-Gas thermal profile mandates as industry-specific forecast inputs.
Inputs from JEDEC working groups and Taiwan packaging corridor equipment vendors were available through the study window; gaps in China domestic GDDR pilot line yield data introduce uncertainty bands around MIIT dual carbon compliance timelines. Forecasts reflect assumptions on hybrid bonding equipment deployment rates and CoWoS capacity expansion schedules. Material deviation in NVIDIA and AMD accelerator socket qualification timelines or Taiwan seismic risk events warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
ECC Memory Market
Memory Chips
Static RAM Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Europe Dynamic Random Access Memory (DRAM) Market
Memory Chips
Digital RF Memory Market
Memory Chips
Memristor Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Static Random-Access Memory (SRAM) Market
Memory Chips
Memory IC Market
Memory Chips
Ferroelectric RAM Market
Memory Chips
In-Memory Grid Market
Memory Chips
Japan Flash Memory Market
Memory Chips
High Bandwidth Memory Market
Memory Chips
Smartphone RAM Market