
 Ferroelectric RAM Market | 2026-2036
Ferroelectric RAM Market Size, Share, and Industry Trends Forecast 2026-2036
Ferroelectric RAM Market Intelligence
Industrial-grade FRAM specifications are rotating toward higher endurance thresholds and wider temperature tolerances. Texas Instruments Incorporated leverages its embedded memory portfolio to anchor automotive microcontroller supply chains. STMicroelectronics N.V. competes through specialized non-volatile memory integration for smart metering applications. Fujitsu Limited dominates ferroelectric material research with proprietary PZT thin-film processes that sustain manufacturing yields.
Ferroelectric RAM stores data via polarized ferroelectric crystals, typically lead zirconate titanate films under 200 nanometers thick, retaining information without power through remanent polarization states. Embedded RAM segments lead unit shipments by binding memory directly into system-on-chip architectures for IoT endpoints. Standalone RAM occupies premium pricing tiers where discrete non-volatile components serve aerospace and medical device certification requirements. Automotive end-user demand concentrates in battery management systems and event data recorders requiring instant write durability beyond flash memory limits.
Japan's METI enforces semiconductor material standards through JIS certification protocols that govern ferroelectric thin-film reliability testing. The EU REACH framework restricts lead content in electronic components, compelling foundries to qualify alternative hafnium oxide ferroelectric formulations. FDA device regulations in the United States mandate non-volatile memory traceability for implantable medical electronics, creating compliance barriers for unqualified suppliers. Stakeholders must monitor hafnium supply chain concentration and foundry qualification timelines as material transitions accelerate.
Market Dynamics
Automotive ECU manufacturers are demanding non-volatile memory capable of instant write durability beyond flash limits, forcing foundries to requalify ferroelectric material stacks for AEC-Q100 Grade 0 temperature ranges.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases are pushing semiconductor firms toward lead-free ferroelectric formulations, expanding addressable markets for hafnium oxide alternatives.
- Battery management systems:Automotive OEMs require real-time data logging for lithium-ion cell monitoring, creating pull for FRAM's unlimited write endurance in electric vehicle platforms.
- Tokyo-Osaka corridor concentration:Japan's clustered fabrication infrastructure enables rapid prototyping cycles and shared thin-film process development across competing foundries.
Market Restraints
- Hafnium supply concentration:Over 60% of hafnium refining capacity sits in a single geography, exposing FRAM producers to raw material availability shocks and price volatility.
- REACH compliance friction:The EU's lead-content restrictions force simultaneous dual-track qualification of PZT alternatives, extending new product introduction timelines by 18-24 months.
- Flash memory cost curve:NOR flash continues compressing price-per-bit through 3D stacking, limiting FRAM penetration in cost-sensitive consumer IoT endpoints.
Strategic Opportunities
- Medical implant traceability:FDA device regulations mandate non-volatile memory for implantable electronics data logging, creating premium certification barriers for qualified FRAM suppliers.
- India PLI scheme:Production-linked incentives for semiconductor manufacturing are attracting foundry investments that could diversify Asia-Pacific fabrication beyond Japan.
- Smart metering integration:Utility-grade revenue meters require 20-year data retention with instant write capability, opening utility procurement channels previously dominated by EEPROM.
Industry Challenges
- Ferroelectric thin-film deposition expertise:The specialized skill set for PZT and HfO2 sputtering process control is concentrated among aging Japanese engineering cohorts with limited knowledge transfer pipelines.
- JIS certification timelines:METI's reliability testing protocols for ferroelectric memory cells require extended high-temperature bake sequences that compress product launch windows.
- Legacy microcontroller integration:System architects face firmware revalidation costs when substituting FRAM for established flash-based memory hierarchies in certified automotive platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferroelectric RAM Market |
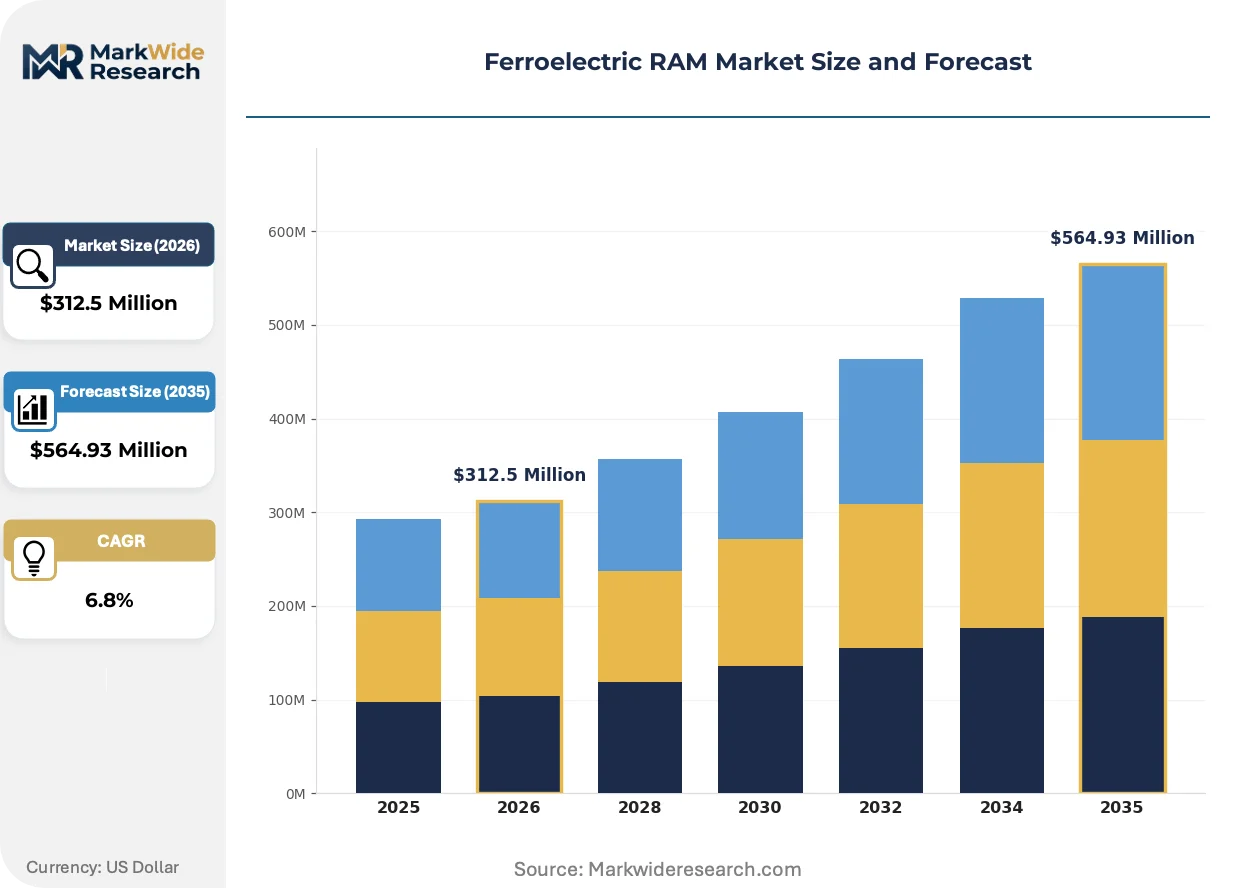
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded RAM, Standalone RAM, Non-volatile RAM, SRAM Technology: Flash Memory, Magnetic RAM, DRAM, PCM End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Application: Internet of Things, Data Centers, Mobile Devices, Wearable Technology |
| Companies Covered | Texas Instruments Incorporated, STMicroelectronics N.V., Infineon Technologies AG, Toshiba Corporation, International Business Machines Corporation, Fujitsu Limited, Samsung Electronics Co. Ltd., Ramtron International Corporation, LAPIS Semiconductor Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferroelectric RAM Market Strategic Shifts & Innovations
Hafnium oxide ferroelectric formulations are displacing legacy PZT thin films across multiple qualification pipelines, while regulatory frameworks accelerate material transitions and procurement patterns favor integrated over discrete memory solutions.
Hafnium oxide ferroelectric layers enable sub-10 nanometer scalability beyond PZT's physical limits, attracting foundry investment from DRAM manufacturers seeking embedded non-volatile options. Automotive MCU architects are adopting HfO2-based FRAM for gateway controllers requiring ASIL-D functional safety certification. This material transition is decomposing the traditional separation between memory and logic process nodes, enabling monolithic integration that reduces board-level component count.
REACH Annex XVII restrictions on lead compounds are compelling foundries to abandon PZT formulations before 2027, with ECHA guidance accelerating substitution timelines. Semiconductor firms are dual-sourcing hafnium oxide precursors to mitigate supply concentration risk. Medical device OEMs face the steepest compliance burden, as FDA 21 CFR Part 820 quality system regulations require revalidation of any material change in implantable electronics.
System-on-chip procurement is displacing standalone FRAM in IoT endpoint designs, with module vendors specifying embedded memory to reduce bill-of-materials complexity. Industrial automation OEMs in Germany are consolidating vendor relationships around microcontroller suppliers offering integrated ferroelectric options. This consolidation is most visible in smart factory sensor networks, where edge node miniaturization priorities override discrete component flexibility.
Ferroelectric RAM Market Segmentation
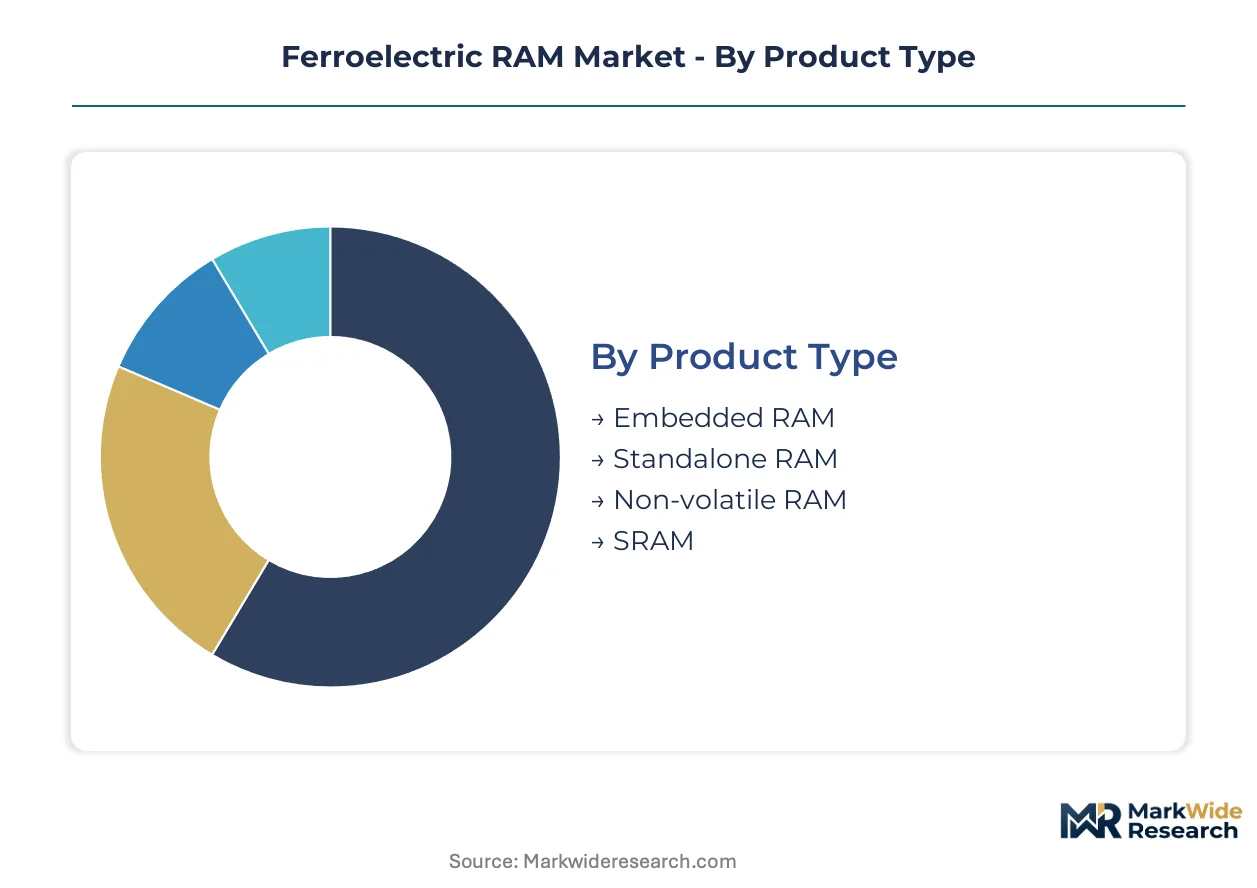
FRAM segmentation reveals divergent vulnerability to flash cost compression and hafnium oxide material transitions. Product architecture and end-use certification requirements determine which segments command sustainable premiums versus facing commoditization pressure.
Product Type:
Standalone RAM faces the most acute substitution threat from 3D-stacked NOR flash, while embedded architectures leverage monolithic integration to defend positioning.
- Embedded RAM:Memory cells integrate directly into system-on-chip designs, eliminating discrete component procurement. Demand concentrates in Japan's IoT module suppliers where Tokyo-Osaka foundries enable rapid prototyping cycles for sensor network endpoints. METI's JIS certification protocols favor integrated architectures by reducing external component qualification burdens.
- Standalone RAM:Discrete ferroelectric components serve aerospace and medical device applications requiring discrete non-volatile elements for traceability compliance. FDA device regulations in the United States mandate standalone memory for implantable electronics data logging, creating certification barriers that buffer flash substitution.
- Non-volatile RAM:Unified memory architectures bridge volatile and non-volatile storage hierarchies.
- SRAM:Volatile cache layers paired with FRAM persistence modules in hybrid configurations.
Embedded RAM retains volume leadership; Standalone RAM holds the steepest expansion curve.
Technology:
Process node scalability separates incumbent formulations from emerging hafnium oxide alternatives.
- Flash Memory:Dominant incumbent technology with established foundry infrastructure and compressed cost curves through 3D stacking. Consumer IoT endpoints in cost-sensitive geographies default to flash despite endurance limitations, constraining FRAM penetration in high-volume, low-margin applications.
- Magnetic RAM:Competing non-volatile architecture leveraging magnetic tunnel junctions for instant write capability. Automotive ECU manufacturers in Germany evaluate MRAM alongside HfO2-FRAM for battery management systems requiring unlimited write endurance.
- DRAM:Volatile memory hierarchy layer requiring FRAM backup for power-loss protection.
- PCM:Phase-change materials offering intermediate endurance between flash and ferroelectric alternatives.
Flash Memory commands installed base dominance; Magnetic RAM exhibits the most aggressive qualification momentum.
End User:
Regulatory stringency varies sharply across verticals, with automotive and medical applications imposing the steepest material traceability requirements.
- Automotive:Battery management systems and event data recorders require instant write durability beyond flash limits. EU F-Gas Regulation and REACH compliance are accelerating lead-free ferroelectric qualification timelines for AEC-Q100 Grade 0 temperature ranges.
- Industrial Automation:Smart factory sensor networks demand 20-year data retention with instant write capability. German OEMs are consolidating procurement around microcontroller suppliers offering integrated ferroelectric options to reduce bill-of-materials complexity.
- Consumer Electronics:Price-sensitive volume applications where flash cost curves limit FRAM adoption.
- Telecommunications:Infrastructure equipment requiring non-volatile configuration storage.
Automotive anchors premium pricing tiers; Industrial Automation is gaining share fastest in utility procurement channels.
Application:
Edge versus cloud architecture decisions determine discrete versus integrated memory procurement patterns.
- Internet of Things:Endpoint miniaturization priorities favor system-on-chip integration over discrete components. Module vendors in Japan's industrial corridors specify embedded FRAM to reduce board-level complexity in smart factory sensor networks.
- Wearable Technology:Medical-grade devices require FDA-compliant non-volatile memory for health data logging. Implantable electronics face the steepest revalidation burdens under 21 CFR Part 820 quality system regulations when material formulations change.
- Data Centers:Persistent memory hierarchies for power-loss protection in server architectures.
- Mobile Devices:Consumer handsets where flash cost compression dominates procurement decisions.
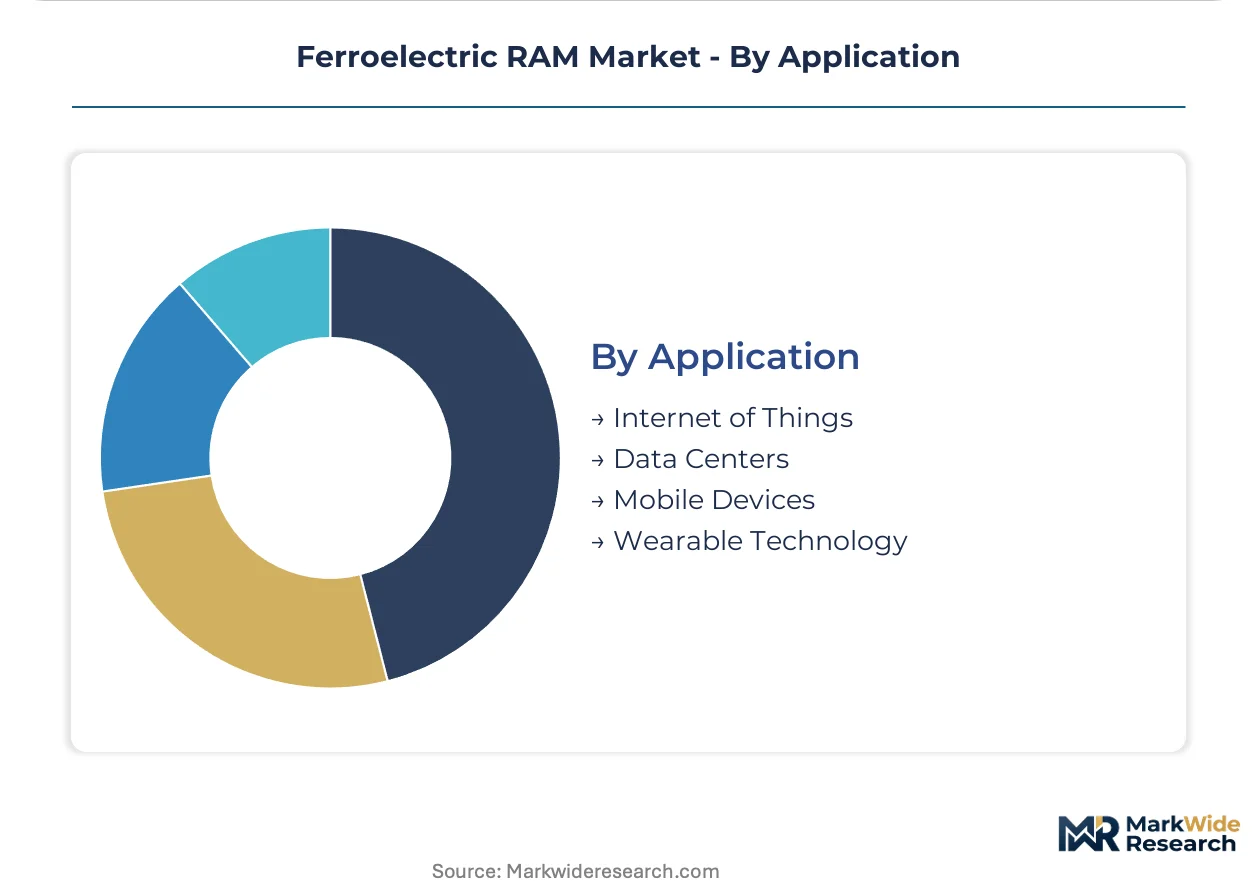
Internet of Things leads unit shipments; Wearable Technology exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for ferroelectric thin-film deposition clusters heavily in Japan's industrial corridors, with METI-administered JIS certification protocols governing material reliability standards. Secondary fabrication investments are emerging in Germany and the United States as REACH compliance deadlines and automotive qualification requirements accelerate geographic diversification.
Japan
Tokyo-Osaka corridor foundries host concentrated PZT and HfO2 thin-film process expertise, serving automotive MCU and IoT module suppliers. METI enforces semiconductor material standards through extended high-temperature bake sequences under JIS certification. Yokohama and Kyoto house competing foundries sharing specialized sputtering equipment for rapid prototyping cycles.
Germany
Automotive ECU manufacturers in Stuttgart and Munich evaluate HfO2-FRAM alongside MRAM for battery management systems requiring ASIL-D certification. ECHA's REACH Annex XVII restrictions on lead compounds are accelerating PZT substitution timelines before 2027. Bavarian industrial automation OEMs are consolidating procurement around microcontroller suppliers offering integrated ferroelectric options.
United States
FDA device regulations mandate non-volatile memory traceability for implantable medical electronics in Massachusetts and Minnesota medical device clusters. The EPA oversees chemical safety in ferroelectric precursor materials under TSCA. Austin and Phoenix host foundry investments targeting automotive AEC-Q100 Grade 0 qualification for event data recorder applications.
South Korea
DRAM manufacturers in Seoul and Suwon are investing in HfO2 ferroelectric layers for embedded non-volatile options at sub-10 nanometer nodes. MFDS regulates medical device components requiring data logging capabilities. Pangyo and Hwaseong industrial parks concentrate foundry development for monolithic memory-logic integration.
India
The PLI scheme for semiconductor manufacturing is attracting foundry investments that could diversify Asia-Pacific fabrication beyond Japan. CDSCO oversees medical device regulations for implantable electronics requiring non-volatile memory. Karnataka and Telangana are emerging as evaluation sites for thin-film process qualification under production-linked incentive frameworks.
Ferroelectric RAM Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with proprietary PZT thin-film specialists defending premium positioning against scale-driven memory conglomerates. The vendor base spans three tiers: integrated device manufacturers with captive fabrication, fabless designers licensing ferroelectric IP, and specialized foundries offering thin-film deposition services. Dominant competitive moves include strategic partnerships for hafnium oxide precursor dual-sourcing and portfolio diversification into automotive-qualified product lines.
Among Japan-based fabricators, Fujitsu Limited and Toshiba Corporation exemplify the integrated archetype with proprietary thin-film process control, while Texas Instruments Incorporated anchors the diversified semiconductor conglomerate tier with embedded memory portfolio breadth. STMicroelectronics N.V. occupies a position bridging European automotive qualification requirements with foundry partnerships for ferroelectric integration.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| Infineon Technologies AG |
| Toshiba Corporation |
| International Business Machines Corporation |
| Fujitsu Limited |
| Samsung Electronics Co. Ltd. |
| Ramtron International Corporation |
| LAPIS Semiconductor Co. Ltd. |
| Others |
Cost & Logistics Intelligence
REACH Annex XVII restrictions on lead compounds gate both foundry qualification timelines and tiered pricing structures across automotive and medical segments. EU F-Gas Regulation compliance costs compress margins on legacy PZT formulations while opening premium capture for hafnium oxide alternatives that meet AEC-Q100 Grade 0 requirements.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across the ferroelectric RAM market. Certification grade separates automotive-qualified HfO2-FRAM from industrial-grade PZT alternatives, with FDA device regulations for implantable electronics creating the steepest premium tier for medical traceability compliance. Cost compression in consumer IoT endpoints runs through flash memory substitution pressure, while battery management system procurement shows the least price sensitivity due to unlimited write endurance requirements.
Supply Chain Analysis
Hafnium refining concentration in a single geography exposes FRAM producers to raw material availability shocks and price volatility. The supply chain draws from Japan for thin-film deposition equipment, South Korea for DRAM-compatible process nodes, and Germany for automotive qualification testing. Single-source vulnerability sits with hafnium oxide precursor supply. Distribution runs through direct foundry relationships with automotive ECU manufacturers and medical device OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ferroelectric RAM market is entering a cyclical recovery phase driven by automotive electrification mandates accelerating battery management system procurement cycles.
For Market Incumbents: Consolidate thin-film deposition expertise through captive engineering retention programs targeting Japan's aging specialist cohorts. Secure dual-source hafnium oxide precursor agreements to mitigate supply concentration risk. Anchor automotive qualification pipelines with AEC-Q100 Grade 0 certification investments before REACH Annex XVII deadlines force material transitions. For New Entrants and Emerging Players: Anchor in India's PLI scheme evaluation sites for thin-film process qualification under production-linked incentive frameworks. Target utility-grade smart metering procurement channels in Germany where 20-year data retention requirements displace EEPROM incumbents. Pursue licensing partnerships with Tokyo-Osaga corridor foundries for rapid prototyping access rather than greenfield fabrication investment. For Investors and Strategic Acquirers: REACH Annex XVII reshapes the acquisition landscape by devaluing PZT-dependent specialists and premium-capturing hafnium oxide qualification pipelines. Five-to-ten year viability favors foundries with embedded memory-logic integration capabilities at sub-10 nanometer nodes. Target acquisition archetype: fabless designers with automotive MCU socket relationships. Monitor hafnium supply contract renegotiation cycles as inflection indicators for input cost pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Hafnium Oxide Precursor Agreement | Mitigates supply concentration risk from single-geography refining dominance. |
| AEC-Q100 Grade 0 Qualification Investment | Opens automotive battery management system procurement above flash memory limits. |
| Embedded Memory-Logic Integration Partnership | Enables monolithic system-on-chip architectures for IoT endpoint miniaturization. |
| FDA 21 CFR Part 820 Quality System Certification | Creates premium barriers for implantable medical electronics data logging. |
| Tokyo-Osaka Corridor Foundry Alliance | Accelerates thin-film process development through shared sputtering equipment access. |
Research Approach
Operator-level perspectives from foundry process engineers, automotive ECU procurement managers, medical device quality assurance leads, and thin-film materials scientists anchored the qualitative base. Primary interviews triangulated with secondary validation from METI JIS certification protocols, ECHA REACH guidance documents, FDA 21 CFR Part 820 regulations, and AEC-Q100 automotive qualification standards. SEC filings from semiconductor conglomerates and customs data on hafnium oxide precursor trade flows provided quantitative anchors. Bottom-up unit shipment estimates across embedded and standalone RAM segments reconciled with top-down market value approaches.
Sensitivity analysis framed the forecast envelope across material transition scenarios and automotive electrification adoption curves. Segmentation dimensions modeled include product architecture, process node scalability, end-user certification requirements, and geographic regulatory clusters. CAGRs derived from historical foundry capacity expansion rates and projected qualification timeline compression. Industry-specific inputs incorporated JIS reliability testing protocol durations and REACH Annex XVII substitution deadlines.
Material uncertainties — hafnium supply disruptions, ECHA guidance acceleration, FDA revalidation requirements for implantable electronics — sit outside the modeled envelope. Forecasts reflect assumptions around foundry qualification timelines and automotive platform certification cycles. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement intensity and India PLI scheme disbursement schedules evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Static RAM Market
Memory Chips
Contactless Memory Market
Memory Chips
Second-Gen Magneto Resistive RAM (STT MRAM) Market
Memory Chips
Memory IC Market
Memory Chips
Japan DRAM Market
Memory Chips
Next Generation Memory Market
Memory Chips
United States Semiconductor Memory Market
Memory Chips
MRAM Market
Memory Chips
ECC Memory Market
Memory Chips
APAC Dynamic Random Access Memory (DRAM) Market
Memory Chips
Mask PROM and EPROM Market
Memory Chips
Graphics DDR SDRAM Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
GDDR6 Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Global Standalone Memory Market