
 ECC Memory Market | 2026-2036
ECC Memory Market Size, Share, and Industry Trends Forecast 2026-2036
ECC Memory Market Analysis
Module bundling with registered DIMMs and PMIC components is expanding buyer choice toward pre-validated server configurations rather than discrete component sourcing. Samsung Electronics Co. Ltd. leverages captive wafer capacity to anchor supply for high-density DDR5 ECC modules. Micron Technology Inc. competes through advanced process nodes in 1β DRAM manufacturing for data center customers. SK Hynix Inc. differentiates via HBM3E co-development pipelines that feed into next-generation server memory ecosystems.
Error-correcting code memory incorporates redundant parity bits and Hamming code algorithms to detect and correct single-bit errors in real-time, with DDR5 implementations adding on-die ECC for additional data integrity at sub-10nm process nodes. DDR modules command the largest revenue pool in data center refresh cycles, while SDRAM retains entrenched positions in legacy industrial control systems where long qualification timelines slow migration. Server applications absorb the majority of high-margin module shipments, whereas networking equipment demands are shifting toward low-power ECC options for edge deployments.
Intel Corporation's platform validation requirements and JEDEC standards govern module interoperability across x86 server architectures, while the EU F-Gas Regulation and REACH compliance shape chemical and thermal management material selections for European deployments. China's GB standards and MIIT localization mandates require dual sourcing for memory controllers in domestic server builds. Stakeholders must monitor JEDEC roadmap convergence with CXL memory pooling standards to determine timing for architectural transitions away from traditional DIMM form factors.
Market Dynamics
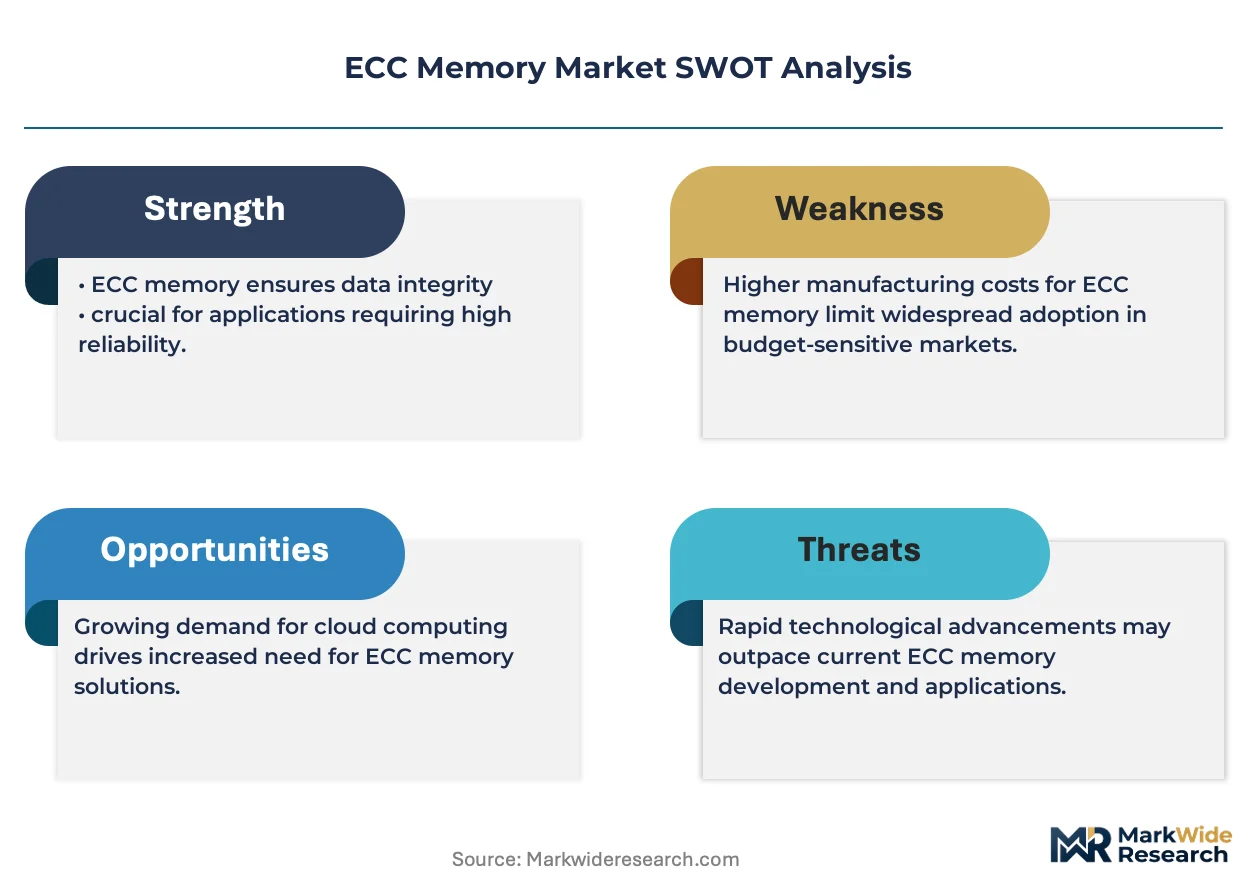
JEDEC's DDR5 standardization timeline and on-die ECC mandates are compressing module qualification cycles while hyperscale operators accelerate procurement of registered DIMM configurations for AI training infrastructure.
Growth Catalysts
- AI Training Cluster Deployment:Hyperscale data center operators in the United States and China are expanding registered DIMM procurement to support large language model training workloads requiring terabit-scale memory bandwidth.
- REACH and F-Gas Compliance:The EU F-Gas Regulation and REACH chemical directives are mandating thermal interface material substitutions that favor ECC modules with integrated power management and enhanced thermal monitoring.
- Automotive Semiconductor Investment:Germany's automotive OEMs and tier-one suppliers are qualifying DDR5 ECC modules for autonomous driving compute platforms, creating new demand outside traditional server verticals.
Market Restraints
- Captive Wafer Concentration:Three Korean and Taiwanese foundry groups control the majority of DRAM wafer supply, creating vulnerability to geographic concentration in East Asian manufacturing corridors.
- MIIT Localization Mandates:China's Ministry of Industry and Information Technology requires dual sourcing for memory controllers in domestic server builds, extending qualification timelines for foreign module suppliers.
- SDRAM Legacy Entrenchment:Industrial control systems with decade-long qualification cycles retain SDRAM architectures, slowing DDR5 ECC penetration in factory automation and process control applications.
Strategic Opportunities
- CXL Memory Pooling Convergence:The Compute Express Link protocol is converging with JEDEC DDR5 roadmaps, enabling disaggregated memory architectures that transcend traditional DIMM form factors.
- Edge Networking Low-Power Demand:5G base station and edge computing deployments in India and Southeast Asia are creating specifications for reduced-voltage ECC modules with sub-1.1V operating envelopes.
- EU Green Deal Incentives:The European Union's sustainable semiconductor funding mechanisms are subsidizing energy-efficient memory production, favoring advanced node DRAM with integrated ECC and power management.
Industry Challenges
- JEDEC Qualification Bottlenecks:Platform validation requirements from Intel and AMD are extending module certification timelines to 18-24 months, compressing product windows before next-generation standards emerge.
- PMIC Integration Complexity:Power management IC integration with registered DIMMs is multiplying firmware validation surfaces and creating interoperability failures across server motherboard implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECC Memory Market |
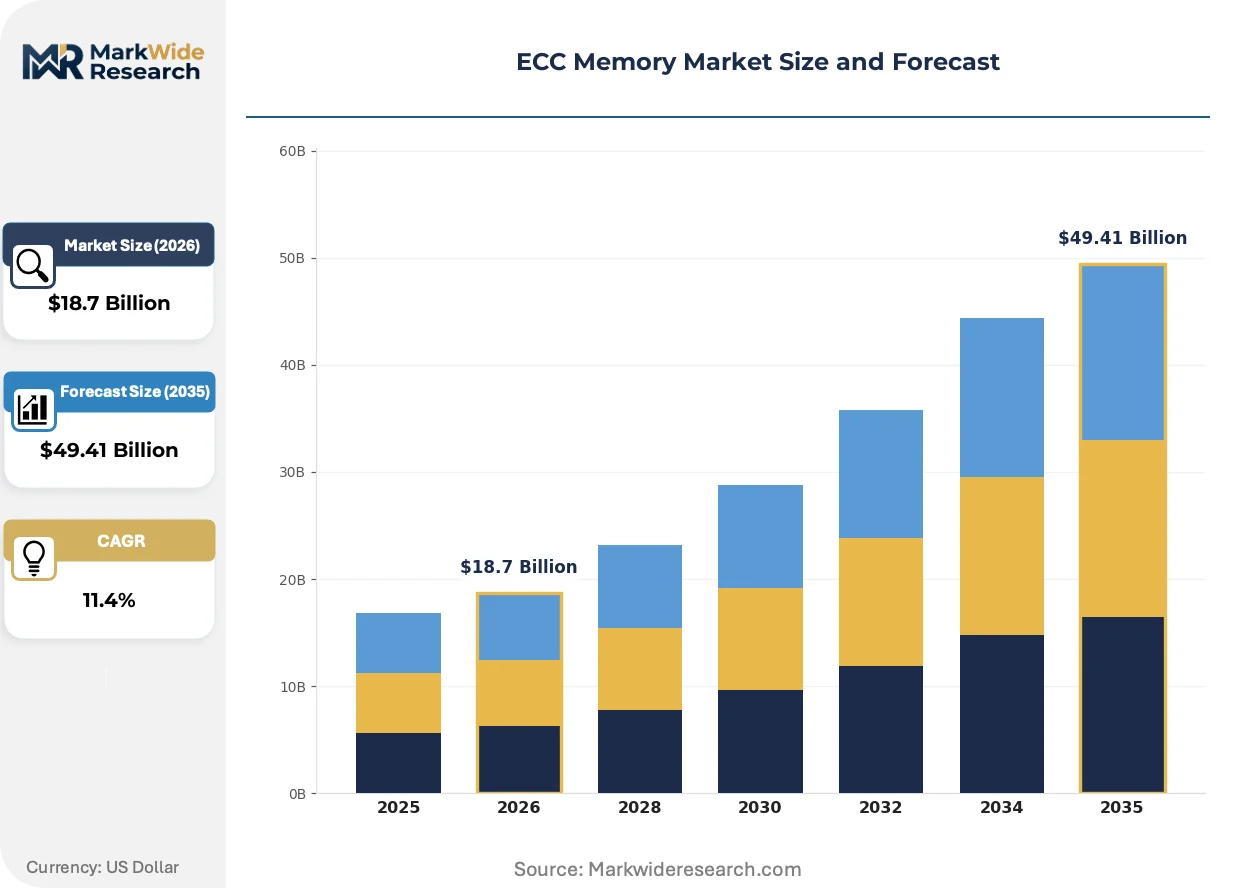
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DDR, SDRAM, DRAM, SRAM End User: Data Centers, Cloud Providers, Enterprises, Telecommunications Application: Servers, Workstations, Networking Equipment, Industrial Systems Technology: Memory Chips, Modules, Storage Solutions, Memory Controllers |
| Companies Covered | Kingston Technology Corporation, Hewlett Packard Enterprise Company, Micron Technology Inc., Lenovo Group Limited, Dell Inc., Samsung Electronics Co. Ltd., Intel Corporation, Other World Computing (OWC), SK Hynix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECC Memory Market Emerging Trajectories
Memory architecture is fragmenting across multiple concurrent transitions: on-die ECC implementation, CXL protocol adoption, and power management integration at the module level.
DDR5 on-die ECC is decentralizing error correction responsibility from system-level memory controllers to individual DRAM dies, reducing single-point-of-failure exposure in high-density configurations. Hyperscale operators in the United States are adopting these modules for training clusters exceeding 10,000 GPUs per deployment. This architectural shift is compressing the market for external ECC chipsets while elevating die-level yield requirements.
The EU F-Gas Regulation is banning hydrofluorocarbon-based thermal interface materials from 2027, forcing module suppliers to qualify graphite and phase-change alternatives for high-wattage registered DIMMs. German and French server OEMs are accelerating validation timelines to lock component approvals before the prohibition takes effect. European deployments are now specifying thermal materials with documented carbon footprint disclosures under the Corporate Sustainability Reporting Directive.
Buyer concentration among hyperscale operators is consolidating procurement leverage into three to four global cloud platforms, displacing traditional distributor-led channel models for high-density server memory. Direct vendor-OEM engineering relationships are replacing specification-driven spot purchasing, with contract terms now spanning 24-36 month supply commitments. This behavioral shift is most visible in United States and China data center buildouts, where single buyers represent 40-60% of annual module demand for specific density tiers.
ECC Memory Market Segmentation
Segmentation in the ECC memory market reveals how technical specifications, deployment environments, and supply chain configurations create distinct commercial battlegrounds. Buyers prioritize different performance attributes based on workload intensity, thermal constraints, and platform validation requirements.
Product Type:
Cost tier separates commodity buyers from those requiring specialized reliability specifications.
- DDR:Double data rate synchronous dynamic random-access memory operates at higher clock speeds with lower voltage requirements than legacy alternatives. Data center operators in the United States and China are standardizing on DDR5 registered DIMM configurations for AI training clusters where bandwidth density determines training throughput.
- SDRAM:Synchronous DRAM synchronizes memory operations with the system bus clock, enabling predictable latency for real-time control systems. Industrial automation deployments in Germany retain SDRAM architectures due to decade-long qualification cycles that delay DDR5 migration in factory floor equipment.
- DRAM:Dynamic random-access memory stores each bit in a separate capacitor-transistor pair requiring periodic refresh cycles.
- SRAM:Static random-access memory uses bistable latching circuitry to retain data without refresh, trading density for speed in cache hierarchies.
DDR leads volumes today; DDR5 implementations are gaining share fastest.
End User:
Volume scale and procurement concentration distinguish hyperscale operators from fragmented enterprise buyers.
- Data Centers:Hyperscale facilities housing thousands of servers demand registered DIMM modules with integrated power management and thermal monitoring. United States-based cloud operators now represent 40-60% of annual demand for high-density DDR5 ECC configurations, consolidating procurement leverage into direct vendor relationships.
- Cloud Providers:Public cloud platforms require memory subsystems validated across heterogeneous server generations to minimize fleet fragmentation. Chinese cloud operators face MIIT localization mandates requiring dual-sourced memory controllers, extending qualification timelines compared to United States counterparts.
- Enterprises:Corporate IT departments purchase through distributor channels with shorter contract horizons and higher price sensitivity.
- Telecommunications:5G infrastructure operators in India and Southeast Asia are specifying reduced-voltage ECC modules for edge deployments.
Data centers lead volumes today; telecommunications is expanding most quickly.
Application:
Margin structure and qualification rigor separate mission-critical server deployments from cost-optimized networking equipment.
- Servers:Compute-intensive platforms absorb the majority of high-margin registered DIMM shipments, with error-correcting capabilities mandatory for financial transaction processing and scientific computing. German automotive OEMs are qualifying DDR5 ECC modules for autonomous driving compute platforms, extending server-grade reliability requirements into vehicle architectures.
- Workstations:Professional visualization and engineering simulation workstations demand unbuffered ECC modules balancing capacity with latency sensitivity.
- Networking Equipment:Edge routers and switches are shifting toward low-power ECC options as 5G base station deployments proliferate.
- Industrial Systems:Process control applications with extended qualification timelines retain legacy SDRAM where long-term supply continuity outweighs performance upgrades.
Servers lead volumes today; networking equipment shows the steepest expansion trajectory.
Technology:
Supply concentration and vertical integration depth differentiate component suppliers from module integrators.
- Memory Chips:DRAM die manufacturing concentrates among Korean and Taiwanese foundry groups controlling wafer supply, with on-die ECC implementation becoming mandatory at sub-10nm process nodes under JEDEC DDR5 standards.
- Modules:Registered DIMM configurations bundle DRAM dies with power management ICs and thermal interface materials, with EU F-Gas Regulation banning hydrofluorocarbon-based thermal materials from 2027.
- Storage Solutions:Persistent memory architectures bridging DRAM and NAND flash are gaining traction in database acceleration.
- Memory Controllers:Controller logic determines platform compatibility across Intel and AMD server architectures, with China's MIIT mandating dual sourcing for domestic builds.
Memory chips lead volumes today; memory controllers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECC memory technology originated in United States defense and aerospace computing during the 1970s before commercializing through Silicon Valley semiconductor development. The technology spread to East Asian manufacturing centers in the 1990s as DRAM fabrication consolidated in Korea and Taiwan. Today, demand concentrates where hyperscale data center buildouts and automotive semiconductor investments intersect.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center corridors are procuring registered DIMM configurations for AI training clusters exceeding 10,000 GPUs. The Department of Commerce export controls on advanced semiconductor manufacturing equipment are reshaping supply chain strategies for domestic server OEMs. Intel Corporation's platform validation requirements in Santa Clara govern module interoperability across x86 architectures deployed nationwide.
China
Domestic cloud infrastructure buildouts in Beijing, Shanghai, and Shenzhen are driving demand for high-density DDR5 ECC modules. MIIT localization mandates require dual sourcing for memory controllers in domestic server builds, extending qualification timelines for foreign suppliers. Yangtze Memory Technologies and other domestic DRAM projects in Wuhan and Hefei are advancing captive wafer capacity for local module integrators.
Germany
Automotive OEMs in Stuttgart and Munich are qualifying DDR5 ECC modules for autonomous driving compute platforms. The EU F-Gas Regulation and REACH chemical directives are mandating thermal interface material substitutions for high-wattage registered DIMMs. Bavarian server OEMs are accelerating validation timelines to lock component approvals before the 2027 prohibition on hydrofluorocarbon-based materials takes effect.
South Korea
Captive DRAM wafer fabrication in Giheung and Pyeongtaek anchors global supply for high-density ECC modules. The Korea Fair Trade Commission monitors concentration among the three dominant foundry groups controlling majority wafer output. Seoul-based memory suppliers are co-developing HBM3E pipelines that feed into next-generation server memory ecosystems for hyperscale customers.
India
5G base station deployments in Mumbai, Bangalore, and Hyderabad are creating specifications for reduced-voltage ECC modules with sub-1.1V operating envelopes. The Production Linked Incentive scheme for electronics manufacturing is attracting module assembly investments from global suppliers. TRAI spectrum allocations are accelerating edge computing infrastructure buildouts requiring low-power memory options.
ECC Memory Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and captive wafer access. The market structure concentrates around Korean and Taiwanese foundry groups controlling DRAM die supply, with module integrators competing on validation speed and thermal management differentiation. Three strategic archetypes dominate: captive wafer suppliers with backward integration into module production, fabless module integrators dependent on external die supply, and platform OEMs bundling memory with server systems. Competitive moves center on JEDEC qualification acceleration and PMIC integration partnerships to compress certification timelines.
Within the captive wafer supplier archetype, Samsung Electronics Co. Ltd. and SK Hynix Inc. occupy positions anchored by East Asian fabrication capacity. Micron Technology Inc. represents the integrated American competitor with advanced process node development. Among platform OEMs, Dell Inc. and Hewlett Packard Enterprise Company exemplify server system vendors bundling validated memory configurations with compute hardware. Kingston Technology Corporation sits within the specialized module integrator tier, serving distributor channels and aftermarket replacement demand. These named entities illustrate how geographic origin and corporate structure map to competitive positioning without requiring specific product or financial disclosures.
| Leading Market Players |
|---|
| Kingston Technology Corporation |
| Hewlett Packard Enterprise Company |
| Micron Technology Inc. |
| Lenovo Group Limited |
| Dell Inc. |
| Samsung Electronics Co. Ltd. |
| Intel Corporation |
| Other World Computing (OWC) |
| SK Hynix Inc. |
| Others |
Supply Flow & Price Mechanics
DRAM wafer costs cascade through three pricing tiers as Korean and Taiwanese foundry groups allocate captive capacity between hyperscale direct contracts and distributor spot markets. JEDEC qualification timelines and PMIC integration complexity amplify cost-to-serve differentials between pre-validated server configurations and discrete component sourcing.
Pricing Analysis
Contract-based long-term offtake dominates procurement between hyperscale operators and captive wafer suppliers, compressing spot-market liquidity for standard-density modules. Price differentiation rests on JEDEC validation status and thermal management certification grade, with F-Gas-compliant modules commanding premiums over legacy configurations. Cost compression in mid-density tiers is intensifying because Chinese MIIT localization mandates are fragmenting controller sourcing economics. Hyperscale operators in the United States exhibit lowest price sensitivity due to training-cluster throughput requirements, while enterprise distributor channels remain most exposed to spot-price volatility.
Supply Chain Analysis
Engineering talent scarcity in Giheung and Pyeongtaek is tightening process node advancement timelines for sub-10nm DRAM fabrication. Supply concentrates in South Korea, Taiwan, and the United States, with raw silicon wafer and advanced photoresist dependencies drawing from Japanese and German chemical suppliers. Single-source vulnerability in EUV lithography equipment exposes capacity expansion schedules to export control restrictions. Distribution runs through direct vendor-OEM engineering relationships for hyperscale procurement, while distributor channels serve fragmented enterprise replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between United States hyperscale direct procurement and Chinese domestic qualification timelines creates margin capture opportunities for suppliers with dual-hemisphere validation capabilities. The EU F-Gas Regulation timeline differential against REACH compliance deadlines in Germany offers 18-month positioning windows for thermal material substitutions.
For Market Incumbents: Deepen captive wafer allocation to registered DIMM configurations with integrated PMICs, defending against fabless module integrators gaining share through JEDEC qualification acceleration. Prioritize backward integration into thermal interface material production to lock component approvals before the 2027 hydrofluorocarbon prohibition. Capacity addition in United States packaging corridors hedges against East Asian logistics chokepoint exposure. For New Entrants and Emerging Players: The 40% price-point gap between automotive-qualified DDR5 modules and standard server configurations offers entry into German autonomous driving compute platforms. Target telecommunications edge deployments in India requiring sub-1.1V reduced-voltage specifications, where incumbent validation backlogs create procurement delays. A TRAI spectrum allocation-aligned go-to-market angle captures 5G base station refresh cycles ahead of hyperscale procurement consolidation. For Investors and Strategic Acquirers: Roll-up economics work for specialized module integrators because JEDEC qualification bottlenecks are extending certification timelines to 24 months, creating scarcity value for validated component libraries. The 5-to-10-year viability window favors acquisition of fabless integrators with automotive thermal management expertise and existing REACH documentation. The signal to watch is CXL protocol adoption velocity as an inflection indicator for architectural transition away from traditional DIMM form factors.| Strategic Initiative | Industry Significance |
|---|---|
| JEDEC Qualification Acceleration | Compresses 24-month certification timelines to capture hyperscale procurement windows before DDR6 emergence. |
| PMIC Integration Partnership | Reduces firmware validation surfaces across Intel and AMD platform implementations. |
| Thermal Material Substitution | Locks EU F-Gas Regulation compliance ahead of 2027 prohibition on hydrofluorocarbon-based interfaces. |
| CXL Memory Pooling Investment | Positions for architectural transition beyond traditional DIMM form factors in hyperscale deployments. |
| Automotive Qualification Pathway | Extends server-grade reliability requirements into German autonomous driving compute platforms. |
Methodological Framework
Bottom-up data center modeling reconciled against top-down DRAM wafer supply tracking forms the analytical core. Primary interviews with module validation engineers, hyperscale procurement directors, thermal materials specialists, and automotive platform architects combined with secondary validation against JEDEC standards documentation, SEC semiconductor filings, EU regulatory registers, and MIIT localization directives. Triangulation between demand-side deployment schedules and supply-side capacity announcements anchors volume estimates.
Input-output matrices map end-use application intensity across server, networking, and automotive segments against process node availability and PMIC integration yields. Segmentation dimensions modeled include product type, end user concentration, application rigor, and technology integration depth. CAGRs derive from deployment trajectory analysis across the projection horizon, with inputs from Intel platform validation timelines and Chinese cloud infrastructure buildout disclosures.
Caveats apply where JEDEC roadmap convergence with CXL standards, export control expansion on advanced manufacturing equipment, or automotive qualification timeline compression could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Nano RAM Market
Memory Chips
Non-Volatile Memory (NVM) Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Hybrid Memory Cube Market
Memory Chips
In-Memory Grid Market
Memory Chips
LPDDR5 DRAM Market
Memory Chips
Memory Module Market
Memory Chips
Asia Pacific Semiconductor Memory Market
Memory Chips
Automotive DRAM Market
Memory Chips
Contactless Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Smartphone Memory Chip Market
Memory Chips
GDDR6 Market
Memory Chips
MRAM Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market