
 Fly Trap Market | 2026-2036
Fly Trap Market Size, Share, and Industry Trends Forecast 2026-2036
Fly Trap Market Insights
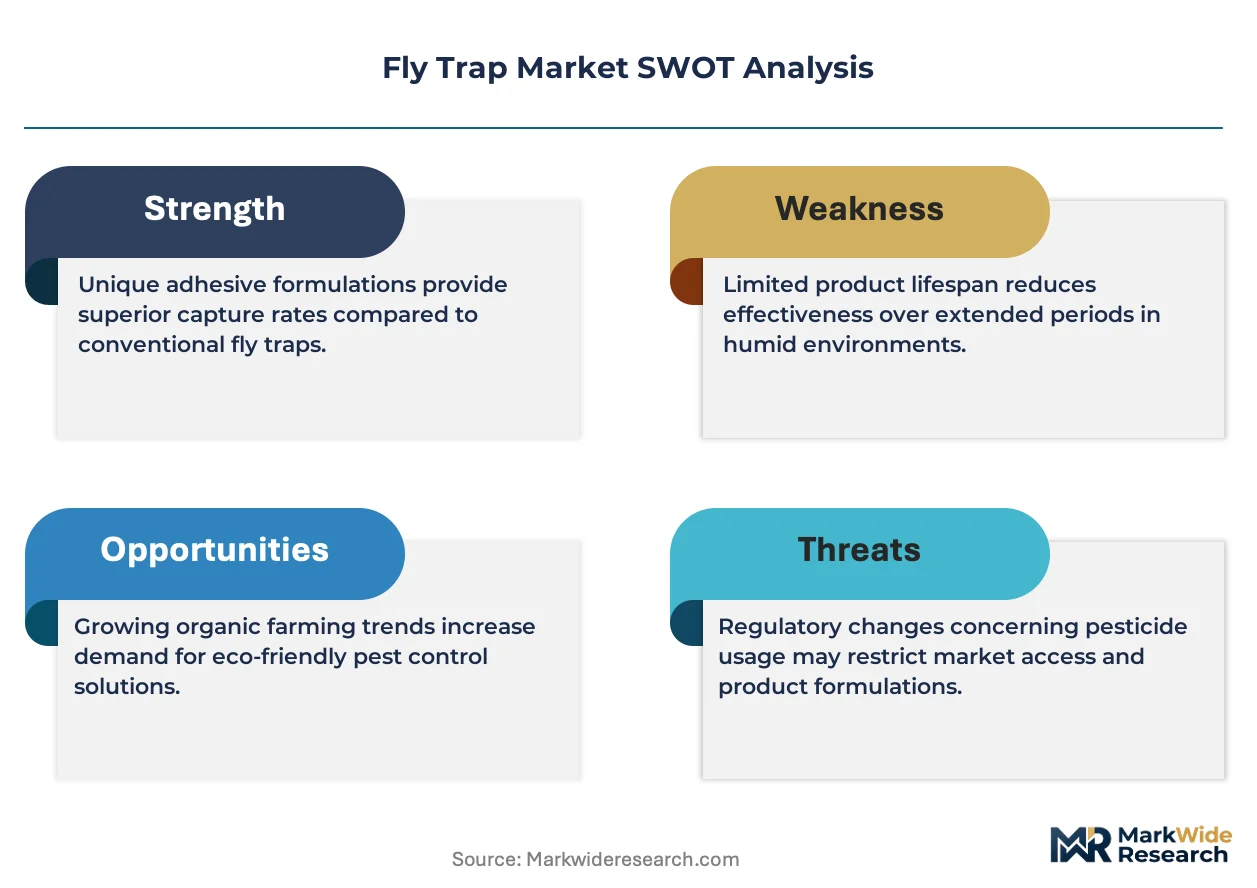
Biodegradable adhesive formulations is pivoting away from petroleum-based glues in sticky trap manufacturing, cutting raw material costs and aligning with sustainability mandates. AP&G Co., Inc. (Catchmaster) leverages its captive supply of natural resin compounds to secure pricing advantages across North American retail channels. Koppert Biological Systems anchors its position through biological pest management integration, bundling traps with beneficial insect programs. Rentokil Initial dominates commercial service contracts, embedding trap hardware into recurring facility management relationships.
Fly traps are mechanical or electromechanical devices designed to capture or kill dipteran pests, typically employing adhesive surfaces, ultraviolet light attraction, or electric grids operating at 2,000–4,000 volts, with housing constructed from UV-stabilized polypropylene or powder-coated aluminum for outdoor durability. These systems serve agricultural, commercial, and residential sectors by reducing pest populations without broadcast pesticide application. Electric traps capture the largest margin pool in commercial settings where 24-hour operation justifies higher capital outlay, while baited traps represent the fastest-growing category as pheromone and food-based attractant formulations improve species specificity. Hybrid technology segments gain traction in agricultural fields where farmers combine mechanical trapping with remote monitoring sensors to optimize deployment timing.
The EPA regulates active ingredient claims in baited traps through FIFRA registration requirements, while the EU Green Deal and REACH restrict persistent organic compounds in adhesive matrices, forcing reformulation across export-bound product lines. The USDA's National Organic Program shapes demand in agricultural fields by certifying trap systems for organic crop production, creating a dual-track market with premium pricing for compliant hardware. Stakeholders must monitor evolving state-level restrictions on neonicotinoid attractants and decide whether to maintain parallel product portfolios or accelerate biological attractant R&D to unify offerings.
Market Dynamics
Integrated pest management mandates in Germany are compressing procurement cycles for non-chemical fly control systems, forcing facility managers to replace legacy pesticide protocols with electromechanical trapping hardware ahead of audit schedules.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants in cold storage facilities accelerates trap deployment as chemical fumigation alternatives face operational restrictions.
- Commercial food processing hygiene audits:Third-party certification bodies now mandate documented pest control logs, embedding trap systems into compliance infrastructure.
- Biological attractant formulations:Pheromone-based species-specific lures reduce bycatch concerns in organic agriculture, opening certified crop production segments.
Market Restraints
- Natural resin supply concentration:Captive sourcing of biodegradable adhesive feedstocks limits formulation flexibility for mid-tier manufacturers lacking backward integration into forestry operations.
- UV-stabilized polypropylene cost volatility:Petrochemical input fluctuations compress hardware margins on electromelectric grid housings designed for outdoor durability.
- Electric grid voltage standardization gaps:Inconsistent 2,000–4,000 volt operating specifications across national electrical codes complicate cross-border product certification.
Strategic Opportunities
- Remote sensor convergence:IoT-enabled trap monitoring systems allow agricultural operators to optimize deployment timing through real-time catch data analytics.
- USDA National Organic Program certification:Premium hardware positioning for compliant systems creates dual-track pricing in agricultural verticals.
- Facility management service bundling:Embedded trap hardware within recurring commercial contracts locks in multi-year replacement cycles.
Industry Challenges
- Neonicotinoid attractant phase-outs:State-level restrictions force parallel product portfolio maintenance or accelerated biological R&D timelines.
- REACH adhesive matrix reformulation:Persistent organic compound restrictions demand export-bound product line redesigns with compressed compliance windows.
- Electromechanical technician scarcity:Grid maintenance and UV lamp replacement protocols require specialized service capabilities not uniformly available in rural agricultural regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fly Trap Market |
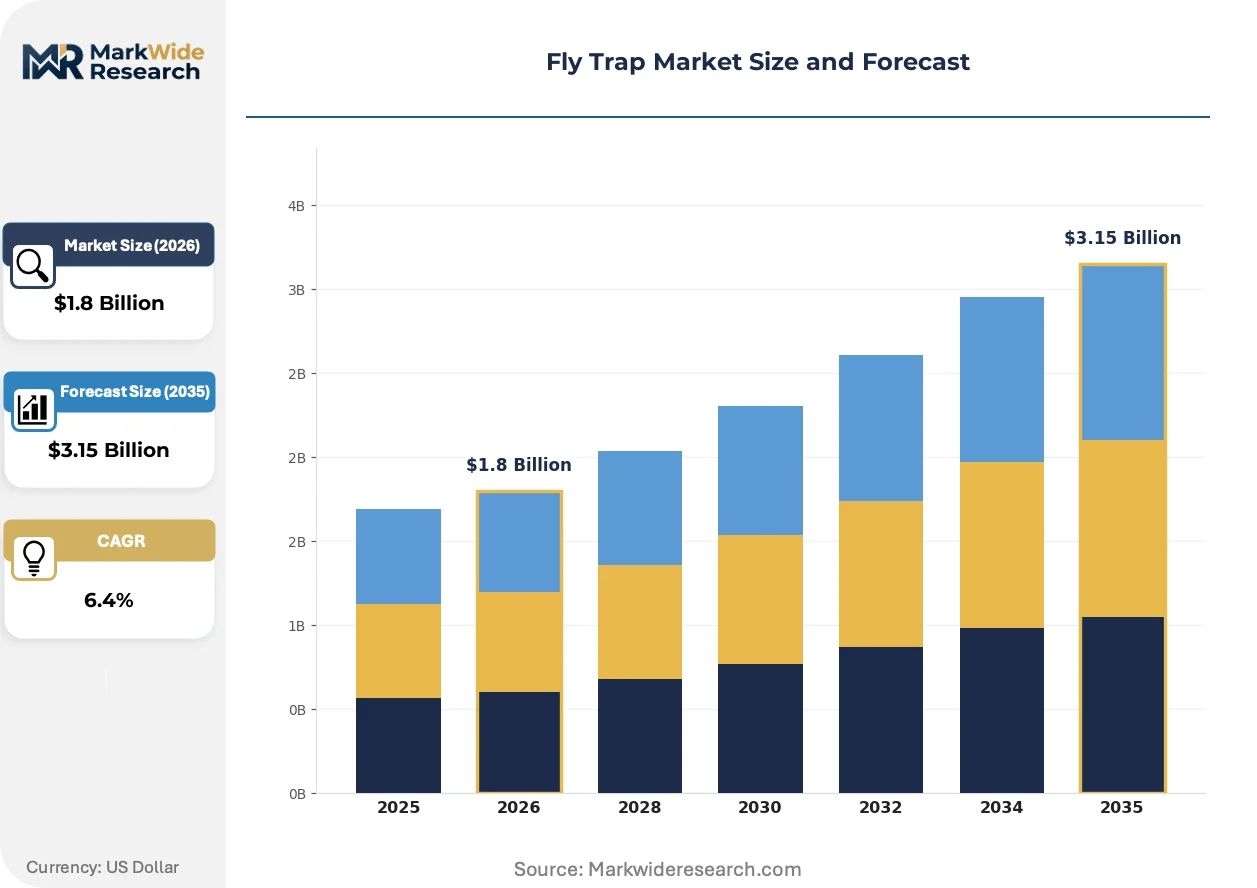
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sticky Traps, Electric Traps, Baited Traps, Ultrasonic Traps Application: Agricultural Fields, Residential Areas, Commercial Spaces, Industrial Sites Material: Plastic, Metal, Paper, Wood Technology: Active Ingredient Based, Mechanical, Electronic, Hybrid |
| Companies Covered | AP&G Co., Inc. (Catchmaster), Koppert Biological Systems, Woodstream Corporation, Rentokil Initial, DynaTrap, Havahart, Flowtron Outdoor Products, Bell Laboratories, Sterling International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fly Trap Market Trends and Innovations
Hybrid trapping architectures are compressing the boundary between mechanical capture and digital monitoring, embedding sensor networks directly into adhesive and electric grid systems to transform passive devices into active data collection nodes.
UV-LED attraction modules are decentralizing trap deployment economics across commercial food processing facilities. These solid-state replacements for mercury vapor lamps reduce energy draw and extend operational lifespans. Facility managers in Germany and the Netherlands are retrofitting existing housing with LED arrays to avoid full hardware replacement. The technology is decentralizing capital planning by enabling incremental upgrade paths rather than consolidated equipment refresh cycles.
REACH restrictions on persistent organic compounds in adhesive matrices are forcing reformulation of export-bound sticky trap product lines. Manufacturers must substitute petroleum-based glues with natural resin compounds to maintain EU market access. Agricultural trap suppliers face the steepest compliance burden, as organic certification requirements already prohibit synthetic adhesives and create overlapping regulatory pressure.
Service contract bundling is compressing hardware procurement autonomy for commercial facility managers. Pest control operators now specify trap brands within integrated facility management agreements, displacing direct manufacturer relationships. This pattern concentrates most visibly in German food processing clusters, where hygiene audit documentation requirements favor single-source service accountability over multi-vendor equipment sourcing.
Fly Trap Market Segmentation
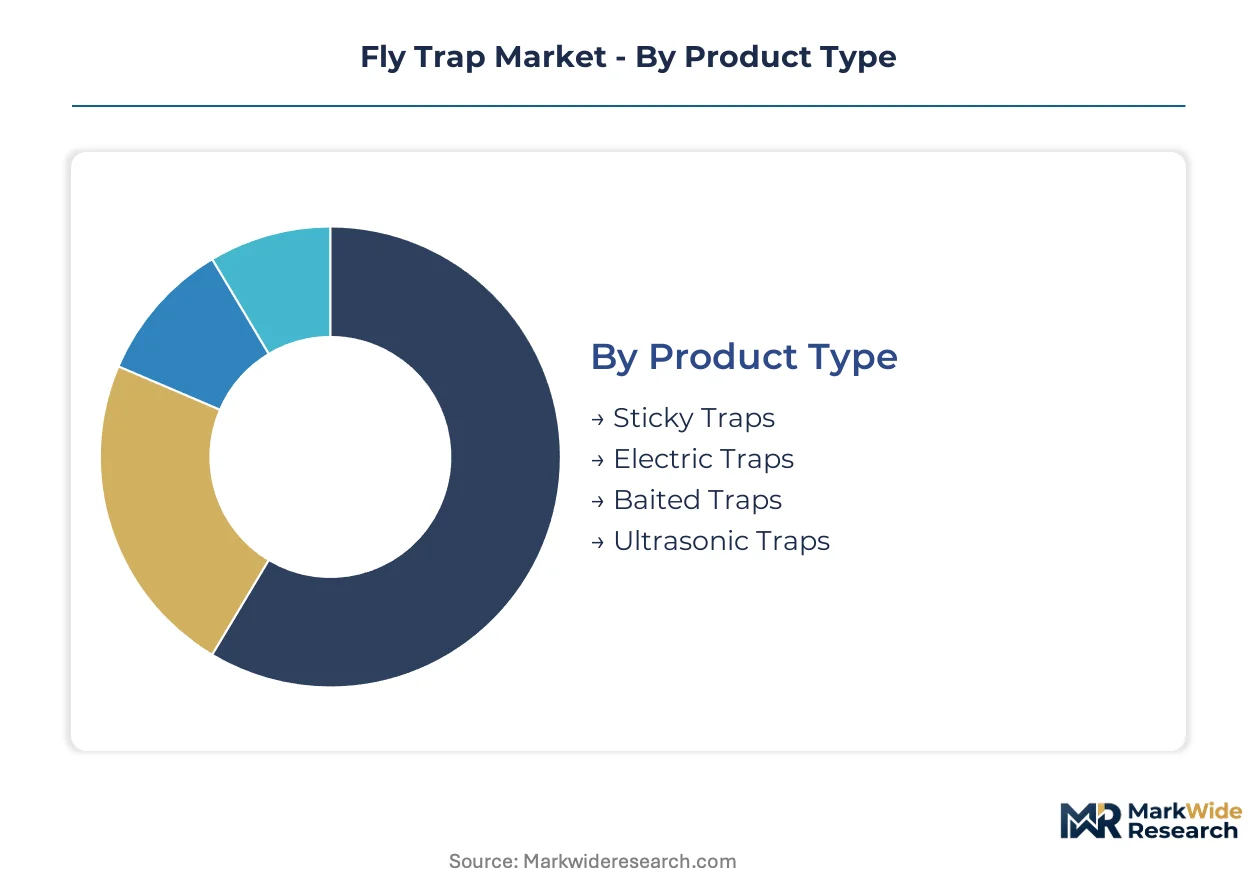
Fly trap procurement splits sharply between capital-intensive commercial installations and disposable retail units. Technology choices cascade through material specifications, regulatory compliance tiers, and service contract structures.
Product Type:
Electric systems command premium positioning through 24-hour operational requirements, while adhesive formats dominate unit volume in retail channels.
- Electric Traps:UV-LED or mercury vapor attraction modules paired with 2,000–4,000 volt grids. Commercial food processing facilities in Germany and the Netherlands favor these for audit-compliant continuous operation.
- Baited Traps:Pheromone and food-based attractant formulations deliver species-specific capture. Organic agriculture segments in the US and EU drive demand as USDA National Organic Program and REACH restrictions exclude synthetic alternatives.
- Sticky Traps:Adhesive-coated boards or ribbons using petroleum-based or natural resin compounds. Retail distribution and residential applications favor low-cost disposability.
- Ultrasonic Traps:Frequency-emitting deterrent devices with limited capture capability. Niche positioning in residential settings where chemical-free claims outweigh efficacy concerns.
Mature deployment sits with Sticky Traps. Newer deployment is concentrated in Baited Traps.
Application:
Facility scale determines hardware specification, with industrial sites demanding integrated monitoring while residential buyers prioritize shelf price.
- Commercial Spaces:Restaurants, hotels, and retail environments requiring documented pest control logs. Third-party hygiene certification in Germany compresses procurement toward electromechanical systems with service bundling.
- Agricultural Fields:Row crops, greenhouses, and orchards deploying traps for integrated pest management. USDA organic certification creates dual-track pricing for compliant hardware.
- Residential Areas:Single-family homes and apartments purchasing disposable adhesive units. Price sensitivity favors mass-market retail channels over specialized distribution.
- Industrial Sites:Warehouses, manufacturing plants, and cold storage facilities. EU F-Gas Regulation phasedown accelerates trap deployment as chemical fumigation alternatives face restrictions.
Procurement autonomy concentrates in Agricultural Fields. Procurement autonomy is eroding fastest in Commercial Spaces.
Material:
Outdoor durability requirements elevate metal and UV-stabilized plastic specifications, while indoor disposability favors paper and untreated wood.
- Plastic:UV-stabilized polypropylene housings for electric grid enclosures and adhesive board frames. Petrochemical input volatility compresses margins on export-bound product lines.
- Metal:Powder-coated aluminum construction for outdoor durability in agricultural and industrial deployments. Higher capital cost justified by extended service life in harsh environments.
- Paper:Biodegradable adhesive board substrates. REACH persistent organic compound restrictions force natural resin formulation shifts.
- Wood:Untreated or minimally processed frames for organic-certified agricultural applications. Limited to niche segments prohibiting synthetic materials.
Cost engineering centers on Plastic. Sustainability compliance is reshaping Paper.
Technology:
Active ingredient claims face escalating regulatory scrutiny, pushing R&D investment toward mechanical and hybrid architectures.
- Hybrid:Mechanical capture combined with remote monitoring sensors. Agricultural operators in Germany and the Netherlands optimize deployment timing through real-time catch data analytics.
- Electronic:UV attraction and electrocution grids. Voltage standardization gaps across national electrical codes complicate cross-border certification.
- Active Ingredient Based:Pheromone or food-based chemical attractants. EPA FIFRA registration and state-level neonicotinoid restrictions force parallel portfolio maintenance.
- Mechanical:Passive adhesive or physical capture without powered components. Lowest regulatory burden supports organic certification compliance.
Regulatory exposure is highest in Active Ingredient Based. Regulatory exposure is lowest in Mechanical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility managers in Germany are replacing legacy pesticide protocols with electromechanical trapping hardware ahead of audit schedules, compressing procurement cycles for non-chemical fly control systems.
Germany
Integrated pest management mandates reshape procurement in commercial food processing. The EU Green Deal and F-Gas Regulation push manufacturers toward non-chemical trapping systems. Food processing clusters in Baden-Württemberg and Bavaria embed trap hardware into compliance infrastructure ahead of third-party hygiene certification.
United States
USDA National Organic Program certification creates dual-track pricing for compliant hardware in agricultural fields. EPA FIFRA registration requirements regulate active ingredient claims in baited traps. California's Central Valley and Florida's citrus belt deploy pheromone-based species-specific lures to reduce bycatch concerns.
Netherlands
Greenhouse operators optimize deployment timing through real-time catch data analytics using hybrid technology segments. REACH restrictions on persistent organic compounds force reformulation of export-bound sticky trap product lines. The Westland region concentrates agricultural trap demand as biological pest management integration accelerates.
China
Domestic food safety audits intensify adoption of UV-LED attraction modules in cold storage facilities. Dual carbon goals accelerate solid-state replacements for mercury vapor lamps. Yangtze River Delta manufacturing hubs retrofit existing housing with LED arrays to avoid full hardware replacement.
India
Organic crop production segments open as FSSAI hygiene standards tighten across food processing. State-level agricultural extension programs promote integrated pest management in horticulture belts. Maharashtra and Karnataka greenhouse clusters drive demand for mechanical trapping systems with remote monitoring sensors.
Fly Trap Market Competitive Landscape
Service contract bundling dominates the current landscape, compressing hardware procurement autonomy for commercial facility managers. The vendor base organizes around three strategic archetypes: biological systems integrators bundling traps with beneficial insect programs, facility management operators embedding hardware into recurring contracts, and adhesive specialists leveraging captive resin supply for pricing advantages. M&A activity concentrates among pest control service networks, while portfolio diversification accelerates as manufacturers add sensor-enabled hybrid systems to traditional electromechanical lines.
Among North American operators, AP&G Co., Inc. (Catchmaster) and Woodstream Corporation exemplify the adhesive-focused archetype with retail channel presence. Rentokil Initial anchors the facility management service tier through embedded commercial contracts. Koppert Biological Systems represents the biological integration model, bundling mechanical capture with broader pest management programs. These three patterns—adhesive manufacturing, service bundling, and biological systems—define competitive positioning across procurement channels.
| Leading Market Players |
|---|
| AP&G Co., Inc. (Catchmaster) |
| Koppert Biological Systems |
| Woodstream Corporation |
| Rentokil Initial |
| DynaTrap |
| Havahart |
| Flowtron Outdoor Products |
| Bell Laboratories |
| Sterling International |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up service networks in commercial pest control are compressing hardware procurement autonomy while locking in multi-year replacement cycles through embedded facility management contracts. This ownership concentration funnels pricing power toward integrated operators and forces standalone manufacturers toward adhesive specialization or biological systems bundling to defend margin positions.
Pricing Analysis
Volume concentrates in disposable sticky traps sold through mass-market retail, while margin pools sit with electric systems deployed in German and Dutch food processing facilities under 24-hour operational requirements. Three-tier pricing structure across premium certified, standard commercial, and economy residential levels reflects USDA National Organic Program compliance and REACH adhesive restrictions as primary differentiation drivers. Cost compression in UV-stabilized polypropylene housings is intensifying because petrochemical input volatility feeds directly into electromechanical hardware margins. Residential buyers exhibit highest price sensitivity, favoring low-cost disposability over performance specifications, while commercial facility managers prioritize audit-compliant documentation over unit cost.
Supply Chain Analysis
Freight cost exposure runs through containerized shipments of UV-stabilized polypropylene pellets from South Korean and Saudi Arabian petrochemical hubs to injection molding operations in China and Germany. Natural resin adhesive feedstocks draw from concentrated forestry operations in Scandinavia and Southeast Asia, while mercury vapor and UV-LED components source from Japanese and Taiwanese optoelectronics specialists. Single-source vulnerability in biodegradable resin supply limits formulation flexibility for mid-tier manufacturers lacking backward integration. Distribution runs through pest control service networks that displace direct manufacturer relationships in commercial channels, consolidating procurement decisions within bundled facility management agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration races are accelerating as manufacturers pursue captive supply of natural resin compounds to secure pricing advantages against REACH-mandated reformulation deadlines. Control over upstream adhesive feedstocks and downstream service channel access represents the decisive leverage point for sustainable margin defense.
For Market Incumbents: Deploy certification investment as the primary defensive lever. Accelerate USDA National Organic Program and EU organic compliance across product lines to capture premium positioning in agricultural segments. Deepen channel control through exclusive service bundling arrangements with facility management operators in German food processing clusters, locking out competing hardware vendors from audit-driven procurement cycles. Counter biological systems integrators like Koppert by embedding sensor-enabled hybrid traps into recurring monitoring contracts that demonstrate measurable pest reduction metrics. For New Entrants and Emerging Players: The EU F-Gas Regulation in Germany and the Netherlands opens a window for solid-state UV-LED retrofit modules that avoid full hardware replacement in existing electromechanical housings. Target greenhouse operators in the Westland region and Baden-Württemberg food processing clusters with incremental upgrade economics rather than capital-intensive system sales. Penetrate through remote sensor convergence, offering IoT-enabled catch analytics as a subscription overlay to commodity trap hardware, displacing incumbent service relationships through superior data transparency. For Investors and Strategic Acquirers: Distressed-cycle entries favor adhesive specialists with captive resin supply in North American retail channels during periods of petrochemical price volatility. The 5-10 year viability window hinges on regulatory compliance trajectory rather than technology displacement risk. Monitor state-level neonicotinoid restriction announcements as the inflection signal: accelerated phase-outs compress parallel portfolio maintenance costs for biological attractant R&D, favoring acquirers with existing natural compound formulation capabilities over synthetic chemistry-dependent targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Resin Supply | REACH adhesive reformulation mandates captive feedstock control for EU market access. |
| UV-LED Retrofit Module Development | Solid-state replacements capture German facility upgrade cycles without full hardware replacement. |
| USDA Organic Certification Acceleration | Dual-track pricing in US agricultural segments separates compliant hardware from commodity alternatives. |
| IoT Sensor Network Embedding | Real-time catch analytics transform passive traps into active data services with recurring revenue. |
| Service Contract Bundling Expansion | Embedded hardware in facility management agreements locks multi-year replacement cycles against price competition. |
Research Methodology
Independent corroboration across regulatory filings, customs trade databases, and industry association disclosures underwrites the qualitative findings in this study. Primary interviews with facility managers at German food processing plants, procurement leads at Dutch greenhouse cooperatives, adhesive formulation chemists, and pest control service operators were combined with secondary validation from EPA FIFRA registrations, ECHA REACH substance restrictions, USDA National Organic Program certification lists, and SEC 10-K disclosures from listed service providers. Bottom-up trap deployment estimates and top-down market sizing triangulate through petrochemical input consumption data and UV-LED import statistics.
Rate-of-change decomposition across product type, application vertical, material specification, and technology architecture anchors the analytical framework. The projection horizon segments electric, baited, sticky, and ultrasonic formats by commercial, agricultural, residential, and industrial end-uses, with further granularity across plastic, metal, paper, and wood material tiers. CAGRs derive from installed base replacement cycles, regulatory compliance deadlines, and technology substitution elasticities. Hybrid technology penetration rates and biological attractant formulation cost curves serve as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for UV-LED solid-state replacement would alter the outlook if mercury vapor lamp phase-outs accelerate beyond baseline assumptions. Forecasts reflect assumptions about regulatory enforcement intensity, resin supply chain stability, and service network consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Automatic Composter Market
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Asia-Pacific Agricultural Tires Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
India Color Sorter Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Food Bucket Elevators Market