
 Aquatic Weed Harvester Market | 2026-2036
Aquatic Weed Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
Aquatic Weed Harvester Market Outlook
North American manufacturing capacity is reconfiguring around specialized amphibious equipment fabrication. Berky GmbH leverages its European engineering heritage to dominate precision cutting systems for municipal contracts. Truxor Wetland Equipment AB anchors the Nordic segment with compact, low-draft units optimized for sensitive wetland environments. Aquarius Systems competes through sustained R&D intensity in conveyor-based collection technologies.
An aquatic weed harvester is a motorized watercraft equipped with submerged cutting blades, conveyor mechanisms, and storage hoppers designed to sever, collect, and transport invasive vegetation from freshwater bodies. Operating depths typically range from 0.5 to 2.5 meters with cutting widths spanning 1.2 to 4.5 meters, enabling targeted removal without chemical discharge into watersheds. Hydraulic harvesters occupy the premium tier where municipalities demand continuous-duty cycles for large waterway cleaning contracts. Automated systems represent the fastest-expanding technology segment as environmental agencies prioritize labor reduction and precision GPS-guided cutting patterns.
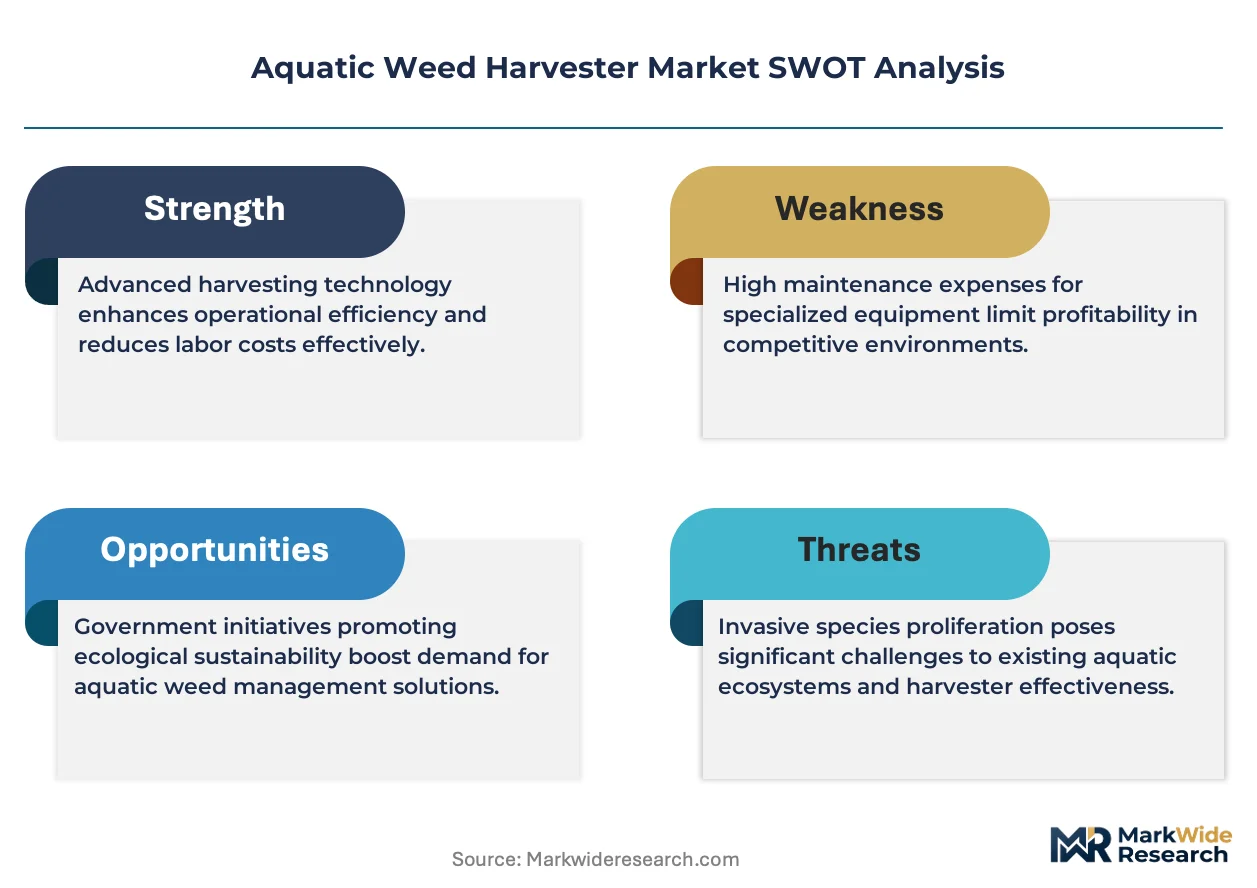
The U.S. EPA coordinates with state-level environmental agencies to enforce Clean Water Act standards that restrict herbicide application near drinking water intakes, directly expanding mechanical harvesting procurement. ISO 14001 environmental management certification and EU Machinery Directive compliance now gate European market access for original equipment manufacturers. Stakeholders must monitor evolving state-level invasive species mandates and assess hybrid propulsion investments against total cost of ownership benchmarks.
Market Dynamics
Municipal procurement offices across the United States are consolidating fleet purchasing around automated harvesting systems as EPA enforcement tightens chemical discharge restrictions near drinking water intakes. This regulatory compression is redistributing contract awards toward mechanical removal specialists capable of ISO 14001-certified continuous operations.
Growth Catalysts
- Clean Water Act Enforcement:The U.S. EPA's intensified scrutiny of herbicide runoff near municipal water supplies is mandating mechanical alternatives for reservoir maintenance contracts.
- Hydrilla Proliferation:Subtropical waterway districts in Florida and the Gulf Coast are experiencing accelerated invasive species spread, forcing state agencies to expand mechanical harvesting fleet procurement.
- GPS-Guided Automation:Precision cutting systems with real-time biomass mapping are reducing labor requirements for large-scale lake management operations.
Market Restraints
- Steel Input Volatility:Amphibious hull fabrication depends on specialized marine-grade alloys subject to commodity price swings, compressing manufacturer margins on fixed municipal contracts.
- Seasonal Utilization Limits:Northern latitude harvesting fleets face 4-6 month operational windows, constraining return on capital for Wisconsin and Minnesota municipal buyers.
- Skilled Technician Scarcity:Hydraulic system maintenance requires certified mechanics with wetland equipment expertise, creating service bottlenecks in rural lake districts.
Strategic Opportunities
- Hybrid Propulsion Mandates:California Air Resources Board standards for harbor craft emissions are creating first-mover advantages for electric-diesel hybrid harvester developers.
- Wetland Restoration Contracts:Army Corps of Engineers ecosystem rehabilitation projects are expanding demand for low-draft precision units in sensitive marsh environments.
- Telematics Integration:Fleet management platforms combining fuel monitoring with cutting-path optimization are opening recurring software revenue streams for equipment vendors.
Industry Challenges
- ISO 14001 Certification Timelines:European export compliance requires 12-18 month environmental management system audits, delaying market entry for North American manufacturers.
- Legacy Fleet Retrofit Complexity:Municipalities with 15-20 year old conveyor systems face integration friction when upgrading to GPS-automated cutting heads without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquatic Weed Harvester Market |
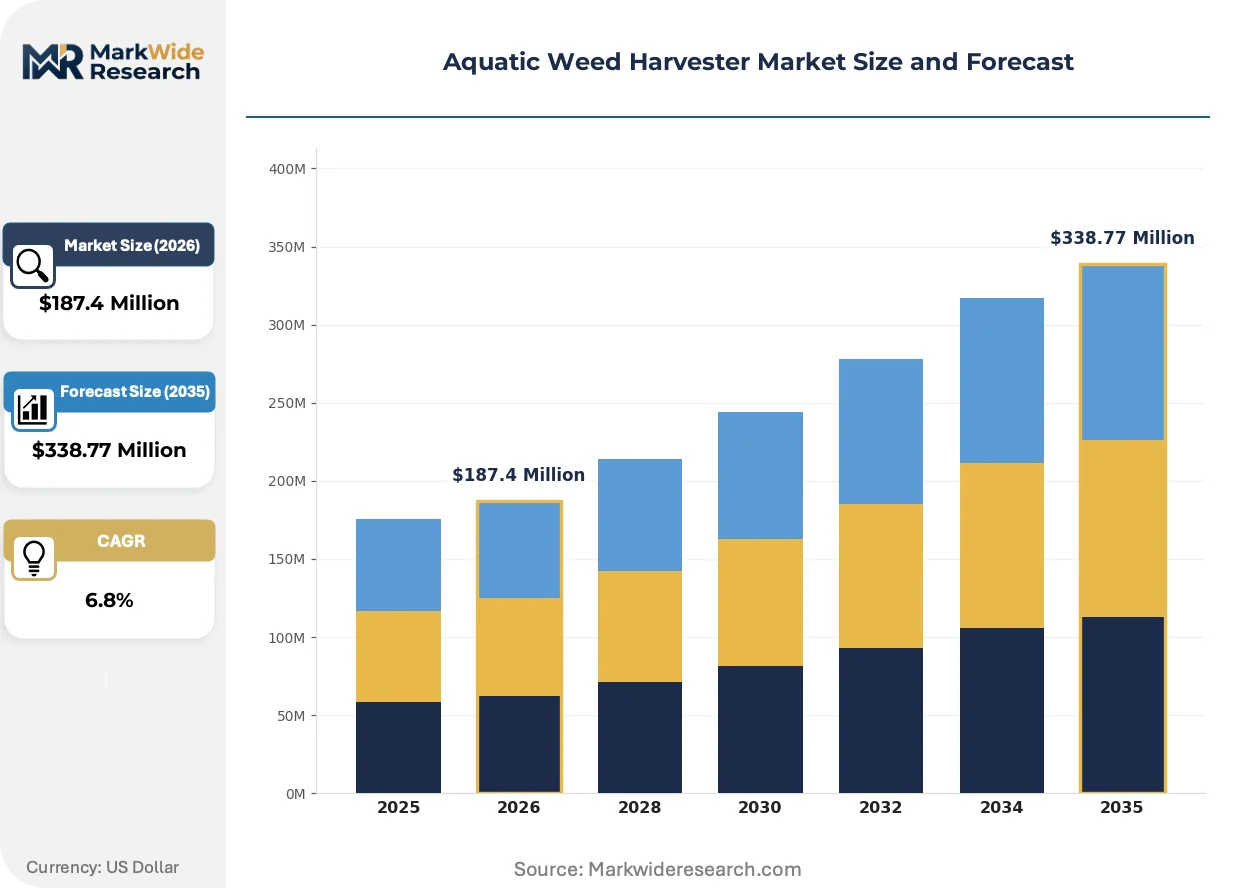
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Harvesters, Mechanical Harvesters, Water-Borne Vehicles, Custom Solutions Application: Lake Management, Pond Maintenance, Waterway Cleaning, Flood Control End User: Municipalities, Private Owners, Environmental Agencies, Recreational Facilities Technology: Automated Systems, Manual Operation, Hybrid Systems, Remote-Controlled Units |
| Companies Covered | Truxor Wetland Equipment AB, Berky GmbH, Aquamarine, Inland Lake Harvesters, Relong, AlphaBoats, Eco-Harvester, SwampThing (American Dredge and Aquatic Weed Control), Aquarius Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquatic Weed Harvester Market Strategic Shifts
Equipment intelligence and propulsion electrification are converging to redefine competitive differentiation in municipal contracting. Vendors are racing to embed automation layers that reduce crew requirements while satisfying tightening emissions standards.
Lidar-equipped cutting heads with real-time biomass density mapping are digitizing harvest path optimization for Florida water management districts. State agencies operating Lake Okeechobee and connected canal systems are piloting these systems to reduce fuel consumption per acre cleared. The technology is digitizing operational planning by enabling precise daily yield forecasting against contractual removal targets.
The U.S. EPA's revised National Pollutant Discharge Elimination System permits are restricting 2,4-D and diquat application within 500 meters of drinking water intakes. Municipal water authorities in Michigan and Ohio are responding by reallocating vegetation management budgets from chemical contractors to mechanical harvesting fleets. This regulatory compression is accelerating RFP issuance for continuous-duty harvester procurement in Great Lakes watersheds.
Performance-based service contracts are displacing traditional equipment purchase arrangements in budget-constrained lake associations. Minnesota and Wisconsin recreational lake districts are contracting harvester operators on per-acre-cleared pricing rather than capitalizing fleet assets. This shift concentrates demand among regional service providers with established maintenance infrastructure, marginalizing smaller equipment-only vendors.
Aquatic Weed Harvester Market Segmentation
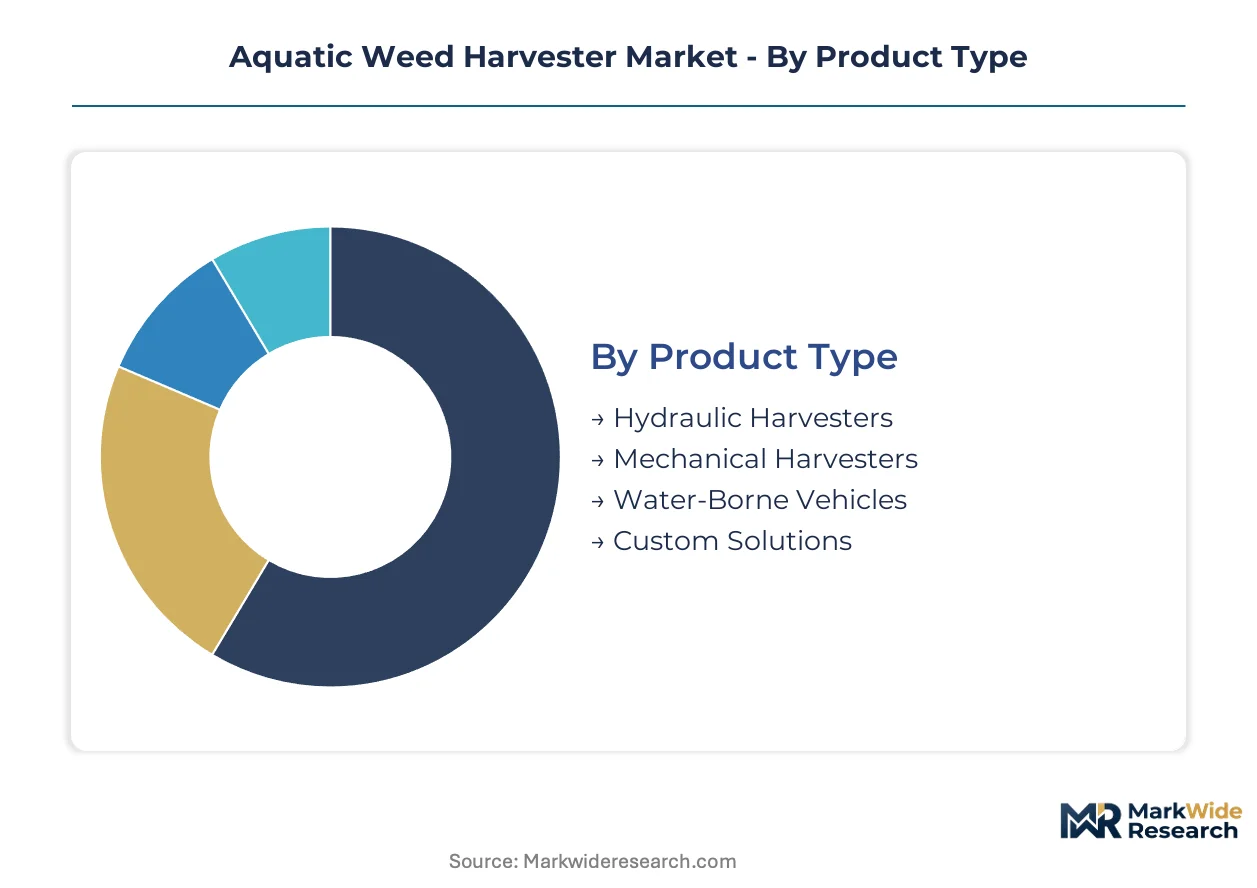
Aquatic weed harvester procurement patterns diverge sharply across operational contexts, from continuous-duty municipal fleets to intermittent private lake maintenance. Equipment specifications, technology tiers, and service models must align with distinct buyer capabilities and regulatory exposure.
Product Type:
The use-case spectrum spans heavy-duty continuous operations requiring industrial hydraulic systems through specialized custom fabrications for unique waterbody geometries.
- Hydraulic Harvesters:These systems deploy high-pressure hydraulic drives powering submerged cutting blades and conveyor mechanisms rated for 8-12 hour daily duty cycles. Municipal contracts across Florida's water management districts concentrate procurement here, driven by state mandates for integrated aquatic plant management plans that specify mechanical removal quotas.
- Mechanical Harvesters:Gear-driven cutting assemblies without hydraulic complexity offer lower capital thresholds and simplified field maintenance for seasonal operators. Demand clusters in Minnesota and Wisconsin lake associations where 4-6 month operational windows constrain capital recovery timelines and favor reduced mechanical complexity.
- Water-Borne Vehicles:Amphibious platforms with integrated propulsion and collection systems serve multi-purpose vegetation and debris removal for flood control authorities.
- Custom Solutions:Purpose-built units address non-standard waterbody dimensions, ultra-shallow draft requirements, or integration with existing fleet infrastructure.
Established volume favors hydraulic harvesters; emerging adoption favors custom solutions.
Application:
Cost tier differentiation separates capital-intensive continuous operations from discretionary maintenance budgets with seasonal cadences.
- Lake Management:Comprehensive vegetation control programs spanning invasive species suppression, native plant preservation, and water quality maintenance. Great Lakes municipalities facing EPA Clean Water Act enforcement are reallocating budgets toward mechanical harvesting contracts for reservoir protection near drinking water intakes.
- Waterway Cleaning:Navigation channel maintenance and flood control infrastructure vegetation removal for Army Corps of Engineers contracts. Gulf Coast districts prioritize these applications where hydrilla proliferation threatens commercial shipping lanes and drainage capacity.
- Pond Maintenance:Smaller-scale private and recreational facility operations with intermittent service requirements and limited operator pools.
- Flood Control:Emergency vegetation removal to maintain hydraulic capacity in stormwater systems and retention basins.
Navigation-dependent contracts concentrate in waterway cleaning; ecosystem restoration dollars flow toward lake management.
End User:
Customer type determines procurement modality, from centralized fleet purchasing through decentralized service contracting.
- Municipalities:City and county water authorities with bonded capital capacity for fleet acquisition and in-house maintenance infrastructure. These buyers dominate Great Lakes and Florida procurement, responding to state invasive species mandates and federal drinking water protection requirements.
- Environmental Agencies:State and federal resource management bodies with ecosystem restoration mandates and performance-based contracting authority. Army Corps of Engineers wetland rehabilitation projects are expanding demand for specialized low-draft equipment in sensitive marsh environments.
- Private Owners:Individual lakefront property holders and small associations with limited capital and seasonal service preferences.
- Recreational Facilities:Golf courses, resorts, and campgrounds requiring aesthetic waterbody maintenance with discretionary timing.
Agency procurement is climbing the fastest; private owner segments show service-model conversion from purchase to contract.
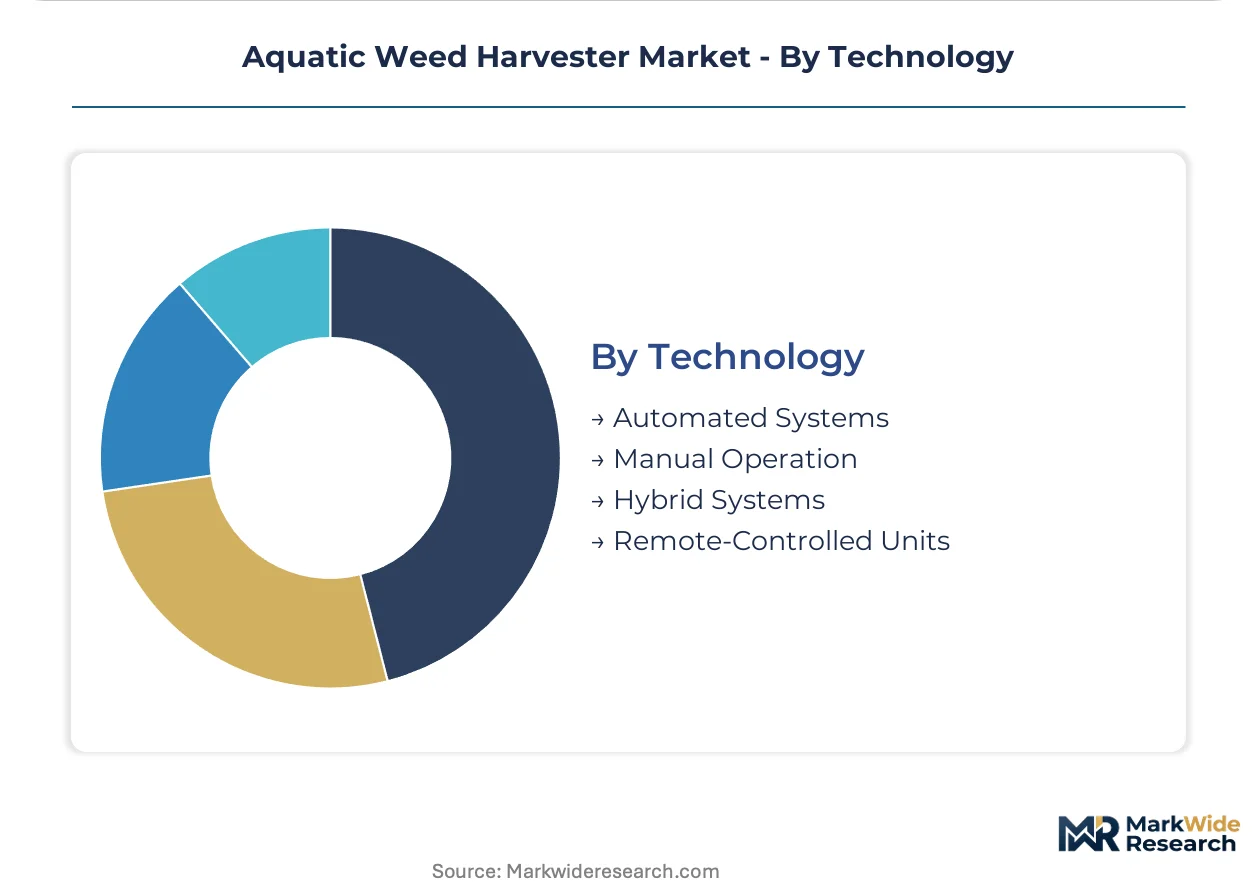
Technology:
Maturity gradients separate proven manual systems from emerging automation layers with embedded intelligence and reduced crew requirements.
- Automated Systems:GPS-guided cutting heads with real-time biomass mapping and autonomous path planning reduce operator count while improving yield precision. Florida water management districts piloting lidar-equipped systems on Lake Okeechobee report reduced fuel consumption per acre cleared through optimized harvest patterns.
- Hybrid Systems:Electric-diesel propulsion architectures addressing California Air Resources Board harbor craft emissions standards while maintaining operational range. First-mover manufacturers are securing municipal contracts in air quality non-attainment zones.
- Manual Operation:Conventional crew-dependent cutting and collection systems with lower capital entry points and established maintenance networks.
- Remote-Controlled Units:Operator-removed platforms for hazardous waterbody access or reduced labor exposure in sensitive environments.
Manual operation retains installed base dominance; hybrid systems are gaining share fastest where emissions regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amphibious equipment fabrication clusters in Germany and Sweden anchor European supply chains, while North American demand concentrates around Great Lakes municipalities and Florida water management districts responding to invasive species mandates.
United States
Florida water management districts and Great Lakes municipalities drive procurement intensity. The U.S. EPA's Clean Water Act enforcement restricts herbicide application near drinking water intakes, forcing mechanical harvesting adoption. Milwaukee and Cleveland water authorities are expanding fleet contracts for reservoir protection.
Germany
Precision engineering heritage supports specialized cutting system manufacturing for municipal export markets. EU Machinery Directive compliance and ISO 14001 certification requirements gate market access for equipment originating here. Bavarian fabricators supply hydraulic harvester components to Dutch water authorities.
Sweden
Nordic wetland preservation priorities sustain demand for low-draft precision units. Truxor Wetland Equipment AB exemplifies compact equipment optimization for sensitive marsh environments. Stockholm archipelago maintenance contracts favor electric-diesel hybrid configurations.
Canada
Ontario and Quebec lake associations face 4-6 month operational windows that constrain capital recovery timelines. Provincial invasive species programs mandate integrated aquatic plant management with mechanical removal quotas. Toronto-area water authorities pilot GPS-guided automation for yield optimization.
Netherlands
Polder waterway maintenance and flood control infrastructure vegetation removal sustain specialized demand. Rotterdam port authorities contract for navigation channel clearing where sediment disturbance restrictions apply. Dutch environmental agencies specify continuous-duty hydraulic systems for canal network contracts.
Aquatic Weed Harvester Market Competitive Environment
European precision specialists and North American automation developers split the market across distinct capability vectors. Consolidation pressure intensifies as municipalities consolidate fleet purchasing around ISO 14001-certified continuous operations. Three archetypes dominate: heritage engineering houses with municipal contract relationships, compact equipment specialists for sensitive wetlands, and R&D-intensive automation developers. Strategic moves concentrate on hybrid propulsion investments and telematics platform integration for recurring software revenue.
Among European heritage fabricators, Berky GmbH and Truxor Wetland Equipment AB occupy positions reflecting distinct geographic specializations—German precision engineering and Nordic wetland optimization respectively. Aquarius Systems sits within the automation development tier, representing conveyor-based collection technology investment patterns visible across North American municipal procurement.
| Leading Market Players |
|---|
| Truxor Wetland Equipment AB |
| Berky GmbH |
| Aquamarine |
| Inland Lake Harvesters |
| Relong |
| AlphaBoats |
| Eco-Harvester |
| SwampThing (American Dredge and Aquatic Weed Control) |
| Aquarius Systems |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in German precision cutting system fabrication is driving extended lead times for municipal contract bidders and compressing pricing flexibility for North American fleet operators. This utilization squeeze simultaneously elevates supplier bargaining power and forces buyers toward longer-term offtake arrangements to secure delivery slots.
Pricing Analysis
The U.S. EPA's Clean Water Act enforcement dictates the pricing tier structure across the aquatic weed harvester market. Three-tier pricing separates ISO 14001-certified continuous-duty hydraulic systems from mechanical harvesters and entry-level seasonal units. Price differentiation centers on certification grade and after-sales service bundling, with municipalities facing drinking water mandates showing lowest price sensitivity while Minnesota lake associations exhibit acute budget constraints. Cost compression in the mechanical tier is intensifying because Wisconsin and Ontario buyers prioritize capital recovery speed over feature depth.
Supply Chain Analysis
Specialized amphibious hull fabricators in Germany, Sweden, and the United States hold concentrated contract-manufacturing capacity for precision cutting assemblies. Raw material flows draw from marine-grade steel suppliers in the Ruhr region, hydraulic component specialists in Bavaria, and conveyor system fabricators in the American Midwest. Single-source vulnerability runs through European hydraulic drive suppliers, where 12-18 month certification timelines constrain alternative sourcing. Distribution runs through municipal procurement offices and environmental agency fleet managers with bonded capital authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aquatic weed harvester market is entering a cyclical recovery phase as EPA enforcement tightens herbicide restrictions and forces mechanical harvesting adoption across Great Lakes watersheds.
For Market Incumbents: Entrench municipal contract relationships through captive maintenance infrastructure and backward integration into hydraulic component supply. ISO 14001 certification investment creates switching costs against emerging automation developers. Capacity addition in Florida water management districts defends position against hybrid propulsion specialists targeting California Air Resources Board compliance mandates. For New Entrants and Emerging Players: Canadian provincial lake associations represent the most penetrable white-space target, where 4-6 month operational windows and constrained capital recovery timelines favor service-model disruption over equipment sales. Telematics-enabled per-acre-cleared contracting offers a defensible go-to-market angle against legacy fleet vendors with rigid purchase arrangements. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid-electric propulsion development programs as California emissions standards propagate to other air quality non-attainment zones. Acquisition targets should display established GPS-guided automation roadmaps and existing municipal pilot program relationships. The signal to watch is state-level invasive species mandate acceleration in Gulf Coast jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Propulsion Development | California Air Resources Board harbor craft standards create first-mover contracting advantages in coastal municipalities. |
| Telematics Platform Integration | Fuel monitoring combined with cutting-path optimization opens recurring software revenue streams from municipal fleet managers. |
| ISO 14001 Certification Investment | European export compliance gates access to Dutch canal network contracts and German component supply partnerships. |
| Backward Integration into Hydraulics | In-house production of cutting drive assemblies defends margins against steel input volatility on fixed municipal contracts. |
| Performance-Based Service Contracting | Per-acre-cleared pricing models convert Minnesota and Wisconsin lake associations from capital purchase to recurring revenue relationships. |
Study Parameters
A standing panel of municipal water authority fleet managers, environmental agency procurement officers, amphibious equipment maintenance directors, and hydraulic system engineers provided ongoing calibration throughout the research process. Primary interviews with these stakeholders were combined with secondary validation from U.S. EPA enforcement databases, state invasive species mandate filings, Army Corps of Engineers contract award records, and EU Machinery Directive compliance registries. Bottom-up equipment shipment tracking and top-down municipal budget allocation analysis were triangulated to establish market sizing.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity bands reflecting regulatory enforcement intensity variation and steel commodity price volatility. Segmentation dimensions modeled include product type tier, application context, end-user procurement modality, and technology maturity gradient. CAGRs were derived from installed base replacement cycles and new fleet expansion patterns, with specific weighting applied to Florida water management district procurement pipelines and Great Lakes reservoir protection mandates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electric-diesel hybrid specialists or automated cutting system developers would shift outcomes beyond modeled ranges. Quarterly review of state-level invasive species mandate issuance and EPA regional enforcement action intensity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Greenhouse Kit Market
Agricultural Equipment
Solar Fruit Dryer Market
Agricultural Equipment
Floating Covers Market
Agricultural Equipment
Feed Mixer Market
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Vegetable Sorting Machines Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Plows Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Global Grain Bin Management Solution Market