
 Grab and Go Bottles Market | 2026-2036
Grab and Go Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Grab and Go Bottles Market Outlook
The EU Single-Use Plastics Directive is rebalancing the cost-of-entry calculus for new packaging formats across Europe. Amcor plc leverages its global recycling infrastructure to sustain supply chain continuity under tightening waste rules. Berry Global Inc. anchors North American capacity through specialized blow-molding operations for portable formats. ALPLA Group competes on lightweight engineering, dominating thin-wall PET production for single-serve beverages.
Grab and go bottles are single-use or limited-reuse containers engineered for immediate consumption, typically manufactured through injection stretch blow molding with wall thicknesses below 0.3 millimeters to minimize material weight. These vessels serve on-the-move hydration needs across retail, foodservice, and institutional channels. Plastic formats still occupy the largest volume share, though aluminum segments are accelerating as brands chase shelf differentiation and extended chill retention. Screw cap closures lead in cost efficiency, while straw lid variants capture premium positioning among fitness enthusiasts and student populations.
The EPA oversees recycling rate targets that shape post-consumer content mandates in the United States, while EFSA guidelines govern food-contact material safety across European supply chains. REACH compliance adds testing burdens for imported additives and colorants. Stakeholders must monitor how extended producer responsibility frameworks evolve and whether deposit-return schemes expand beyond their current geographic footprint.
Market Dynamics
The EU Single-Use Plastics Directive is compressing virgin PET demand while forcing converters to requalify supply chains around post-consumer recycled content and alternative substrates.
Growth Catalysts
- Fitness channel expansion:Gym chains and boutique studios are replacing fountain dispensers with single-serve bottles, creating dedicated SKU demand that bypasses traditional retail velocity requirements.
- REACH additive compliance:Harmonized safety standards across European supply chains reduce testing redundancy for multi-market brands, accelerating cross-border product launches.
- Aluminum canning line retrofitting:Beverage co-packers are converting idle carbonated soft drink capacity to still water, enabling metal format entry without greenfield investment.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in Southern and Eastern Europe limit certified food-grade flake availability, forcing price premiums or volume rationing.
- Blow-molding equipment oligopoly:Three German and Austrian machinery builders control 70% of thin-wall PET output capacity, creating order backlogs during demand surges.
- Extended producer responsibility fee escalation:France and Italy have doubled EPR contributions for non-recyclable formats since 2023, eroding margin on conventional multilayer structures.
Strategic Opportunities
- Deposit-return scheme expansion:Poland and Romania are piloting container deposit legislation modeled on German DRS success, creating closed-loop supply anchors for rPET sourcing.
- Smart vending integration:IoT-enabled refill stations in corporate campuses and transit hubs are integrating reusable bottle sales with usage-tracking subscriptions.
- Medical-grade hydration:Hospital and long-term care facilities are specifying antimicrobial bottle surfaces for immunocompromised patients, opening premium pricing tiers.
Industry Challenges
- Blow mold technician shortage:Specialized knowledge of thin-wall process control and cavitation optimization is retiring faster than vocational programs replace it.
- Multi-material separation:Labels, sleeves, and closure liners using incompatible polymers contaminate mechanical recycling streams, requiring manual sortation or chemical recycling partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grab and Go Bottles Market |
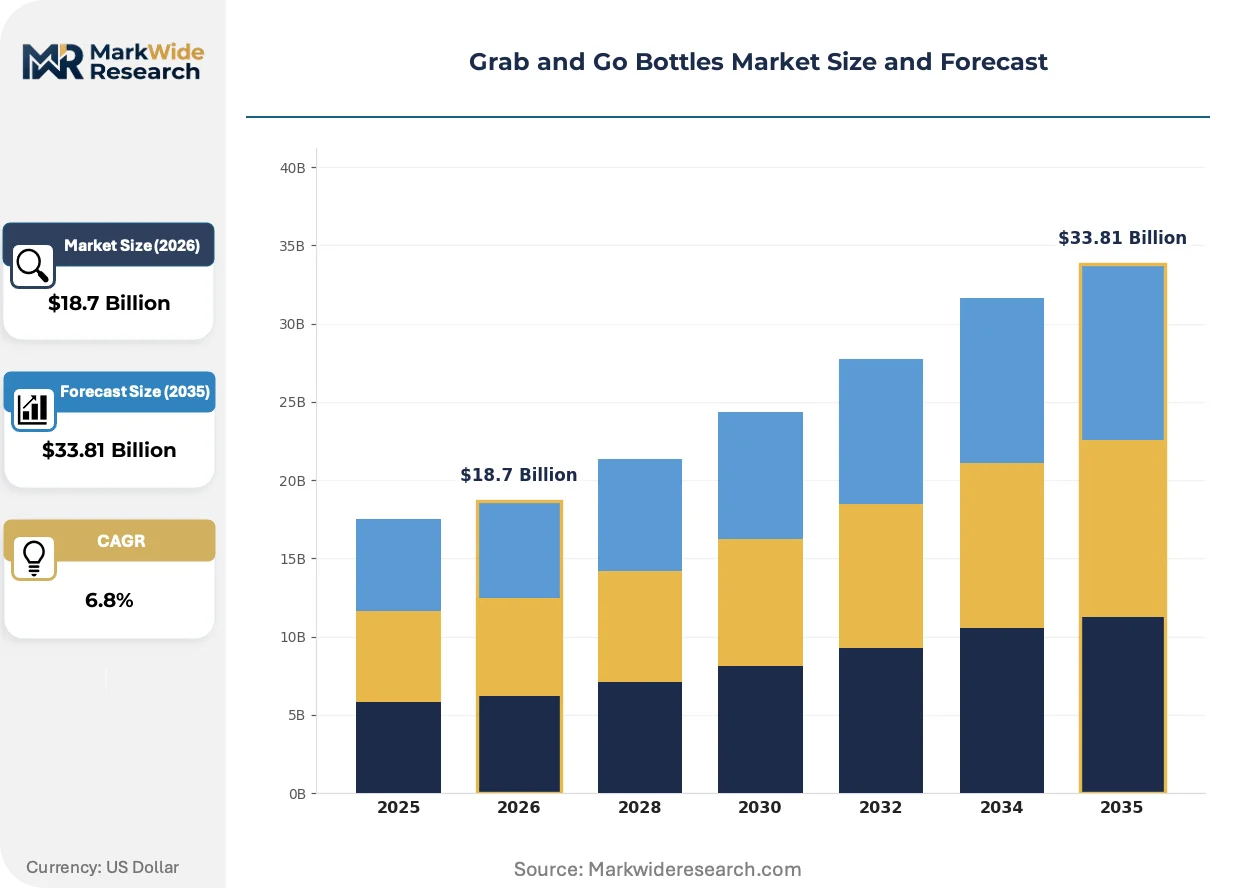
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Stainless Steel, Aluminum Closure Type: Screw Cap, Flip Top, Straw Lid, Pump Capacity: 250ml, 500ml, 750ml, 1L End User: Consumers, Fitness Enthusiasts, Travelers, Students |
| Companies Covered | Amcor plc, Ardagh Group S.A., Tetra Pak Group, Berry Global Inc., Owens-Illinois Inc., Gerresheimer AG, Graham Packaging Company, ALPLA Group, Vidrala SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grab and Go Bottles Market Strategic Shifts
Material science breakthroughs and regulatory sequencing are converging to redefine what constitutes a viable single-serve package, with shelf differentiation now requiring functional performance beyond basic containment.
Enzymatic recycling technology is integrating into European bottle-to-bottle operations, depolymerizing colored and contaminated PET back to virgin-quality monomers. Nestlé Waters and Suntory have offtake agreements with Carbios and Loop Industries respectively, securing non-fossil feedstock for premium lines. This technology is integrating closed-loop credibility into brand equity without the visual degradation associated with mechanical recycling.
EFSA's updated guidance on food-contact recycled plastics is tightening migration testing protocols for contaminants from non-food sources. Compliance now requires supply chain segregation and enhanced decontamination validation, adding six to nine months to new material qualification. Small and mid-sized converters without in-house analytical capabilities are outsourcing testing to certified laboratories in Germany and the Netherlands.
Direct-to-consumer subscription models for functional beverages are bypassing traditional retail slotting fees and velocity requirements. Brands like Liquid Death and Pathwater use owned e-commerce and Amazon storefronts to test aluminum and paper-based formats before securing grocery distribution. This channel shift is most pronounced in California and Pacific Northwest metros where environmental credentialing drives purchase decisions.
Grab and Go Bottles Market Segmentation
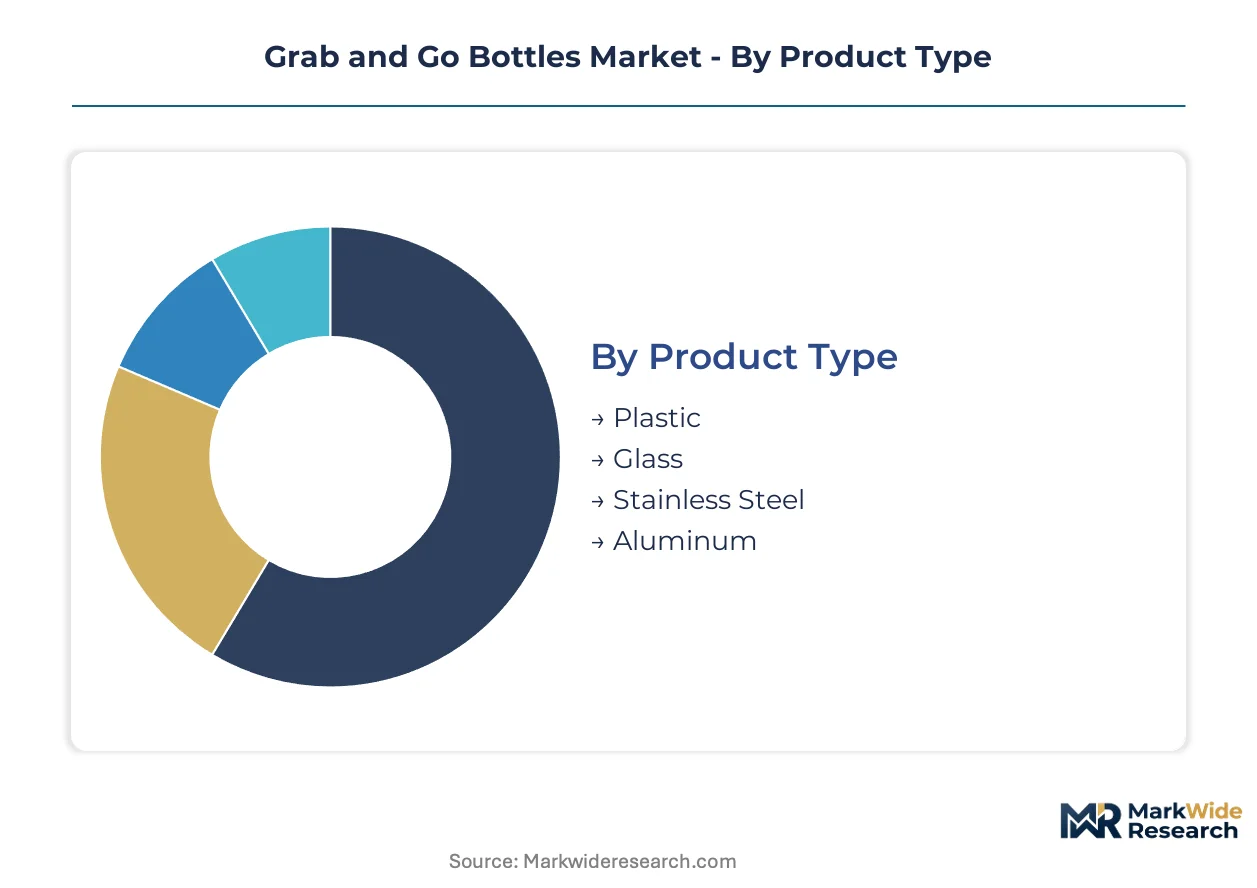
Segmentation in grab and go bottles determines equipment investment thresholds, material qualification timelines, and channel access requirements. Each dimension creates distinct margin profiles and regulatory exposure that shape converter strategy.
Product Type:
Capital intensity varies sharply by substrate, with metal formats demanding the highest upfront tooling and line conversion costs.
- Plastic:Injection stretch blow molding dominates thin-wall PET production, with wall specifications below 0.3 millimeters minimizing resin weight. Gym chains and boutique fitness studios in Germany and the United States are replacing fountain dispensers with single-serve plastic bottles, creating dedicated SKU demand that bypasses traditional retail velocity requirements.
- Aluminum:Beverage co-packers are converting idle carbonated soft drink canning lines to still water, enabling metal format entry without greenfield investment. Aluminum segments are accelerating as brands chase shelf differentiation and extended chill retention in premium hydration formats.
- Glass:Borosilicate and soda-lime compositions serve premium positioning in hospitality and gift channels where tactile weight signals quality.
- Stainless Steel:Double-wall vacuum insulation commands the highest unit economics, targeting reusable applications in corporate and outdoor recreation segments.
Plastic absorbs the bulk of installed capacity; aluminum is expanding most quickly.
Closure Type:
Closure selection correlates with consumption occasion and price tier, with fitness-oriented formats commanding premium positioning.
- Screw Cap:Polypropylene and HDPE threaded designs deliver the lowest per-unit cost across high-velocity retail channels. Screw cap closures lead in cost efficiency for mass-market hydration in Germany, the United States, and Japan.
- Straw Lid:Silicone valve and integrated straw configurations capture premium positioning among fitness enthusiasts and student populations seeking one-handed consumption.
- Flip Top:Hinged polypropylene mechanisms suit cycling and outdoor activity where spill prevention outweighs cost sensitivity.
- Pump:Dispenser mechanisms concentrate in personal care and functional beverage crossovers, requiring specialized molding expertise.
Screw cap configurations dominate volume throughput; straw lid variants are climbing the fastest as fitness channel expansion accelerates.
Capacity:
Volume segmentation maps directly to consumption occasion, with mid-range formats capturing the broadest channel penetration.
- 500ml:The standard single-serve specification balances portability with perceived value across retail and foodservice. Convenience stores in the United States and Japan allocate prime shelf space to 500ml formats as premium hydration gains traction.
- 250ml:Miniature formats serve airline hospitality, hotel minibars, and sampling programs where portion control drives specification.
- 750ml:Extended-duration sizing targets outdoor recreation and long-haul travel segments willing to trade bulk for reduced refill frequency.
- 1L:Value-oriented bulk positioning concentrates in club retail and emergency preparedness channels, with lower per-ounce pricing.
500ml absorbs the bulk of installed capacity; 750ml is gaining share fastest as outdoor and travel segments recover.
End User:
Customer type determines regulatory exposure and channel access, with institutional buyers imposing the most stringent qualification requirements.
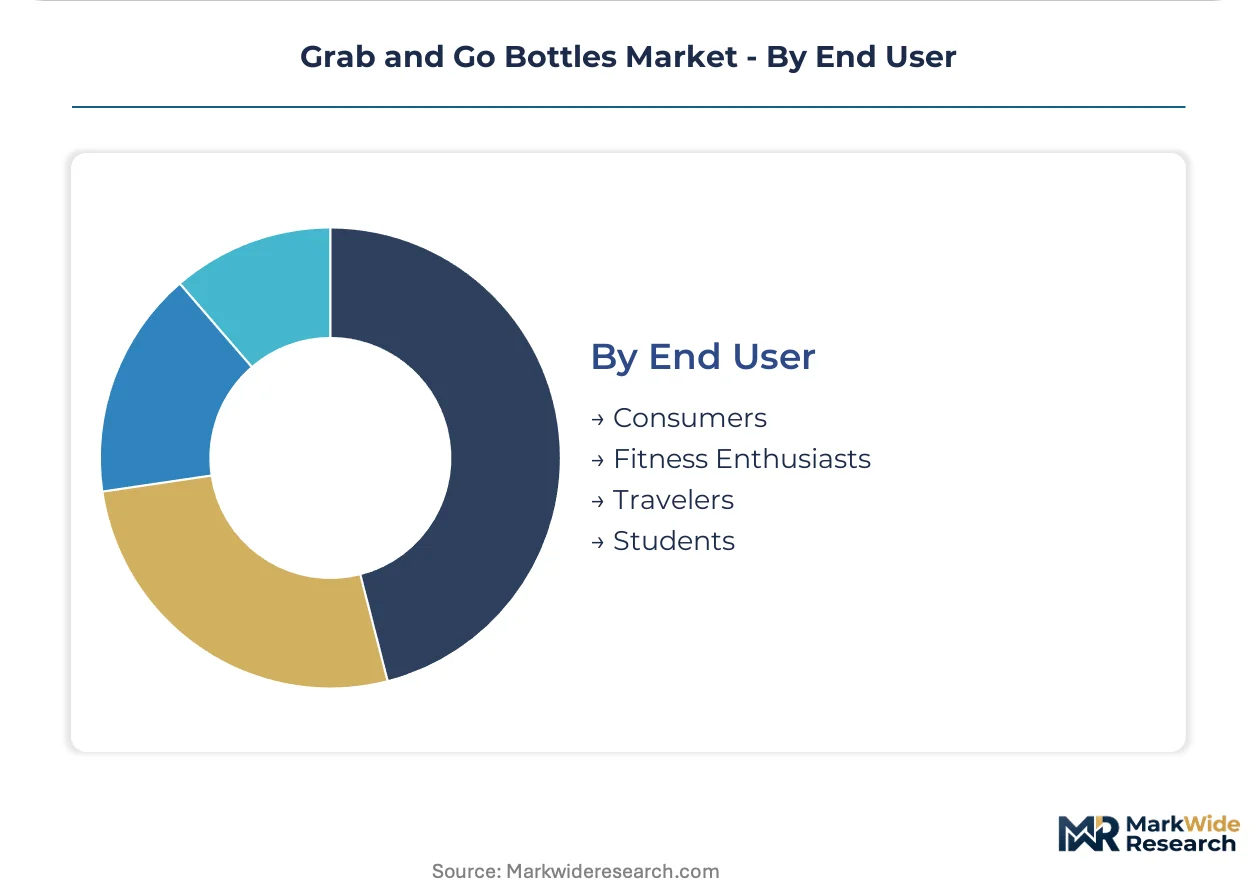
- Fitness Enthusiasts:Protein shaker integration, measurement markings, and antimicrobial surface specifications define this high-engagement segment. Boutique studios and gym chains are replacing fountain dispensers with single-serve bottles, creating dedicated SKU demand with premium pricing tolerance.
- Consumers:Mass-market hydration spans impulse retail, grocery, and e-commerce with the broadest format acceptance and highest price sensitivity.
- Travelers:TSA-compliant sizing, collapsible designs, and leak-proof certification dominate airport retail and hospitality procurement.
- Students:Durability, personalization options, and price accessibility shape back-to-school and campus bookstore purchasing.
General consumers absorb the bulk of installed capacity; fitness enthusiasts represent the steepest expansion trajectory as gym channel partnerships proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for grab and go bottles concentrates in Germany, the United States, and Japan where premium hydration formats command expanding shelf space. Fitness channel partnerships and regulatory pressure on single-use plastics are rebalancing regional production priorities.
United States
Boutique fitness studios and gym chains in California and New York are replacing fountain dispensers with single-serve bottles, creating dedicated SKU demand that bypasses traditional retail velocity requirements. EPA recycling rate targets shape post-consumer content mandates for domestic converters. Berry Global Inc. anchors North American capacity through specialized blow-molding operations concentrated in the Midwest and Southeast manufacturing corridors.
Germany
The EU Single-Use Plastics Directive compresses virgin PET demand while forcing converters to requalify supply chains around post-consumer recycled content. EFSA guidelines govern food-contact material safety with REACH compliance adding testing burdens for imported additives. ALPLA Group competes on lightweight engineering from its Austrian-German industrial base, dominating thin-wall PET production for single-serve beverages across Central European markets.
Japan
Convenience store operators in Tokyo and Osaka allocate prime shelf space to 500ml premium hydration formats as on-the-move consumption patterns intensify. METI standards and container deposit legislation modeled on European DRS success create closed-loop supply anchors for rPET sourcing. Specialized converters in the Chubu region around Nagoya supply precision blow-molded bottles for functional beverage brands targeting fitness enthusiasts and student populations.
United Kingdom
Retail consolidation in London and the Southeast drives demand for differentiated closure formats including straw lid variants that capture premium positioning. Extended producer responsibility frameworks have doubled fee contributions for non-recyclable formats since 2023, eroding margin on conventional multilayer structures. Converters in the Midlands and North England are retrofitting aluminum canning lines to still water production, enabling metal format entry without greenfield investment.
France
EPR fee escalation for non-recyclable formats has accelerated material substitution toward recycled PET and aluminum among Paris-based beverage brands. ANSM and ECHA compliance requirements shape additive selection for food-contact applications. Enzymatic recycling technology is integrating into bottle-to-bottle operations in the Hauts-de-France industrial cluster, depolymerizing colored and contaminated PET back to virgin-quality monomers for premium line supply.
Grab and Go Bottles Market Competitive Environment
European producers anchor one tier; North American specialists hold differentiated positions in fitness and foodservice channels. The vendor base spans integrated packaging conglomerates with global recycling infrastructure and regional converters focused on thin-wall process optimization. Three archetypes dominate: vertically integrated material-science leaders, dedicated blow-molding operators, and diversified rigid packaging generalists. Capacity expansion and strategic partnerships with beverage co-packers constitute the primary competitive moves as brands chase aluminum format entry.
Within the integrated material-science tier, Amcor plc and Berry Global Inc. occupy positions defined by global recycling infrastructure and North American blow-molding specialization respectively. ALPLA Group exemplifies the lightweight engineering archetype, sitting within the Austrian-German machinery corridor that controls dominant shares of thin-wall PET output capacity. These three anchors illustrate how geographic concentration of technical expertise shapes competitive positioning under tightening waste regulations.
| Leading Market Players |
|---|
| Amcor plc |
| Ardagh Group S.A. |
| Tetra Pak Group |
| Berry Global Inc. |
| Owens-Illinois Inc. |
| Gerresheimer AG |
| Graham Packaging Company |
| ALPLA Group |
| Vidrala SA |
| Others |
Value Chain & Pricing Dynamics
Captive integration into rPET flake processing anchors both supply security and pricing power for converters serving German and French beverage brands under EU Single-Use Plastics Directive mandates. This backward control insulates qualified suppliers from feedstock scarcity premiums while forcing non-integrated competitors into spot-market vulnerability.
Pricing Analysis
Volume throughput concentrates in mass-market 500ml screw-cap PET bottles where per-unit margins compress under rPET feedstock scarcity, while premium straw-lid aluminum formats in fitness channels command pricing tolerance through extended chill retention and shelf differentiation. Price differentiation rests on EFSA compliance certification and post-consumer recycled content thresholds, with non-compliant multilayer structures facing EPR fee escalation in France and Italy. Cost compression in conventional plastic tiers intensifies because blow-molding equipment backlogs limit capacity response. Mass-market retail buyers exhibit highest price sensitivity; boutique fitness studios and hospital procurement show lowest.
Supply Chain Analysis
Domestic-content mandates under extended producer responsibility frameworks in Germany and France are reshaping sourcing toward certified European rPET collection networks and regional aluminum canning retrofits. Manufacturing gravity centers on Germany, Austria, and the United States where thin-wall PET machinery builders and beverage co-packers cluster. Raw material flows draw from post-consumer PET collection infrastructure, primary aluminum smelters, and imported colorant additives under REACH registration. Single-source vulnerability concentrates in German-Austrian blow-molding equipment supply. Distribution runs through retail grocery, fitness channel direct partnerships, and hospital procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The grab and go bottles market sits in a substrate-transition phase where enzymatic recycling technology displaces mechanical recycling for premium brand lines requiring virgin-quality aesthetic performance.
For Market Incumbents: Acquire rPET collection and decontamination assets in Poland and Romania ahead of deposit-return scheme expansion. Backward integration into food-grade flake processing defends margin position against feedstock scarcity premiums. Invest in enzymatic recycling partnerships to secure non-fossil feedstock offtake for EFSA-compliant premium lines before qualification timelines lengthen. For New Entrants and Emerging Players: Capture white-space in medical-grade antimicrobial bottle surfaces for hospital and long-term care procurement where premium pricing tolerance exceeds fitness channel benchmarks. Target underpenetrated corporate campus IoT-enabled refill station integration with usage-tracking subscription bundling. Lead with direct-to-consumer functional beverage subscription models to bypass retail slotting fee barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated packaging conglomerates seeking European rPET supply chain control. Long-term viability favors converters with in-house analytical capabilities for EFSA migration testing and enzymatic recycling offtake agreements. Watch enzymatic recycling cost curves as the inflection signal for mechanical recycling displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Collection Infrastructure Acquisition | Secures qualified food-grade flake supply ahead of EU mandate tightening and deposit-return expansion. |
| Enzymatic Recycling Partnership | Enables virgin-quality aesthetic performance for premium lines without mechanical recycling visual degradation. |
| Aluminum Canning Line Retrofit | Converts idle carbonated soft drink capacity to still water production without greenfield capital deployment. |
| Medical-Grade Surface Certification | Opens hospital procurement channels with antimicrobial specifications for immunocompromised patient hydration. |
| Smart Vending Integration | Captures corporate campus and transit hub demand through IoT-enabled refill stations with subscription tracking. |
Study Parameters
Multi-period observation of rPET feedstock pricing, EPR fee trajectories, and enzymatic recycling deployment anchored the trend analysis, supplemented by interviews with blow-molding plant managers, beverage brand procurement leads, fitness channel category buyers, and EFSA compliance consultants. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, EPA recycling rate publications, SEC filings of integrated packaging conglomerates, and trade data on thin-wall PET machinery imports. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Input-output matrices mapped resin weight specifications, closure type premiums, and channel-specific velocity requirements across product type, capacity, and end-user dimensions over the projection horizon. CAGRs were derived from segmented growth rate blending and cross-validation against macroeconomic consumption indicators. Forecast inputs included gym chain expansion pipelines, deposit-return scheme legislative timelines, and aluminum canning line conversion announcements.
The model holds under continued EU regulatory enforcement and rPET collection infrastructure investment; deviation in enzymatic recycling cost breakthroughs or EPR fee suspension would shift substrate substitution velocity. Forecasts reflect documented assumptions about EFSA qualification timelines and machinery order backlogs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
India Bottled Water Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Fruit Vinegar Market
Beverages
Sports Drink Market
Beverages
Beverage Premix Market
Beverages
United States Smoothie Market
Beverages
Japan Energy Drink Market
Beverages
Global Soda Maker Market
Beverages
Europe Bottled Water Processing Market
Beverages
Morocco Bottled Water Market
Beverages
United States Soy Beverages Market
Beverages
Superfood Infused Beverages Market
Beverages
Citrus Water Market
Beverages
Flavored Powder Drinks Market
Beverages
Detox Drinks Market
Beverages
Kvass Market