
 Fruit Vinegar Market | 2026-2036
Fruit Vinegar Market Size, Share, and Industry Trends Forecast 2026-2036
Fruit Vinegar Market Foresight
The EU Green Deal is decoupling fruit vinegar production from carbon-intensive supply chains, compelling manufacturers to adopt renewable energy in fermentation facilities. ACETUM SRL leverages its Modena heritage to sustain geographic dominance in aged balsamic exports. Bragg Live Food Products anchors the North American organic segment through raw-unfiltered positioning. Mizkan Group competes across Asian markets with rice-fruit hybrid formulations.
Fruit vinegar is an acidic liquid produced by double fermentation of fruit sugars into ethanol, then acetic acid by bacteria such as Acetobacter, typically achieving four to six percent acidity for food-grade applications. The product serves as a preservative, flavor enhancer, and functional ingredient across commercial kitchens and packaged goods manufacturing. Apple vinegar occupies the largest share among product types due to established wellness associations and broad culinary versatility. Beverage applications represent the fastest-expanding segment as drinking vinegars and shrubs gain traction in specialty retail channels. Food Manufacturers among end users capture concentrated margin pools through bulk procurement and private-label formulation contracts.
EMA food-contact guidelines and EU REACH chemical safety standards govern acetic acid purity thresholds and packaging material compliance for European fruit vinegar producers. FDA Good Manufacturing Practices and USDA organic certification shape market access requirements in the United States, while FSSAI labeling mandates govern imported vinegar sales across India. Stakeholders must monitor evolving fermentation technology patents and shifting retailer sustainability scorecards to secure shelf placement in consolidated distribution channels.
Market Dynamics
The EU F-Gas Regulation is forcing ambient fermentation adoption across European fruit vinegar production, decoupling traditional cold-chain processing from synthetic refrigerants and redrawing facility investment priorities.
Growth Catalysts
- Wellness Routine Integration:Household consumers in Germany and France are expanding pantry purchases of apple cider vinegar for daily health regimens, creating sustained pull-through demand.
- EMA Food-Contact Guidelines:Harmonized acetic acid purity standards across Europe are reducing cross-border compliance friction and enabling scaled distribution.
- Traditional Production Clusters:Demand concentrates in Italy's Modena and Reggio Emilia provinces, where aged balsamic heritage commands premium export positioning.
Market Restraints
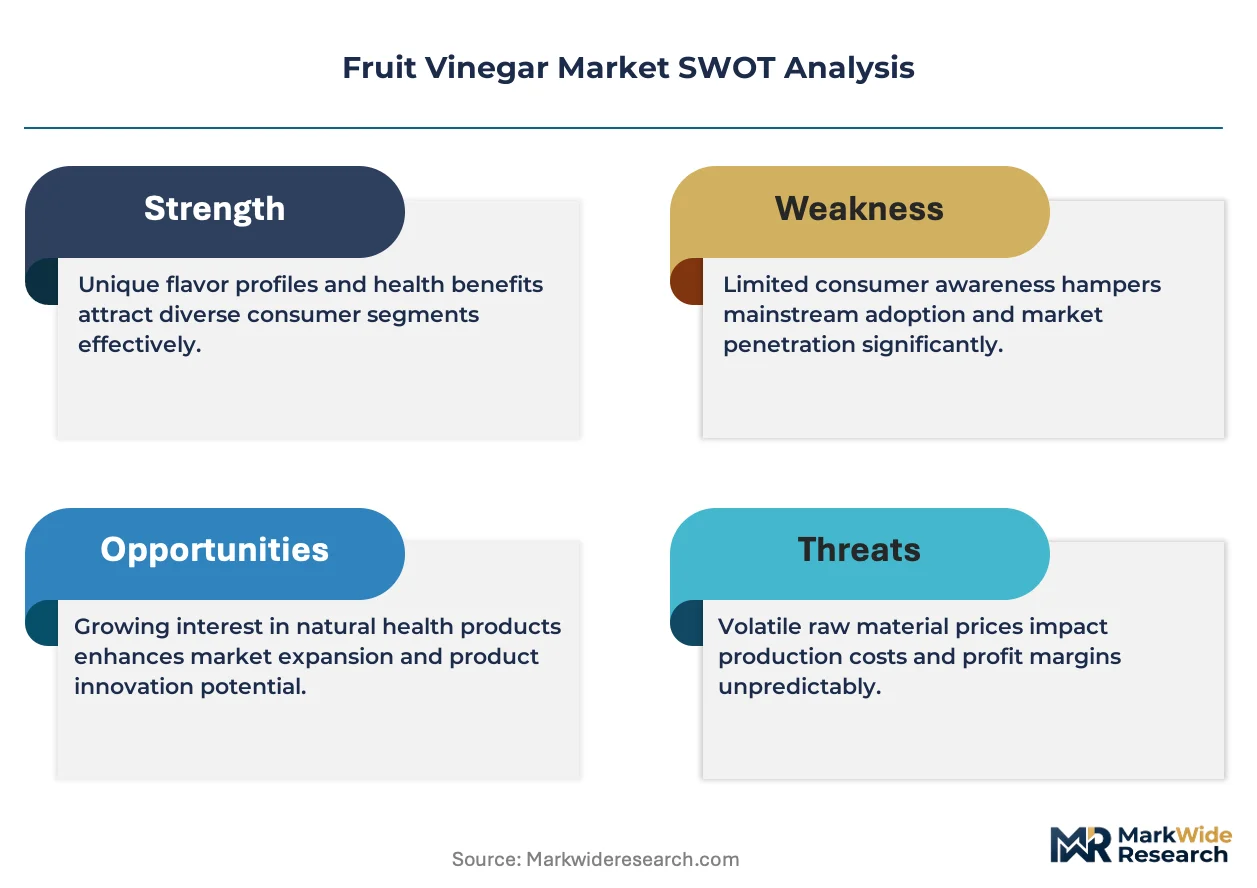
- Input Cost Volatility:Fruit substrate prices fluctuate with seasonal harvest yields and climate stress, compressing margin predictability for batch producers.
- Supply Concentration Risk:Premium aged balsamic output depends on concentrated Italian terroir, creating geographic vulnerability to regional weather shocks.
- Substitution Threat:Grain-derived and synthetic acetic acid alternatives compete on cost in industrial food manufacturing applications.
Strategic Opportunities
- Beverage Application Expansion:Drinking vinegars and shrubs are gaining traction in specialty retail channels, opening new consumption occasions beyond culinary use.
- EU Green Deal Alignment:Renewable energy mandates in fermentation facilities create first-mover advantage for producers securing carbon-neutral certification.
- Rice-Fruit Hybrid Formulations:Technology convergence between traditional fruit fermentation and rice vinegar processing is enabling novel product development for Asian market entry.
Industry Challenges
- Acetobacter Cultivation Expertise:Skilled microbiologists capable of managing double-fermentation consistency remain scarce relative to facility expansion timelines.
- USDA Organic Certification Timelines:Multi-year conversion requirements for orchards delay organic product launches and tie up working capital.
- Cold-Chain Reconfiguration:Legacy refrigeration infrastructure requires capital-intensive retrofitting to comply with ambient processing mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fruit Vinegar Market |
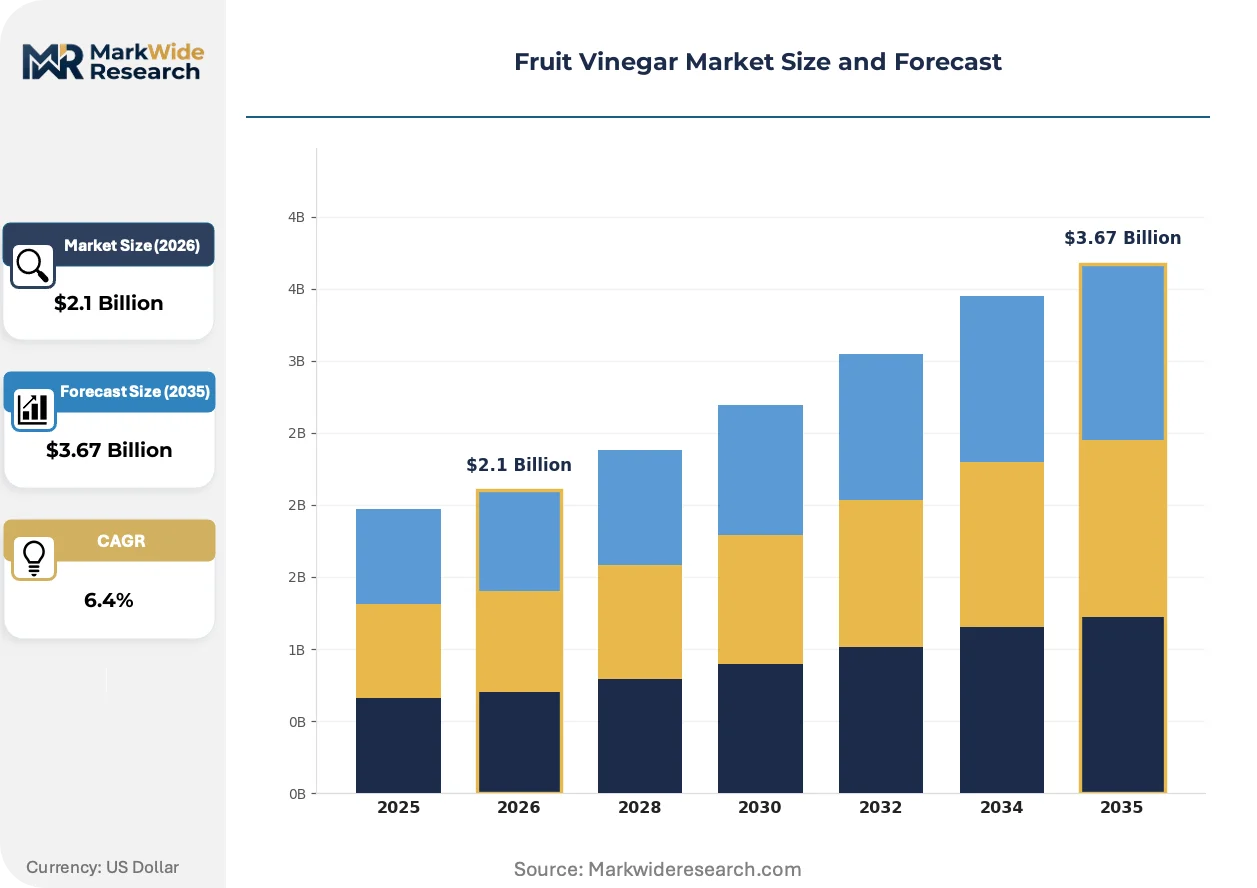
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple, Grape, Balsamic, Coconut Application: Food Preservation, Salad Dressing, Marinades, Beverages Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Health Stores End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Australian Vinegar, ACETUM SRL, Bragg Live Food Products, Nature's Truth, Fleischmann's Vinegar Company, Mizkan Group, Acetificio Marcello De Nigris, Dabur India, Vitacost, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fruit Vinegar Market Shifts & Advancements
Ambient fermentation systems are displacing conventional refrigerated processing, while regulatory pressure on synthetic inputs and shifting procurement patterns are compressing traditional supply chain configurations.
Continuous-flow fermentation technology is decentralizing production economics by enabling smaller-batch, distributed facility models. Mid-sized producers in Spain and Portugal are adopting skid-mounted systems at accelerating pace. This technology is decentralizing geographic concentration away from historic Modena-centric supply.
The EU F-Gas Regulation is mandating synthetic refrigerant phase-out across food processing facilities. Industrial consequence includes accelerated capital redeployment toward passive cooling and underground cellaring infrastructure. Italian balsamic producers with heritage aging stockpiles are responding by emphasizing traditional ambient methods as market differentiation.
Direct-to-foodservice procurement is bypassing traditional wholesale intermediaries in North American and European markets. Specialty retailers and restaurant groups are establishing captive supply relationships with named-origin producers. This pattern is most visible in California's farm-to-table restaurant networks and France's bistronomy sector.
Fruit Vinegar Market Segmentation
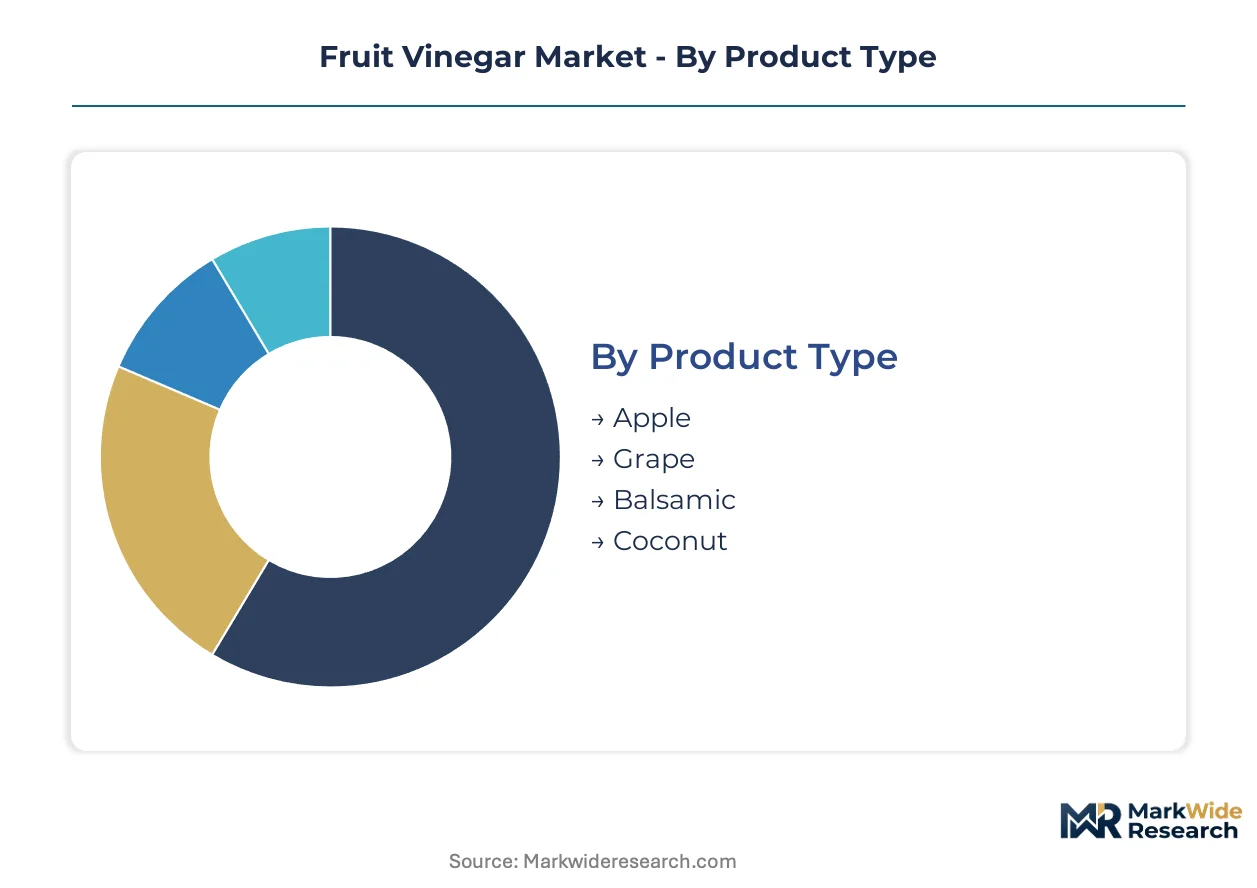
Fruit vinegar producers calibrate formulation chemistry and channel economics against distinct use occasions, from industrial batch processing to single-serve wellness consumption. Segmentation discipline separates commodity acetic acid suppliers from heritage-origin premium extractors commanding shelf placement in consolidated retail.
Product Type:
Standalone vinegar categories dominate pantry purchases, while embedded formulations serve as functional ingredients within compound food systems.
- Apple:Achieves four to six percent acidity through double fermentation of pressed cider must, with raw-unfiltered variants commanding wellness positioning in German and French household routines. Demand concentrates in North American organic retail channels where daily health regimens drive repeat purchase frequency.
- Balsamic:Requires minimum twelve-year aging in wooden casks under Modena and Reggio Emilia protected designation protocols, concentrating premium export value in Italian terroir. Supply vulnerability to regional weather shocks constrains volume scalability despite heritage pricing power.
- Grape:Derived from wine must fermentation, serving industrial food manufacturing as cost-competitive acidity regulators.
- Coconut:Emerging from Southeast Asian sap fermentation, gaining traction in specialty health stores as low-glycemic alternatives.
Volume placements concentrate in Apple; the faster expansion belongs to Balsamic.
Application:
Cost-tier stratification separates bulk industrial procurement from premium-positioned direct consumption formats.
- Beverages:Drinking vinegars and shrubs achieve four to six percent dilution for ready-to-drink positioning, with specialty retail channels in California farm-to-table networks and France's bistronomy sector capturing new consumption occasions. ACETUM SRL and Mizkan Group compete on formulation novelty for on-premise placement.
- Food Preservation:Industrial acetic acid applications leverage pH reduction for shelf-life extension in packaged goods manufacturing. Food manufacturers capture concentrated margin pools through bulk procurement contracts and private-label formulation partnerships.
- Salad Dressing:Blended emulsion formulations requiring emulsifier compatibility and flavor stability testing.
- Marinades:Protein tenderization applications with specific enzyme interaction requirements.
Procurement scale favors Food Preservation; Beverages climb the fastest as consumption occasion expansion outpaces traditional culinary use.
Distribution Channel:
Customer-type fragmentation drives channel-specific packaging and certification requirements across retail formats.
- Supermarkets:Consolidated shelf placement governed by retailer sustainability scorecards and EMA food-contact compliance documentation. Bragg Live Food Products anchors North American placement through raw-unfiltered organic positioning.
- Online Retailers:Direct-to-consumer logistics enabling subscription wellness routines with temperature-controlled shipping for live-culture preservation. German and French consumers expand pantry replenishment through digital channels.
- Specialty Stores:Named-origin curation emphasizing Modena heritage and aged stockpile provenance.
- Health Stores:Supplement-adjacent positioning with functional claims requiring FSSAI or FDA labeling compliance.
Foot traffic concentrates in Supermarkets; Online Retailers gain share fastest through subscription model penetration.
End User:
Supply concentration in Italian terroir creates geographic dependency for premium segments while industrial users diversify sourcing.
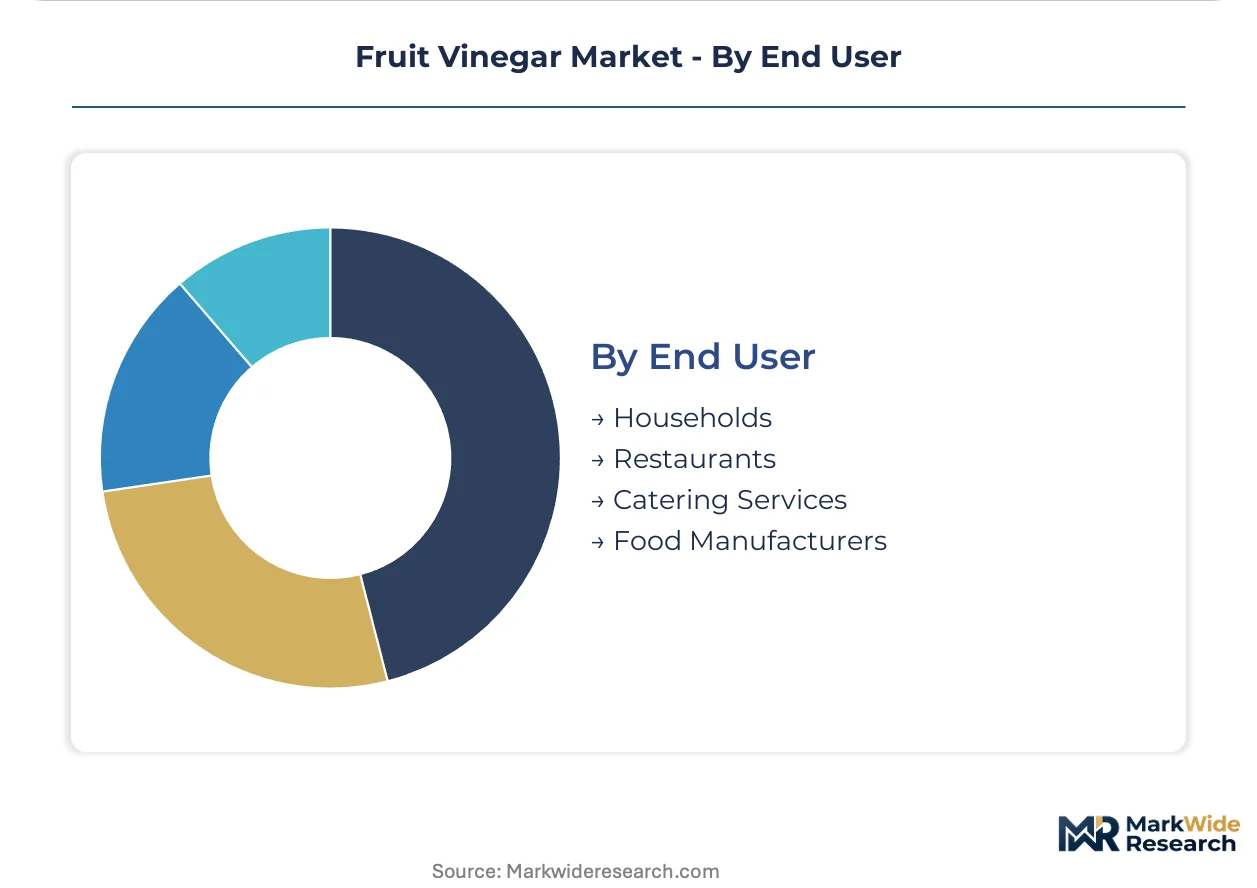
- Food Manufacturers:Batch-scale procurement with private-label formulation contracts and acetic acid purity specifications governed by EU REACH and FDA Good Manufacturing Practices. Input cost volatility from fruit substrate prices compresses margin predictability.
- Households:Single-serve and pantry-stock formats with wellness routine integration driving German and French market expansion. USDA organic certification timelines delay product launches for orchard-conversion suppliers.
- Restaurants:Direct-to-foodservice procurement bypassing wholesale intermediaries in California and France.
- Catering Services:Volume-contract pricing with consistency requirements across event-scale preparation.
Revenue concentration sits with Food Manufacturers; Households expand most quickly as daily health regimen adoption accelerates repeat purchase velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modena anchors global fruit vinegar production through its protected designation of origin for aged balsamic, with heritage stockpiles concentrated in wooden cask cellars across Emilia-Romagna. Regulatory pressure on synthetic refrigerants is reshaping fermentation facility investments across multiple jurisdictions.
Italy
Household demand for traditional balsamic vinegar drives premium pantry purchases in Modena and Reggio Emilia provinces. The EU F-Gas Regulation mandates synthetic refrigerant phase-out, pushing producers toward passive cooling infrastructure. Heritage aging stockpiles in wooden casks command export pricing power through protected designation protocols.
Germany
Daily wellness routines fuel apple cider vinegar consumption across German households seeking organic pantry staples. EMA food-contact guidelines harmonize acetic acid purity standards for cross-border distribution. Berlin-Brandenburg fermentation facilities are retrofitting cold-chain infrastructure to comply with ambient processing mandates.
United States
California farm-to-table restaurant networks establish direct-to-foodservice procurement relationships with named-origin producers. FDA Good Manufacturing Practices and USDA organic certification shape market access requirements. Pacific Northwest specialty retailers drive subscription-based drinking vinegar distribution through temperature-controlled logistics.
Japan
Rice-fruit hybrid formulations gain traction in Asian market expansion strategies from established fermentation houses. METI standards govern food-grade acetic acid specifications for domestic manufacturing. Kansai regional producers leverage technology convergence between traditional fruit and rice vinegar processing methods.
India
Urban household adoption of wellness-oriented pantry products accelerates apple vinegar purchases in metropolitan markets. FSSAI labeling mandates govern imported vinegar sales and domestic production compliance. Maharashtra-based food manufacturers negotiate bulk procurement contracts for industrial acetic acid applications.
Fruit Vinegar Market Competitive Landscape
The competitive structure tilts toward heritage-origin specialists with protected geographic designations commanding premium shelf placement. Consolidated retail channels favor established players with sustained organic certification and compliance documentation across multiple regulatory jurisdictions. Three archetypes dominate: traditional aged-balsamic extractors with terroir-based pricing power, organic wellness-positioned brands with raw-unfiltered differentiation, and diversified Asian conglomerates with rice-fruit hybrid technology. Capacity expansion into ambient fermentation infrastructure and strategic partnerships with direct-to-foodservice channels represent the dominant competitive moves.
Within the heritage-origin tier, ACETUM SRL exemplifies Modena-based protected designation dominance through geographic concentration of aged stockpiles. Bragg Live Food Products anchors North American organic positioning with raw-unfiltered wellness credentials. Mizkan Group occupies the technology-convergence archetype, representing rice-fruit hybrid formulation capabilities across Asian market development. These three entities collectively illustrate the geographic and technological segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Australian Vinegar |
| ACETUM SRL |
| Bragg Live Food Products |
| Nature's Truth |
| Fleischmann's Vinegar Company |
| Mizkan Group |
| Acetificio Marcello De Nigris |
| Dabur India |
| Vitacost |
| Others |
Supply & Pricing Matrix
Heritage-origin certification ladders in aged balsamic production create pronounced tier divergence, with Modena-protected designation commanding substantial premiums while commodity fruit vinegar competes on input cost efficiency. This bifurcation manifests in supply chain configurations: premium extractors anchor in Italian wooden cask cellars with multi-decade aging cycles, whereas industrial processors deploy continuous-flow fermentation across distributed Spanish and Portuguese facilities.
Pricing Analysis
Value-based pricing anchored in aging duration and geographic provenance dominates premium tiers, with Modena heritage stockpiles extracting rents from scarcity-enforced throughput limitations. Price differentiation separates twelve-year cask-aged balsamic from ambient-processed commodity vinegar through protected designation protocols and organic certification tiers. Pricing pressure stems from grain-derived acetic acid substitutes undercutting industrial food manufacturing applications. Food manufacturers exhibit highest price sensitivity due to bulk procurement scale, while specialty retailers absorb premiums for named-origin curation.
Supply Chain Analysis
Dual-sourcing requirements from North American and European food manufacturers mandate multi-supplier qualification across Italian heritage producers and distributed ambient fermentation facilities. Geographic supply concentration centers on Italy for aged balsamic, Spain and Portugal for continuous-flow systems, and Germany for organic apple cider processing. Raw material dependencies encompass wine must, pressed cider, and wooden cask inventory. Supply chain risk manifests in single-source vulnerability from concentrated Emilia-Romagna weather exposure. Distribution runs through direct-to-foodservice channels bypassing wholesale intermediaries in California and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints from twelve-year minimum aging protocols and concentrated Italian terroir prop pricing power for heritage-origin producers, creating durable margin pools for incumbent defenders.
For Market Incumbents: Hedge against substitution threats from synthetic acetic acid by deepening backward integration into orchard assets and captive must supply. Reinforce channel control through direct-to-foodservice partnerships with California farm-to-table networks and France's bistronomy sector. Prioritize certification investment in USDA organic and EU carbon-neutral fermentation credentials to defend shelf placement against retailer sustainability scorecards.
For New Entrants and Emerging Players: Begin with beverage application white space in drinking vinegars and shrubs, where consumption occasion expansion outpaces established culinary saturation. Target German and French household wellness routines through subscription-based online retail with temperature-controlled logistics for live-culture preservation. Deploy rice-fruit hybrid formulations as differentiated go-to-market angle for Asian market entry leveraging technology convergence.
For Investors and Strategic Acquirers: Re-rating potential sits with heritage-origin specialists given EU F-Gas Regulation acceleration of ambient fermentation capital redeployment. Long-term viability favors protected designation holders with existing wooden cask stockpiles and Modena geographic concentration. Monitor Acetobacter cultivation expertise scarcity as inflection signal for facility expansion bottlenecks and margin compression risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Ambient Fermentation Infrastructure | EU F-Gas Regulation mandates synthetic refrigerant phase-out, forcing capital redeployment toward passive cooling. |
| Direct-to-Foodservice Partnership | Bypassing wholesale intermediaries secures captive supply relationships with California and France restaurant networks. |
| Rice-Fruit Hybrid Development | Technology convergence enables Mizkan Group and competitors to penetrate Asian markets with novel formulations. |
| Organic Certification Investment | USDA multi-year orchard conversion timelines create defensive moats against commodity substitute competition. |
| Continuous-Flow System Deployment | Skid-mounted fermentation decentralizes production economics away from historic Modena-centric supply concentration. |
Research Methodology
Trade databases, EMA regulatory filings, and EU agricultural statistics formed the secondary backbone, cross-referenced against primary interviews with balsamic consortium representatives, fermentation facility engineers, and specialty retail category buyers. Bottom-up volume estimates from Italian protected designation registries reconciled with top-down expenditure analysis across German and French household wellness segments. Triangulation validated pricing tier divergence between heritage-origin and commodity processors.
Historical trendline analysis of Modena aging stockpile throughput and ambient fermentation capacity expansion informed projection modeling across the analysis window. Segmentation dimensions encompassed product type, application, distribution channel, and end-user archetype with regional regulatory cluster differentiation. CAGRs derived from weighted average of volume trajectories and value-per-unit expansion from certification premium capture. Forecast inputs incorporated EU Green Deal renewable energy mandates and FSSAI labeling compliance timelines for Indian market access.
Underlying measurement precision varies by segment; beverage application forecasts carry tighter precision than industrial food preservation projections due to established channel data availability. Forecasts reflect assumptions regarding sustained wellness routine adoption and synthetic refrigerant phase-out compliance schedules. Deviation in Acetobacter cultivation expertise availability or Emilia-Romagna weather shocks would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Smoothies Market
Beverages
South America Bottled Water Market
Beverages
Grape Juice Concentrate for Wine Making Market
Beverages
Semillon Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Europe Coconut Water Market
Beverages
United States and Australia Coconut Water Market
Beverages
Breakfast Drink Market
Beverages
India Bottled Water Market
Beverages
Probiotic Beverage Market
Beverages
Sarsaparilla Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
NFC JUICE Market
Beverages
Sports and Energy Drinks Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Powdered Beverages Market