
 Data Integration Market | 2026-2036
Data Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Data Integration Market Intelligence
Apache Iceberg table formats is realigning data lake economics by enabling time-travel queries and schema evolution without pipeline rewrites. IBM Corporation leverages mainframe connectivity expertise to anchor high-value government and banking accounts. Oracle Corporation competes through database-native integration that reduces extract-load latency for enterprise warehouses. SAP SE specializes in ERP-centric data federation, dominating manufacturing and supply chain verticals where S/4HANA footprints are entrenched.
Data integration encompasses the architectural discipline of combining data from disparate sources into unified, queryable structures through ETL pipelines, change data capture, virtualization layers, and API orchestration, typically operating at sub-second latency thresholds for operational use cases and batch windows for analytical workloads. Cloud deployment now leads solution distribution as enterprises abandon capital-intensive on-premise hardware, while ETL tools remain the largest solution category though data virtualization is expanding fastest among segments requiring real-time access without physical consolidation. Application demand clusters around business intelligence and customer analytics, where margin pools are deepest due to recurring licensing and professional services attach rates.
FDA 21 CFR Part 11 and HIPAA shape data integration requirements in US healthcare by mandating audit trails and access controls across clinical systems, while EU GDPR and the EU AI Act impose purpose-limitation and algorithmic transparency obligations on cross-border data flows. ISO 27001 and SOC 2 Type II certifications have become baseline prerequisites for vendor selection in regulated industries. Stakeholders must weigh sovereignty requirements against cloud elasticity when architecting multi-region replication strategies.
Market Dynamics
Cloud-native ETL pipelines are compressing the architectural lifecycle of enterprise data estates, forcing incumbents to abandon decade-old batch processing investments before full depreciation. This displacement is accelerating vendor consolidation as pure-play specialists struggle to fund multi-cloud compatibility roadmaps.
Growth Catalysts
- FDA 21 CFR Part 11:Audit trail mandates in US healthcare are driving replacement of shadow IT data pipelines with validated integration platforms that capture lineage automatically.
- Apache Iceberg table formats:Time-travel query capabilities are eliminating the need for pipeline rewrites during schema evolution, reducing maintenance overhead for data lakehouse architectures.
- Germany:Manufacturing conglomerates with entrenched SAP S/4HANA footprints are expanding data federation investments to unify ERP telemetry with IoT sensor streams.
Market Restraints
- Skilled data engineer scarcity:Pipeline orchestration expertise concentrates in San Francisco, London, and Bangalore, inflating implementation costs for enterprises outside these clusters.
- Legacy mainframe connectivity:IBM proprietary protocols create switching costs that lock banking and government accounts into incumbent vendor relationships.
- GDPR purpose limitation:Cross-border replication strategies face legal friction when US cloud regions process EU citizen data without explicit consent frameworks.
Strategic Opportunities
- India:RBI-mandated financial data localization is creating captive demand for domestic cloud integration infrastructure as foreign providers build in-country presence.
- Real-time CDC-ML convergence:Change data capture pipelines feeding operational machine learning models are opening new pricing tiers for sub-second latency guarantees.
- EU AI Act algorithmic transparency:Automated lineage documentation requirements are expanding addressable market for governance-integrated ETL platforms.
Industry Challenges
- Hybrid skill deficit:Practitioners who bridge legacy COBOL systems with Kubernetes-native pipelines command premium compensation that squeezes project margins.
- ISO 27001 certification timelines:Six-to-twelve month audit cycles delay vendor onboarding for healthcare and defense buyers with mandatory compliance gates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Integration Market |
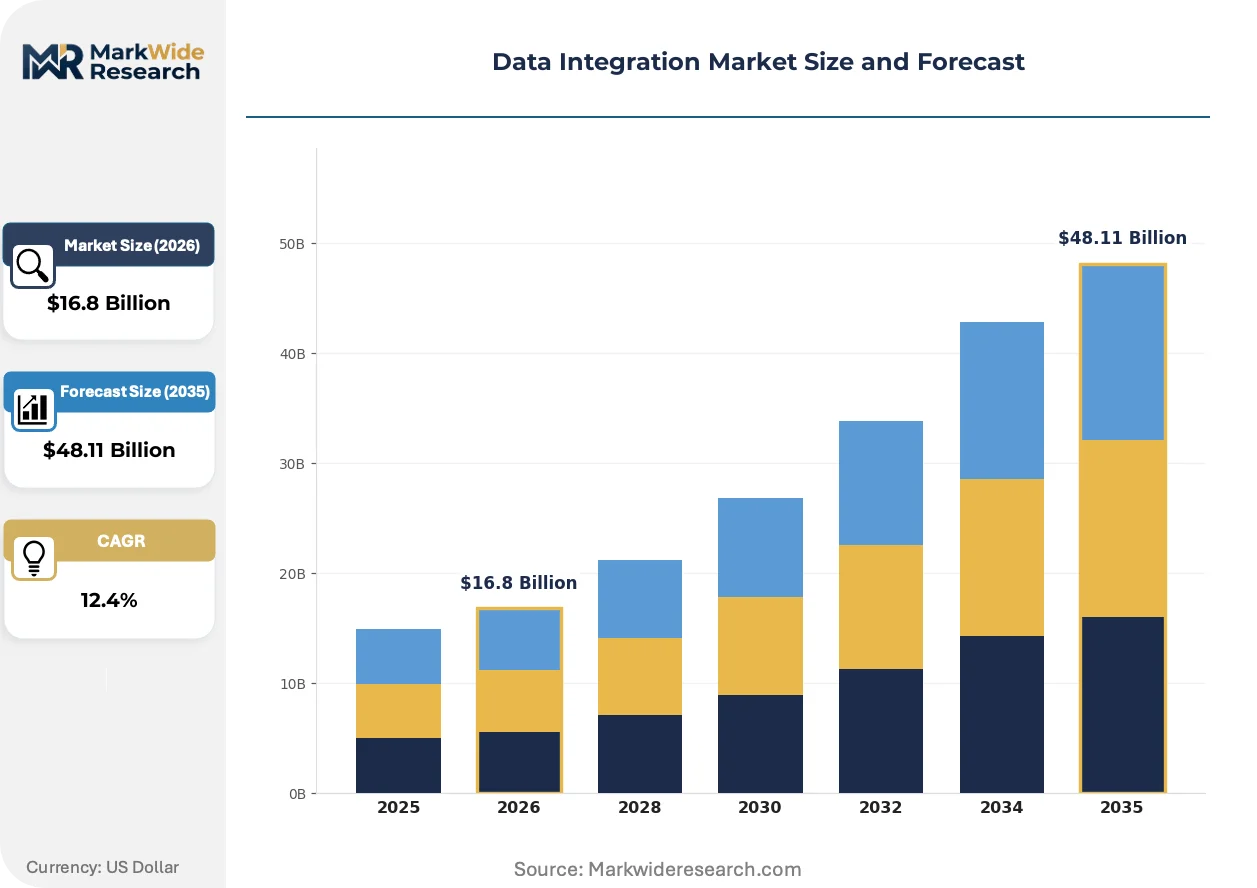
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $48.11 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud, Hybrid, Multi-Cloud, Edge Computing Solution/Offering: ETL Tools, Data Virtualization, Data Replication, Data Migration, Data Warehousing Application: Business Intelligence, Customer Analytics, Supply Chain Optimization, Fraud Detection, Risk Management End User: BFSI, Manufacturing, Telecom, Government, Education |
| Companies Covered | IBM Corporation, Oracle Corporation, SAP SE, Microsoft Corporation, Informatica Inc., TIBCO Software Inc., Denodo Technologies, Fivetran Inc., Talend S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Integration Market Strategic Shifts & Innovations
Data integration architecture is bifurcating into two competing design philosophies: physical consolidation through ETL versus logical federation through virtualization layers. This tension is reshaping vendor roadmaps and buyer evaluation criteria across regulated industries.
Apache Iceberg open table formats are unifying data lake and warehouse semantics through ACID transactions and hidden partitioning. Financial services firms in New York and London are adopting Iceberg-native query engines to collapse the Lambda architecture into single pipelines. This compression is eliminating the maintenance tax of maintaining separate batch and stream processing codebases.
EU AI Act algorithmic transparency obligations are mandating automated data lineage capture for high-risk AI systems. Healthcare providers deploying diagnostic algorithms must now demonstrate provenance from raw EHR extracts through model training inputs. German university hospitals are piloting integration platforms that embed governance metadata at ingestion to preempt regulatory audit requests.
Buyers are consolidating vendor relationships to reduce integration touchpoint complexity. Procurement teams at US insurers now require single-platform coverage for ETL, reverse ETL, and data quality rather than best-of-breed stitching. This concentration is favoring full-stack vendors with embedded catalog and observability modules over specialized point solutions.
Data Integration Market Segmentation
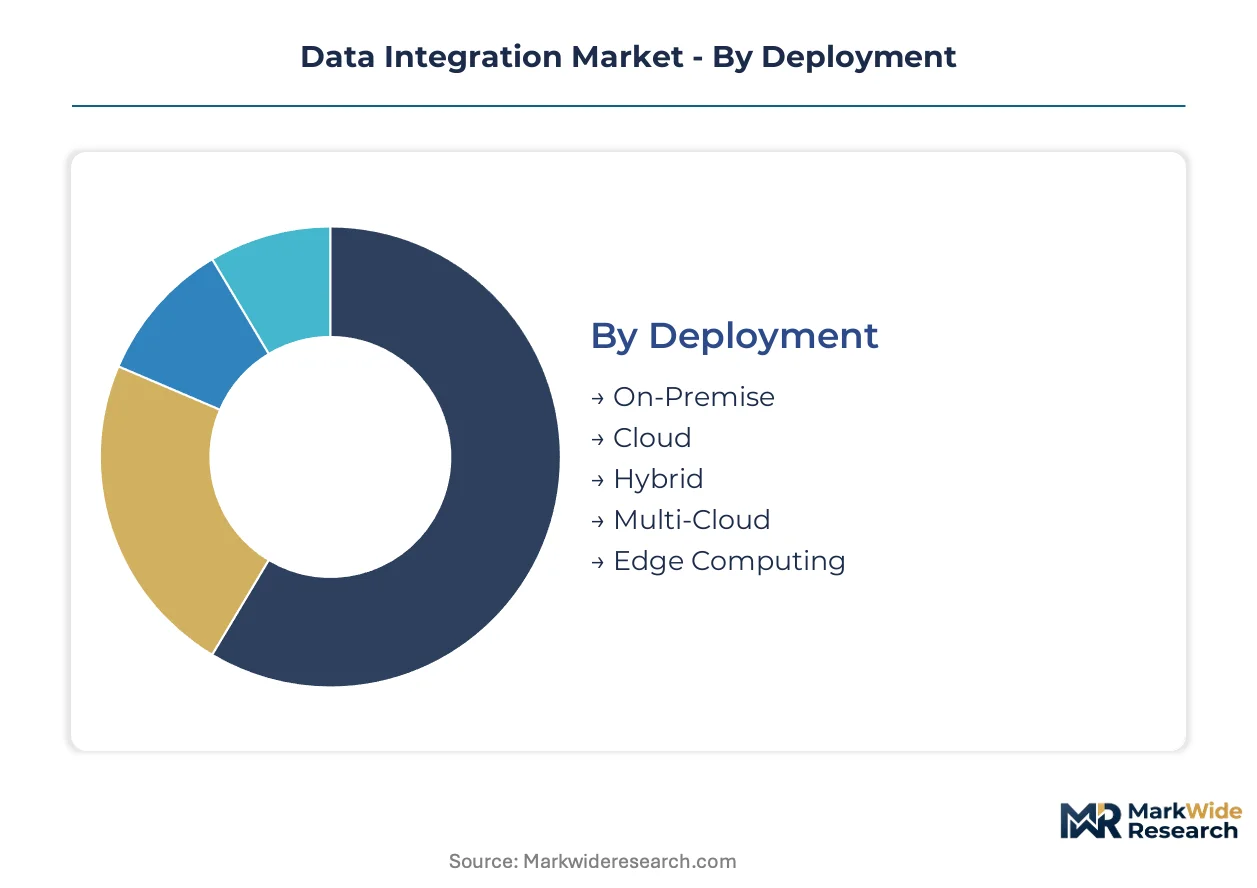
Segmentation in data integration reveals how capital allocation, latency requirements, and compliance obligations fragment buyer needs across deployment modes, solution architectures, and industry verticals. Procurement teams evaluate total cost of ownership differently when balancing cloud elasticity against data sovereignty mandates.
Deployment:
Capital intensity peaks with on-premise infrastructure, where hardware depreciation and facility costs dominate multi-year investment horizons.
- On-Premise:Dedicated server clusters and proprietary networking hardware deliver sub-millisecond latency for high-frequency trading floors. Financial services firms in Frankfurt and New York maintain these estates for regulatory auditability despite higher TCO.
- Cloud:Consumption-based pricing eliminates upfront CapEx while enabling elastic scaling for variable analytical workloads. Healthcare providers in the United States favor this model for HIPAA-compliant disaster recovery without secondary data center construction.
- Hybrid:Split architectures route sensitive operations on-premise while bursting non-critical analytics to public cloud. Manufacturing conglomerates with legacy SCADA systems adopt this pattern to preserve OT network isolation.
- Multi-Cloud:Abstraction layers prevent vendor lock-in across AWS, Azure, and GCP regions. Enterprises with distributed workforces deploy this architecture to optimize egress costs and latency.
- Edge Computing:Micro-data centers positioned near IoT sensors enable local preprocessing before cloud transmission. Autonomous vehicle fleets and smart factory deployments drive this segment.
On-premise deployments absorb the bulk of installed capacity; edge computing is expanding most quickly as IoT sensor density increases.
Solution/Offering:
Margin profiles diverge sharply between mature tooling categories and emerging governance-integrated platforms.
- ETL Tools:Batch extraction, transformation, and loading pipelines remain the workhorse for data warehouse population. Cloud-native ETL services from hyperscalers capture the majority of new contract value.
- Data Virtualization:Logical abstraction layers query distributed sources without physical consolidation, reducing storage redundancy. Real-time customer 360 applications in telecom drive this segment.
- Data Replication:Change data capture mechanisms maintain synchronized copies across operational and analytical systems. BFSI disaster recovery mandates sustain demand.
- Data Migration:One-time bulk transfer services support cloud repatriation and legacy system retirement. Government digital transformation programs generate project-based revenue.
- Data Warehousing:Columnar storage engines optimized for analytical query patterns. Separation of compute and storage architectures is reshaping vendor economics.
ETL tools command the largest revenue pool; data virtualization is gaining share fastest as buyers prioritize agility over physical consolidation.
Application:
Use case complexity determines professional services attach rates and recurring license pricing power.
- Business Intelligence:Dashboard and reporting pipelines aggregate structured data for executive decision-making. This application category generates the highest renewal rates due to embedded workflow dependencies.
- Customer Analytics:Behavioral segmentation and churn prediction models require real-time feature engineering. Retail and telecom verticals drive implementation velocity here.
- Supply Chain Optimization:Multi-enterprise data federation unifies ERP, logistics, and supplier systems. SAP-centric manufacturing networks in Germany represent concentrated demand.
- Fraud Detection:Sub-second pattern recognition across transaction streams demands specialized streaming architectures. Payment processors and insurers invest heavily here.
- Risk Management:Regulatory capital calculations and stress testing pipelines integrate market and counterparty data. Basel III compliance sustains BFSI spending.
Business intelligence absorbs the bulk of deployment hours; fraud detection is climbing the fastest as real-time ML pipelines mature.
End User:
Industry-specific compliance regimes create divergent vendor qualification requirements and sales cycle lengths.
- BFSI:Banking, financial services, and insurance institutions mandate SOC 2 Type II and ISO 27001 certifications. RBI data localization rules in India are reshaping supplier selection criteria.
- Manufacturing:Industrial IoT integration and ERP federation dominate procurement priorities. German automotive suppliers with SAP S/4HANA footprints represent a captive market segment.
- Telecom:Subscriber data platforms and network performance analytics drive volume. 5G rollout investments are expanding edge computing requirements.
- Government:FedRAMP and state-level security clearances restrict vendor eligibility. Census, tax, and benefits administration systems sustain long-term contracts.
- Education:Student information system integration and learning analytics adoption lag commercial sectors. Federal research grant compliance is accelerating modernization.
BFSI captures the bulk of vendor R&D investment; manufacturing is expanding most quickly as Industry 4.0 initiatives scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and India as enterprises modernize analytics infrastructure and replace legacy batch systems with cloud-native pipelines.
United States
Financial services firms in New York and healthcare systems nationwide drive platform investments. FDA 21 CFR Part 11 mandates audit trails for clinical data pipelines, forcing validated integration purchases. The San Francisco Bay Area hosts concentrated data engineering talent that commands premium implementation rates.
Germany
Manufacturing conglomerates with entrenched SAP S/4HANA footprints expand federation investments to unify ERP telemetry with IoT sensor streams. EU GDPR and the EU AI Act impose purpose-limitation obligations on cross-border data flows. Munich and Stuttgart anchor automotive supplier demand for supply chain optimization platforms.
India
RBI-mandated financial data localization creates captive demand for domestic cloud integration infrastructure. The central bank's strict data residency rules force foreign providers to build in-country presence. Bangalore and Hyderabad concentrate pipeline orchestration expertise that inflates project costs for enterprises elsewhere.
United Kingdom
London-based insurers and asset managers prioritize real-time fraud detection architectures with sub-second latency guarantees. FCA operational resilience requirements shape vendor selection criteria for critical data services. The Thames Valley corridor hosts concentrated demand from telecom subscriber data platforms.
Japan
Tokyo-headquartered conglomerates modernize mainframe connectivity for hybrid cloud analytics while preserving legacy system investments. METI industrial data sharing initiatives accelerate cross-enterprise federation pilots. Osaka manufacturing networks drive edge computing deployments for smart factory preprocessing.
Data Integration Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with full-stack vendors capturing consolidation benefits while point solutions face pricing pressure. The vendor base concentrates around three tiers: hyperscale cloud platforms, established enterprise software incumbents, and cloud-native specialists. Strategic archetypes include mainframe connectivity anchors, database-native integrators, and open-source lakehouse enablers. Dominant competitive moves span multi-cloud compatibility roadmaps and embedded governance module development.
Within the incumbent tier, IBM Corporation, Oracle Corporation, and SAP SE occupy positions defined by proprietary protocol lock-in and ERP-centric federation expertise. These entities exemplify how decades-old customer relationships create switching costs that resist displacement by cloud-native alternatives. IBM leverages mainframe connectivity anchors in government and banking accounts. Oracle competes through database-native integration reducing extract-load latency. SAP dominates manufacturing verticals where S/4HANA footprints are entrenched.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| SAP SE |
| Microsoft Corporation |
| Informatica Inc. |
| TIBCO Software Inc. |
| Denodo Technologies |
| Fivetran Inc. |
| Talend S.A. |
| Others |
Cost & Logistics Intelligence
Pipeline orchestration expertise concentrates in Bangalore, London, and San Francisco, and these labor-cost differentials widen pricing-tier spreads between premium managed services and self-service SaaS tiers. Cloud-native ETL vendors price implementation support at a premium in talent-scarce markets while offering lower-touch subscriptions where engineering density permits.
Pricing Analysis
Volume concentrates in standardized SaaS subscriptions while margin pools in professional services and custom implementation. The dominant pricing structure runs on consumption-based SaaS tiers with per-pipeline or per-connector metering. Price differentiation hinges on SOC 2 Type II certification status and real-time latency guarantees for operational workloads. Cost compression in mid-market self-service tiers is intensifying because hyperscaler-native alternatives commoditize basic ETL functionality. Healthcare and defense buyers show the least price sensitivity due to mandatory compliance gates, while retail and education segments negotiate aggressively on per-seat costs.
Supply Chain Analysis
Cloud compute supply rests on hyperscaler infrastructure in the United States, Ireland, and Singapore, with regional data center expansion accelerating in India and Germany. Raw material dependencies include specialized silicon for edge inference, submarine cable capacity for intercontinental replication, and renewable energy contracts for carbon-neutral hosting commitments. Single-source vulnerability concentrates in mainframe connectivity protocols where IBM proprietary stacks lock banking and government accounts. Distribution runs through direct enterprise sales teams for large accounts and self-service marketplaces for mid-market adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native ETL pipelines are displacing legacy batch processing architectures, compressing the architectural lifecycle and forcing incumbents to abandon decade-old investments before full depreciation.
For Market Incumbents: Cement mainframe connectivity anchors in government and banking accounts through FedRAMP and state-level security clearance investments. Deepen embedded governance modules to preempt EU AI Act algorithmic transparency mandates. Acquire cloud-native CDC specialists to fill real-time ML pipeline gaps before pure-plays capture operational ML pricing tiers. For New Entrants and Emerging Players: Begin with RBI-compliant data localization infrastructure in India, where captive demand outpaces domestic supply. Target German automotive suppliers with SAP S/4HANA federation tools that unify ERP telemetry with IoT sensor streams. Lead with open-source Apache Iceberg-native positioning to bypass incumbent sales cycles in financial services. For Investors and Strategic Acquirers: The window for entry favors governance-integrated platforms with automated lineage documentation and pre-built compliance templates. Long-term viability centers on vendors that collapse Lambda architectures into single pipelines through open table formats. Watch for inflection when EU AI Act enforcement triggers replacement cycles for shadow IT data pipelines in healthcare.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidating ETL, reverse ETL, and data quality into single platforms reduces procurement complexity for US insurers. |
| Geographic Expansion | Building India data centers satisfies RBI localization mandates and captures captive financial services demand. |
| Strategic Partnership | Embedding Apache Iceberg support collapses batch and stream processing codebases for New York banks. |
| Acquisition of Specialist Firm | Buying CDC-ML convergence vendors opens sub-second latency pricing tiers for operational machine learning. |
| Product Launch | Releasing governance-embedded ETL platforms preempts EU AI Act audit requests from German hospitals. |
Research Approach
Document review covered hyperscaler capex disclosures, SEC filings, and regulatory guidance from FDA and RBI, complemented by interviews with data platform engineers, IT procurement officers, and compliance leads at financial services and healthcare enterprises. Secondary validation drew from GPO contracts, hospital procurement databases, and customs records of data center equipment imports. Bottom-up pipeline counts and top-down enterprise software spending estimates were triangulated to anchor market sizing.
Cross-referencing historical deployment velocity against panel input from integration architects shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment mode, solution architecture, application complexity, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and infrastructure replacement cycles. Industry-specific forecast inputs incorporated SAP S/4HANA migration timelines and 5G edge computing rollout schedules.
Underlying measurement precision varies by segment; cloud and hybrid deployment estimates carry tighter precision than edge computing projections where IoT sensor density assumptions remain speculative. Forecasts reflect assumptions about regulatory enforcement intensity and hyperscaler pricing discipline. A small set of triggers—EU AI Act audit frequency, RBI data localization enforcement, and mainframe modernization budget releases—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Agriculture Software Market
Digital Solutions
IT Service Management Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Digital Manufacturing Software Market
Digital Solutions
Webrtc Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Online Home Service Market
Digital Solutions
Turkey ICT Market
Digital Solutions
Social Networking App Market
Digital Solutions
Japan E-Invoicing Market
Digital Solutions
Europe Smart Card Market
Digital Solutions
IT Operations Management Market
Digital Solutions
Insight As a Service Application Market
Digital Solutions
Global Correspondence Management System Market
Digital Solutions
Asia-Pacific Digital Marketing Software Market
Digital Solutions
India PLM Market