
 Cloud E-Signature Tools Market | 2026-2036
Cloud E-Signature Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud E-Signature Tools Market Insights
Platform bundling of authentication, workflow automation, and document management into unified suites is rebalancing buyer evaluation criteria away from point solutions. DocuSign Inc. leverages its early-mover scale across real estate and legal verticals to sustain recurring revenue density. Adobe Inc. anchors its competitive stance through deep Creative Cloud and Acrobat integration that controls document lifecycles end-to-end. Zoho Corporation competes on price-accessibility for SMEs across emerging markets, while OneSpan Inc. specializes in high-assurance financial-grade signatures that occupy regulated banking channels.
Cloud e-signature tools are software platforms that cryptographically bind signatory identity to electronic documents using public-key infrastructure, timestamping, and audit trails, with primary commercial purpose of replacing wet-ink execution in contract workflows. Public cloud deployment leads volume due to low friction onboarding, though hybrid cloud configurations are gaining traction among enterprises with data residency requirements. The SME end-user segment represents the fastest expansion pool as self-service onboarding and per-seat pricing lower barriers, while workflow automation services capture disproportionate margin as vendors layer value beyond basic signature capture.
The EU eIDAS framework, the US ESIGN Act, and state-level remote online notarization statutes collectively shape product certification requirements and cross-border enforceability standards that vendors must satisfy for market access. The FDA's 21 CFR Part 11 guidelines for electronic records in pharmaceutical trials further segment the addressable market by compliance tier. Stakeholders must monitor whether emerging AI-generated document fraud prompts regulators to mandate stronger biometric binding or qualified trust service provider accreditation as a baseline requirement.
Market Dynamics
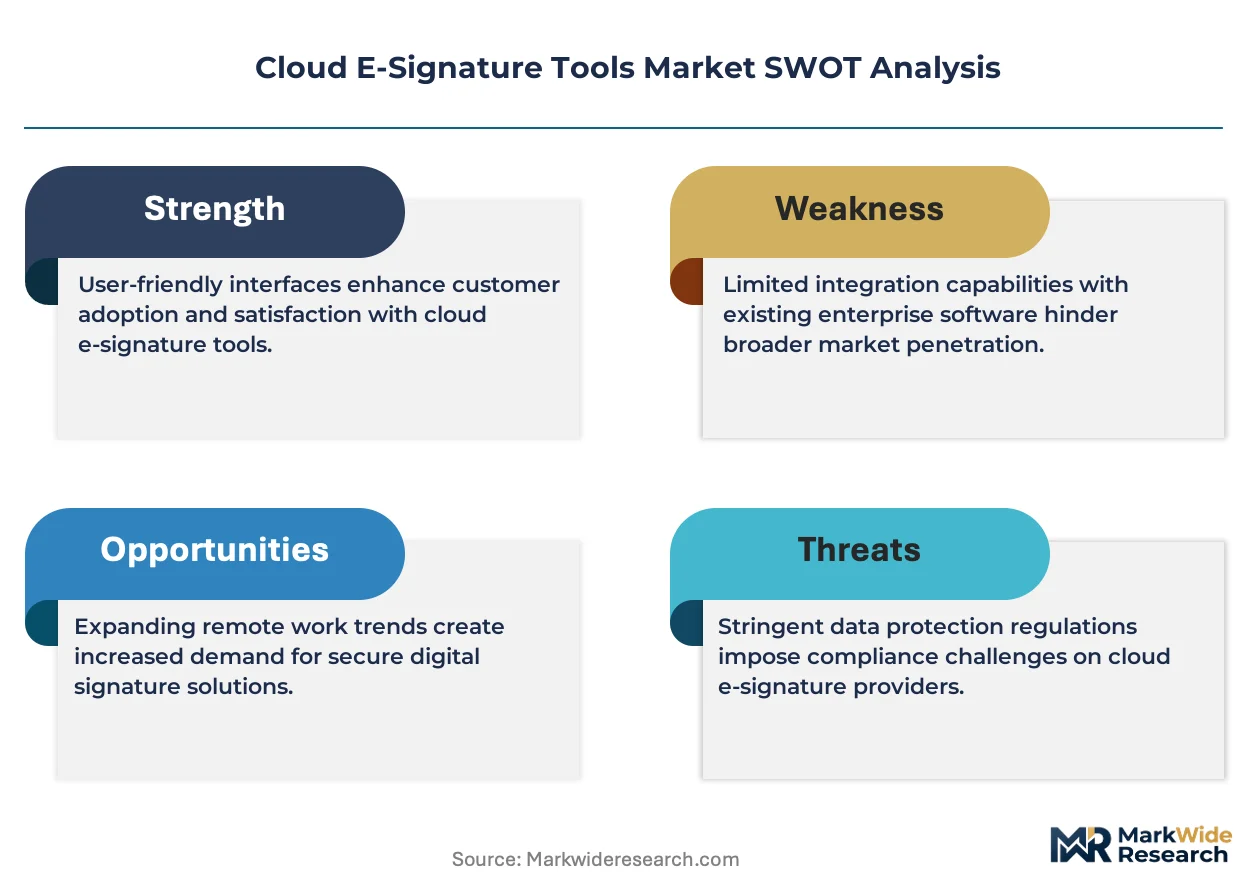
Platform consolidation is compressing vendor margins as authentication, workflow automation, and document management fuse into unified suites, forcing point-solution providers toward niche specialization or acquisition.
Growth Catalysts
- Remote Online Notarization Statutes:State-level RON laws across the United States have normalized digital closing workflows in real estate and financial services, removing legal friction for cloud-based execution.
- Financial Services:Banks and insurers are mandating cryptographically bound audit trails for compliance, accelerating procurement of qualified electronic signature infrastructure.
- eIDAS Tiered Framework:The EU's qualified signature tier creates procurement standards that favor vendors with trust service provider accreditation, reshaping competitive access across member states.
Market Restraints
- Data Residency Requirements:Enterprises in Germany, France, and Switzerland demand hybrid cloud configurations, increasing infrastructure costs and complicating vendor architectures.
- Biometric Binding Uncertainty:Emerging AI-generated document fraud threatens to invalidate basic signature capture methods, potentially forcing costly technology refreshes.
- Cross-Border Enforceability Gaps:Divergent recognition standards between the US ESIGN Act, EU eIDAS, and Asian electronic transaction laws create legal friction for multinational contract execution.
Strategic Opportunities
- India SME Penetration:Self-service onboarding and per-seat pricing models remain underdeveloped among Indian small and medium enterprises, creating whitespace for accessible platforms.
- Pharmaceutical Trials:FDA 21 CFR Part 11 compliance requirements for electronic records in clinical research segment the addressable market by certification tier, favoring specialized vendors.
- AI-Biometric Convergence:Liveness detection fused with behavioral biometrics offers a pathway to stronger non-repudiation guarantees that regulators may eventually mandate as baseline.
Industry Challenges
- PKI Talent Scarcity:Shortages of cryptographers and trust infrastructure engineers constrain vendor ability to maintain and audit public-key certificate hierarchies at scale.
- Legacy System Integration:Enterprise content management and customer relationship platforms built on pre-cloud architectures resist API-native signature embedding, extending sales cycles.
- Qualified Trust Service Accreditation Timelines:EU member state supervisory body certification processes for qualified signature creation devices average 18-24 months, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud E-Signature Tools Market |
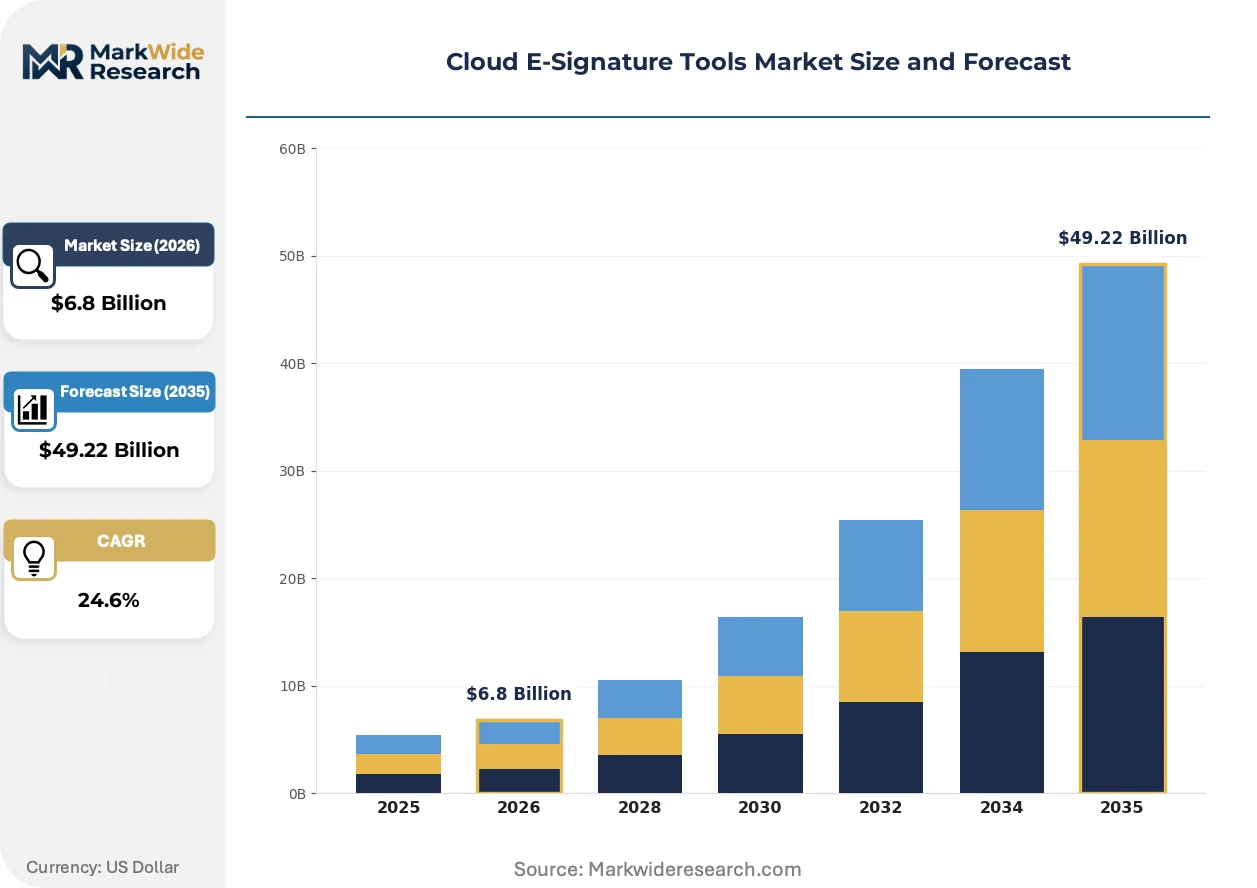
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $49.22 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: SMEs, Enterprises, Government, Education Service Type: Authentication, Authorization, Document Management, Workflow Automation Integration Level: API Integration, Webhooks, Third-Party Integrations, Native Applications |
| Companies Covered | DocuSign Inc., Adobe Inc., Zoho Corporation, PandaDoc Inc., OneSpan Inc., SignEasy Inc., GlobalSign, Entrust, Thales S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud E-Signature Tools Market Trends and Innovations
Artificial intelligence is infiltrating identity verification layers, compressing the gap between basic electronic signatures and qualified trust-grade assurance while forcing vendors to re-architect authentication pipelines.
Blockchain-based timestamping and immutable audit logging is electrifying high-value contract workflows in capital markets and international trade finance. Investment banks and commodity traders are piloting distributed ledger anchoring for derivatives documentation and letters of credit. This architecture is electrifying vendor roadmaps toward decentralized identity models that reduce reliance on centralized certificate authorities.
The EU AI Act's risk classification framework for biometric identification systems is tightening compliance obligations for facial recognition and voiceprint-based signature binding. Vendors must now document algorithmic transparency and human oversight protocols to maintain qualified signature status. Financial institutions in Germany and the Netherlands are front-running these requirements by procuring only AI Act-conformant identity verification modules.
Buyer preference is rotating toward consumption-based pricing tied to document volume rather than per-seat subscriptions, compressing vendor revenue predictability. Mid-market legal departments and property management firms are leading this shift, negotiating tiered commit structures with overage penalties. This pattern is most visible in the United States, where procurement teams increasingly benchmark total cost against wet-ink process replacement rather than software feature comparisons.
Cloud E-Signature Tools Market Segmentation
Cloud e-signature procurement diverges sharply by infrastructure control requirements, organizational scale, and workflow complexity. Buyers evaluate segments through the lens of compliance tier, integration burden, and total cost of ownership rather than feature checklists alone.
Deployment:
Cost tier separates buyers most cleanly in this category, with infrastructure overhead and data sovereignty obligations driving divergent procurement paths.
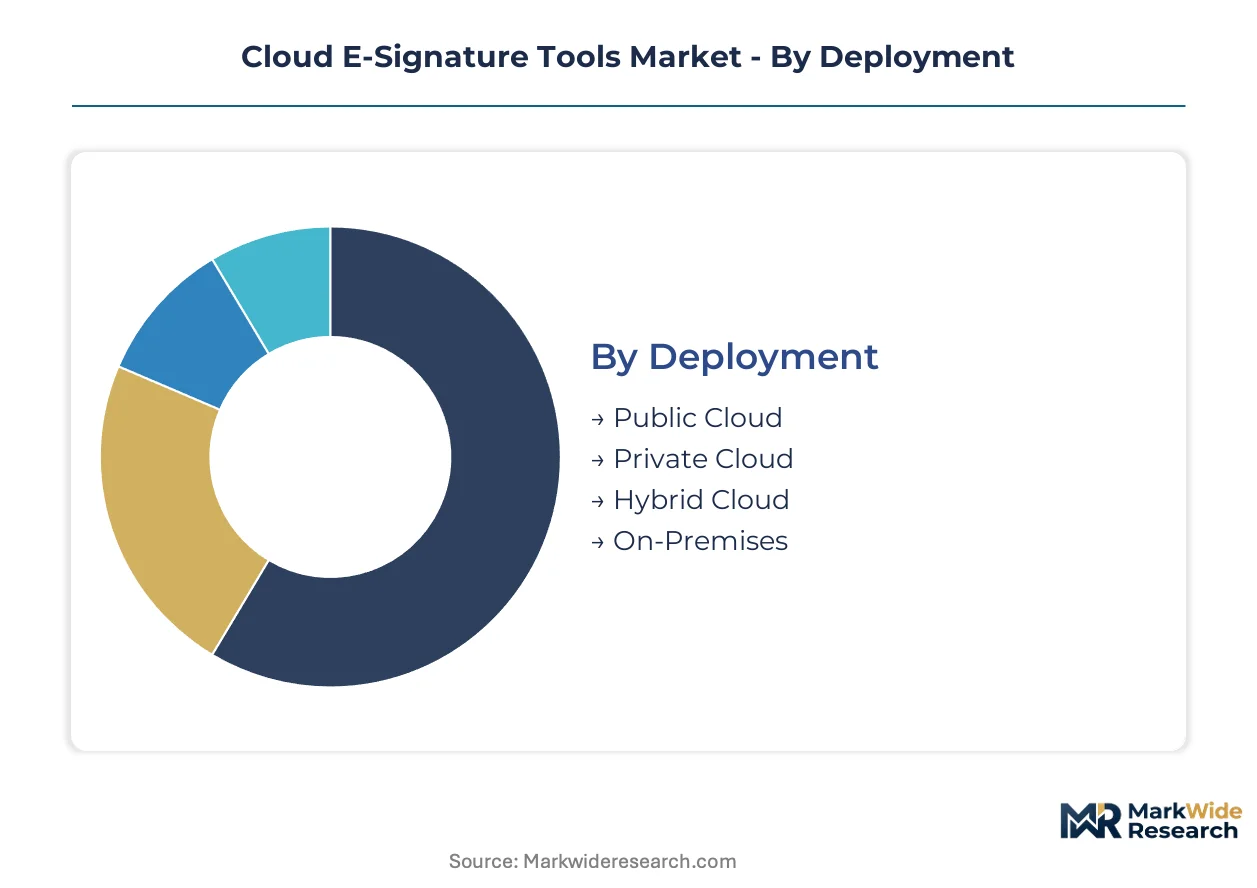
- Public Cloud:Multi-tenant architectures with shared certificate infrastructure and elastic compute scaling. United States real estate closings and mid-market legal departments concentrate here, drawn by per-seat pricing and instant provisioning without capital expenditure.
- Hybrid Cloud:Split architectures retaining signature creation keys on-premises while routing audit trails through cloud aggregation layers. German and Swiss financial institutions mandate this configuration for GDPR and FINMA compliance, accepting 40-60% higher total cost of ownership for jurisdictional control.
- Private Cloud:Dedicated tenant isolation with single-organization certificate hierarchies and custom trust anchor configuration. Defense contractors and EU qualified trust service providers occupy this tier where supervisory body audit requirements exceed public cloud certification scope.
- On-Premises:Fully air-gapped deployments with hardware security modules managing private key material. Intelligence agencies and critical infrastructure operators in France and the Netherlands procure here despite 18-24 month implementation timelines.
Public Cloud leads volumes today; Hybrid Cloud is gaining share fastest as data residency mandates proliferate across European member states.
End User:
Customer type determines pricing elasticity and sales cycle length more than any other segmentation dimension in this market.
- SMEs:Organizations under 500 employees purchasing through self-service portals with credit-card onboarding and standardized templates. Indian professional services firms and United States property management companies represent the steepest expansion trajectory as per-seat models collapse entry barriers.
- Enterprises:Multi-divisional organizations negotiating master service agreements with custom SLA terms and dedicated customer success coverage. Pharmaceutical manufacturers pursuing FDA 21 CFR Part 11 validation and investment banks requiring immutable audit trails anchor procurement here.
- Government:Federal, state, and municipal agencies with FedRAMP or equivalent security accreditation requirements. United States state motor vehicle departments and county recorder offices drive volume as remote online notarization statutes expand jurisdiction by jurisdiction.
- Education:Universities and K-12 districts with FERPA compliance obligations and semester-bound procurement cycles. Research institutions managing grant-funded clinical trials segment further by electronic record retention requirements.
SMEs lead volumes today; Enterprises are expanding most quickly as board-level digital transformation mandates accelerate qualified signature procurement.
Service Type:
Application focus distinguishes vendor margin profiles, with basic capture commoditizing while orchestration layers retain pricing power.
- Workflow Automation:Conditional routing, parallel signature sequencing, and exception handling across multi-stakeholder document lifecycles. United States mortgage originators and insurance claims processors concentrate demand here, paying premium pricing for straight-through processing metrics.
- Authentication:Identity verification through government ID matching, biometric liveness detection, and knowledge-based challenge-response. EU financial institutions front-running AI Act compliance requirements are procuring only algorithmically transparent modules with documented human oversight protocols.
- Document Management:Version control, retention scheduling, and legal hold integration with enterprise content repositories. Law firms and healthcare systems in Germany and France require this for professional liability and patient record mandates.
- Authorization:Role-based signing permissions and delegated execution authority with immutable delegation chains. Corporate treasury functions and board secretaries in Switzerland and the Netherlands specify this for internal control documentation.
Authentication leads volumes today; Workflow Automation is climbing the fastest as buyers benchmark total cost against wet-ink process replacement rather than software feature comparisons.
Integration Level:
Technical maturity of buyer IT organizations creates the primary fault line in this segmentation, determining implementation complexity and time-to-value.
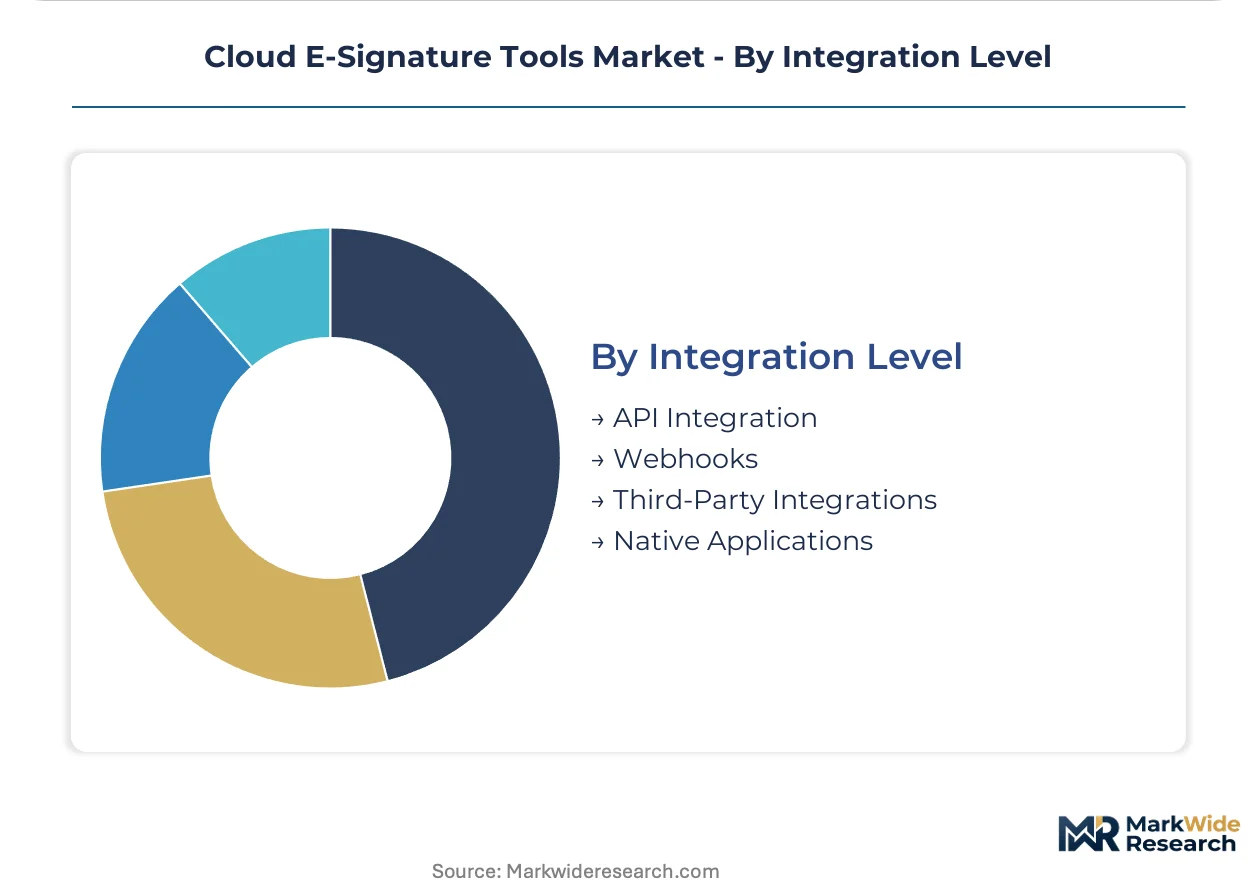
- API Integration:REST and SOAP endpoints enabling embedded signature capture within custom applications. Technology companies and fintech startups in the United States and India dominate this segment, demanding sub-200-millisecond response times for user experience parity.
- Third-Party Integrations:Pre-built connectors for Salesforce, Microsoft 365, Google Workspace, and vertical-specific platforms. Mid-market professional services firms across all geographies default here to minimize development resource allocation.
- Webhooks:Event-driven callbacks triggering downstream system updates upon signature completion. ERP-dependent manufacturers and supply chain operators in Germany and Japan favor this pattern for purchase order and invoice automation.
- Native Applications:Standalone mobile and desktop clients without external system dependencies. Field sales organizations and solo practitioners in emerging markets rely on these where integration infrastructure remains immature.
Third-Party Integrations lead volumes today; API Integration is expanding most quickly as product-led growth companies prioritize embedded workflow experiences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud e-signature tools originated in United States technology corridors during the early 2000s, with Silicon Valley startups pioneering SaaS delivery models that displaced on-premises document execution systems. This foundational architecture now diffuses across regulatory jurisdictions with varying compliance stringency.
United States
State-level remote online notarization statutes in Florida, Texas, and Virginia have normalized digital real estate closings. The ESIGN Act provides federal enforceability standards. Austin and Dallas-Fort Worth clusters host mortgage technology vendors integrating qualified signature workflows for title insurance processors.
Germany
FINMA and BaFin regulations mandate hybrid cloud configurations for banking signatures. The eIDAS qualified trust service framework creates procurement barriers favoring accredited providers. Frankfurt's financial services concentration drives demand for hardware security module-backed execution environments.
India
IT Act 2000 amendments recognize electronic signatures, though qualified tier adoption lags. RBI guidelines for digital lending documentation accelerate bank procurement. Bengaluru and Mumbai professional services firms represent underpenetrated SME expansion targets for self-service platforms.
United Kingdom
Post-Brexit eIDAS alignment maintains qualified signature recognition for EU contract enforceability. The Electronic Communications Act underpins commercial adoption. London's legal services corridor concentrates demand for document management-integrated execution suites.
Switzerland
FINMA circulars on operational resilience shape banking procurement standards for high-assurance signatures. Data residency requirements exceed EU baseline. Zurich and Geneva private banking centers specify immutable audit trails for wealth management documentation.
Cloud E-Signature Tools Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and integration depth, with qualified trust service accreditation creating a structural wedge. The vendor base stratifies between horizontal platform consolidators and vertical specialists. Three archetypes dominate: early-mover scale platforms, creative suite integrators, and financial-grade assurance specialists. Competitive moves concentrate on workflow automation bundling and trust infrastructure acquisition.
Within the early-mover tier, DocuSign Inc. and Adobe Inc. exemplify platform consolidation strategies, while OneSpan Inc. occupies a position among financial-grade specialists. DocuSign's real estate and legal vertical concentration represents recurring revenue density archetypes. Adobe's document lifecycle control through Creative Cloud integration exemplifies suite-based competitive positioning. OneSpan's regulated banking channel focus illustrates high-assurance specialization.
| Leading Market Players |
|---|
| DocuSign Inc. |
| Adobe Inc. |
| Zoho Corporation |
| PandaDoc Inc. |
| OneSpan Inc. |
| SignEasy Inc. |
| GlobalSign |
| Entrust |
| Thales S.A. |
| Others |
Pricing and Supply Chain Analysis
Hardware security module procurement costs in Germany and Switzerland cascade through hybrid cloud deployment tiers, compressing margins for qualified signature infrastructure while public cloud vendors in the United States absorb certificate authority overhead through multi-tenant scale economics.
Pricing Analysis
Per-seat subscription models with volume-tiered discounts dominate the United States mid-market, while qualified trust service accreditation in the EU commands premium pricing for hardware-backed execution environments. Price differentiation rests on certification grade and data residency compliance, with German financial institutions accepting substantially higher total cost of ownership for jurisdictional control. Cost compression in basic electronic signature tiers is intensifying because self-service onboarding commoditizes capture functionality. SMEs in India and United States property management firms exhibit the sharpest price sensitivity, whereas Swiss private banks and pharmaceutical manufacturers pursuing FDA validation show minimal elasticity.
Supply Chain Analysis
Dual-sourcing requirements for hardware security modules and qualified timestamping services are mandating multi-vendor qualification among EU financial institutions and defense contractors. Supply concentrates in the United States for cloud infrastructure and certificate authority services, Germany for HSM manufacturing and trust service provider accreditation, and India for software development talent. The vendor ecosystem draws from cryptographic chipset fabrication, public-key infrastructure software stacks, and biometric sensor modules. Single-source vulnerability in qualified trust service provider accreditation creates procurement bottlenecks, with EU member state supervisory body certification timelines extending 18-24 months. Distribution runs through direct enterprise sales for regulated verticals and self-service portals for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cloud E-Signature Tools Market functions as a geographic-arbitrage play where vendors can exploit the cost differential between United States public cloud scale economics and European qualified signature premium pricing.
For Market Incumbents: Cement platform consolidation advantages by acquiring specialized trust service providers with existing EU accreditation, insulating against margin erosion from AI-generated document fraud that threatens basic signature capture methods. Deepen vertical integration into hardware security module partnerships to secure supply continuity for qualified signature creation devices, while expanding hybrid cloud deployment capacity in Frankfurt and Zurich to capture German and Swiss banking procurement. For New Entrants and Emerging Players: Indian professional services firms represent the most penetrable buyer archetype, with self-service onboarding and per-seat pricing models remaining underdeveloped relative to United States benchmarks. Target workflow automation bundling for United States mortgage originators seeking straight-through processing metrics, and pursue API-first embedded signature capture for fintech startups demanding sub-200-millisecond response times. For Investors and Strategic Acquirers: Roll-up economics work for vertical specialists with FDA 21 CFR Part 11 validation or qualified trust service accreditation because certification moats create durable pricing power against horizontal platform commoditization. Acquisition targets should demonstrate existing trust infrastructure and regulatory relationships rather than pure technology differentiation. Watch for AI Act biometric identification risk classification tightening as the inflection indicator for authentication module procurement standards.| Strategic Initiative | Industry Significance |
|---|---|
| Trust Service Provider Acquisition | EU eIDAS accreditation compresses competitive access for unqualified vendors across member states. |
| Hybrid Cloud Deployment Expansion | German FINMA and Swiss FINMA regulations mandate on-premises key retention for banking signatures. |
| AI-Biometric Convergence Investment | Liveness detection fused with behavioral biometrics addresses emerging AI-generated document fraud threats. |
| Workflow Automation Platform Integration | United States mortgage originators pay premium pricing for straight-through processing metrics. |
| India SME Self-Service Launch | Bengaluru and Mumbai professional services firms represent underpenetrated expansion targets for accessible platforms. |
Research Methodology
Coverage spans the United States, Germany, India, the United Kingdom, and Switzerland, with primary inputs from each geography triangulated against secondary validation. The research combines interviews with trust service provider executives, bank procurement officers, pharmaceutical regulatory affairs leads, software platform engineers, and legal technology consultants with secondary analysis of SEC filings, eIDAS supervisory body accreditation registers, FDA 21 CFR Part 11 guidance documents, and RBI digital lending circulars. Bottom-up segment sizing and top-down market reconciliation ensure cross-verification across deployment models, end-user categories, and service type tiers.
Rate-of-change decomposition separates volume expansion from pricing trajectory across the projection horizon, with analytical frameworks modeling deployment architecture, organizational scale, workflow complexity, integration level, and regional regulatory cluster as core segmentation dimensions. CAGRs derive from trend extrapolation of remote online notarization statute expansion, qualified signature procurement patterns among EU financial institutions, and SME self-service adoption curves in emerging markets. Industry-specific forecast inputs include trust service provider accreditation pipeline data and hardware security module shipment volumes for qualified signature creation devices.
Underlying measurement precision varies by segment; public cloud deployment and SME end-user categories carry tighter precision than private cloud and government procurement due to disclosed vendor metrics and self-service transaction transparency. Forecasts reflect assumptions around regulatory stability for cross-border enforceability and continued state-level remote online notarization statute expansion in the United States. Deviation in EU AI Act biometric identification risk classification or qualified trust service accreditation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Europe Digital Marketing Software Market
Digital Solutions
Middle East and Africa Cloud Integration Market
Digital Solutions
Mobile Tracking Solution Market
Digital Solutions
Global Machine Translation (MT) Market
Digital Solutions
Global BYOD and Enterprise Mobility Market
Digital Solutions
Assortment and Space Optimization (ASO) Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Integrated Systems Market
Digital Solutions
Global Assistive Technologies for Visually Impaired Market
Digital Solutions
Cannabis POS System Market
Digital Solutions
Global Data Quality Tool Market
Digital Solutions
Mobile Engagement Market
Digital Solutions
US Transcription Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market