
 Omeprazole and Antihistamine Market | 2026-2036
Omeprazole and Antihistamine Market Size, Share, and Industry Trends Forecast 2026-2036
Omeprazole and Antihistamine Market Insights
Continuous manufacturing is narrowing the cost gap between originator and generic formulations across oral solid dose production. Pfizer leverages backward integration into active pharmaceutical ingredient supply to protect margin pools in omeprazole. AstraZeneca anchors its position through sustained R&D investment in modified-release antihistamine platforms. Teva Pharmaceutical competes aggressively on volume scale across multiple therapy areas.
Omeprazole and antihistamines comprise a class of histamine receptor antagonists and proton pump inhibitors used to suppress gastric acid secretion and block H1 receptor-mediated allergic responses, with formulations typically ranging from 10 mg to 40 mg for omeprazole and 10 mg to 180 mg for fexofenadine depending on indication and regional monograph. These agents serve primary commercial purposes in managing chronic gastrointestinal disorders and seasonal or perennial allergic rhinitis through both prescription and over-the-counter channels. The omeprazole product type dominates current volume due to extensive genericization and established reimbursement pathways, while fexofenadine segments expand fastest in self-directed pharmacy purchases as consumers shift from sedating first-generation alternatives. Home care end users represent an emerging margin pool where direct-to-patient delivery models bypass traditional hospital pharmacy markups.
FDA bioequivalence requirements under 21 CFR 320 and EMA's revised pharmacovigilance guidelines shape product development timelines and post-market surveillance obligations for manufacturers seeking abbreviated new drug approvals. India's CDSCO and BIS standards further govern import quality for API sourcing, creating multi-jurisdictional compliance burdens for supply chain operators. Stakeholders must monitor evolving FDA guidance on elemental impurity limits and EU MDR traceability rules as these frameworks determine which formulations retain market access versus face reformulation costs.
Market Dynamics
Continuous manufacturing adoption is compressing production economics for oral solid dose formulations, narrowing the cost gap between originator and generic omeprazole while forcing legacy batch facilities into accelerated retrofit cycles.
Growth Catalysts
- FDA bioequivalence pathways:Abbreviated new drug approval frameworks under 21 CFR 320 accelerate generic entry for proton pump inhibitors, expanding pharmacy channel availability.
- Aging self-medication patterns:Elderly populations in Japan and Germany increasingly bypass physician visits for recurrent acid reflux management, driving over-the-counter volume.
- Non-sedating antihistamine substitution:Clinical guidelines across the United States favor fexofenadine over first-generation alternatives for chronic allergic rhinitis, redirecting prescription flows.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for omeprazole concentrates in Indian and Chinese manufacturing clusters, creating single-source vulnerability.
- Elemental impurity compliance:Revised ICH Q3D guidelines and FDA guidance on metal residues force reformulation costs for legacy generic filings.
- Reimbursement compression:United States Medicare Part D and Japanese NHI price revision cycles erode margin pools for established proton pump inhibitor brands.
Strategic Opportunities
- Home care delivery models:Direct-to-patient subscription services bypass hospital pharmacy markups, capturing margin in chronic GERD management.
- Modified-release platforms:Sustained-release antihistamine formulations address unmet need in nocturnal allergy symptoms, opening premium positioning.
- EU MDR traceability mandates:Serialization requirements favor manufacturers with integrated packaging capabilities, disadvantaging fragmented assemblers.
Industry Challenges
- Post-market surveillance burdens:EMA pharmacovigilance guidelines require expanded adverse event reporting infrastructure, stretching mid-tier generic operators.
- Continuous manufacturing retrofit costs:Batch-to-continuous conversion demands capital deployment in process analytical technology and real-time release testing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omeprazole and Antihistamine Market |
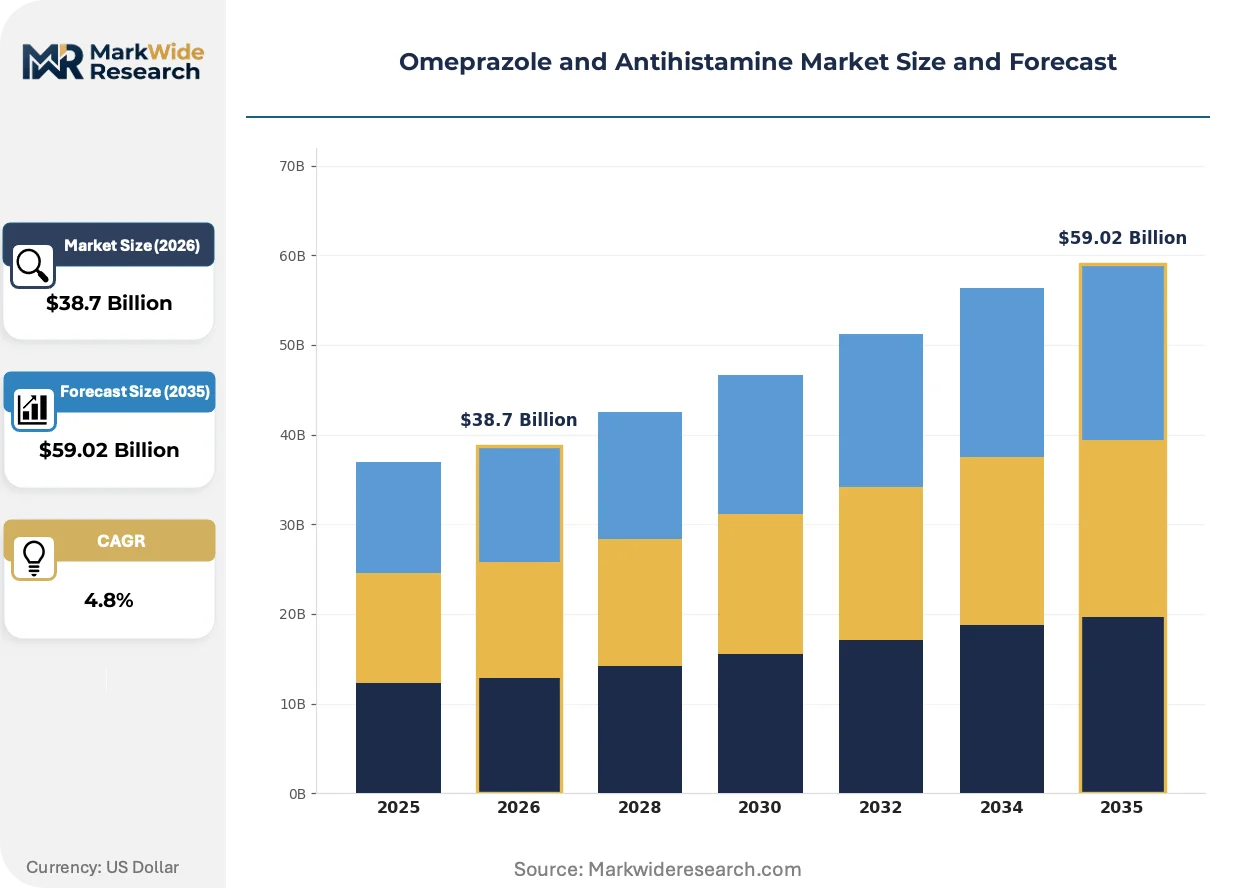
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omeprazole, Ranitidine, Fexofenadine, Cetirizine Therapy Area: Gastrointestinal Disorders, Allergies, Acid Reflux, Respiratory Issues End User: Hospitals, Outpatient Clinics, Pharmacies, Home Care Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesale |
| Companies Covered | Pfizer, AstraZeneca, Bayer AG, Novartis, Teva Pharmaceutical, Sanofi, Procter & Gamble, Johnson & Johnson Consumer Inc, Takeda Pharmaceutical Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omeprazole and Antihistamine Market Trends and Innovations
Formulation science and regulatory technology are converging to reshape competitive boundaries, with manufacturing modality and compliance architecture becoming primary differentiators rather than secondary operational concerns.
Hot-melt extrusion technology for amorphous solid dispersions is migrating from specialty applications to mainstream oral solid dose production. Generic manufacturers in India and the United States adopt this platform to enhance bioavailability of poorly soluble actives. The shift is compressing development timelines for complex generics while raising technical barriers for traditional wet-granulation facilities.
EMA's revised pharmacovigilance guidelines and FDA's emerging guidance on real-world evidence integration are tightening post-approval accountability frameworks. Manufacturers must now maintain active surveillance systems rather than passive adverse event collection. The burden falls heaviest on multi-product generic portfolios where signal detection requires specialized pharmacovigilance infrastructure.
Consumer-directed pharmacy purchasing is fragmenting traditional prescriber-channel relationships. Patients in Germany and Japan increasingly initiate therapy through pharmacist consultation rather than physician diagnosis, particularly for seasonal allergic rhinitis. This shift rewards brands with direct-to-consumer marketing authorization and pharmacy trade relationships over those dependent on clinical detailing.
Omeprazole and Antihistamine Market Segmentation
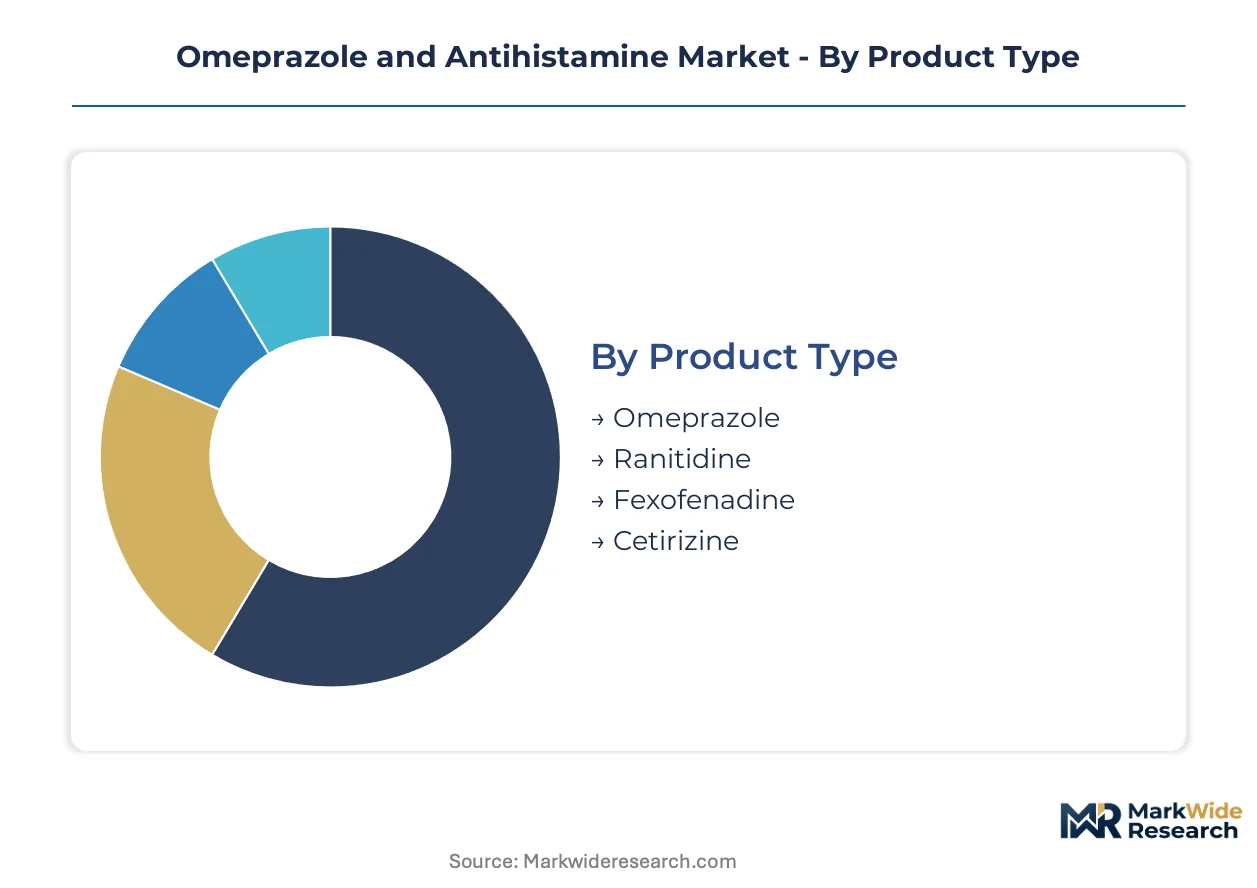
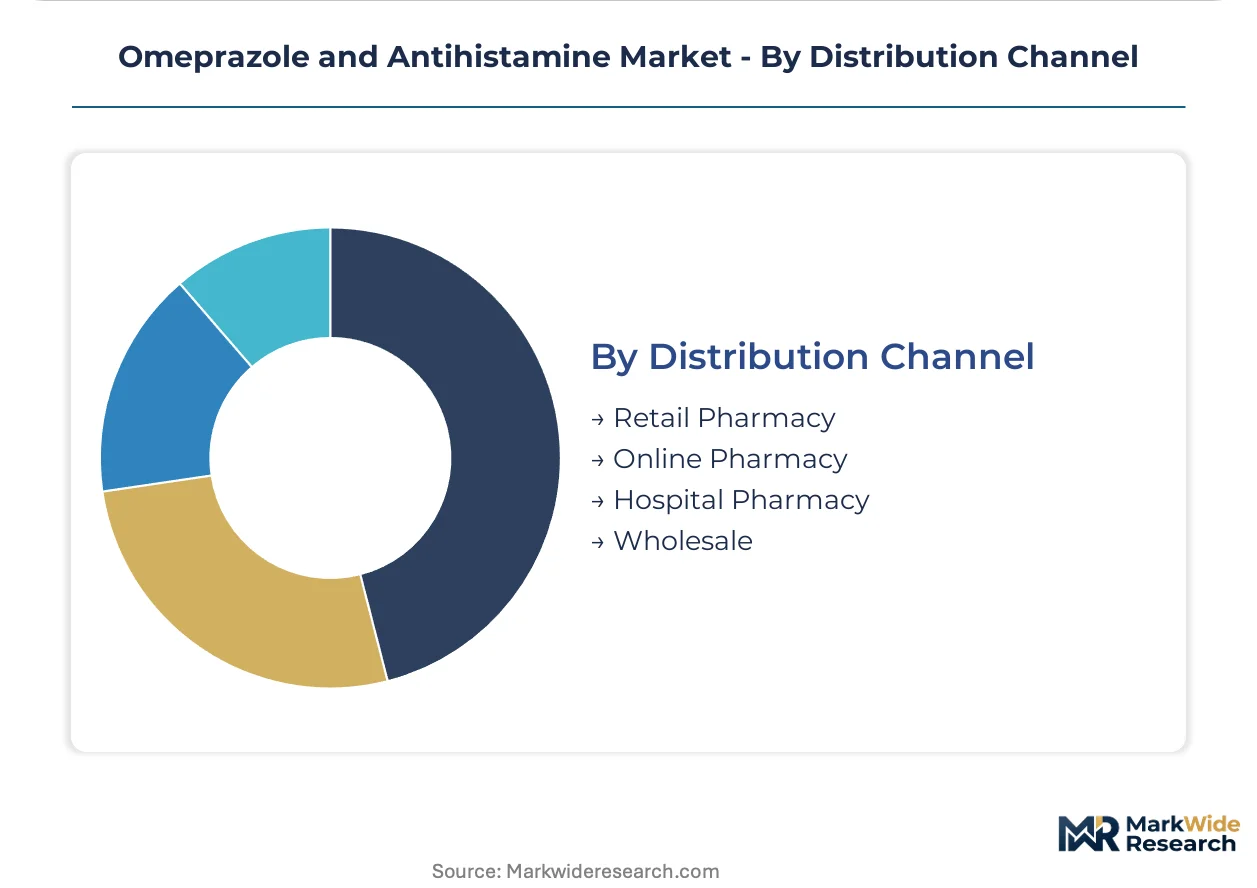
Segmentation in the omeprazole and antihistamine market reveals distinct margin pools and channel dependencies that shape competitive positioning. Product type and therapy area classifications determine reimbursement pathways, while end-user and distribution channel splits expose where self-medication trends are eroding traditional prescriber control.
Product Type:
Mature proton pump inhibitors dominate volume, while emerging antihistamine platforms reshape growth trajectories across prescription and over-the-counter channels.
- Omeprazole:The proton pump inhibitor exists as racemic mixtures and esomeprazole single-enantiomer formulations, with bioequivalence under 21 CFR 320 governing generic substitution patterns. United States Medicare Part D reimbursement and Japanese NHI price revisions concentrate demand for this segment, though margin compression from multi-source generic entry constrains originator returns.
- Fexofenadine:This non-sedating H1 antagonist delivers 24-hour coverage through active metabolite pharmacokinetics, positioning it against first-generation alternatives in clinical guidelines. German pharmacy channels and United States direct-to-consumer advertising drive self-directed purchasing for seasonal allergic rhinitis, bypassing traditional physician consultation.
- Ranitidine:H2 receptor antagonist with faster onset but shorter duration than PPIs, facing regulatory scrutiny over NDMA impurities.
- Cetirizine:Second-generation antihistamine with established over-the-counter status across European and North American markets.
Omeprazole handles the majority of throughput; fexofenadine is the fastest mover on share.
Therapy Area:
Application focus spans acute symptom relief to chronic disease management, with reimbursement intensity varying by condition severity and treatment duration.
- Gastrointestinal Disorders:Peptic ulcer disease and functional dyspepsia indications anchor hospital formulary placement, with Cleveland Clinic and Mayo Clinic procurement patterns influencing regional prescribing. Chronic maintenance therapy for erosive esophagitis generates recurring pharmacy volume in United States and Japan.
- Acid Reflux:GERD management spans prescription step-up protocols to over-the-counter maintenance, with direct-to-patient subscription models emerging in United States urban markets.
- Allergies:Seasonal and perennial allergic rhinitis drive antihistamine selection, with immunotherapy co-prescription patterns affecting duration of use.
- Respiratory Issues:Adjunctive use in allergic asthma and chronic cough protocols, typically secondary to inhaled corticosteroid regimens.
Gastrointestinal disorders command the largest prescription volume; acid reflux applications are expanding most quickly through self-care channels.
End User:
Customer type segmentation exposes where channel markups concentrate and where direct-to-patient models are disintermediating traditional intermediaries.
- Home Care:Patients managing chronic GERD or perennial allergies through self-directed therapy, increasingly initiated via pharmacist consultation in Germany and Japan rather than physician diagnosis. Amazon Pharmacy and CVS Caremark subscription services capture margin by bypassing hospital pharmacy markups for 90-day maintenance supplies.
- Pharmacies:Community and chain retail outlets serve as primary consultation points for seasonal allergy onset and acid reflux recurrence, with private-label generic substitution driving price competition.
- Hospitals:Inpatient formulary committees govern acute ulcer prophylaxis and anaphylaxis management, with group purchasing organization contracts determining vendor selection.
- Outpatient Clinics:Specialist gastroenterology and allergy practices guide step-up therapy decisions, though their influence erodes as over-the-counter access expands.
Pharmacies handle the majority of throughput; home care is the fastest mover on share.
Distribution Channel:
Channel configuration determines compliance burden and working capital requirements, with serialization mandates favoring integrated operators over fragmented assemblers.
- Retail Pharmacy:Walgreens, CVS, and Rite Aid networks in the United States combine with Boots and dm-drogerie markt in Germany to dominate face-to-face consultation and immediate fulfillment. EU MDR traceability requirements and FDA DSCSA serialization favor distributors with integrated packaging capabilities.
- Online Pharmacy:PillPack, Capsule, and local e-pharmacy platforms in Japan enable subscription-based chronic disease management, with cold-chain requirements for some formulations limiting geographic reach.
- Hospital Pharmacy:Captive distribution within integrated delivery networks, with 340B pricing programs affecting United States procurement economics.
- Wholesale:McKesson, AmerisourceBergen, and Cardinal Health in the United States plus Phoenix and Alliance Healthcare in Europe manage inventory aggregation and just-in-time delivery to fragmented retail endpoints.
Retail pharmacy handles the majority of throughput; online pharmacy is the fastest mover on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and pharmacy chains concentrate purchasing power in the United States, Germany, and Japan, while direct-to-consumer channels expand fastest in urban markets with aging demographics and pharmacist consultation access.
United States
Medicare Part D reimbursement drives volume for proton pump inhibitors, with Cleveland Clinic and Mayo Clinic procurement patterns influencing regional prescribing habits. FDA bioequivalence standards under 21 CFR 320 govern generic substitution, accelerating pharmacy channel competition. The New Jersey and Pennsylvania corridor hosts API sourcing operations serving domestic formulation facilities.
Germany
Pharmacist consultation models enable self-directed therapy initiation for seasonal allergic rhinitis, bypassing traditional physician channels. EMA pharmacovigilance guidelines require expanded adverse event reporting infrastructure for all marketed formulations. The Rhine-Main and Bavarian regions concentrate manufacturing facilities serving both domestic and export markets.
Japan
NHI price revision cycles compress margin pools for established proton pump inhibitor brands while expanding over-the-counter access for chronic GERD management. PMDA oversight governs quality thresholds for imported active pharmaceutical ingredients. The Kanto region around Tokyo anchors distribution networks for hospital pharmacy and retail channels.
India
CDSCO and BIS standards govern import quality for API sourcing, creating compliance burdens for multi-jurisdictional supply chain operators. Domestic formulation manufacturers serve export markets across Africa and Southeast Asia. The Mumbai-Pune corridor and Hyderabad cluster concentrate active pharmaceutical ingredient production for omeprazole.
United Kingdom
Boots and pharmacy chain networks dominate face-to-face consultation for seasonal allergy onset, with private-label generic substitution intensifying price competition. EU MDR traceability requirements favor distributors with integrated packaging capabilities. The Southeast England corridor hosts distribution centers serving both domestic and Irish markets.
Omeprazole and Antihistamine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across prescription and over-the-counter segments. The market structures around three tiers: originator pharmaceutical companies with sustained R&D investment, high-volume generic manufacturers competing on scale, and consumer health divisions of diversified conglomerates. Consolidation pressures favor backward integration into API supply and strategic partnerships for modified-release platform access.
Among originator pharmaceutical companies, Pfizer and AstraZeneca occupy positions representing backward integration and sustained R&D investment archetypes respectively. Teva Pharmaceutical exemplifies the high-volume generic manufacturer competing across multiple therapy areas. These three anchors illustrate how competitive positioning diverges between margin protection through captive supply, premium positioning through formulation innovation, and market share capture through manufacturing scale.
| Leading Market Players |
|---|
| Pfizer |
| AstraZeneca |
| Bayer AG |
| Novartis |
| Teva Pharmaceutical |
| Sanofi |
| Procter & Gamble |
| Johnson & Johnson Consumer Inc |
| Takeda Pharmaceutical Company Limited |
| Others |
Pricing and Supply Chain Analysis
Indian and Chinese API manufacturing clusters for omeprazole and fexofenadine intermediates anchor upstream supply, concentrating margin capture with integrated formulators who bypass spot-market procurement. Cost-plus contracts with acetaminophen and hydroxypropyl methylcellulose indexation govern long-term supply agreements, while hospital pharmacy markups and retail generic substitution create divergent margin pools downstream.
Pricing Analysis
Cost-plus contracts with acetaminophen and hydroxypropyl methylcellulose indexation dominate API procurement, though finished-formulation pricing stratifies across premium originator brands, standard bioequivalent generics, and economy private-label alternatives. Price differentiation hinges on FDA bioequivalence certification tier and vertical integration depth into active pharmaceutical ingredient supply. Cost compression in economy-tier generics intensifies as Indian manufacturers expand direct-to-pharmacy distribution, while originator brands face margin erosion from Medicare Part D reimbursement compression. Hospital procurement committees exhibit lowest price sensitivity; retail pharmacy substitution drives highest sensitivity.
Supply Chain Analysis
Contract manufacturing concentrates with Dr. Reddy's Laboratories, Aurobindo Pharma, and Teva Pharmaceutical facilities across Hyderabad, Mumbai-Pune, and Israel. Active pharmaceutical ingredient production draws from Indian and Chinese chemical synthesis clusters, with hydroxypropyl methylcellulose and croscarmellose sodium excipients sourced from European specialty chemical suppliers. Single-source vulnerability in NDMA-tested ranitidine alternatives creates regulatory restriction risk for legacy formulation lines. Distribution runs through McKesson and AmerisourceBergen wholesale networks in the United States, Phoenix and Alliance Healthcare in Europe, with direct-to-patient subscription models bypassing traditional retail pharmacy markups in urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as Amazon Pharmacy and CVS Caremark subscription ecosystems disintermediate traditional prescriber-channel relationships, rewarding manufacturers with direct-to-consumer marketing authorization and integrated serialization capabilities.
For Market Incumbents: Insulate margin pools by deepening backward integration into Indian API supply through captive Hyderabad or Mumbai-Pune manufacturing, while accelerating continuous manufacturing retrofit to narrow cost gaps with high-volume generic competitors. EMA pharmacovigilance guideline expansion threatens mid-tier operators with compliance infrastructure burdens; investment in real-time release testing systems defends quality-tier positioning against batch-facility competitors.
For New Entrants and Emerging Players: Pursue home care delivery models for chronic GERD maintenance therapy in United States urban markets, where direct-to-patient subscription services bypass hospital pharmacy markups and capture 90-day supply margin pools. Modified-release antihistamine platforms for nocturnal allergy symptoms represent the most penetrable white space; partner with PillPack or Capsule for pharmacy trade relationships rather than building clinical detailing infrastructure.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic manufacturers lacking pharmacovigilance infrastructure for EMA post-market surveillance compliance. Five-to-ten year viability hinges on continuous manufacturing conversion completion and EU MDR serialization integration. Watch FDA guidance on elemental impurity limits as inflection signal for reformulation cost exposure across legacy generic portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Supply | Captive Hyderabad manufacturing protects margin pools from Indian spot-market volatility. |
| Continuous Manufacturing Retrofit | Real-time release testing narrows cost gaps with legacy batch facilities. |
| Direct-to-Patient Subscription Launch | Amazon Pharmacy partnerships bypass hospital pharmacy markups in chronic GERD. |
| Modified-Release Platform Development | Sustained-release antihistamine formulations command premium positioning for nocturnal symptoms. |
| EU MDR Serialization Compliance | Integrated packaging capabilities advantage fragmented assemblers under traceability mandates. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at FDA and EMA, formulary directors at Cleveland Clinic and Mayo Clinic, hospital procurement managers at integrated delivery networks, and pharmacy trade specialists at Walgreens and CVS, then refined through secondary validation against FDA 21 CFR 320 bioequivalence filings, EMA pharmacovigilance submissions, ClinicalTrials.gov protocol registries, and Medicare Part D utilization databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to converge on segment-level estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, therapy area, end user, and distribution channel, plus dosage form and regional regulatory cluster as pharmaceutical-specific layers. CAGRs were derived from prescription volume trajectories and pricing elasticity modeling, incorporating NHI price revision cycles in Japan and Medicare Part D reimbursement compression in the United States as forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in exchange rate volatility affecting Indian API import costs or NHI reimbursement policy shifts would shift the trajectory. Forecasts reflect underlying assumptions about bioequivalence pathway stability and pharmacovigilance infrastructure scalability. Quarterly review of FDA guidance issuance on elemental impurity limits and EMA adverse event reporting thresholds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Renal Drugs Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Long-Acting Insulin Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Human Immunodeficiency Virus Therapeutics Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Vascular Endothelial Growth Factor (VEGF) Antibodies Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
France Diabetes Drugs Market